
 Atomic Battery Market | 2026-2036
Atomic Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Atomic Battery Market Insights
Market Context
Modular power-system packaging is rebalancing buyer choice in atomic batteries, shifting procurement from standalone units toward integrated mission-ready configurations. City Labs leverages its betavoltaic specialization to anchor commercial micro-power contracts for remote sensing networks. Lockheed Martin Corporation competes through captive aerospace integration, sustaining program-level relationships with defense agencies. NASA dominates civilian demand, extending its technology leadership through deep-space mission specifications that require multi-decade operational lifespans.
Technical Definition and Segment Structure
An atomic battery converts energy released from radioactive decay directly into electrical power through thermoelectric or betavoltaic transduction, typically achieving power densities of milliwatts to hundreds of watts with operational lifespans spanning ten to fifty years depending on isotope half-life. The primary industrial purpose centers on powering devices where battery replacement proves impossible, impractical, or prohibitively expensive, including implantable medical devices, subsea instrumentation, and interplanetary spacecraft. Radioisotope thermoelectric generators occupy the largest value pool given their established role in space probe propulsion and planetary lander systems, while betavoltaic cells represent the fastest-expanding segment as semiconductor junction efficiency improves and tritium sourcing stabilizes. Strontium-90 thermal batteries retain mature military demand for missile guidance and weapons systems, though environmental handling constraints limit new application development.
Regulatory Environment and Outlook
The US Nuclear Regulatory Commission and Department of Transportation jointly govern isotope possession, transport, and device certification, creating multi-layered compliance pathways that extend product development timelines. The European Union's Euratom framework and REACH chemical regulations impose parallel constraints on material sourcing and cross-border shipment of sealed radioactive sources. China's National Nuclear Safety Administration and Ministry of Ecology and Environment administer parallel licensing for domestic atomic battery programs. Stakeholders must monitor evolving dual-use export control classifications and emerging small modular reactor regulatory precedents that could reshape isotope availability and pricing structures.
Market Dynamics
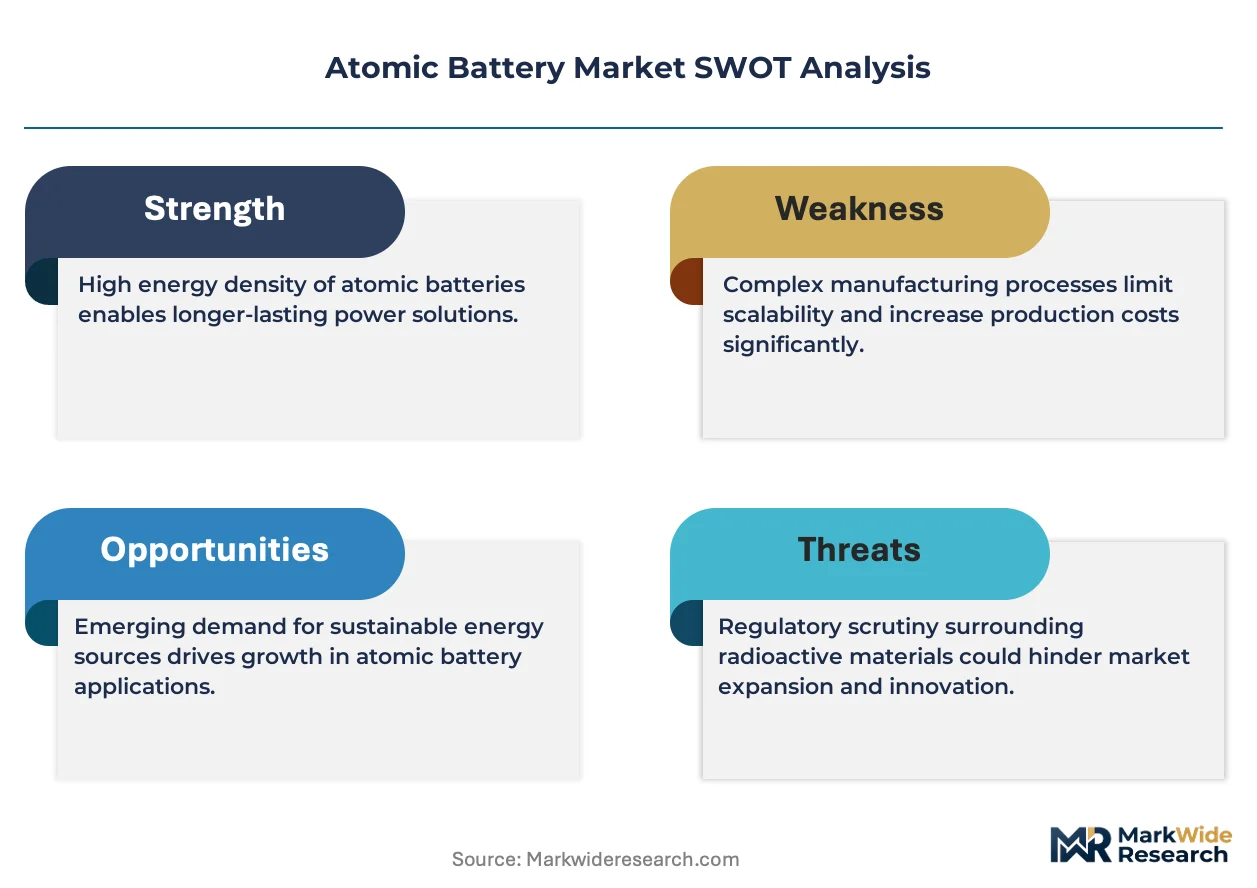
The atomic battery market faces a structural tension between mission-critical demand for multi-decade power autonomy and the regulatory chokehold on isotope sourcing and device certification. Buyers in aerospace and defense sectors prioritize operational lifespan over unit economics, while suppliers navigate multi-jurisdictional licensing that extends development cycles by years.
Growth Catalysts
- Deep-space mission specifications:NASA's Artemis program and interplanetary probe deployments require power systems operational for twenty-plus years without maintenance. Thermoelectric generators satisfy this demand profile where chemical batteries fail.
- Unmanned system proliferation:Pentagon programs for underwater drones and stratospheric surveillance platforms specify atomic power for endurance missions beyond refueling range. Defense procurement budgets are redirecting toward these long-duration assets.
- Betavoltaic efficiency gains:Semiconductor junction improvements and tritium supply stabilization are expanding commercial viability for remote sensing networks and implantable medical devices.
Market Restraints
- Plutonium-238 scarcity:Production capacity at Oak Ridge National Laboratory constrains supply for deep-space thermoelectric generators. Alternative isotopes require redesign validation cycles.
- Cross-border shipment restrictions:International Atomic Energy Agency safeguards and bilateral agreements limit sealed-source transport. European Union REACH regulations compound material-handling complexity.
- Lithium-ion cost compression:Stationary and mobile applications where battery replacement remains feasible face substitution pressure from improving chemical storage economics.
Strategic Opportunities
- Arctic and Antarctic research infrastructure:Polar monitoring stations and subglacial sensor networks require power immune to temperature extremes. Atomic batteries eliminate logistical resupply dependency.
- Medical implant miniaturization:Cardiac pacemakers and neurostimulators are extending replacement intervals. Betavoltaic cells could displace primary lithium cells in next-generation devices.
- Small modular reactor regulatory precedents:Streamlined licensing frameworks under development for advanced nuclear may reduce isotope handling compliance burdens for atomic battery manufacturers.
Industry Challenges
- Radioisotope handling certification:Engineers and technicians require specialized training for sealed-source assembly. Workforce pipeline constraints limit production scaling.
- Device qualification timelines:Multi-year validation cycles for space-rated thermoelectric generators compress competitive windows. Design changes trigger recertification costs.
- Legacy integration complexity:Atomic power systems must interface with digital control architectures and power management electronics developed for conventional sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atomic Battery Market |
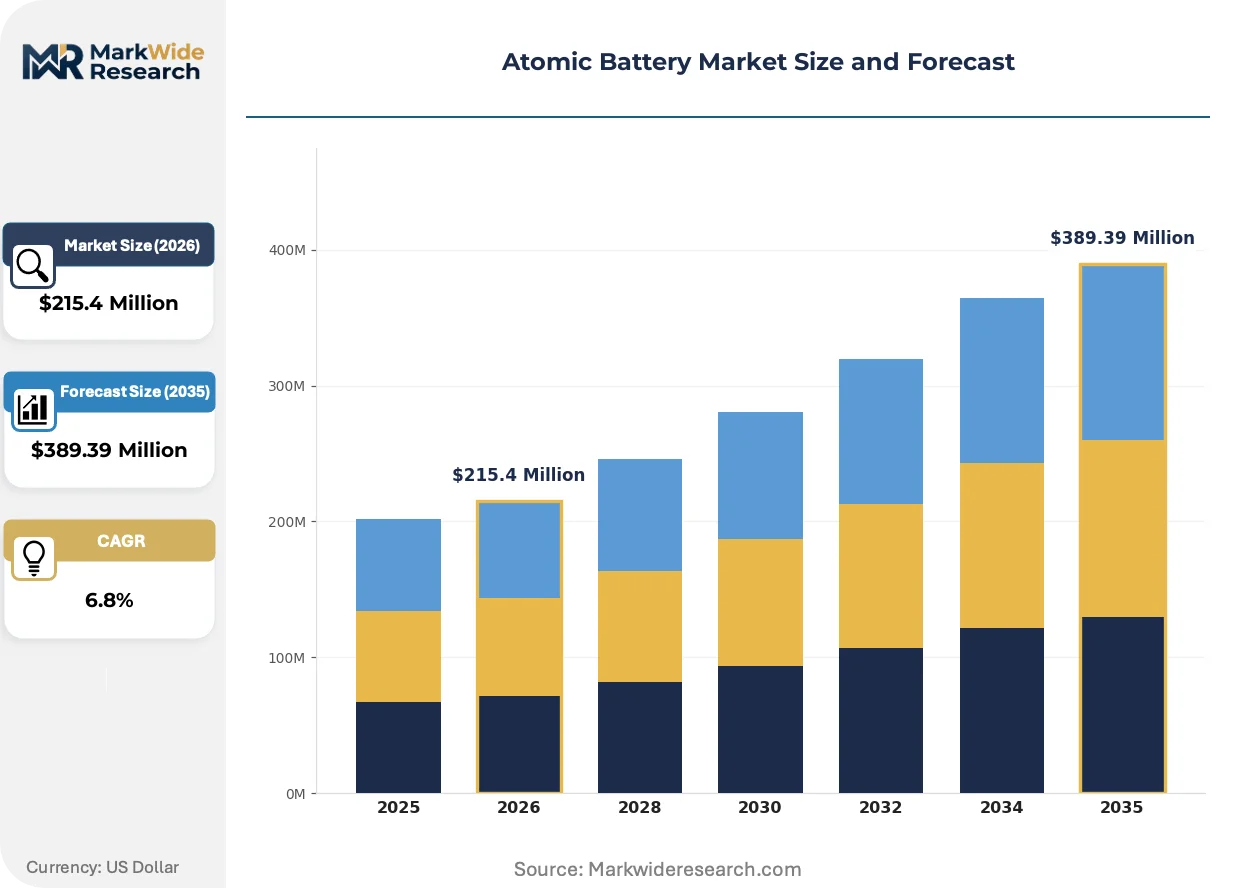
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Radioisotope Thermoelectric Generators, Betavoltaic Cells, Thermal Batteries, Nuclear Batteries Material: Polonium-210, Strontium-90, Tritium, Americium-241 End User: Aerospace, Military, Remote Sensing, Medical Devices Application: Space Probes, Pacemakers, Deep Space Missions, Underwater Equipment |
| Companies Covered | Exide Technologies, City Labs, NDB, Lockheed Martin Corporation, General Atomics, ROSATOM, NASA, Northrop Grumman Corporation, Curtiss Wright Nuclear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atomic Battery Market Trends and Innovations
Atomic battery development is pivoting from isotope-centric engineering toward system-level integration with host platforms. Manufacturers are embedding power conditioning, thermal management, and radiation shielding into mission-ready modules rather than delivering standalone cells.
Thermoelectric converter materials are consolidating around segmented architectures combining bismuth telluride and skutterudite compounds. Jet Propulsion Laboratory and Roscosmos are deploying these configurations in Mars rover and lunar lander applications. Higher conversion efficiency is consolidating supplier relationships with specialized ceramics producers and extending competitive moats for integrated system vendors.
The US Nuclear Regulatory Commission is harmonizing device certification pathways with Department of Transportation packaging rules for Category 1 radioactive materials. This regulatory consolidation reduces redundant review cycles for manufacturers. Space and defense contractors with established NRC relationships are accelerating program timelines while commercial entrants face steeper compliance barriers.
Buyers are specifying power-as-a-service contracts rather than capital equipment purchases for remote infrastructure deployments. Oil and gas operators in the Permian Basin and North Sea are contracting atomic power providers for subsea monitoring networks. This model transfers isotope sourcing and regulatory liability to vendors while locking in decade-long revenue streams for suppliers with handling licenses.
Atomic Battery Market Segmentation
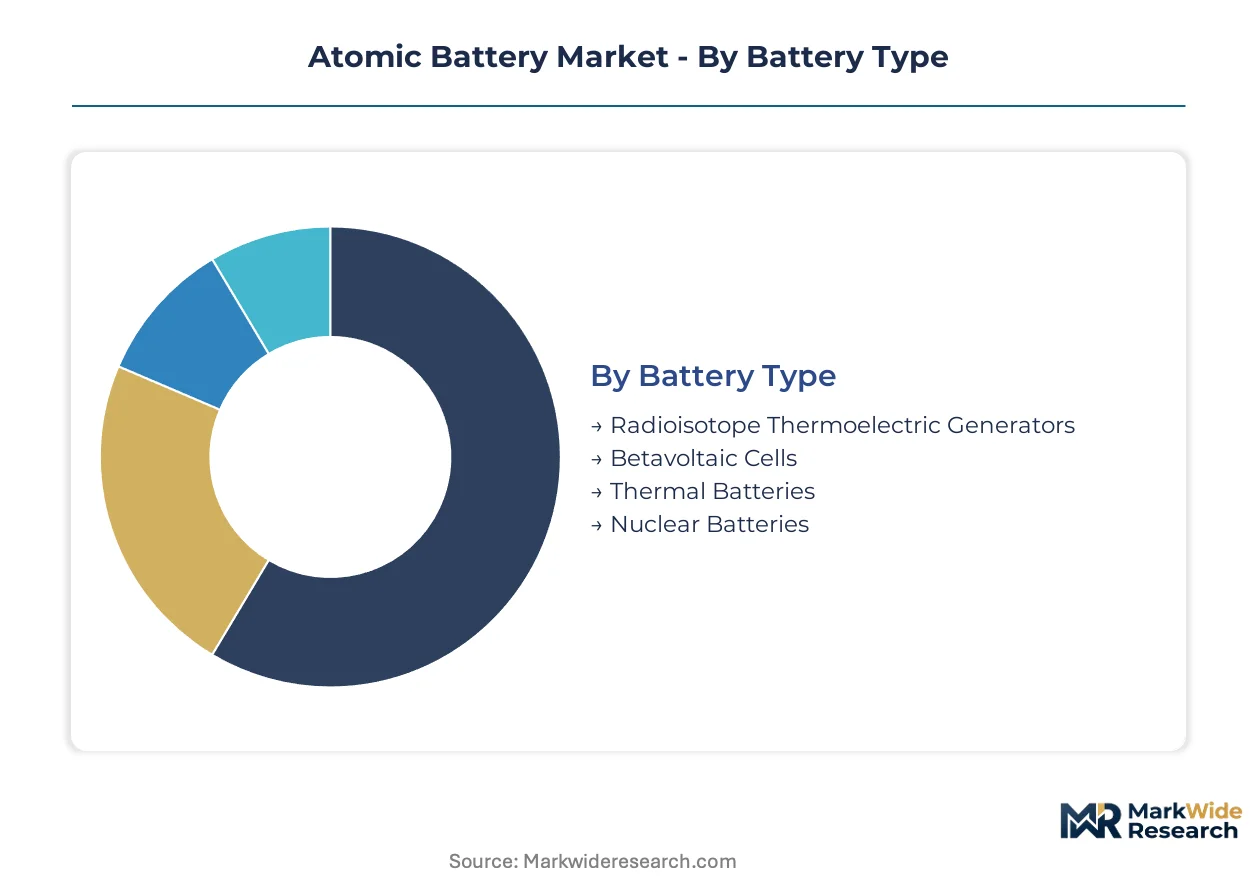
Segmentation in atomic batteries reveals how regulatory burden and mission requirements reshape procurement patterns. Buyers sort options by certification pathway, isotope handling complexity, and operational lifespan rather than unit economics alone.
Battery Type:
US NRC Category 1 device certification governs thermoelectric generators most stringently, while betavoltaic cells face streamlined pathways under exempt quantity thresholds.
- Radioisotope Thermoelectric Generators:Bismuth telluride and skutterudite thermocouples convert decay heat directly to electricity. NASA deep-space missions specify these for 20-plus year operational lifespans where maintenance is impossible. Plutonium-238 scarcity at Oak Ridge National Laboratory constrains supply expansion.
- Betavoltaic Cells:Semiconductor junctions capture beta-particle kinetic energy from tritium or nickel-63. Remote sensing networks in the Permian Basin and North Sea are contracting power-as-a-service models. Tritium supply stabilization and junction efficiency gains are accelerating commercial viability.
- Thermal Batteries:Strontium-90 heat sources power military missile guidance systems. Environmental handling constraints limit new application development outside defense procurement.
- Nuclear Batteries:Direct-charge collectors and self-reciprocating cantilevers represent experimental architectures. Research programs at national laboratories dominate funding flows.
Radioisotope thermoelectric generators sit at the top of the volume ranking, with betavoltaic cells climbing the fastest.
Material:
Cost tiers stratify sharply by isotope production infrastructure and dual-use export control classification.
- Polonium-210:High specific activity enables compact thermal sources. Russian production facilities supply most non-US demand for space and defense programs. IAEA safeguards documentation adds procurement lead time.
- Strontium-90:Fission product recovery from nuclear fuel reprocessing yields stable supply. Military thermal battery programs in the United States and Russia anchor demand. Disposal liability transfers to end-users under EULA terms.
- Tritium:Commercial betavoltaic feedstock with established handling protocols. Canadian CANDU reactor production and US commercial inventory release programs balance supply. Semiconductor fabrication facilities integrate tritium handling into existing radiation safety programs.
- Americium-241:Neptunium-237 neutron capture production creates supply bottleneck. European Space Agency studies evaluate americium for deep-space missions as plutonium-238 alternative. Longer half-life reduces power density but extends operational duration.
Strontium-90 dominates current procurement volumes, with tritium gaining share fastest in commercial applications.
End User:
Customer type determines whether procurement flows through defense acquisition channels, civilian space agency specifications, or commercial vendor relationships.
- Aerospace:Jet Propulsion Laboratory and prime contractors specify integrated power systems for Mars rovers and lunar landers. Segmented thermoelectric architectures require qualification cycles spanning multiple years.
- Military:Pentagon unmanned underwater vehicle and stratospheric surveillance programs specify atomic power for endurance beyond refueling range. Defense procurement budgets are redirecting toward these long-duration assets.
- Remote Sensing:Oil and gas operators contract atomic power for subsea monitoring networks. Power-as-a-service models transfer isotope sourcing and regulatory liability to vendors.
- Medical Devices:Cardiac pacemaker and neurostimulator manufacturers evaluate betavoltaic cells for extended replacement intervals. FDA device classification and NRC byproduct material licensing create dual regulatory pathways.
Aerospace commands the premium pricing tier, with remote sensing expanding most quickly through service-based contracting.
Application:
Maturity gradients separate flight-proven architectures from developmental concepts awaiting qualification data.
- Space Probes:Voyager, New Horizons, and Cassini heritage validates multi-decade thermoelectric performance. NASA Radioisotope Power Systems Program maintains design authority and fuel supply allocation.
- Pacemakers:Betavoltaic prototypes target 20-year replacement intervals versus 7-10 years for lithium primary cells. Miniaturization challenges focus on semiconductor junction area optimization.
- Deep Space Missions:Artemis lunar surface operations and interplanetary probe deployments specify power systems operational without maintenance. Alternative isotope evaluation programs address plutonium-238 scarcity.
- Underwater Equipment:Seafloor sensor networks and autonomous underwater vehicles operate where battery replacement is logistically prohibitive. Pressure vessel integration and corrosion resistance dominate engineering requirements.
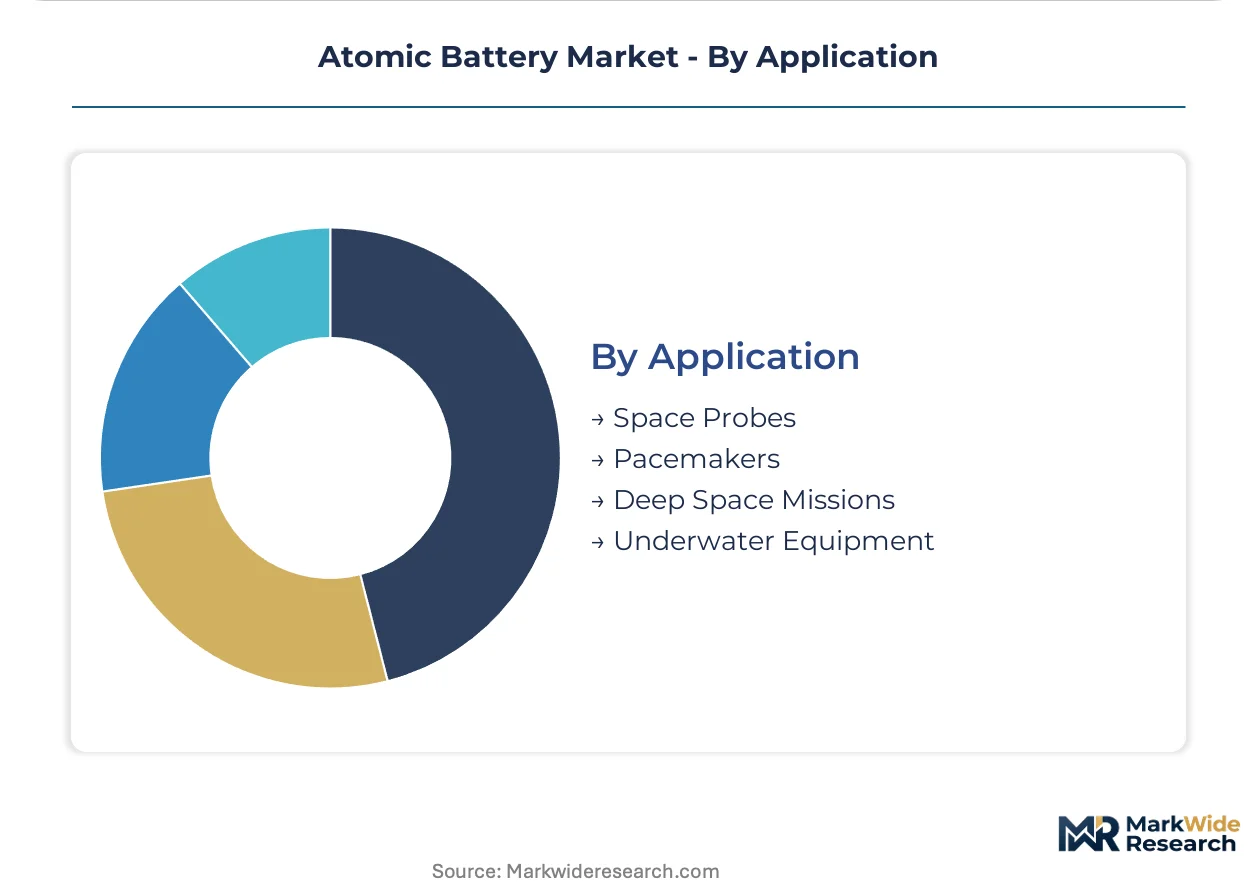
Space probes anchor established demand, with underwater equipment representing the steepest expansion trajectory as offshore infrastructure monitoring scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The atomic battery industry traces its commercial roots to Cold War-era programs at Oak Ridge National Laboratory and Soviet-era isotope production facilities. NASA's Radioisotope Power Systems Program established the first sustained demand for multi-decade thermoelectric generators. Civilian applications expanded through European Space Agency research and Japanese betavoltaic development programs.
United States
NASA's Artemis lunar surface operations and Pentagon unmanned underwater vehicle programs anchor domestic demand for long-duration power systems. The US Nuclear Regulatory Commission and Department of Transportation jointly govern Category 1 device certification and sealed-source transport. Oak Ridge National Laboratory in Tennessee maintains plutonium-238 production capacity, constraining supply expansion for deep-space thermoelectric generators.
Russia
ROSATOM's radioisotope division supplies polonium-210 and strontium-90 for space and defense applications across former Soviet states. The country's national nuclear regulator administers parallel licensing for domestic atomic battery programs alongside IAEA safeguards documentation. Production facilities near Moscow and Tomsk anchor isotope recovery from nuclear fuel reprocessing operations.
China
China's lunar exploration program and polar research infrastructure generate procurement specifications for temperature-immune power systems. The National Nuclear Safety Administration and Ministry of Ecology and Environment administer licensing for domestic programs. Beijing-Tianjin-Hebei research clusters evaluate americium-241 as a plutonium-238 alternative for extended-duration missions.
United Kingdom
The European Space Agency's Harwell campus studies americium-based systems for deep-space missions requiring half-lives beyond plutonium capabilities. Euratom framework regulations and REACH chemical rules impose constraints on sealed-source cross-border shipment. Culham Centre for Fusion Energy anchors national isotope handling expertise and workforce training pipelines.
Canada
CANDU reactor operations at Bruce Power and Ontario Power Generation yield tritium feedstock for commercial betavoltaic applications. Health Canada and the Canadian Nuclear Safety Commission govern byproduct material licensing for medical and industrial device integration. Chalk River Laboratories maintain heritage expertise in radioisotope thermoelectric generator design validation.
Atomic Battery Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and mission-critical integration depth. The vendor base stratifies between integrated aerospace primes with captive NRC relationships and specialized isotope handlers serving commercial remote sensing contracts. Three archetypes dominate: defense-anchored system integrators, betavoltaic specialists, and national laboratory technology transfer vehicles. Competitive moves center on power-as-a-service contracting models and segmented thermoelectric architecture licensing.
Within the defense-anchored tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify program-level relationships with Pentagon unmanned system procurement. City Labs occupies a position among betavoltaic specialists, representing commercial micro-power contracting for remote infrastructure networks. ROSATOM anchors the national laboratory transfer archetype, leveraging captive isotope production infrastructure for integrated system delivery.
| Leading Market Players |
|---|
| Exide Technologies |
| City Labs |
| NDB |
| Lockheed Martin Corporation |
| General Atomics |
| ROSATOM |
| NASA |
| Northrop Grumman Corporation |
| Curtiss Wright Nuclear |
| Others |
Pricing and Supply Chain Analysis
Captive isotope production at Oak Ridge National Laboratory and ROSATOM facilities anchors supply positions for thermoelectric generators, granting integrated vendors pricing power over buyers locked into NASA and Pentagon mission specifications. This vertical control over plutonium-238 and polonium-210 feedstocks insulates premium-tier suppliers from cost compression while forcing commercial betavoltaic competitors to compete on tritium sourcing efficiency.
Pricing Analysis
Mission-based contract pricing with decade-long service terms dominates aerospace and defense procurement, separating flight-proven thermoelectric systems from emerging betavoltaic alternatives. Price differentiation rests on NRC Category 1 certification status and isotope half-life specifications, with uncertified commercial cells facing intense cost compression from lithium-ion substitution. Margins are tightening in remote sensing applications as power-as-a-service vendors absorb regulatory liability to win oil and gas contracts. Military buyers show lowest price sensitivity, prioritizing operational lifespan over unit economics, while medical device manufacturers remain most cost-constrained.
Supply Chain Analysis
Direct-to-mission-prime channels handle NASA and Pentagon procurement, bypassing distributor layers for classified program integration. Geographic supply concentrates in the United States, Russia, and Canada, with Oak Ridge producing plutonium-238, ROSATOM facilities recovering polonium-210 and strontium-90, and CANDU reactors yielding tritium feedstock. Raw material dependencies center on specialized thermoelectric ceramics, semiconductor junction substrates, and radiation shielding alloys. Single-source vulnerability at Oak Ridge constrains deep-space generator expansion. Distribution runs through defense acquisition channels and civilian space agency specifications rather than open commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atomic battery market functions as a regulatory compounder, where NRC Category 1 certification timelines and isotope handling licenses create durable competitive moats. The US Nuclear Regulatory Commission's harmonization with Department of Transportation packaging rules accelerates program timelines for established vendors while extending barriers for new entrants.
For Market Incumbents: To counter plutonium-238 scarcity threatening deep-space generator output, secure alternative isotope qualification partnerships with ESA americium-241 programs and accelerate segmented thermoelectric architecture licensing to commercial remote sensing vendors. Backward integration into tritium handling infrastructure captures power-as-a-service revenue streams from Permian Basin and North Sea operators. For New Entrants and Emerging Players: Begin with betavoltaic cell manufacturing for implantable medical devices, where FDA-NRC dual pathway complexity deters aerospace incumbents and tritium supply stabilization reduces feedstock risk. Target cardiac pacemaker manufacturers seeking 20-year replacement intervals through semiconductor foundry partnerships offering integrated radiation safety programs. For Investors and Strategic Acquirers: Roll-up economics work for betavoltaic specialists because NRC exempt-quantity handling licenses fragment across regional service providers and power-as-a-service contracts generate decade-long recurring revenue. Monitor ESA americium-241 mission qualification data as the inflection signal for plutonium-238 alternative viability.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Isotope Qualification | ESA americium-241 programs reduce Oak Ridge plutonium-238 dependency for deep-space missions. |
| Power-as-a-Service Expansion | Oil and gas operators in the Permian Basin transfer regulatory liability to atomic battery vendors. |
| Segmented Thermoelectric Licensing | Jet Propulsion Laboratory architectures extend competitive moats for integrated system vendors. |
| Betavoltaic Medical Device Integration | Cardiac pacemaker manufacturers evaluate semiconductor junction cells for 20-year replacement intervals. |
| NRC-DOT Regulatory Harmonization | Consolidated certification pathways accelerate program timelines for established defense contractors. |
Research Methodology
Coverage spans the United States, Russia, China, the United Kingdom, and Canada, with primary inputs from each jurisdiction's nuclear regulatory framework. The analysis combines structured interviews with NASA program managers, Pentagon unmanned system procurement officers, NRC licensing specialists, and oil and gas subsea engineering directors with secondary validation from Department of Energy isotope production reports, ESA technical publications, IAEA safeguards documentation, and national laboratory research disclosures. Bottom-up segment sizing triangulates against top-down mission budget allocations.
Granularity-level modeling addresses battery type, isotope material, end-user sector, and application maturity across the projection horizon. The analytical framework derives CAGRs from mission specification timelines, defense procurement budget trajectories, and betavoltaic efficiency improvement curves. Industry-specific forecast inputs include plutonium-238 production capacity at Oak Ridge National Laboratory and tritium inventory release schedules from Canadian CANDU operations.
Several conditions sit outside the modeled scope, including small modular reactor regulatory precedents that could reshape isotope handling compliance burdens and unforeseen IAEA safeguards modifications affecting cross-border sealed-source transport. Forecasts reflect assumptions regarding sustained NASA Artemis funding and Pentagon unmanned underwater vehicle program expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Netherlands Rechargeable Battery Market
Batteries
Grid-Scale Flow Battery Stack Endurance Test Benches Market
Batteries
Non-Rechargeable Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Semi-Solid Flow Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Nuclear Battery Sales Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
Maintenance-Free Lead-Acid Battery Market
Batteries
South Europe Battery Market
Batteries
South Asia Battery Market
Batteries
Europe Battery Systems for Electric Vehicles Market
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
Grid-Scale Lead-Acid Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market