
 Electrolyte Solutions for Li-Ion Batteries Market | 2026-2036
Electrolyte Solutions for Li-Ion Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolyte Solutions for Li-Ion Batteries Market Insights
Electrolyte formulation services bundled with cell-design consulting is consolidating supplier-customer relationships in the battery materials sector. Mitsubishi Chemical Corporation leverages its integrated carbonate solvent and additive portfolio to anchor long-term supply agreements with Japanese automotive OEMs. Shenzhen Capchem Technology Co., Ltd. sustains cost-competitive positions through captive fluorinated salt production and proximity to China's cathode manufacturing belt. Soulbrain Co., Ltd. dominates the high-purity LiPF6 segment for premium cylindrical cells serving South Korean battery makers.
Electrolyte solutions for Li-ion batteries comprise lithium salts dissolved in organic carbonate solvent blends, with functional additives forming the solid-electrolyte interphase at graphite anodes to prevent capacity fade during charge cycling. These formulations enable ionic transport between electrodes while maintaining electrochemical stability across operating temperatures from minus twenty to sixty degrees Celsius. Liquid electrolytes occupy the dominant volume position due to mature manufacturing infrastructure and compatibility with existing cell assembly lines, though solid electrolytes represent the fastest-growing category as sulfide and oxide ceramic conductors approach commercial scale for next-generation solid-state architectures. Among components, electrolyte additives command disproportionate margin pools because proprietary additive packages differentiate cell performance metrics including cycle life and fast-charge capability.
FDA and EPA oversight in the United States governs worker exposure limits for organic carbonate solvents and fluorinated salt handling in electrolyte blending facilities. China's MIIT enforces GB standards for electrolyte purity and cell-level thermal runaway propagation, while the EU's REACH regulation restricts hazardous substance content in imported electrolyte formulations. South Korea's MFDS coordinates with METI-aligned Japanese standards to harmonize cross-border quality certifications for regional battery supply chains. Stakeholders must monitor regulatory divergence between jurisdictions on fluorinated compound restrictions and carbon footprint disclosure requirements to anticipate reformulation costs and sourcing reconfigurations.
Market Dynamics
High-voltage cathode chemistries above 4.3V are forcing electrolyte suppliers to reformulate solvent blends and additive packages, compressing development cycles and tightening purity specifications across the supply base.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating investment in localized LiPF6 production and closed-loop recycling infrastructure.
- Electric vehicle OEM procurement:Long-term supply agreements for 800V architecture cells are pulling high-concentration electrolyte formulations into mass production.
- Sulfide solid electrolytes:Pilot-scale sulfide ceramic processing is validating dry-electrode compatibility, opening pathways for solvent-free cell manufacturing.
Market Restraints
- LiPF6 supply concentration:Over 70% of battery-grade lithium hexafluorophosphate originates from Chinese salt processors, creating single-source vulnerability for non-Chinese cell makers.
- Carbonate solvent volatility:Ethylene carbonate and dimethyl carbonate pricing tracks ethylene oxide and methanol feedstock swings, eroding margin predictability for blenders.
- Moisture sensitivity:Sub-20 ppm water specifications require nitrogen-purged logistics and hermetic packaging, adding cost layers that scale with shipment distance.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting electrolyte formulators to Gujarat and Tamil Nadu industrial corridors.
- Stationary storage systems:Grid-scale battery deployments tolerate wider operating temperature ranges, enabling simplified additive packages and lower-cost solvent blends.
- Dual carbon goals:China's national carbon neutrality targets are mandating renewable-powered electrolyte plants, creating first-mover advantage for low-carbon-certified suppliers.
Industry Challenges
- Electrochemical engineer scarcity:Formulation expertise spanning organic synthesis, ionic transport modeling, and cell failure analysis concentrates at a handful of South Korean and Japanese research institutes.
- GB standard compliance timelines:China's MIIT certification cycles for new electrolyte additive combinations extend 18-24 months, delaying product launches versus unregulated markets.
- Solid-liquid interface engineering:Hybrid cell architectures combining oxide-coated separators with gel polymer electrolytes require cross-functional teams unfamiliar to traditional liquid electrolyte houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolyte Solutions for Li-Ion Batteries Market |
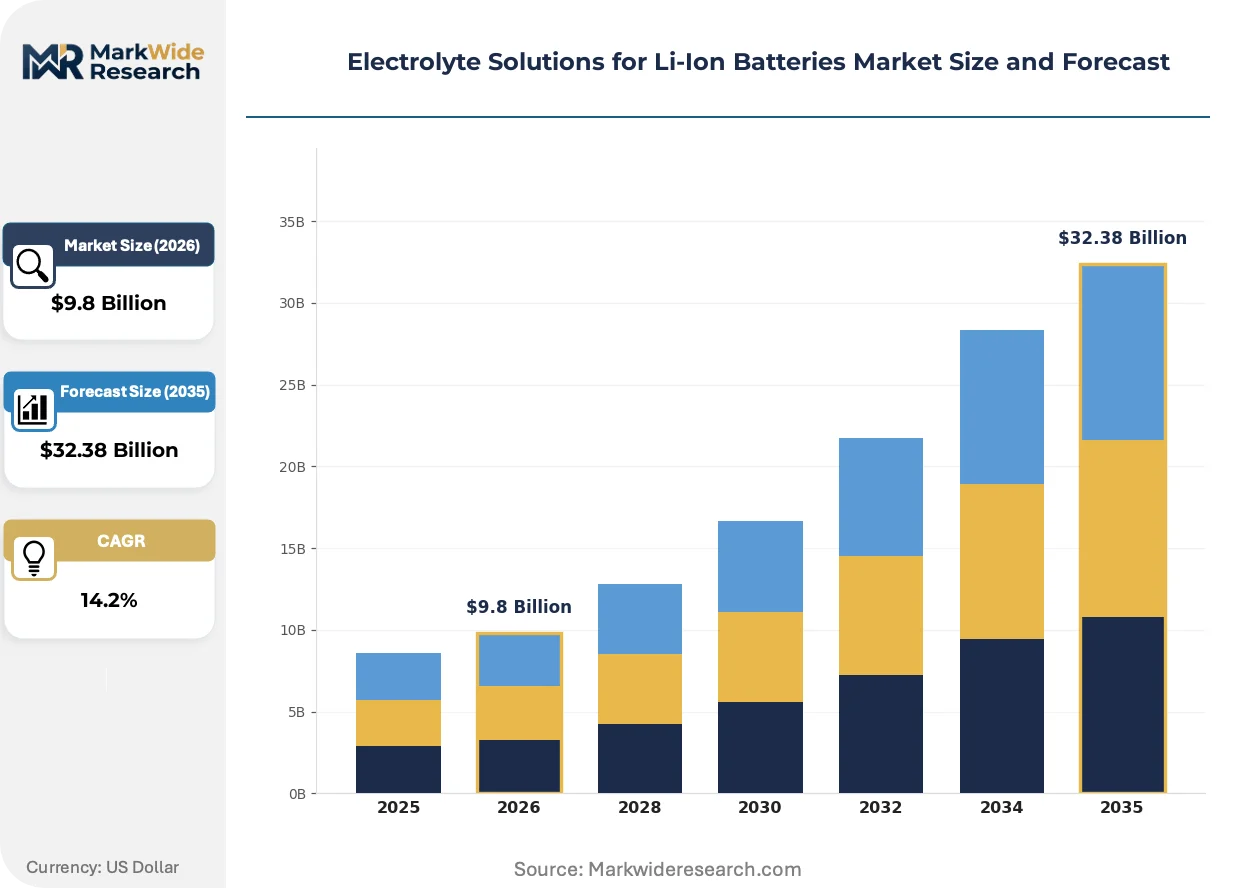
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $32.38 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolytes, Gel Electrolytes, Solid Electrolytes, Polymer Electrolytes Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Equipment Component: Electrolyte Additives, Solvents, Salts, Conductive Polymers End User: Aerospace, Automotive OEMs, Energy Providers, Electronics Manufacturers |
| Companies Covered | Mitsubishi Chemical Corporation, Shenzhen Capchem Technology Co., Ltd., Guangzhou Tinci Materials Technology Co., Ltd., Soulbrain Co., Ltd., ENCHEM Co., Ltd., Zhangjiagang Guotai-Huarong New Chemical Materials Co., Ltd., UBE Corporation, Dongwha Electrolyte, Shanshan Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolyte Solutions for Li-Ion Batteries Market Trends and Innovations
Novel additive chemistries are displacing conventional vinylene carbonate and fluoroethylene carbonate packages, promising enhanced high-temperature stability and reduced gas generation during formation cycling.
Sulfide-based solid electrolytes is unifying ionic conductivity benchmarks previously split between oxide ceramics and polymer composites. Automotive OEMs in Japan and South Korea are qualifying sulfide materials for 2027-2028 production targets. This convergence is compressing the technology readiness gap between laboratory-scale synthesis and gigafactory integration.
REACH authorization requirements for cyclic carbonate substances are compelling European formulators to submit full substance dossiers for novel co-solvents. The industrial consequence is a 12-18 month lag between laboratory validation and commercial import clearance. Premium cylindrical cell producers serving German automotive OEMs are absorbing these compliance costs through dedicated regulatory affairs teams.
Cell makers are consolidating electrolyte procurement under direct material partnerships rather than distributor-mediated spot purchasing. Tier-one battery producers in South Korea now specify salt-to-blend supply chains audited for carbon intensity and conflict mineral status. This preference shift is most visible in cathode-electrolyte clusters around Ulsan and Ochang, where co-located logistics parks enable just-in-time delivery windows under four hours.
Electrolyte Solutions for Li-Ion Batteries Market Segmentation
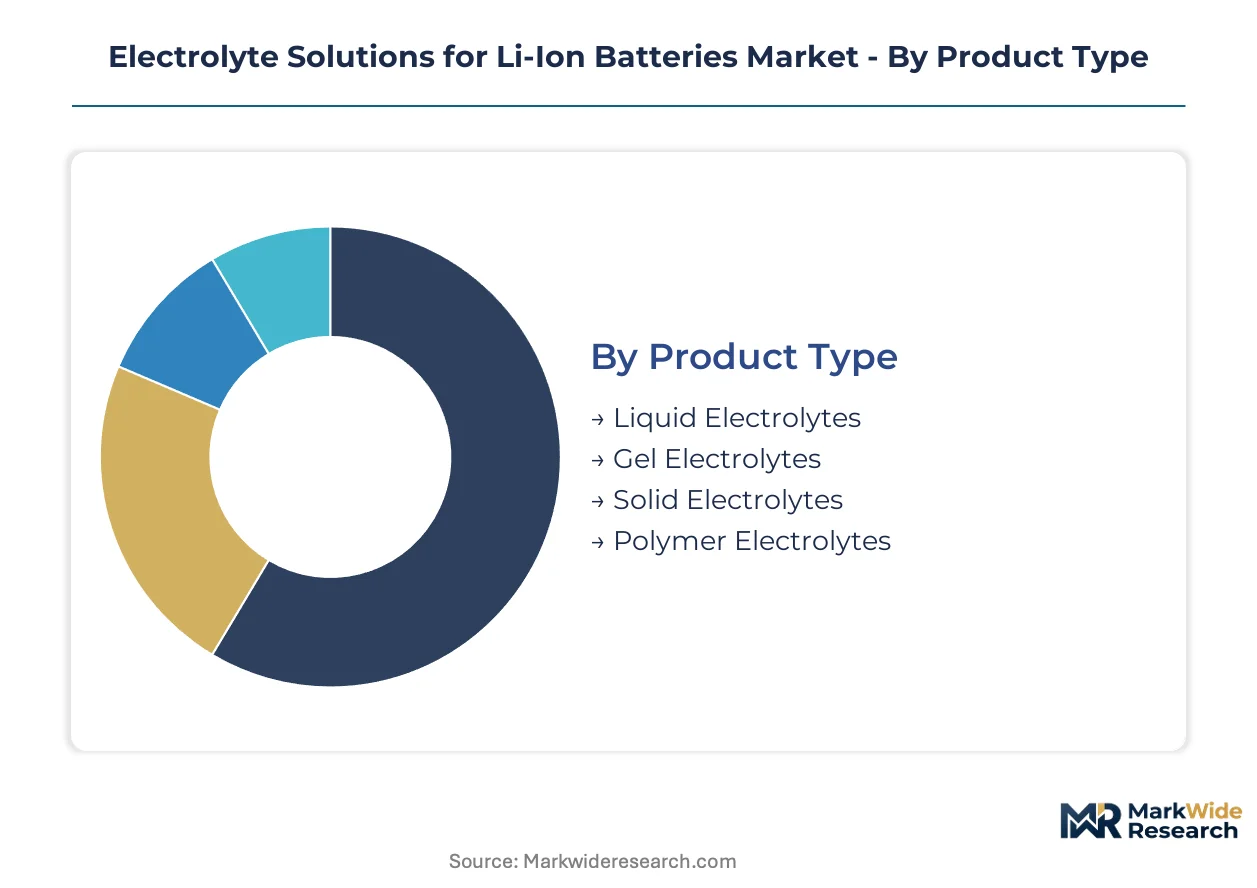
Electrolyte suppliers configure product portfolios around distinct performance tiers and application requirements. Cell chemistry roadmaps diverge across automotive, consumer, and stationary storage end-uses, forcing formulators to maintain parallel qualification tracks.
Product Type:
Upgrade cycles from conventional liquid systems to next-generation solid architectures are compressing supplier R&D timelines and reshaping capital allocation priorities.
- Liquid Electrolytes:Lithium salt solutions in carbonate solvent blends dominate current manufacturing infrastructure. Automotive OEM procurement for 800V architectures is pulling high-concentration formulations into mass production.
- Solid Electrolytes:Sulfide and oxide ceramic conductors enable solvent-free cell architectures with enhanced thermal stability. Pilot-scale validation by Japanese and South Korean battery makers is accelerating gigafactory integration timelines.
- Gel Electrolytes:Semi-solid matrices combining polymer hosts with retained liquid conductivity serve niche medical and wearable applications requiring mechanical flexibility.
- Polymer Electrolytes:Dry solid-state films eliminate leakage risks for thin-film microbatteries in Internet-of-Things sensors and smart cards.
Volume placements concentrate in liquid electrolytes; the faster expansion belongs to solid electrolytes.
Application:
Cost tier differentiation separates commodity formulations for grid storage from precision-blended premium grades for automotive qualification cycles.
- Electric Vehicles:High-voltage cathode compatibility above 4.3V demands customized additive packages and ultra-low moisture specifications. South Korean cathode-electrolyte clusters anchor regional supply security for cylindrical cell producers.
- Consumer Electronics:Pouch cell formats for smartphones and laptops prioritize energy density over cycle life. Shenzhen Capchem sustains cost-competitive positions through captive fluorinated salt production.
- Renewable Energy Storage:Grid-scale battery deployments tolerate wider operating temperature ranges, enabling simplified additive packages and lower-cost solvent blends.
- Industrial Equipment:Forklift and warehouse automation batteries require electrolyte formulations optimized for partial state-of-charge cycling durability.
Revenue concentration sits with electric vehicles; renewable energy storage is climbing the fastest.
Component:
Margin structures vary sharply across the formulation stack, with proprietary additives commanding premium pricing over commodity solvents and salts.
- Electrolyte Additives:Functional compounds forming the solid-electrolyte interphase at graphite anodes differentiate cell performance metrics. Novel chemistries displacing conventional vinylene carbonate packages are gaining traction for high-temperature stability.
- Salts:Lithium hexafluorophosphate constitutes the dominant conductivity source, though over 70% of battery-grade supply originates from Chinese processors. Soulbrain Co., Ltd. anchors the high-purity segment for premium cylindrical cells.
- Solvents:Ethylene carbonate and dimethyl carbonate blends provide the ionic transport medium, with pricing tracking ethylene oxide and methanol feedstock volatility.
- Conductive Polymers:Polymeric ion conductors serve specialized applications requiring mechanical integrity without liquid leakage risks.
Procurement volume clusters around salts; additive packages are gaining share fastest.
End User:
Customer type determines qualification intensity, with aerospace and automotive OEMs imposing the most stringent audit protocols for supply chain carbon intensity and conflict mineral status.
- Automotive OEMs:Direct material partnerships are replacing distributor-mediated spot purchasing for tier-one battery producers. Mitsubishi Chemical leverages integrated carbonate solvent and additive portfolios to anchor long-term Japanese supply agreements.
- Electronics Manufacturers:Consumer device assemblers prioritize formulation consistency and logistics reliability over technical customization.
- Energy Providers:Utility-scale project developers source electrolytes through engineering-procurement-construction contractors with bulk volume pricing structures.
- Aerospace:Satellite and aviation battery applications impose extreme purity specifications and extended qualification cycles for mission-critical reliability.
Contract value concentrates with automotive OEMs; energy providers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures over seventy percent of battery-grade lithium salts while South Korea and Japan consume the highest-value electrolyte formulations for automotive cell production. This production-consumption divide shapes trade flows and regulatory arbitrage across the supply chain.
China
Domestic cathode manufacturing clusters in Fujian and Hunan provinces pull electrolyte blending capacity inland from coastal ports. MIIT enforces GB standards for electrolyte purity and thermal runaway propagation testing. Shenzhen Capchem Technology Co., Ltd. operates captive fluorinated salt production within the Pearl River Delta cathode belt.
South Korea
OEM procurement for 800V architecture cylindrical cells drives demand for ultra-high-purity LiPF6 formulations. MFDS coordinates additive safety certifications with METI-aligned Japanese standards. The Ulsan-Ochang industrial corridor hosts co-located cathode-electrolyte logistics parks enabling sub-four-hour just-in-time delivery windows.
Japan
Automotive OEMs impose the most stringent supply chain audits for carbon intensity and conflict mineral status. METI-aligned quality standards harmonize cross-border certifications with South Korean battery makers. Mitsubishi Chemical Corporation leverages integrated carbonate solvent portfolios to anchor long-term supply agreements with domestic vehicle manufacturers.
United States
IRA production credits are attracting electrolyte formulators to co-locate with emerging cell manufacturing in the Southeast and Midwest. FDA and EPA oversight governs worker exposure limits for organic carbonate solvents in blending facilities. The Pacific Northwest hosts pilot-scale solid electrolyte validation programs with sulfide ceramic conductors.
Germany
REACH authorization requirements for cyclic carbonate substances impose twelve-to-eighteen-month lags between laboratory validation and commercial import clearance. The EU F-Gas Regulation phase-down mandates are accelerating investment in localized LiPF6 production and closed-loop recycling infrastructure. Premium cylindrical cell producers serving domestic automotive OEMs maintain dedicated regulatory affairs teams to absorb compliance costs.
Electrolyte Solutions for Li-Ion Batteries Market Competitive Landscape
Top-tier vendors anchor integrated salt-to-blend supply chains, while mid-tier formulators compete on regional logistics proximity and cost-optimized solvent portfolios. The market structure concentrates around Japanese and South Korean chemical conglomerates with captive carbonate production, Chinese specialists with backward integration into fluorinated salts, and European blenders navigating REACH compliance complexity. Three archetypes dominate: integrated chemical majors controlling upstream solvent supply, salt specialists commanding high-purity LiPF6 segments, and regional blenders optimizing for logistics cost and local certification speed. Competitive moves center on capacity co-location with cathode manufacturing clusters and strategic partnerships with automotive OEMs for 800V cell qualification cycles.
Within the integrated chemical major tier, Mitsubishi Chemical Corporation and UBE Corporation exemplify Japanese conglomerates with carbonate solvent and additive portfolios spanning multiple performance tiers. Shenzhen Capchem Technology Co., Ltd. represents Chinese specialists with backward integration into fluorinated salt production, occupying cost-competitive positions through proximity to cathode manufacturing belts. Soulbrain Co., Ltd. anchors the high-purity salt specialist archetype for premium cylindrical cell applications.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Shenzhen Capchem Technology Co., Ltd. |
| Guangzhou Tinci Materials Technology Co., Ltd. |
| Soulbrain Co., Ltd. |
| ENCHEM Co., Ltd. |
| Zhangjiagang Guotai-Huarong New Chemical Materials Co., Ltd. |
| UBE Corporation |
| Dongwha Electrolyte |
| Shanshan Technology |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals for renewable-powered electrolyte manufacturing gates qualified supply access and premium-tier pricing for low-carbon-certified suppliers serving automotive OEM procurement.
Pricing Analysis
Cost-down pressure on high-purity LiPF6 accelerates because automotive OEM procurement for 800V architectures demands ultra-low moisture specifications and customized additive packages. Three-tier pricing structure across automotive qualification grades, industrial standard formulations, and grid storage commodity blends dominates the market. Price differentiation rests on certification grade and volume scale, with premium cylindrical cell producers absorbing REACH compliance costs through dedicated regulatory affairs teams. Grid-scale energy providers exhibit highest price sensitivity; aerospace and automotive OEMs show lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Nitrogen-purged logistics and hermetic packaging costs scale nonlinearly with shipment distance from Chinese salt processors to South Korean cathode-electrolyte clusters. Geographic supply concentration centers on China for battery-grade lithium hexafluorophosphate, South Korea for high-purity formulation blending, and Japan for integrated carbonate solvent production. Raw material dependencies draw from ethylene oxide and methanol feedstocks for carbonate solvents, fluorinated salt precursors, and specialty additive chemistries. Single-source vulnerability from over 70% Chinese LiPF6 concentration creates structural risk. Distribution runs through direct material partnerships audited for carbon intensity and conflict mineral status, replacing distributor-mediated spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid electrolyte architectures are displacing conventional liquid systems as sulfide ceramic conductors approach commercial scale, compressing supplier R&D timelines and reshaping capital allocation priorities.
For Market Incumbents: Hedge against sulfide solid electrolyte substitution by anchoring long-term supply agreements with Japanese automotive OEMs while maintaining parallel qualification tracks for liquid electrolyte formulations. Deepen backward integration into captive fluorinated salt production to defend margin position against Chinese specialists with Pearl River Delta proximity. Prioritize GB standard compliance investment to accelerate MIIT certification cycles for novel additive combinations. For New Entrants and Emerging Players: Stationary storage system developers represent an underserved buyer archetype tolerating wider operating temperature ranges and simplified additive packages. India's PLI scheme for advanced chemistry cell manufacturing offers the most penetrable geography, with Gujarat and Tamil Nadu industrial corridors attracting electrolyte formulators. Pursue cost-optimized solvent portfolios through regional logistics proximity rather than technical customization. For Investors and Strategic Acquirers: Pilot-scale sulfide ceramic validation by Japanese and South Korean battery makers is the leading indicator that solid-state gigafactory integration timelines are compressing. The five-to-ten-year viability window favors acquisition targets with dry-electrode compatibility expertise and cross-functional teams spanning oxide-coated separator engineering. Monitor EU F-Gas Regulation phase-down mandates as the inflection signal for localized LiPF6 production investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorinated Salt Production | Shenzhen Capchem sustains cost-competitive positions through captive LiPF6 supply within China's cathode manufacturing belt. |
| Long-term Supply Agreement with Automotive OEMs | Mitsubishi Chemical anchors Japanese vehicle manufacturer relationships through integrated carbonate solvent and additive portfolios. |
| Green Manufacturing Transition | China's dual carbon goals mandate renewable-powered electrolyte plants, creating first-mover advantage for low-carbon-certified suppliers. |
| Joint Venture for Sulfide Solid Electrolyte Scale-Up | Pilot-scale validation programs in the Pacific Northwest accelerate solvent-free cell manufacturing pathways. |
| Capacity Expansion in Cathode-Electrolyte Clusters | Co-located logistics parks around Ulsan and Ochang enable sub-four-hour just-in-time delivery windows for South Korean battery makers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with electrolyte formulation directors, cathode plant managers, automotive OEM procurement leads, and MIIT certification specialists. Secondary sources drew from MIIT GB standard documentation, ECHA REACH substance dossiers, EPA worker exposure guidelines, and SEC filings from integrated chemical majors. Bottom-up volume modeling triangulated against top-down demand aggregation from electric vehicle production forecasts and stationary storage deployment pipelines.
Reconciliation of salt production volumes, solvent blending capacity, and cell manufacturing output streams shaped the analytical framework across the projection horizon. Segmentation dimensions spanned electrolyte state, application end-use, component margin tier, and customer qualification intensity. CAGRs derived from elasticity-adjusted demand curves incorporating high-voltage cathode chemistry roadmaps and solid-state technology readiness transitions. Industry-specific inputs included ethylene oxide and methanol feedstock pricing volatility and nitrogen-purged logistics cost scaling functions.
Revisions become necessary when regulatory divergence on fluorinated compound restrictions accelerates, sulfide solid electrolyte pilot programs achieve commercial scale, or automotive OEM procurement shifts from 800V to higher-voltage architectures. Forecasts reflect documented assumptions on technology substitution rates and certification timeline elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Bio Based Battery Market
Batteries
FORTELION Battery Module Market
Batteries
India Rechargeable Battery Market
Batteries
18650 And 21700 Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Asia-Pacific Consumer Battery Market
Batteries
Battery Anode Materials Market
Batteries
Solid Electrolyte Market
Batteries
USA Forklift Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Vanadium Redox Batteries Market
Batteries
United States Household Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Watch Battery Market
Batteries
Elastic Battery Binders Market