
 Europe Lead-Acid Battery Market | 2026-2036
Europe Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lead-Acid Battery Market Foresight
Lead-acid battery chemistry is fragmenting across multiple electrochemical architectures as manufacturers balance cost, cycle life, and recyclability. EnerSys leverages its European manufacturing footprint to sustain long-term supply agreements with industrial UPS buyers. Clarios anchors its position through closed-loop lead recycling infrastructure that reduces raw material exposure. Robert Bosch GmbH competes in the automotive starter battery segment through OEM channel control and service network density.
Europe lead-acid batteries are rechargeable electrochemical cells using lead dioxide cathodes, sponge lead anodes, and sulfuric acid electrolyte, typically operating at nominal voltages of 2V per cell with energy densities of 30–50 Wh/kg. The technology serves as economical bulk energy storage for engine starting, backup power, and off-grid renewable systems where capital cost sensitivity outweighs energy density requirements. Flooded batteries still occupy the largest share of automotive starting applications due to established supply chains and low unit costs, while AGM variants are capturing share in premium vehicles and cyclic industrial roles where maintenance-free operation commands value. The renewable energy application segment is expanding fastest as rural solar installations and microgrids in Southern and Eastern Europe adopt deep-cycle lead-acid for overnight storage.
The EU Green Deal and REACH frameworks mandate responsible lead sourcing and end-of-life collection, while CE marking and the EU Battery Regulation set performance and labeling standards that filter lower-tier imports. ECHA substance restrictions and national Extended Producer Responsibility schemes in Germany and France raise compliance costs but also consolidate demand around certified domestic recyclers. Stakeholders must monitor how carbon border adjustments and evolving recycling efficiency thresholds reshape cost structures for imported versus locally manufactured cells.
Market Dynamics
The EU Battery Regulation and F-Gas Regulation are compressing margins for non-compliant imports while consolidating procurement around certified domestic recyclers with closed-loop lead recovery capabilities.
Growth Catalysts
- Data Center Buildouts:Hyperscale facilities in Frankfurt and Amsterdam are procuring megawatt-scale stationary backup systems, pulling premium AGM and gel-cell configurations into long-term service contracts.
- REACH-Driven Circularity:Extended Producer Responsibility schemes in Germany and France now mandate minimum recycling efficiency thresholds, rewarding manufacturers with captive smelter networks.
- Eastern European Solar Microgrids:Rural installations across Poland and Romania are adopting deep-cycle flooded batteries for overnight storage where lithium-ion capital costs remain prohibitive.
Market Restraints
- Lead Price Volatility:LME lead pricing swings directly compress cell margins for distributors without forward hedging programs or captive mine offtake.
- Energy Density Ceiling:The 30–50 Wh/kg practical limit excludes lead-acid from electric vehicle traction applications regardless of cost advantage.
- Chinese Import Competition:Non-compliant flooded batteries from unregistered producers circumvent CE marking through gray-channel distribution in Southern Europe.
Strategic Opportunities
- Polish Industrial Automation:Automotive component plants in Silesia are retrofitting UPS systems, creating demand for high-rate discharge AGM cells with 10-year design life.
- Carbon Border Adjustment Mechanism:CBAM phase-in from 2026 penalizes embedded emissions in imported cells, advantaging European smelters with renewable-powered recycling.
- Telecom Tower Hybridization:Operators are blending lead-acid with lithium-ion in hybrid racks, preserving the former for surge capacity and temperature resilience.
Industry Challenges
- Lead Smelter Talent Shortage:Electrochemical engineering expertise for battery-grade lead refining is concentrating at a handful of Central European facilities.
- EU Battery Regulation Certification Lag:New carbon footprint declaration and recycled content verification requirements are extending product launch timelines by 8–14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lead-Acid Battery Market |
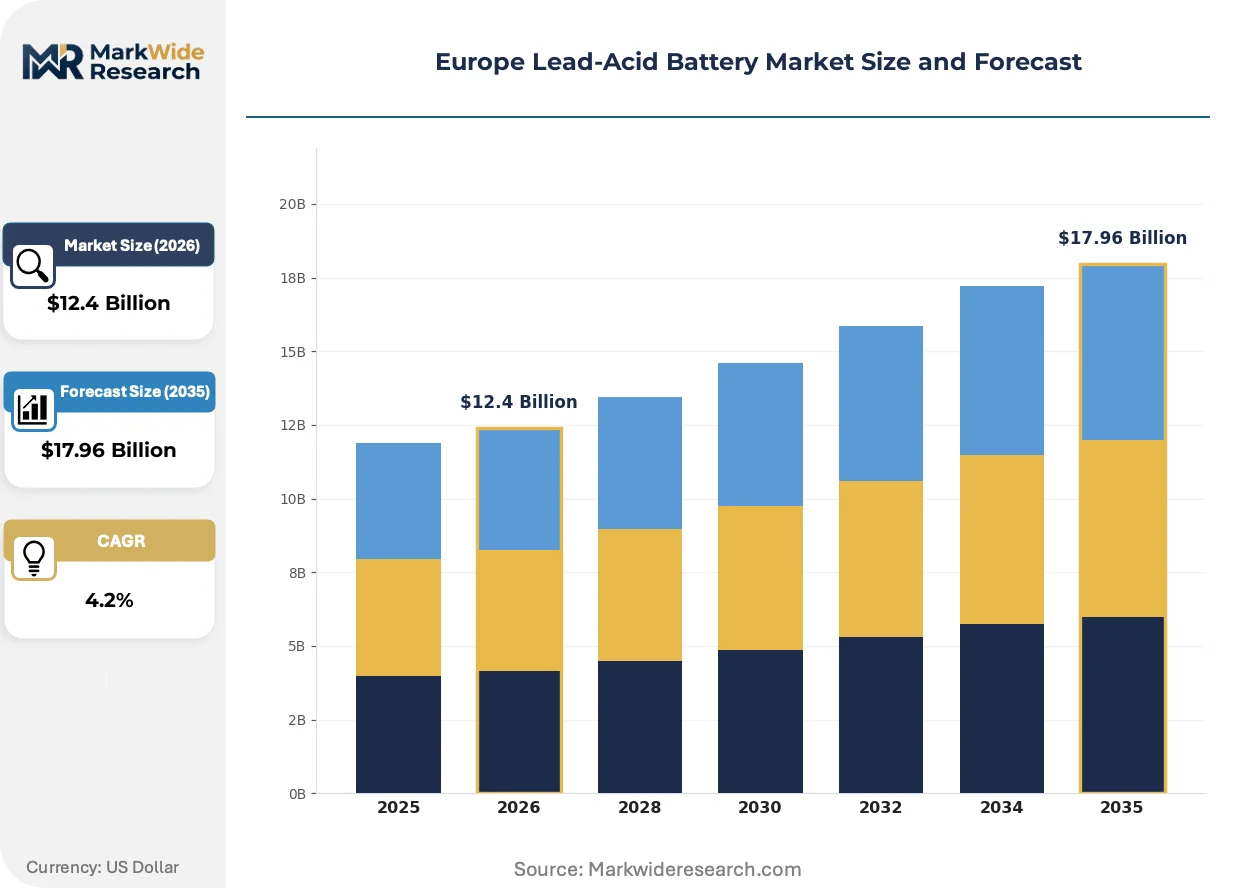
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $17.96 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, UPS, Telecom, Renewable Energy Type: Flooded, AGM, Gel, Lithium Hybrid End User: Manufacturing, Construction, Transportation, Energy Technology: Lead Recycling, Valve-Regulated, Absorbent Glass Mat, Deep Cycle |
| Companies Covered | EnerSys, FIAMM Energy Technology S.p.A, Clarios, Robert Bosch GmbH, TAB Batteries, Exide Technologies, Banner Batterien, Leoch International Technology Limited, GS Yuasa Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lead-Acid Battery Market Shifts & Advancements
Electrochemical architectures are diverging as manufacturers optimize for either cycle endurance or capital cost, while regulatory pressure on carbon intensity and material provenance rewrites procurement specifications.
Carbon foam negative electrodes are migrating from laboratory validation to pilot production lines at industrial battery specialists. Data center operators in the Netherlands and Ireland are testing these configurations for partial state-of-charge cycling resilience. The technology is compressing the total cost-of-ownership gap against entry-level lithium-ion for 4–6 hour backup applications.
The EU Battery Regulation's digital battery passport mandate requires full supply chain traceability from 2027. Manufacturers must disclose recycled lead content and carbon intensity per kWh. Automotive OEMs in Germany are already rejecting cells without verified passport data, filtering spot-market suppliers from approved vendor lists.
Asset-light leasing models are displacing outright purchase for telecom and UPS applications. Energy service companies in France and Spain now offer battery-as-a-service contracts with performance guarantees and end-of-life takeback. This transfers recycling compliance risk from tower operators to manufacturers with certified smelter networks.
Europe Lead-Acid Battery Market Segmentation
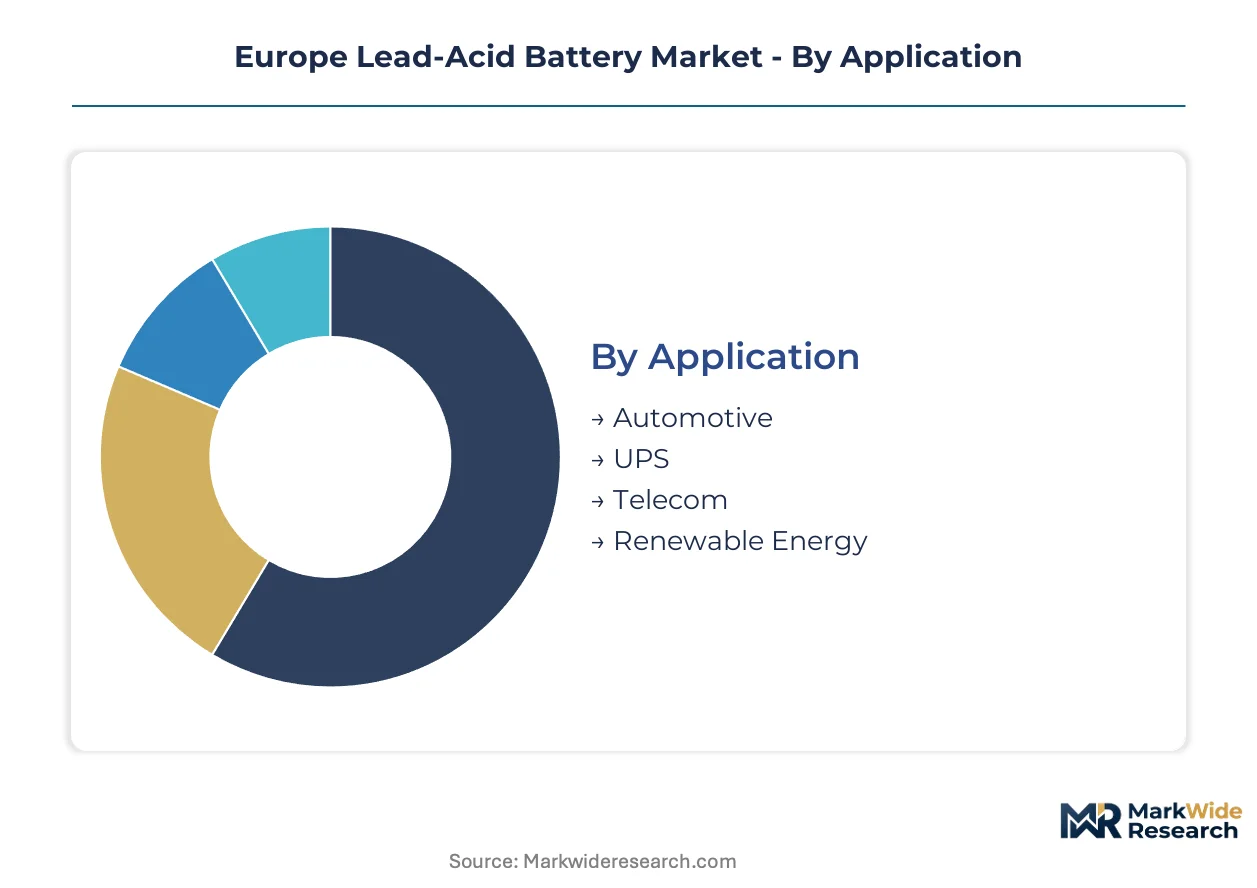
Lead-acid battery procurement in Europe fragments across electrochemical architectures, end-use intensity cycles, and compliance-grade requirements. Each dimension reshapes margin structures and supplier qualification pathways differently.
Application:
Application segments map directly to duty cycle profiles and replacement frequency economics, separating high-turnover automotive from long-life stationary installations.
- Automotive:Starter-lighting-ignition batteries dominate unit volume across OEM and aftermarket channels, with AGM configurations penetrating stop-start vehicle architectures. German and French automakers specify enhanced flooded designs for cost-sensitive platforms while reserving AGM for premium segments.
- UPS:Uninterruptible power supply installations in Frankfurt and Amsterdam data centers specify high-rate discharge AGM cells with 10-15 year design life. REACH-mandated recycling certificates now gate entry to hyperscale procurement lists.
- Telecom:Remote tower infrastructure across Poland and Romania favors maintenance-free valve-regulated designs for temperature resilience in uncontrolled enclosures.
- Renewable Energy:Rural solar microgrids in Southern and Eastern Europe adopt deep-cycle flooded architectures where lithium-ion capital costs remain prohibitive for off-grid developers.
Automotive holds installed capacity. Renewable Energy is rotating up the share rankings.
Type:
Type distinctions capture electrolyte immobilization methods and maintenance requirements, with cost premiums scaling to operational convenience.
- Flooded:Conventional liquid electrolyte designs retain cost leadership in price-sensitive automotive starting and deep-cycle renewable applications. Established supply chains across Spain and Italy sustain volume production despite weight and maintenance penalties.
- AGM:Absorbent glass mat separators enable sealed operation and position-tolerant mounting for UPS and premium automotive segments. Dutch data center operators specify AGM for vibration resistance in containerized power modules.
- Gel:Silica-thickened electrolyte variants tolerate deep discharge cycling and temperature extremes in telecom and marine applications. French rail infrastructure operators specify gel cells for platform backup systems.
- Lithium Hybrid:Rack configurations blending lead-acid surge capacity with lithium-ion energy density are penetrating telecom tower retrofits. German operators pilot hybrid architectures to preserve temperature resilience while reducing footprint.
Flooded retains volume dominance. Lithium Hybrid is climbing the fastest in new installation specifications.
End User:
End user categories align with industrial capital expenditure cycles and regulatory exposure to carbon accounting mandates.
- Manufacturing:Automotive component plants in Silesia and Bavaria retrofit UPS systems with high-rate discharge cells to protect automated production lines from grid instability.
- Construction:Temporary power and equipment starting applications favor low-cost flooded batteries with rapid replacement schedules.
- Transportation:Fleet operators and rail infrastructure specify maintenance-free designs for reduced total cost of ownership across vehicle and signaling applications.
- Energy:Utility-scale renewable integration and substation backup drive demand for long-life deep-cycle configurations with verified carbon footprint declarations.
Manufacturing holds installed capacity. Energy is rotating up the share rankings.
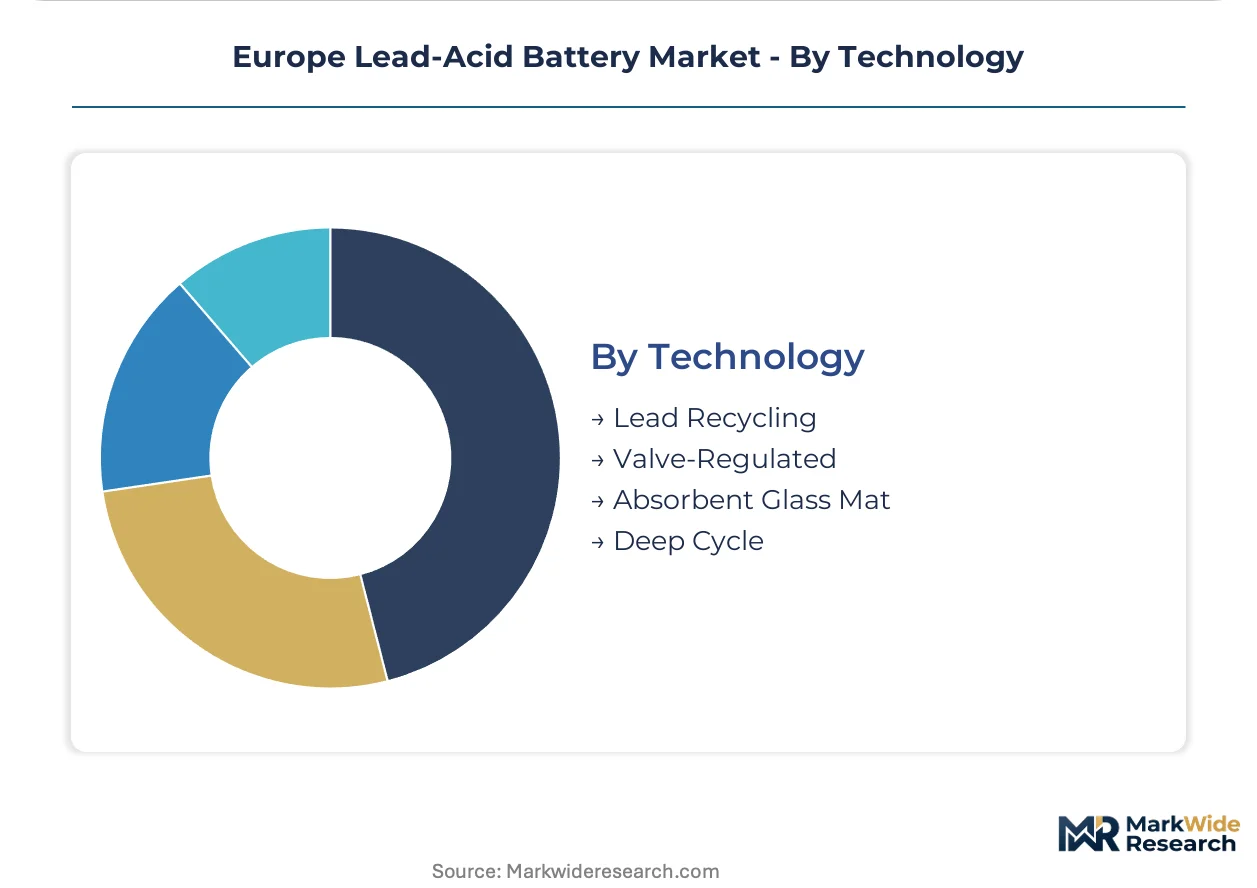
Technology:
Technology segments differentiate around materials recovery capabilities and electrochemical optimization for specific duty cycles.
- Lead Recycling:Closed-loop smelter networks in Germany and France recover battery-grade lead with renewable-powered refining, satisfying EU Battery Regulation recycled content thresholds. Clarios and EnerSys anchor positions through captive recycling infrastructure.
- Valve-Regulated:Sealed recombinant designs eliminate watering requirements for telecom and UPS applications where access is constrained. CE marking compliance filters gray-market competition from unregistered producers.
- Absorbent Glass Mat:Electrolyte saturation control enables high-rate discharge and partial state-of-charge tolerance for premium automotive and data center segments.
- Deep Cycle:Thick-plate architectures optimize cycle endurance for renewable energy storage and electric vehicle traction in industrial fleets.
Lead Recycling holds installed capacity. Deep Cycle is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish battery exports flow to German automotive OEMs and Dutch data center operators, establishing a Central European supply corridor that channels lead-acid cells into high-specification industrial applications.
Germany
Automotive starter battery demand from Stuttgart and Wolfsburg OEMs drives volume procurement of enhanced flooded and AGM configurations. The KBA enforces type-approval standards that filter non-compliant imports from approved supplier lists. Bavarian industrial automation plants in Ingolstadt and Regensburg retrofit UPS systems with high-rate discharge cells to protect precision manufacturing lines.
France
Rail infrastructure operators in Paris and Lyon specify gel-cell architectures for platform backup systems requiring deep discharge tolerance. ANSM and national Extended Producer Responsibility schemes mandate recycling efficiency thresholds that reward manufacturers with captive smelter networks. Auvergne-Rhône-Alpes hosts concentrated lead refining capacity serving battery-grade material demand.
Poland
Automotive component plants in Silesia procure megawatt-scale stationary backup for robotic assembly line protection. The national environmental regulator enforces EU Battery Regulation alignment through carbon footprint declaration requirements. Warsaw-area distribution hubs channel Polish-manufactured cells into Romanian and Bulgarian renewable microgrid projects.
Netherlands
Hyperscale data center operators in Amsterdam and Eindhoven specify AGM configurations for containerized power modules requiring vibration resistance. REACH compliance gates entry to procurement lists for facilities serving EU-wide cloud infrastructure. Rotterdam's port logistics cluster handles bulk lead concentrate imports feeding Central European smelter networks.
Spain
Rural solar installations across Andalusia and Extremadura adopt deep-cycle flooded batteries for overnight storage where lithium-ion capital costs exclude off-grid developers. The national climate regulator implements EU Green Deal recycling mandates through regional collection scheme enforcement. Barcelona-area manufacturing retains cost-leadership in conventional liquid electrolyte designs for Mediterranean aftermarket channels.
Europe Lead-Acid Battery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where OEM relationships and recycling infrastructure determine margin capture. The market consolidates around three strategic archetypes: integrated manufacturers with captive smelter networks, automotive channel specialists leveraging service density, and industrial UPS providers securing long-term service contracts. Dominant competitive moves include backward integration into lead refining capacity and geographic expansion through distribution partnerships in Eastern European growth markets.
Among integrated manufacturers, EnerSys and Clarios anchor positions through closed-loop recycling infrastructure that satisfies EU Battery Regulation thresholds. Robert Bosch GmbH exemplifies the automotive channel specialist archetype, leveraging OEM relationships and service network density in German and French aftermarket segments. These three players represent distinct competitive vectors—recycling-integrated supply security, automotive channel control, and industrial service contracting—that structure rivalry across application segments.
| Leading Market Players |
|---|
| EnerSys |
| FIAMM Energy Technology S.p.A |
| Clarios |
| Robert Bosch GmbH |
| TAB Batteries |
| Exide Technologies |
| Banner Batterien |
| Leoch International Technology Limited |
| GS Yuasa Corporation |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp barge freight corridors carry lead concentrate from Iberian mines to Central European smelters, with route cost volatility feeding directly into cell pricing tiers and procurement concentration around certified recyclers with captive logistics contracts.
Pricing Analysis
AGM-to-flooded-to-gel pricing spreads widen as carbon foam electrodes enter pilot production, compressing mid-tier value propositions. Three-tier pricing structure across premium certification-grade, standard CE-marked, and economy flooded tiers reflects after-sales service bundling and recycling certificate inclusion. Pricing pressure stems from Chinese gray-market imports circumventing ECHA substance declarations. Renewable microgrid developers in Poland and Romania exhibit highest price sensitivity, while Frankfurt data center operators prioritize 10-year design life over unit cost.
Supply Chain Analysis
EU Battery Regulation material provenance rules restrict lead concentrate flows from non-certified smelters outside the customs union, channeling supply toward German, Polish, and French refining capacity. Battery-grade lead draws from Spanish mine concentrates, recycled secondary lead from domestic smelter networks, and sulfuric acid from regional chemical producers. Single-source vulnerability concentrates at Central European facilities with electrochemical engineering expertise gaps. Distribution runs through Warsaw and Amsterdam hubs serving Eastern European renewable installations and Western European industrial automation clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe lead-acid battery demand is recovering through data center buildout cycles and renewable storage project pipelines, with Frankfurt and Amsterdam hyperscale commitments providing visible procurement anchors across the projection horizon.
For Market Incumbents: Pre-empt lithium-ion encroachment in telecom hybrid racks by accelerating carbon foam electrode commercialization and securing 10-year service contracts with Dutch data center operators. Backward integration into renewable-powered smelter capacity in Auvergne-Rhône-Alpes satisfies EU Battery Regulation recycled content thresholds before digital passport mandates activate. For New Entrants and Emerging Players: Rural solar microgrids across Romania and Bulgaria represent the most penetrable entry point, with deep-cycle flooded battery demand outpacing certified supplier capacity. Polish automotive component plant UPS retrofits offer second-tier volume opportunity. Go-to-market through Warsaw distribution partnerships with carbon footprint declaration capabilities gates access to German OEM approved vendor lists. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded lead-acid battery divisions lacking closed-loop recycling infrastructure. Five-to-ten year viability hinges on EU Battery Regulation compliance cost absorption and lithium-ion substitution pace in stationary applications. Monitor CBAM phase-in enforcement stringency as early inflection indicator for European smelter margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Smelter Network Expansion | Auvergne-Rhône-Alpes renewable-powered refining satisfies ECHA recycled content mandates for automotive OEM procurement. |
| Carbon Foam Electrode Scale-Up | Netherlands data center pilot programs validate partial state-of-charge cycling resilience against entry-level lithium-ion. |
| Digital Battery Passport Integration | Full supply chain traceability from 2027 gates access to German automaker approved vendor lists. |
| Hybrid Rack Configuration Development | Telecom tower operators blend lead-acid surge capacity with lithium-ion density for temperature resilience. |
| Extended Producer Responsibility Compliance | German and French recycling efficiency thresholds consolidate demand around certified domestic recyclers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with battery manufacturing executives, lead smelter operations directors, data center procurement managers, and automotive OEM platform engineers; and secondary validation through ECHA substance restriction filings, EU Battery Regulation implementation guidance, customs trade data for lead concentrate flows, and SEC disclosures from publicly traded energy storage companies. Bottom-up cell shipment estimates by application and country triangulated against top-down smelter capacity and renewable project development databases.
Forecast inputs span electrochemical architecture adoption curves, REACH-driven circularity compliance cost trajectories, and hyperscale data center construction pipelines across the analysis window. Segmentation modeling incorporated application duty cycle intensity, type maintenance requirements, end user capital expenditure cycles, and technology materials recovery capabilities. CAGRs derived from volume-weighted average of country-level demand projections calibrated to industrial automation and renewable storage project announcements.
Practitioners should monitor lead price volatility on LME markets, CBAM enforcement phase-in timing, and lithium-ion cost curve movements for early signals of forecast deviation. Material shifts in EU Battery Regulation recycled content verification requirements or carbon border adjustment scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Li-Ion Pouch Battery Market
Batteries
West Africa Battery Market
Batteries
Tubular GEL Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
America SLI Battery Market
Batteries
HIT Battery Market
Batteries
Europe Battery Cell Market
Batteries
Vietnam Battery Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Drone Power Sources Market
Batteries
Smart Battery Charger Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Automotive AGM Battery Market
Batteries
Tubular Batteries Market
Batteries
Flow Battery Market