
 Lithium-Ion Battery Anode Market | 2026-2036
Lithium-Ion Battery Anode Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Anode Market Outlook
UN 38.3 lithium battery transport certification is redrawing supplier qualification requirements for anode material producers seeking cell maker partnerships. BTR New Material Group leverages integrated mining-to-refining operations across graphite feedstock assets. POSCO Future M anchors large-scale synthetic graphite output from its Pohang complex. Mitsubishi Chemical Group Corporation differentiates through proprietary surface treatment technologies that enhance cycle stability.
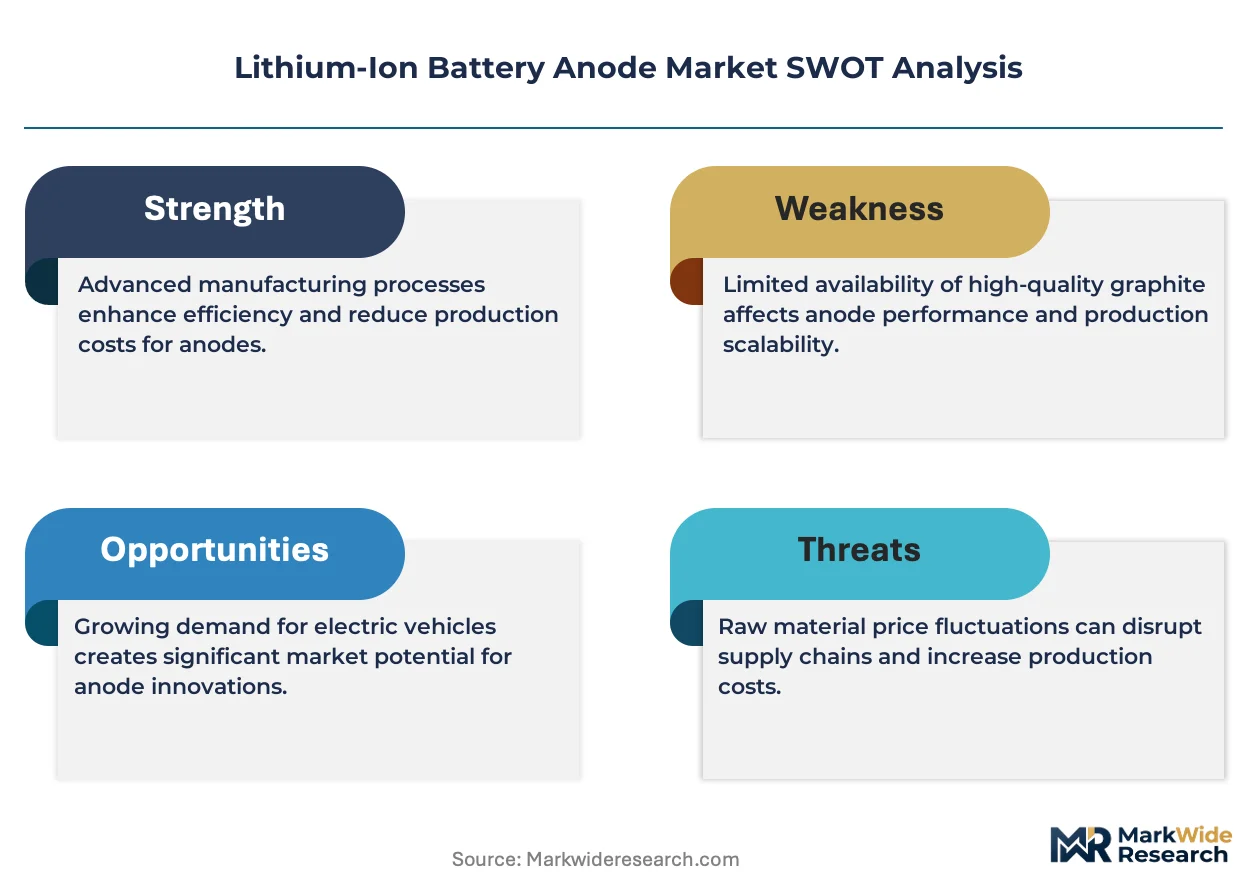
Lithium-ion battery anodes function as the negative electrode during electrochemical cycling, typically comprising carbonaceous matrices with intercalation potentials near 0.05 V versus lithium metal that enable reversible lithium ion storage at capacities of 340–360 mAh/g for graphite variants. Silicon-based alternatives promise theoretical capacities exceeding 4,000 mAh/g but require engineered binder systems and nano-structured architectures to accommodate volumetric expansion during lithiation. Graphite maintains dominant commercial share across electric vehicle applications where cell makers prioritize proven cycle life and manufacturing scale. Silicon blends represent the fastest-expanding product category as automotive manufacturers demand higher energy density packs for extended-range platforms. Energy storage systems applications favor lithium titanate configurations where ultra-long cycle life offsets higher material costs in grid-scale deployments.
EPA tailpipe emission rules and China's MIIT new energy vehicle credit mandates jointly accelerate anode specification tightening across automotive supply chains. REACH substance restrictions in Europe constrain certain synthetic graphite precursor chemistries, redirecting R&D toward bio-based and recycled feedstock pathways. Stakeholders must monitor silicon content thresholds in qualification protocols as cell makers balance energy density gains against manufacturing yield risks in high-volume gigafactory environments.
Market Dynamics
Silicon-blend anode chemistry is forcing a wholesale reconfiguration of qualification protocols across cell manufacturing, as energy density mandates from EPA and MIIT outpace the cycle-life reliability of incumbent graphite systems.
Growth Catalysts
- EPA Vehicle Emission Standards:Tightening tailpipe rules in the US accelerate OEM demand for higher energy density cells, directly pulling silicon-enhanced anode specifications into procurement contracts.
- China's Dual Carbon Goals:Beijing's MIIT credit mandates for new energy vehicles create binding volume floors that favor advanced anode materials capable of extending single-charge range.
- Pohang-Gwangyang Cluster Concentration:South Korea's integrated cathode-anode manufacturing corridor enables just-in-time material flows that reduce qualification friction for next-generation formulations.
Market Restraints
- Petroleum Coke Feedstock Volatility:Synthetic graphite precursor costs fluctuate with refining margins, compressing anode producer margins when oil markets spike.
- UN 38.3 Certification Bottlenecks:Transport safety testing timelines for novel silicon-blend chemistries extend supplier onboarding cycles by 6-18 months versus conventional graphite.
- Volumetric Expansion Physics:Silicon's 300% lithiation swelling demands engineered binder architectures that remain unproven at automotive gigafactory scale.
Strategic Opportunities
- India PLI Scheme for ACC:Production-linked incentives for advanced chemistry cells create first-mover advantages for anode suppliers establishing local precursor processing.
- Grid-Scale Energy Storage:Lithium titanate configurations for 20,000-cycle utility deployments represent a premium segment with less silicon-blend competition.
- EU Battery Regulation Recycled Content Mandates:2030 thresholds for recovered graphite in new cells reward anode producers with closed-loop refining capabilities.
Industry Challenges
- Electrolyte Formulation Expertise Gap:Silicon-compatible additive chemistry requires rare skill sets concentrated in Japanese and South Korean research institutes.
- Gigafactory Yield Ramp Complexity:High-volume cell lines face defect rate spikes when transitioning from graphite to silicon-blend slurry coating processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Anode Market |
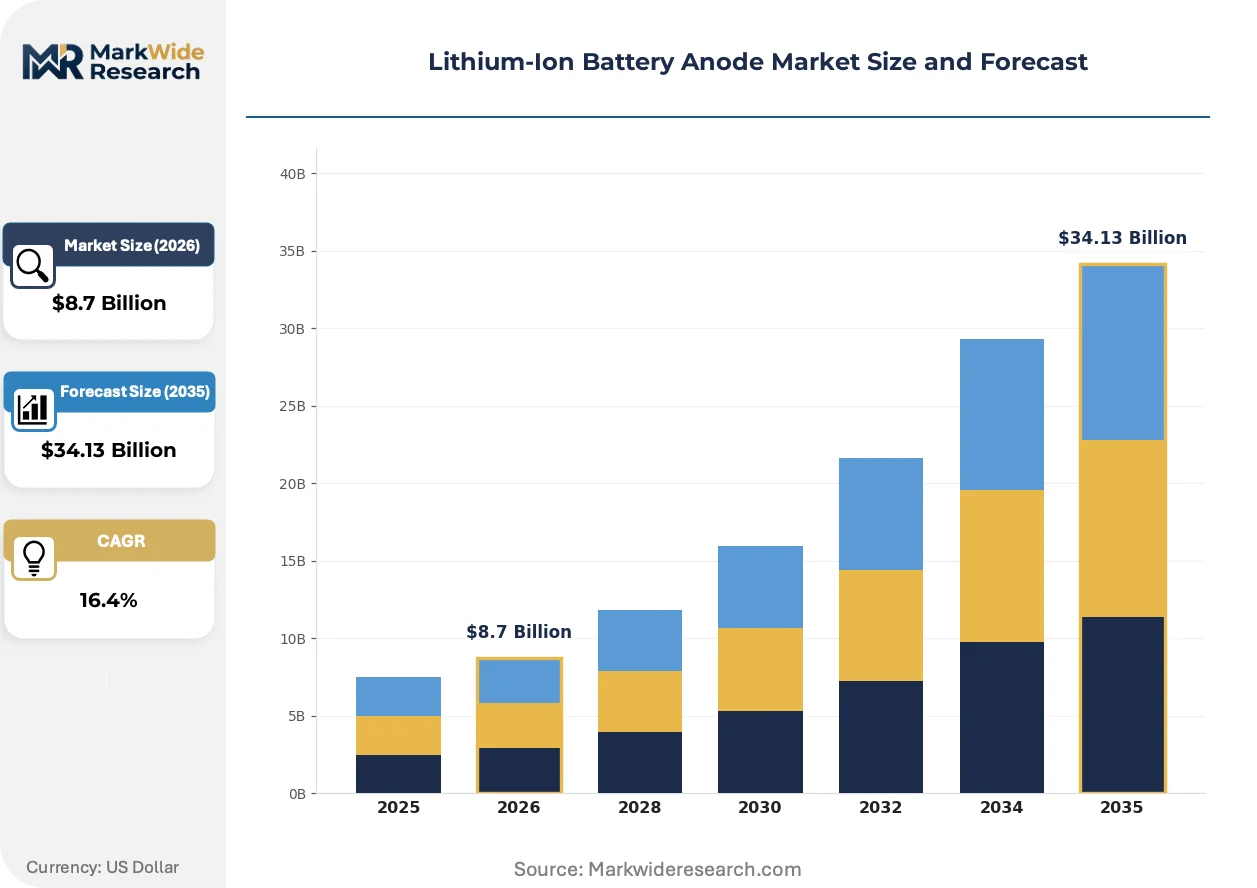
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite, Silicon, Lithium Titanate, Other Application: Electric Vehicles, Consumer Electronics, Energy Storage Systems, Aerospace End User: Automotive Manufacturers, Electronics Companies, Power Utilities, Aerospace Firms Innovation Stage: Research & Development, Prototype, Commercialization, Mass Production |
| Companies Covered | POSCO Future M, SGL Carbon, Ningbo Shanshan Co., Ltd., Jiangxi Zhengtuo New Energy Technology, Tokai Carbon, BTR New Material Group, Mitsubishi Chemical Group Corporation, Showa Denko Materials, Resonac Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Anode Market Strategic Shifts
Anode technology trajectories are diverging sharply between evolutionary graphite optimization and disruptive silicon architectures, with regulatory pressure and manufacturing scale determining which path dominates specific end-use segments.
Silicon nano-structuring is bifurcating the anode supply base into two distinct tiers. High-purity silicon nanoparticles enable 400-600 mAh/g blended electrodes for premium electric vehicle platforms. Korean and Chinese cell makers are qualifying these formulations for 2026-2027 vehicle programs. The technology is bifurcating procurement relationships, as established graphite suppliers without silicon capabilities face exclusion from flagship OEM battery contracts.
REACH substance restrictions are redirecting European synthetic graphite R&D toward bio-based needle coke alternatives. ECHA's evolving candidate list constrains certain petroleum-derived precursor chemistries used in high-performance anodes. German and Scandinavian anode producers are accelerating pilot lines for lignin-derived carbon feedstocks to preempt compliance-driven supply disruptions.
Cell maker consolidation is compressing supplier qualification windows and raising technical collaboration requirements. Tier-one battery manufacturers now demand co-development agreements rather than arms-length material procurement. This pattern is most pronounced in South Korea, where POSCO Future M and Samsung SDI maintain captive engineering relationships that lock out second-tier anode vendors from premium supply tiers.
Lithium-Ion Battery Anode Market Segmentation
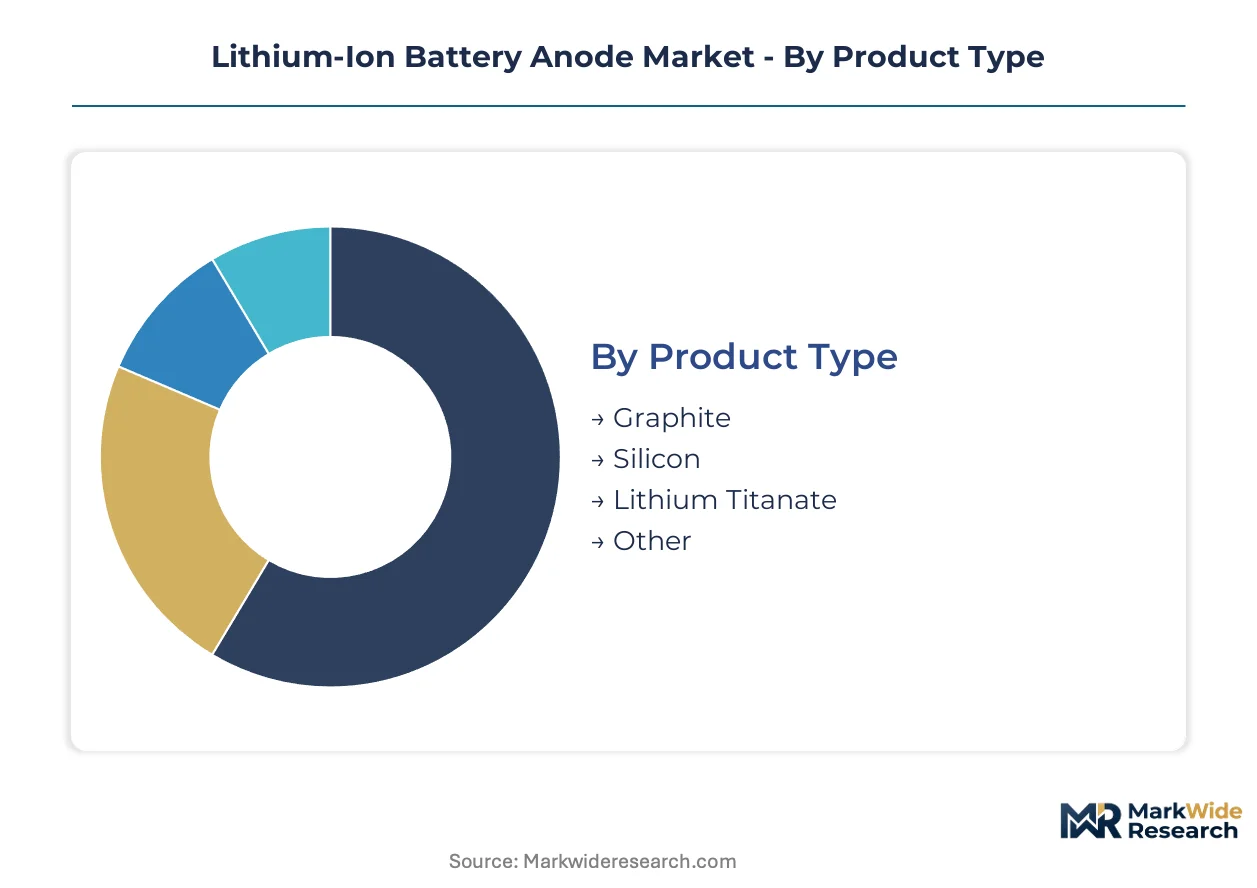
Anode material selection determines cell energy density, cycle life, and manufacturing economics. Each segmentation dimension reveals distinct margin structures and qualification barriers that shape supplier competitive position.
Product Type:
Margin pools concentrate in materials capable of meeting automotive energy density thresholds without sacrificing manufacturing yield.
- Graphite:Carbonaceous matrices with intercalation potentials near 0.05 V versus lithium metal deliver 340-360 mAh/g reversible capacity. Korean cell makers at Pohang and Gwangyang facilities anchor procurement volumes as EPA emission standards tighten range requirements.
- Silicon:Theoretical capacities exceeding 4,000 mAh/g demand engineered binder systems and nano-structured architectures to manage 300% volumetric expansion during lithiation. Silicon-blend formulations are expanding most quickly as OEMs specify higher energy density packs for extended-range electric vehicle platforms.
- Lithium Titanate:Ultra-long cycle life configurations offset higher material costs in grid-scale deployments where 20,000-cycle durability justifies premium positioning.
- Other:Hard carbon and alloy-type materials serve niche medical and specialty applications with limited automotive crossover.
The dominant share belongs to Graphite, while Silicon is closing the gap fastest.
Application:
Volume concentration tracks directly to regulatory mandates that enforce minimum energy density or emission performance.
- Electric Vehicles:EPA tailpipe rules and China's MIIT credit mandates jointly accelerate anode specification tightening. Cell makers prioritize proven cycle life and manufacturing scale in procurement decisions.
- Consumer Electronics:Smartphone and laptop manufacturers favor graphite-dominant anodes where space constraints matter less than cost optimization and supply security.
- Energy Storage Systems:Utility deployments favor lithium titanate configurations where calendar life and thermal stability outweigh energy density metrics.
- Aerospace:Satellite and electric aircraft applications impose stringent UN 38.3 transport certification requirements that extend supplier qualification timelines.
Electric Vehicles commands the largest volume position, though Energy Storage Systems is gaining share fastest as grid interconnection queues expand.
End User:
Procurement sophistication varies sharply, with automotive OEMs imposing the most demanding technical collaboration requirements.
- Automotive Manufacturers:Tier-one battery producers demand co-development agreements rather than arms-length material procurement, locking anode suppliers into multi-year engineering relationships.
- Electronics Companies:Consumer device assemblers prioritize supply security and cost predictability over technical co-development, maintaining broader qualified supplier bases.
- Power Utilities:Grid operators specify lithium titanate anodes for frequency regulation and renewable integration projects with 20-plus year service life requirements.
- Aerospace Firms:Aviation and satellite manufacturers impose qualification protocols that exclude all but the most mature anode chemistries from procurement consideration.
Automotive Manufacturers hold the dominant procurement volume, while Power Utilities are expanding their anode demand most steeply.
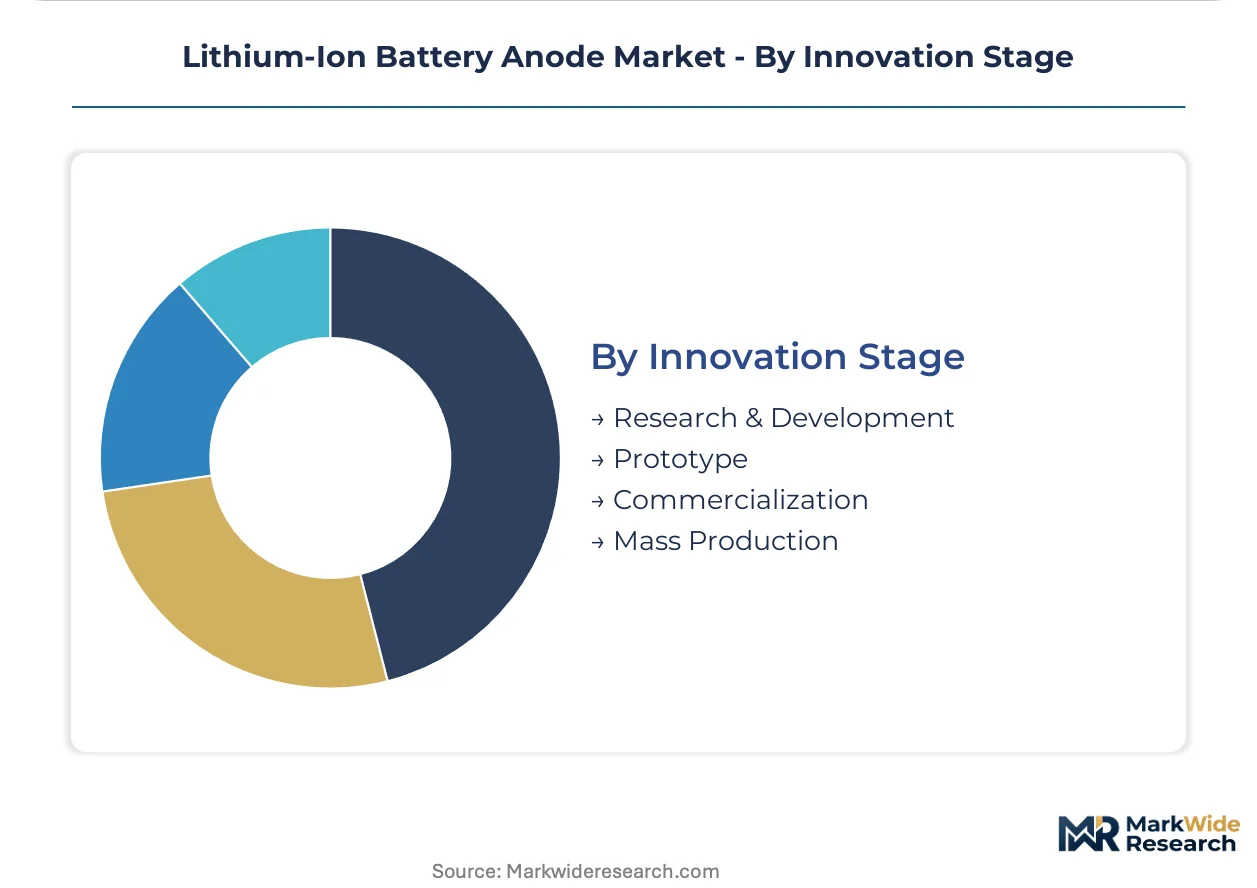
Innovation Stage:
Capital deployment intensity peaks at the transition from prototype validation to commercial-scale production.
- Research & Development:Laboratory-scale silicon nano-structuring and bio-based precursor pathways absorb R&D funding without near-term revenue contribution.
- Prototype:Engineered silicon-blend formulations undergo cell maker qualification testing with 6-18 month UN 38.3 certification timelines.
- Commercialization:First commercial volumes of silicon-enhanced anodes ship to Korean and Chinese cell makers for 2026-2027 vehicle program integration.
- Mass Production:Synthetic graphite from Pohang-complex facilities and integrated mining-to-refining operations in China supply established automotive qualification protocols.
Mass Production dominates supply volumes, though Commercialization is climbing the fastest as silicon-blend formulations achieve automotive qualification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes in India and China's MIIT credit mandates are redirecting anode manufacturing capacity toward Asia-Pacific industrial corridors. EPA emission standards in the United States and REACH substance restrictions in Europe are simultaneously tightening qualification requirements for cell maker partnerships.
China
MIIT new energy vehicle credit mandates enforce binding volume floors that pull silicon-blend anode specifications into procurement contracts. The country's dual carbon goals accelerate cell energy density targets for extended-range electric vehicle platforms. Jiangxi and Zhejiang provinces host integrated mining-to-refining operations that supply synthetic graphite feedstock to domestic cell makers.
South Korea
Pohang and Gwangyang industrial clusters enable just-in-time material flows between cathode and anode producers. UN 38.3 lithium battery transport certification timelines compress supplier onboarding cycles for qualified vendors. POSCO Future M anchors large-scale synthetic graphite output from its Pohang complex, locking in regional supply chain integration.
United States
EPA vehicle emission standards tighten tailpipe rules that accelerate OEM demand for higher energy density cells. The Inflation Reduction Act domestic content provisions reshape qualification protocols for anode material producers seeking automotive partnerships. Michigan and Tennessee gigafactory corridors concentrate cell manufacturing capacity that pulls upstream anode supply chain investment.
Germany
ECHA REACH substance restrictions constrain certain petroleum-derived synthetic graphite precursor chemistries used in high-performance anodes. The EU Battery Regulation recycled content mandates redirect R&D toward bio-based needle coke alternatives. Bavaria and North Rhine-Westphalia host pilot lines for lignin-derived carbon feedstocks to preempt compliance-driven supply disruptions.
India
PLI scheme production-linked incentives for advanced chemistry cells create first-mover advantages for anode suppliers establishing local precursor processing. Central Electricity Authority grid interconnection standards favor lithium titanate configurations for utility-scale deployments. Gujarat and Tamil Nadu industrial corridors attract anode material investments targeting domestic cell manufacturing scale-up.
Lithium-Ion Battery Anode Market Competitive Environment
Player mix skews toward integrated mining-to-refining operators and synthetic graphite specialists with captive engineering relationships. Market structure concentrates procurement influence among tier-one battery manufacturers demanding multi-year co-development agreements. Two strategic archetypes dominate: vertically integrated feedstock controllers and surface treatment technology licensors. Competitive moves center on capacity expansion in Pohang-Gwangyang and Jiangxi-Zhejiang corridors alongside strategic partnerships locking qualification protocols.
Within the integrated feedstock tier, BTR New Material Group and Ningbo Shanshan Co., Ltd. exemplify Chinese operators with mining-to-refining asset control. POSCO Future M occupies a position as the Korean synthetic graphite anchor, representing the captive engineering relationship archetype with domestic cell makers. Mitsubishi Chemical Group Corporation sits within the surface treatment technology tier, exemplifying Japanese specialists with proprietary cycle stability enhancement capabilities.
| Leading Market Players |
|---|
| POSCO Future M |
| SGL Carbon |
| Ningbo Shanshan Co., Ltd. |
| Jiangxi Zhengtuo New Energy Technology |
| Tokai Carbon |
| BTR New Material Group |
| Mitsubishi Chemical Group Corporation |
| Showa Denko Materials |
| Resonac Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with Korean cell makers lock in both synthetic graphite supply access and price visibility for anode producers, insulating procurement teams from petroleum coke feedstock volatility while binding volumes to MIIT-mandated energy density trajectories.
Pricing Analysis
UN 38.3 certification tier creates the primary spread between qualified and unqualified suppliers, with transport-safety-validated silicon-blend anodes commanding premium positioning over conventional graphite. Three-tier pricing structure separates automotive-grade formulations from consumer electronics specifications and grid-scale lithium titanate configurations. Cost compression in synthetic graphite runs through petroleum coke refining margin exposure, while silicon-blend premiums reflect electrolyte additive expertise scarcity. Power utilities demonstrate lowest price sensitivity due to 20,000-cycle durability requirements, whereas consumer electronics assemblers prioritize cost predictability over technical collaboration.
Supply Chain Analysis
Strait of Malacca transit underwrites needle coke feedstock flows from Middle Eastern refineries to Jiangxi-Zhejiang processing hubs, exposing anode producers to maritime logistics concentration. Feedstock sourcing draws from Chinese mining-to-refining operations, Korean Pohang-complex synthetic graphite output, and Japanese surface treatment technology licensors. Single-source vulnerability concentrates in petroleum coke precursor supply, where refining capacity constraints ripple through qualified supplier tiers. Distribution runs through cathode-anode cluster corridors enabling just-in-time material flows to cell manufacturing lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where UN 38.3 certification timelines and MIIT qualification protocols create structural barriers that extend incumbent advantage windows.
For Market Incumbents: Fortify captive engineering relationships with tier-one battery manufacturers through co-development agreements that embed silicon-blend specifications into 2026-2027 vehicle programs. Expand Pohang-complex synthetic graphite capacity to preempt feedstock competition from Chinese integrated operators. Prioritize electrolyte additive R&D partnerships with Japanese research institutes to defend against emerging silicon nano-structuring specialists. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors for advanced chemistry cells, where domestic precursor processing incentives create qualification shortcuts absent from saturated Korean-Chinese supply tiers. Target grid-scale lithium titanate deployments for utility frequency regulation, a premium segment with less silicon-blend competition and 20-plus year service life requirements. Lead with closed-loop refining capabilities to capture EU Battery Regulation recycled content mandates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among anode producers with integrated mining-to-refining assets and long-term offtake visibility. Five-to-ten year viability hinges on silicon-blend commercialization scale rather than graphite optimization maturity. Acquisition target archetype: mid-cap specialists with UN 38.3 certification progress and Korean cell maker qualification relationships. Monitor EPA emission standard tightening velocity as inflection indicator for silicon content thresholds in OEM procurement contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Blend Capacity Expansion | Captures EPA and MIIT energy density mandates pulling advanced anode specifications into automotive procurement. |
| Backward Integration into Needle Coke | Insulates margin structures from petroleum refining volatility while securing synthetic graphite precursor supply. |
| UN 38.3 Certification Investment | Accelerates supplier onboarding timelines with tier-one battery manufacturers and unlocks aerospace qualification tiers. |
| Joint Venture with Korean Cell Makers | Locks in Pohang-Gwangyang cluster access and embeds co-development protocols for next-generation formulations. |
| Closed-Loop Refining Capability Buildout | Positions for EU Battery Regulation recycled content thresholds while differentiating against petroleum-derived competitors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, encompassing anode material procurement managers at tier-one battery manufacturers, synthetic graphite plant engineers at Pohang-complex facilities, electrolyte formulation specialists at Japanese research institutes, and utility-scale energy storage project developers. Secondary validation incorporated customs and trade data for needle coke feedstock flows, SEC filings from integrated mining-to-refining operators, MIIT new energy vehicle credit mandate documentation, and ECHA REACH substance restriction updates. Bottom-up volume modeling triangulated against top-down regulatory mandate impact assessments.
Across the analysis window, the forecasting framework segmented by product type, application, end user, and innovation stage, with additional dimensional modeling for regional regulatory cluster alignment. CAGRs were derived from regression analysis against EPA emission standard trajectory scenarios and MIIT credit mandate enforcement patterns. Industry-specific inputs included silicon content qualification timelines, petroleum coke refining margin sensitivity curves, and gigafactory yield ramp complexity factors.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA and MIIT regulatory enforcement; material deviation in emission standard tightening velocity or silicon-blend manufacturing yield breakthroughs would warrant model refresh. Practitioners should keep alternative scenarios live as REACH substance restriction evolution and EU Battery Regulation recycled content mandate implementation timelines clarify.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
Lithium Cobalt Oxide Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
UAV Lithium Battery Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Nanotechnology Enabled Battery Market
Lithium-ion Battery
Lithium Battery Pack Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Marine Lithium-Ion Battery Market