
 North Europe Battery Market | 2026-2036
North Europe Battery Market Size, Share, and Industry Trends Forecast 2026-2036
North Europe Battery Market Analytics
Software-defined battery management is shifting value capture from cell hardware to predictive analytics and fleet optimization subscriptions. Northvolt AB leverages its vertically integrated cell-to-pack architecture to control cost positions across the Nordic supply base. FREYR Battery anchors its growth on Norwegian renewable energy access for low-carbon cell production. Saft specializes in defense and industrial nickel-based systems, occupying a premium tier with long-cycle reliability requirements.
North Europe batteries encompass electrochemical energy storage devices utilizing lithium-ion, solid-state, or nickel-metal hydride chemistries with nominal voltages from 3.2V to 800V and cycle lives exceeding 2,000 deep discharges, engineered for grid stabilization, electric propulsion, and portable power applications. Lithium-ion technology dominates installed capacity, though solid-state formulations represent the fastest-growing technology segment as manufacturers resolve ceramic electrolyte manufacturing yields. Energy Storage Systems applications attract the deepest margin pools, driven by Scandinavian grid operators procuring multi-hour duration assets for wind and solar balancing. Electric Vehicles constitute the largest volume segment, with Automotive OEMs demanding high-capacity packs above 80 kWh for premium Nordic SUV and sedan platforms.
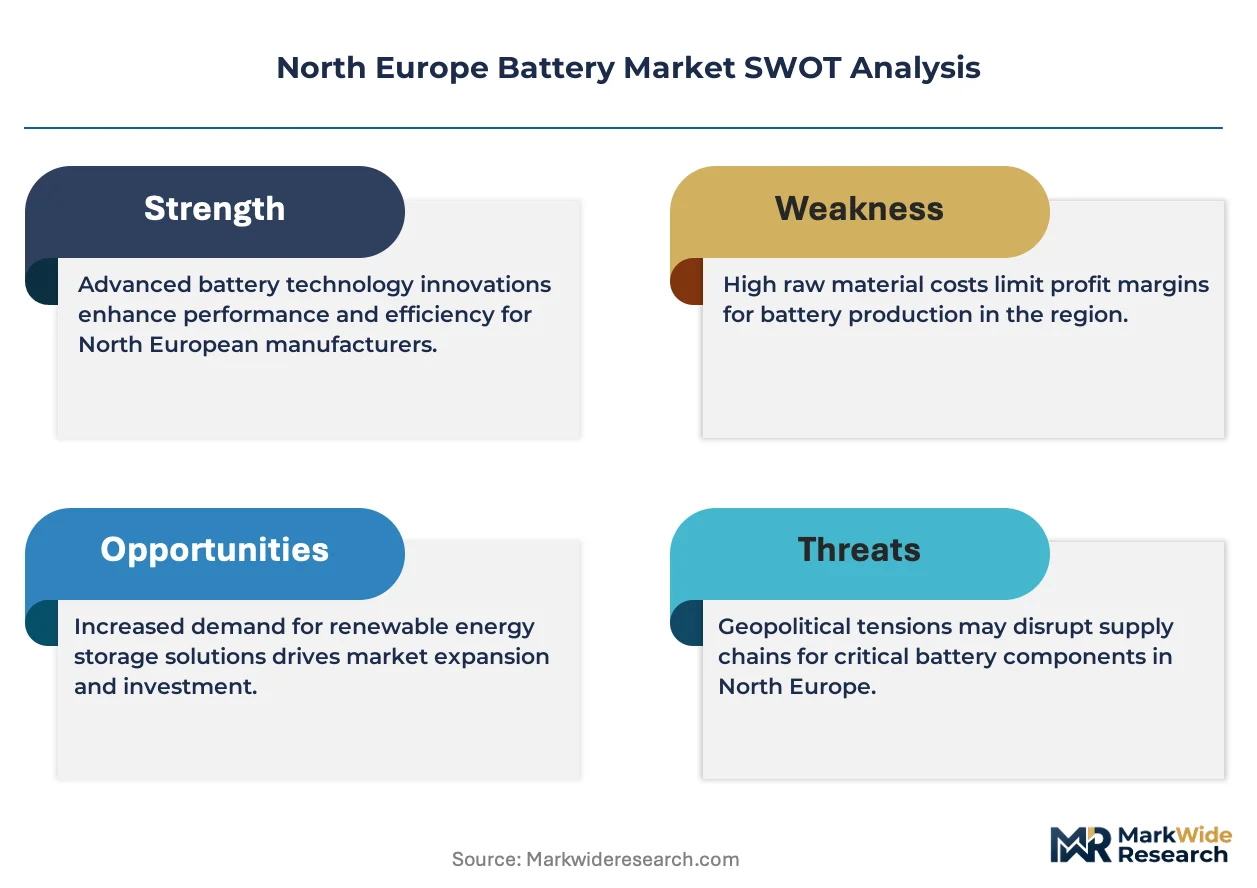
EU Battery Regulation mandates carbon footprint declarations and recycled content minimums, compelling producers to reconfigure supply chains toward European-sourced active materials. ECHA REACH restrictions on nickel and cobalt compounds shape cathode chemistry selection and water treatment investments across Finnish and Swedish production sites. Norway's national battery strategy aligns with dual carbon goals through MEE enforcement of lifecycle emissions thresholds. Stakeholders must monitor regulatory tightening on due diligence for raw material extraction, as compliance costs will separate integrated Nordic producers from import-dependent assemblers.
Market Dynamics
EU Battery Regulation carbon footprint declarations are forcing Nordic producers to reconfigure active material sourcing toward European-sourced supply chains, compressing cost positions for import-dependent assemblers while rewarding vertically integrated cell manufacturers with captive mining partnerships.
Growth Catalysts
- Norwegian hydroelectric grid integration:Near-zero marginal power costs enable electrolytic processing of battery-grade materials at 40-60 percent below continental European energy benchmarks, attracting cell production capacity to Nordic industrial zones.
- EU Green Deal industrial policy:Strategic autonomy mandates and production-linked incentives under the Net-Zero Industry Act channel capital toward domestic cell manufacturing, tightening offtake commitments from Scandinavian grid operators for multi-hour duration storage assets.
- Solid-state ceramic electrolyte manufacturing:Resolving sintering yield rates above 85 percent unlocks energy densities exceeding 400 Wh/kg, positioning Nordic producers to capture premium automotive platform contracts requiring 800V architectures.
Market Restraints
- Lithium carbonate price volatility:Concentrated South American brine and Australian spodumene supply exposes Nordic cell producers to input cost swings exceeding 300 percent across 18-month cycles, compressing margin visibility for long-dated offtake contracts.
- ECHA REACH nickel compound restrictions:Classification of nickel sulfate and cobalt chloride as substances of very high concern imposes water treatment capital burdens exceeding 15 million euros per production line, disadvantaging cathode-active-material plants against Asian competitors with less stringent effluent standards.
- Solid-state manufacturing yield gaps:Ceramic electrolyte layer defect rates above 20 percent at pilot scale prevent cost parity with liquid-electrolyte lithium-ion systems, delaying commercial deployment timelines for next-generation Nordic cell platforms.
Strategic Opportunities
- Finnish-Swedish mining corridor development:Keliber lithium spodumene deposits and Rönnskär cobalt refinery capacity enable fully traceable European active material supply chains, satisfying EU Battery Regulation recycled content minimums and due diligence requirements for Nordic OEMs.
- Second-life stationary storage applications:Retired electric vehicle packs from Norwegian and Swedish logistics fleets aggregate into 2-4 hour grid balancing assets, creating aftermarket revenue streams for battery management software providers with predictive degradation analytics.
- Nordic defense procurement modernization:NATO alignment commitments accelerate nickel-metal hydride and lithium-thionyl chloride system orders for subsea and arctic applications, opening premium-tier contracts with 15-20 year operational life requirements.
Industry Challenges
- Electrochemical engineering talent scarcity:Solid-state ceramic processing and dry electrode coating expertise concentrates in Asian and North American research clusters, forcing Nordic producers to relocate R&D functions or compete for limited European technical university graduates.
- Cell-to-pack certification timelines:UN 38.3 transport testing and IEC 62660 automotive qualification protocols require 18-24 month validation cycles, delaying revenue recognition for novel form factors and thermal management architectures.
- Legacy grid interconnection standards:Scandinavian transmission system operators maintain divergent frequency response requirements, complicating standardized energy storage system designs and forcing product customization for Swedish, Norwegian, and Finnish utility procurements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Europe Battery Market |
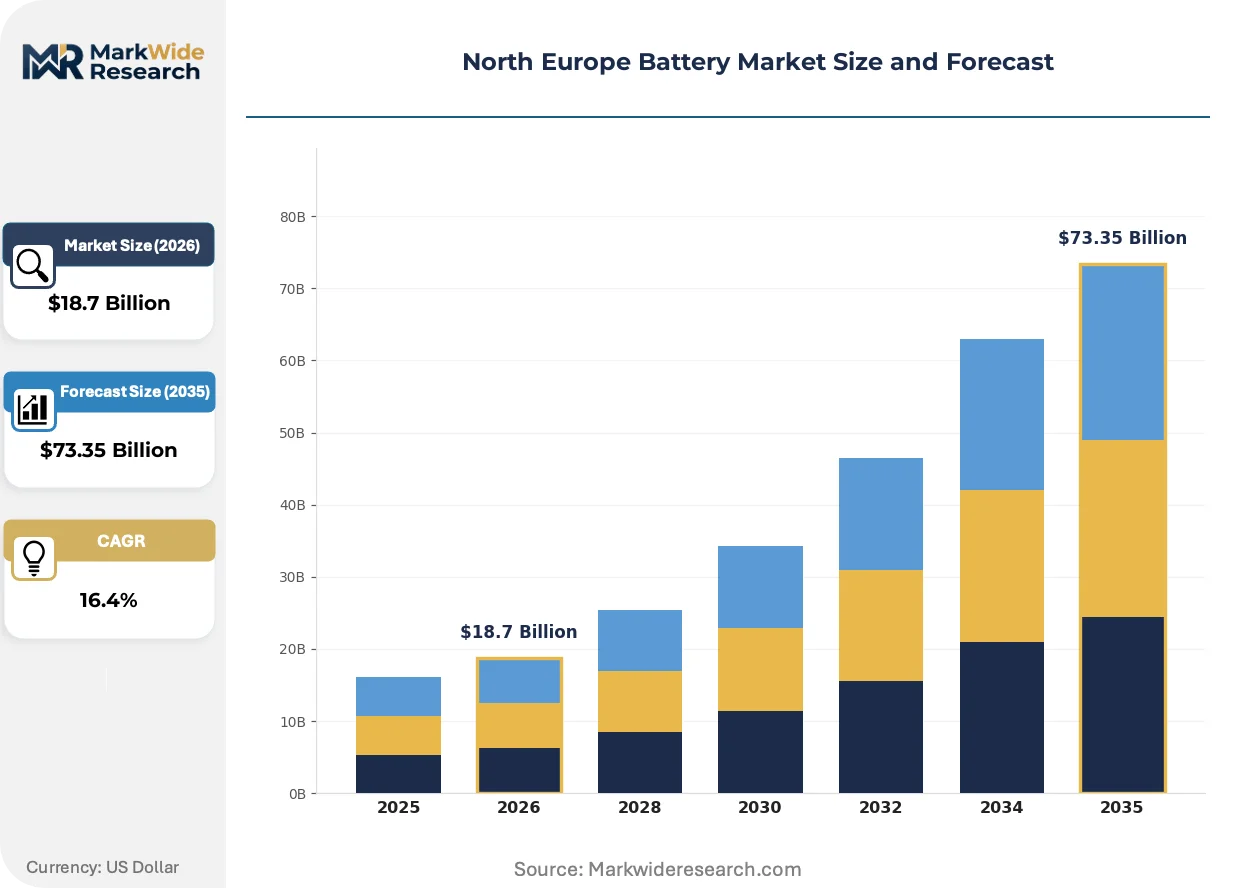
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-state End User: Automotive OEMs, Consumer Electronics, Renewable Energy, Industrial Applications Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity Application: Electric Vehicles, Energy Storage Systems, Portable Devices, Grid Stabilization |
| Companies Covered | Northvolt AB, FREYR Battery, Clayton Power, Broadbit Batteries Oy, Geyser Batteries Oy, Micropower Group AB, Saft, BMZ Group, Panasonic Energy Nordic, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Europe Battery Market Evolving Landscape
Cell architecture standardization and software-defined control layers are compressing hardware differentiation while elevating predictive analytics and fleet optimization platforms as primary value capture mechanisms in Nordic battery markets.
Solid-state battery manufacturing is modularizing around dry electrode processing and ceramic electrolyte deposition units that scale independently of cell form factor. Swedish and Norwegian pilot lines are adopting these modular process blocks to reconfigure production between cylindrical and prismatic formats within 8-12 week windows. This modularization is compressing capital deployment timelines for gigafactory expansions while enabling rapid product mix shifts in response to automotive platform contract awards.
EU Battery Regulation due diligence obligations are tightening supply chain documentation requirements for raw material extraction, refining, and active material production. Nordic producers must deploy blockchain-traceability systems and third-party audit partnerships to satisfy carbon footprint declaration mandates and recycled content verification. Energy Storage System applications face the most intensive compliance burdens, as Scandinavian grid operators embed regulatory adherence into procurement scoring criteria above pure cost metrics.
Logistics fleet operators are consolidating procurement decisions through battery-as-a-service contracts that unbundle cell hardware from predictive maintenance and residual value guarantees. Norwegian maritime and Swedish heavy trucking segments are leading this transition, contracting Nordic cell producers for 10-year operational leases with guaranteed cycle life performance. This financing-structure shift transfers degradation risk to manufacturers while locking in long-term offtake commitments for regional production capacity.
North Europe Battery Market Segmentation
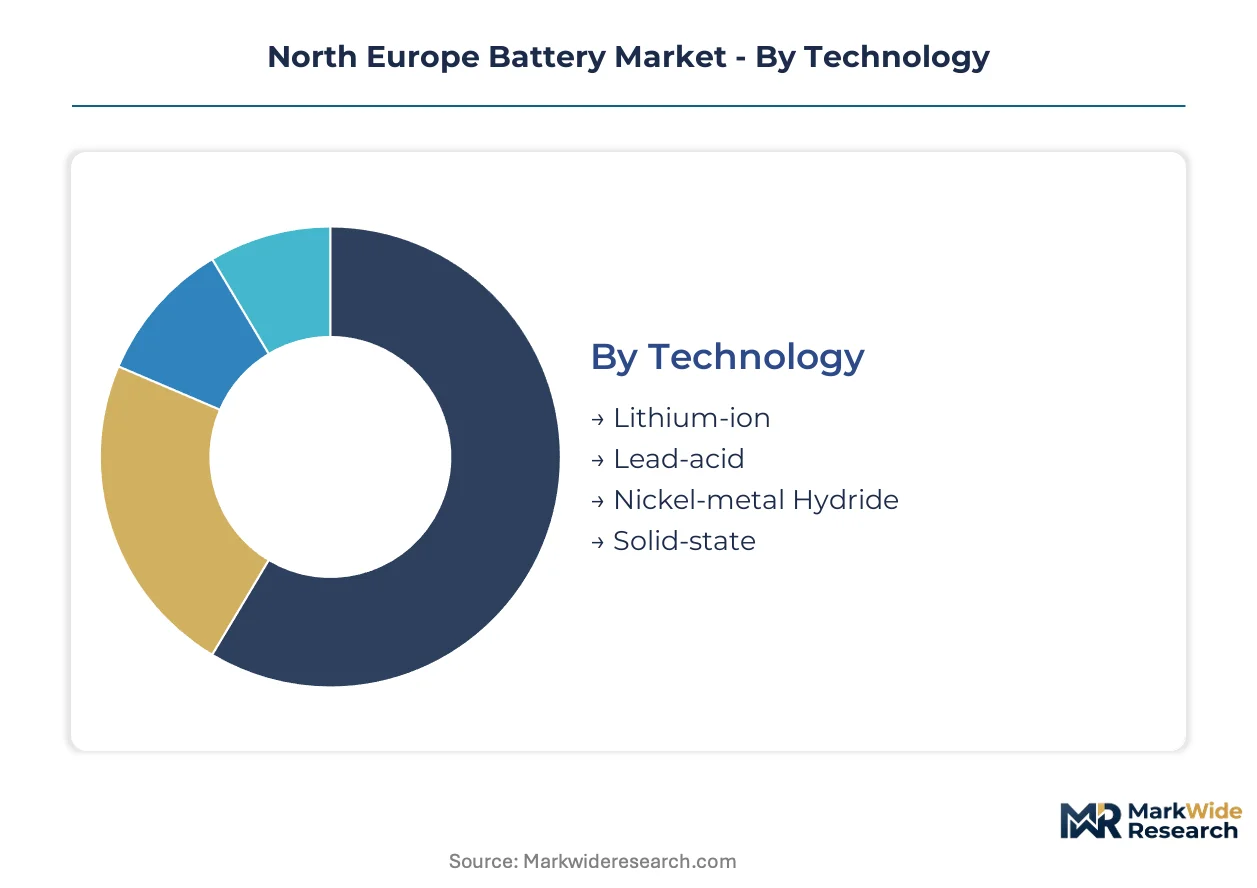
Technology and application boundaries in Nordic battery markets are dissolving as solid-state platforms mature and automotive OEMs consolidate multi-use procurement. Segmentation discipline reveals where capital deployment concentrates and which specifications command premium pricing.
Technology:
Cathode chemistry and electrolyte formulation determine manufacturing yield, energy density, and regulatory compliance cost across Swedish and Norwegian production corridors.
- Lithium-ion:NMC and LFP formulations dominate installed gigawatt-hour capacity, with nickel-rich cathodes preferred by Swedish automotive platforms for cold-climate performance. Norwegian cell producers leverage hydroelectric power integration to compress electrolytic processing costs below continental European benchmarks.
- Solid-state:Ceramic electrolyte architectures with lithium-metal anodes promise energy densities exceeding 400 Wh/kg once sintering yields stabilize above 85 percent. Pilot lines in Sweden and Norway are reconfiguring between cylindrical and prismatic formats using modular process blocks.
- Lead-acid:Flooded and AGM variants persist in backup power and starter applications where cost sensitivity outweighs cycle life requirements.
- Nickel-metal Hydride:Rare-earth hydride cathodes serve defense and industrial segments requiring 15-20 year operational lifespans in arctic conditions.
Mature deployment sits with Lithium-ion. Newer deployment is concentrated in Solid-state.
End User:
Procurement authority and volume concentration vary sharply across customer types, with fleet operators consolidating purchasing power faster than fragmented consumer channels.
- Automotive OEMs:Swedish and Norwegian manufacturers specify pack capacities above 80 kWh for premium SUV and sedan platforms, demanding cell-to-pack architectures that compress thermal management complexity. Long-dated offtake contracts lock Nordic producers into qualification cycles spanning 18-24 months.
- Renewable Energy:Scandinavian grid operators procure multi-hour duration assets for wind and solar balancing, embedding EU Battery Regulation compliance into procurement scoring above pure cost metrics.
- Consumer Electronics:Cylindrical and pouch formats for portable power applications face margin compression from Asian supply chain competition.
- Industrial Applications:Forklift, maritime, and stationary backup segments require nickel-based systems with extended cycle life under partial state-of-charge operation.
Volume concentrates with Automotive OEMs. Margin expansion is steepest with Renewable Energy.
Capacity:
Pack scaling economics favor high-volume production lines, though ultra-high configurations require bespoke thermal management and safety certification pathways.
- High Capacity:Packs from 80-150 kWh serve electric SUV and light commercial vehicle platforms across Swedish and Norwegian logistics fleets. Cell balancing and state-of-estimation algorithms differentiate Nordic producers in this tier.
- Ultra High Capacity:Systems exceeding 150 kWh target heavy trucking and maritime electrification, where Norwegian battery-as-a-service contracts transfer degradation risk to manufacturers over 10-year operational leases.
- Medium Capacity:20-80 kWh packs dominate passenger car segments with standardized module architectures.
- Low Capacity:Sub-20 kWh configurations serve hybrid platforms and portable power tools with limited Nordic production footprint.
Standardized output sits with Medium Capacity. Custom engineering concentrates in Ultra High Capacity.
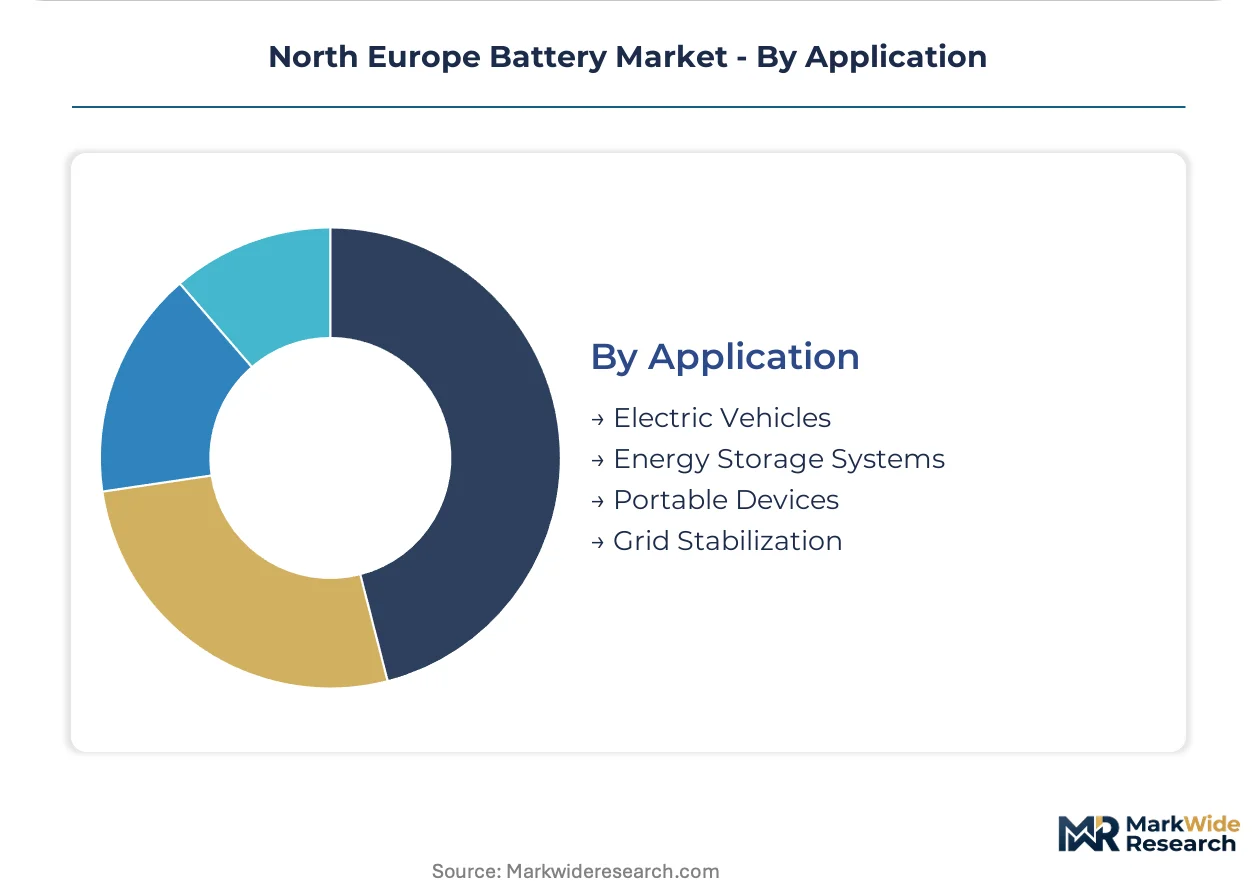
Application:
Use-case thermal profiles and duty cycles dictate cell selection, with grid-facing applications imposing the most stringent safety and longevity requirements.
- Energy Storage Systems:Multi-hour duration assets for Scandinavian wind and solar balancing require predictive degradation analytics and second-life residual value guarantees. Norwegian and Swedish grid operators mandate blockchain-traceable supply chains under EU Battery Regulation due diligence.
- Electric Vehicles:Automotive propulsion consumes the largest cell volume, with 800V architectures driving solid-state ceramic electrolyte development for fast-charge compatibility.
- Grid Stabilization:Frequency response and synthetic inertia services favor lithium-ion systems with sub-second response times.
- Portable Devices:Consumer electronics applications face commoditization pressure with limited Nordic manufacturing presence.
Revenue concentration rests with Electric Vehicles. Steepest expansion trajectory belongs to Energy Storage Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden and Norway dominate cell production capacity while Finland anchors upstream material processing. Denmark and Iceland concentrate on grid integration and maritime electrification applications.
Sweden
Automotive OEM demand and gigafactory investments drive procurement volumes. The Swedish Energy Agency enforces national carbon-neutrality mandates tightening material sourcing obligations. Västerås and Skellefteå industrial corridors host cell-to-pack manufacturing facilities with captive hydroelectric power integration.
Norway
Maritime fleet electrification and heavy trucking logistics accelerate battery-as-a-service contracting. The Ministry of Climate and Environment enforces lifecycle emissions thresholds through dual carbon goals enforcement. Stavanger and Oslo harbor zones concentrate maritime system integration and offshore wind storage procurement.
Finland
Lithium spodumene mining and cobalt refining capacity enable traceable European active material supply chains. ECHA REACH restrictions on nickel compounds shape cathode chemistry selection and water treatment investments. Kokkola and Harjavalta industrial sites host fully integrated precursor production meeting EU Battery Regulation recycled content minimums.
Denmark
Offshore wind balancing and district heating electrification create multi-hour duration storage demand. National energy island programs mandate domestic content requirements for North Sea infrastructure. Esbjerg port facilities aggregate second-life vehicle packs into grid stabilization assets.
Iceland
Aluminum smelter load balancing and data center renewable power contracts drive stationary storage procurement. The National Energy Authority regulates grid interconnection standards for frequency response services. Reykjanes peninsula geothermal and hydroelectric clusters enable near-zero marginal cost electrolytic processing.
North Europe Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Nordic cell manufacturing. The market structures around vertically integrated gigafactory operators, specialized industrial battery fabricators, and captive automotive supply divisions. Three archetypes dominate: full-stack cell-to-pack manufacturers controlling upstream material access; niche specialists serving defense and maritime segments with long-cycle reliability requirements; and Asian-owned regional distribution subsidiaries. Competitive moves concentrate on securing European-sourced active material partnerships and modular production line reconfigurations between cylindrical and prismatic formats.
Among Swedish-anchored integrated producers, Northvolt AB exemplifies the full-stack archetype with captive mining partnerships and in-house recycling capabilities. Norwegian-based FREYR Battery occupies the low-carbon production position leveraging hydroelectric grid integration. Finnish specialists Geyser Batteries Oy and Broadbit Batteries Oy represent the industrial niche tier serving custom electrochemical requirements outside automotive volume segments.
| Leading Market Players |
|---|
| Northvolt AB |
| FREYR Battery |
| Clayton Power |
| Broadbit Batteries Oy |
| Geyser Batteries Oy |
| Micropower Group AB |
| Saft |
| BMZ Group |
| Panasonic Energy Nordic |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers anchored in Norwegian hydroelectric zones and Swedish state-supported industrial corridors command asymmetric pricing power through captive energy access, while private-equity-rolled-up specialists face margin compression from lithium carbonate volatility and ECHA REACH compliance burdens that reshape procurement economics across Nordic cell manufacturing.
Pricing Analysis
Margin tightening in standard lithium-ion tiers reflects concentrated South American brine and Australian spodumene supply exposing Nordic producers to input cost swings exceeding threefold across eighteen-month cycles. Three-tier pricing structure across premium solid-state, standard NMC-LFP, and economy lead-acid levels stratifies by certification grade and cycle-life guarantees. Pricing pressure stems from EU Battery Regulation carbon footprint declarations compressing cost positions for import-dependent assemblers. Renewable Energy grid operators show least price sensitivity due to regulatory compliance scoring embedded above pure cost metrics, while Consumer Electronics segments face commoditization from Asian supply chain competition.
Supply Chain Analysis
Single-source vulnerability sits with Chilean and Argentine lithium brine operations, Australian spodumene concentrators, and Indonesian nickel processing corridors feeding Nordic cathode-active-material plants. Active material supply draws from Chinese precursor refining dominance, South Korean electrolyte formulation, and Japanese separator membrane production. Supply chain risk centers on tariff exposure from EU-Asia trade frictions and ECHA REACH nickel compound restrictions imposing water treatment capital burdens exceeding fifteen million euros per production line. Distribution runs through captive automotive OEM offtake contracts, Scandinavian grid operator direct procurement, and maritime battery-as-a-service leasing platforms consolidating logistics fleet demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North Europe Battery Market operates as a cost-of-compliance arena where EU Battery Regulation due diligence obligations and recycled content minimums erect barrier-to-entry moats favoring vertically integrated producers with European-sourced active material partnerships over import-dependent assemblers.
For Market Incumbents: Deepen backward integration into Finnish-Swedish mining corridor assets controlling Keliber lithium spodumene and Rönnskär cobalt refinery capacity to satisfy traceability mandates. Expand modular production line reconfigurations between cylindrical and prismatic formats within eight-to-twelve week windows to capture automotive platform contract volatility. Solid-state ceramic electrolyte yield gaps above twenty percent at pilot scale threaten margin visibility for next-generation investments. For New Entrants and Emerging Players: EU Battery Regulation in Scandinavia opens a window for blockchain-traceability system providers and third-party audit partnerships serving compliance-burdened Energy Storage System procurements. Target second-life stationary storage aggregation from retired Norwegian and Swedish logistics fleet packs into two-to-four hour grid balancing assets. Enter through predictive degradation analytics software subscriptions unbundled from cell hardware in battery-as-a-service contracts. For Investors and Strategic Acquirers: Distressed-cycle entries favor industrial niche specialists with defense and maritime nickel-metal hydride capabilities in Finnish and Norwegian geographies. Long-term viability hinges on five-to-ten year operational lease structures transferring degradation risk to manufacturers while locking in offtake. Watch solid-state sintering yield stabilization above eighty-five percent as inflection indicator for premium automotive platform contract awards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mining Assets | Captive lithium spodumene and cobalt refinery access satisfies EU Battery Regulation traceability mandates for Nordic OEMs. |
| Modular Production Line Reconfiguration | Pilot lines adopting dry electrode and ceramic electrolyte process blocks shift between formats within compressed capital deployment timelines. |
| Battery-as-a-Service Platform Launch | Norwegian maritime and Swedish heavy trucking segments contract ten-year operational leases transferring degradation risk to manufacturers. |
| Second-Life Storage Aggregation | Retired electric vehicle packs from Nordic logistics fleets create aftermarket revenue streams for predictive analytics providers. |
| Solid-State Yield Rate Improvement | Sintering stabilization above eighty-five percent unlocks energy densities exceeding four hundred Wh per kilogram for eight hundred volt architectures. |
Research Methodology
European Commission trade databases, ECHA REACH regulatory filings, and Scandinavian transmission system operator procurement records formed the secondary backbone, cross-referenced with primary interviews spanning cell manufacturing executives, cathode chemistry R&D directors, Nordic grid operator planning officers, and maritime fleet procurement leads. Bottom-up cell production capacity modeling triangulated against top-down electric vehicle registration data and energy storage system deployment pipelines across Swedish, Norwegian, Finnish, Danish, and Icelandic regulatory jurisdictions.
Historical trendline analysis of gigafactory investment cycles, lithium carbonate price volatility bands, and solid-state manufacturing yield progression informed the analytical framework across the analysis window. Segmentation dimensions modeled encompass technology pathway, end-user procurement authority, pack capacity tier, and application thermal profile. CAGRs derived from production capacity buildout schedules, automotive platform electrification roadmaps, and grid operator multi-hour duration storage procurement pipelines incorporating EU Green Deal industrial policy incentive trajectories.
The model assumes a particular technology adoption path; alternative pathways for solid-state ceramic electrolyte commercialization would alter the outlook if sintering yields fail to stabilize or liquid-electrolyte lithium-ion cost curves outpace projections. Forecasts reflect assumptions on Nordic hydroelectric grid integration sustaining near-zero marginal power costs, ECHA REACH enforcement tightening without regulatory rollback, and EU Battery Regulation due diligence obligations remaining binding across the projection horizon. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
Asia-Pacific Battery Market
Batteries
India SLI Battery Market
Batteries
United States SLI Battery Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
Deep Cycle Battery Market
Batteries
South America Micro Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Battery Separators Market
Batteries
India Battery Cell Market
Batteries
Atomic Battery Market
Batteries
DMC for Battery Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Floor Scrubber Battery Market