
 Asia-Pacific Rechargeable Battery Market | 2026-2036
Asia-Pacific Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Rechargeable Battery Market Insights
Lithium iron phosphate chemistry is repositioning cost structures across the Asia-Pacific rechargeable battery supply chain. Contemporary Amperex Technology Co. Limited leverages vertical integration into cathode precursor production to compress unit economics. BYD Company Ltd. sustains manufacturing scale through in-house vehicle-to-cell demand alignment. Samsung SDI anchors premium positioning via solid-state R&D pipelines in its South Korean facilities.
A rechargeable battery stores electrochemical energy through reversible redox reactions, typically operating at voltages from 1.2 V to 4.2 V depending on chemistry, and enables repeated charge-discharge cycles exceeding 500 to 3,000 iterations for industrial and mobility applications. The lithium-ion product type dominates value capture owing to energy density thresholds required by electric vehicle platforms, while lead-acid retains residual share in industrial backup systems where capital constraints override performance metrics. Among end users, automotive applications absorb the majority of cell output as OEMs in Japan and South Korea enforce stricter pack-level efficiency standards.
China's MIIT enforces GB standards for battery safety and recycling traceability, compelling manufacturers to redesign pack architectures for disassembly compliance. South Korea's MFDS coordinates with METI-aligned Japanese regulators on harmonized cell testing protocols, reducing cross-border certification friction. India's BIS certification mandates for lithium-ion cells are tightening import gateways and accelerating local assembly investments. Stakeholders must track how solid-state technology transitions alter cathode material procurement strategies and factory retooling timelines.
Market Dynamics
Cell-to-pack architecture adoption is compressing manufacturing steps and redirecting capital toward integrated production lines across China's Jiangsu and Guangdong provinces. This structural shift eliminates module assembly entirely, reducing BOM complexity while demanding precision welding and thermal management capabilities.
Growth Catalysts
- India's PLI scheme for advanced chemistry cells:The production-linked incentive framework redirects foreign direct investment toward domestic gigafactory construction, accelerating local assembly capacity for lithium-ion systems.
- Electric vehicle fleet procurement:Commercial operators across China and South Korea are scaling binding offtake agreements for lithium-ion packs, creating guaranteed demand pipelines for cell manufacturers.
- Solid-state R&D pipelines:South Korean facilities are anchoring next-generation cathode-electrolyte interfaces, positioning the region for post-lithium-ion chemistry transitions.
Market Restraints
- Cathode precursor supply concentration:Upstream nickel and cobalt refining capacity clusters in Indonesian processing parks, creating single-point vulnerability for regional cell producers.
- GB standards compliance costs:China's MIIT mandates for battery safety and recycling traceability force pack architecture redesigns that extend engineering timelines.
- Lead-acid residual lock-in:Industrial backup applications in cost-constrained segments continue absorbing capital that might otherwise migrate to advanced chemistry systems.
Strategic Opportunities
- Vietnam and Thailand assembly zones:Underpenetrated Southeast Asian manufacturing corridors offer tariff-advantaged export platforms for cells destined for European and North American markets.
- Vehicle-to-grid integration:Bidirectional charging infrastructure creates new revenue streams for automotive OEMs while extending battery asset utilization cycles.
- BIS certification tightening:India's import gateway restrictions accelerate local assembly investments by foreign cell producers seeking market access.
Industry Challenges
- Electrolyte formulation expertise scarcity:Solid-state transition roadmaps require polymer and ceramic electrolyte specialists that existing workforce pipelines fail to supply.
- Gigafactory commissioning timelines:Dry electrode coating and precision stacking equipment procurement stretches from 18 to 36 months, delaying capacity activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Rechargeable Battery Market |
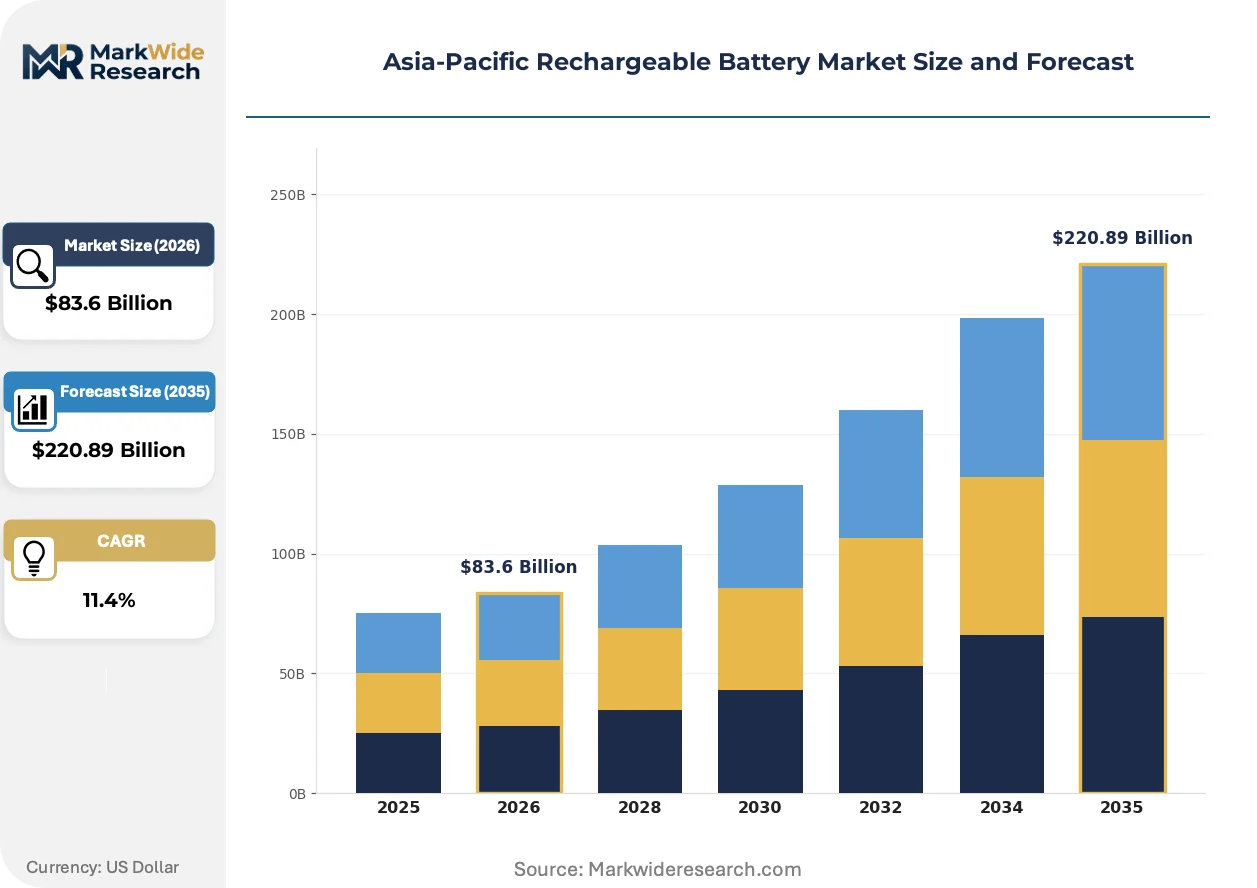
| Market Size in 2026 | $83.6 Billion |
| Market Size in 2035 | $220.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Cadmium, Nickel-Metal Hydride, Lead-acid End User: Consumer Electronics, Automotive, Industrial Equipment, Energy Storage Technology: Solid-State, Flow Battery, Lithium-Sulfur, Rechargeable Fuel Cell Application: Electric Vehicles, Portable Devices, Grid Storage, Power Tools |
| Companies Covered | Contemporary Amperex Technology Co. Limited, BYD Company Ltd., LG Energy Solution, Panasonic Corporation, Samsung SDI, GS Yuasa Corporation, SK Innovation, EVE Energy Co., Ltd., Gotion High-tech, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Rechargeable Battery Market Trends and Innovations
Lithium iron phosphate chemistry is actively repositioning cost structures across cell manufacturing while solid-state prototypes advance toward pilot production. These parallel developments are compressing incumbent technology windows and forcing cathode material procurement recalibration.
Lithium iron phosphate cathodes deliver thermal stability and cycle longevity without nickel or cobalt dependencies. Energy storage system integrators and entry-segment electric vehicle platforms are adopting the chemistry at accelerating rates. The technology is expanding into cost-sensitive mobility applications previously reserved for nickel-manganese-cobalt formulations.
China's MIIT enforces GB standards for battery safety and recycling traceability that compel disassembly-compliant pack architectures. Manufacturers must redesign housing geometries and bonding methods to enable automated component recovery. Automotive OEMs in Japan and South Korea are responding by pre-qualifying domestic recycling partners before pack launches.
Binding offtake agreements are replacing spot market purchasing for lithium-ion cells in commercial vehicle fleets. Fleet operators are consolidating procurement through direct manufacturer relationships, bypassing traditional distributor networks. This pattern concentrates most visibly across China's Jiangsu province where cell-to-pack integration lines cluster near OEM assembly plants.
Asia-Pacific Rechargeable Battery Market Segmentation
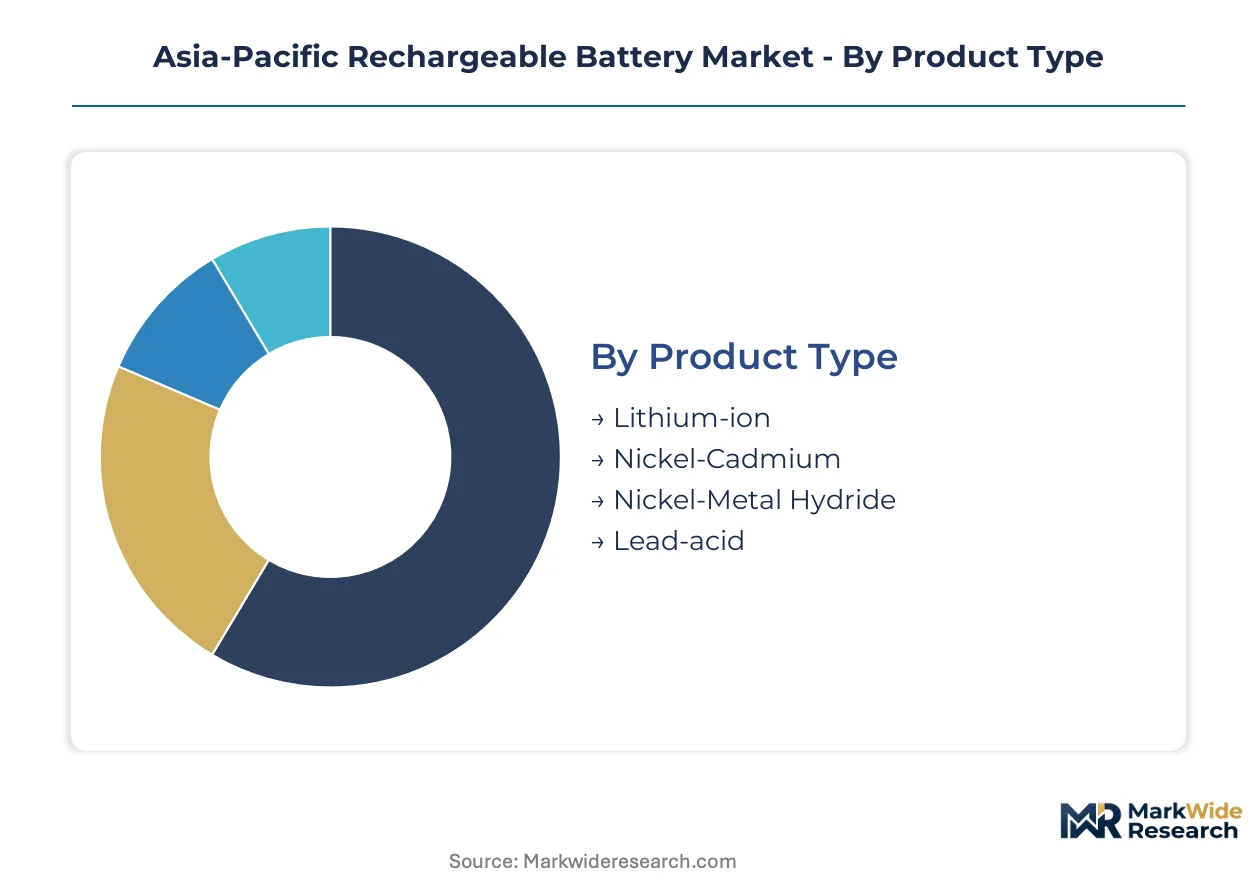
Segmentation reveals how certification burdens, chemistry trade-offs, and application requirements fragment procurement patterns across the Asia-Pacific rechargeable battery supply chain. Manufacturers must align product architectures with divergent thermal, cycle-life, and safety standards enforced by MIIT, MFDS, and BIS.
Product Type:
MIIT GB standards impose tiered testing protocols on lithium-ion and lead-acid systems, while nickel-cadmium faces additional environmental discharge restrictions under China's MEE directives.
- Lithium-ion:Electrochemical systems operating at 3.2 V to 4.2 V utilizing intercalation compounds in graphite anodes and metal oxide cathodes. Demand concentrates in Jiangsu and Guangdong provinces where cell-to-pack integration lines serve domestic electric vehicle OEMs, though cathode precursor supply concentration in Indonesian processing parks creates single-point vulnerability.
- Lead-acid:Mature flooded and valve-regulated designs delivering 2.0 V per cell with established recycling infrastructure. Industrial backup applications in cost-constrained Indian and Southeast Asian segments absorb residual capital that might otherwise migrate to advanced chemistry systems.
- Nickel-Cadmium:Alkaline storage chemistry with tolerance for deep discharge cycles and temperature extremes, now restricted in consumer applications but retained in aviation and rail signaling systems where reliability overrides environmental concerns.
- Nickel-Metal Hydride:Rare earth alloy hydride anodes paired with nickel oxyhydroxide cathodes, sustaining niche demand in hybrid electric vehicle battery packs from Japanese and South Korean OEMs.
Lithium-ion sits at the top of the volume ranking, with nickel-metal hydride climbing the fastest in hybrid vehicle applications.
End User:
Customer procurement scale determines whether manufacturers deploy direct sales teams or distributor networks, with automotive and energy storage commanding dedicated account management.
- Automotive:OEM pack procurement governed by METI-aligned efficiency standards from Japan and MFDS testing protocols from South Korea, requiring cell suppliers to maintain dual certification capabilities. Binding offtake agreements from fleet operators in China and South Korea are replacing spot market purchasing.
- Energy Storage:Grid-scale and behind-the-meter installations utilizing lithium iron phosphate chemistry for thermal stability in stationary applications. India's CEA mandates and Australia's grid connection standards impose additional inverter integration testing burdens on battery system integrators.
- Consumer Electronics:Smartphone, laptop, and wearable device manufacturers specifying prismatic and pouch cell formats with slim profile requirements and rapid charge capabilities.
- Industrial Equipment:Forklift, material handling, and backup power systems where capital constraints favor lead-acid in emerging markets and lithium-ion in premium efficiency-seeking operations.
Automotive commands the largest revenue share, while energy storage is expanding most quickly as renewable integration mandates proliferate.
Technology:
Development-stage technologies face extended certification timelines compared to incumbent chemistries, stretching commercialization pathways.
- Solid-State:Ceramic or polymer electrolyte architectures eliminating liquid components and thermal runaway risks. Samsung SDI and South Korean facilities are anchoring pilot production lines, though electrolyte formulation expertise scarcity constrains workforce pipelines.
- Lithium-Sulfur:High theoretical energy density utilizing elemental sulfur cathodes and lithium metal anodes, currently limited by polysulfide shuttle degradation and cycle instability in commercial prototypes.
- Flow Battery:Vanadium and zinc-bromine redox systems with decoupled power and energy scaling for multi-hour grid storage applications, constrained by electrolyte cost and footprint requirements.
- Rechargeable Fuel Cell:Hydrogen-based regenerative systems with niche deployment in remote power and aerospace applications where refueling infrastructure exists.
Solid-state sits at the top of the investment ranking, with lithium-sulfur gaining share fastest in defense and aviation weight-critical applications.
Application:
Application-specific duty cycles and operating environments dictate cell format selection and thermal management system complexity.
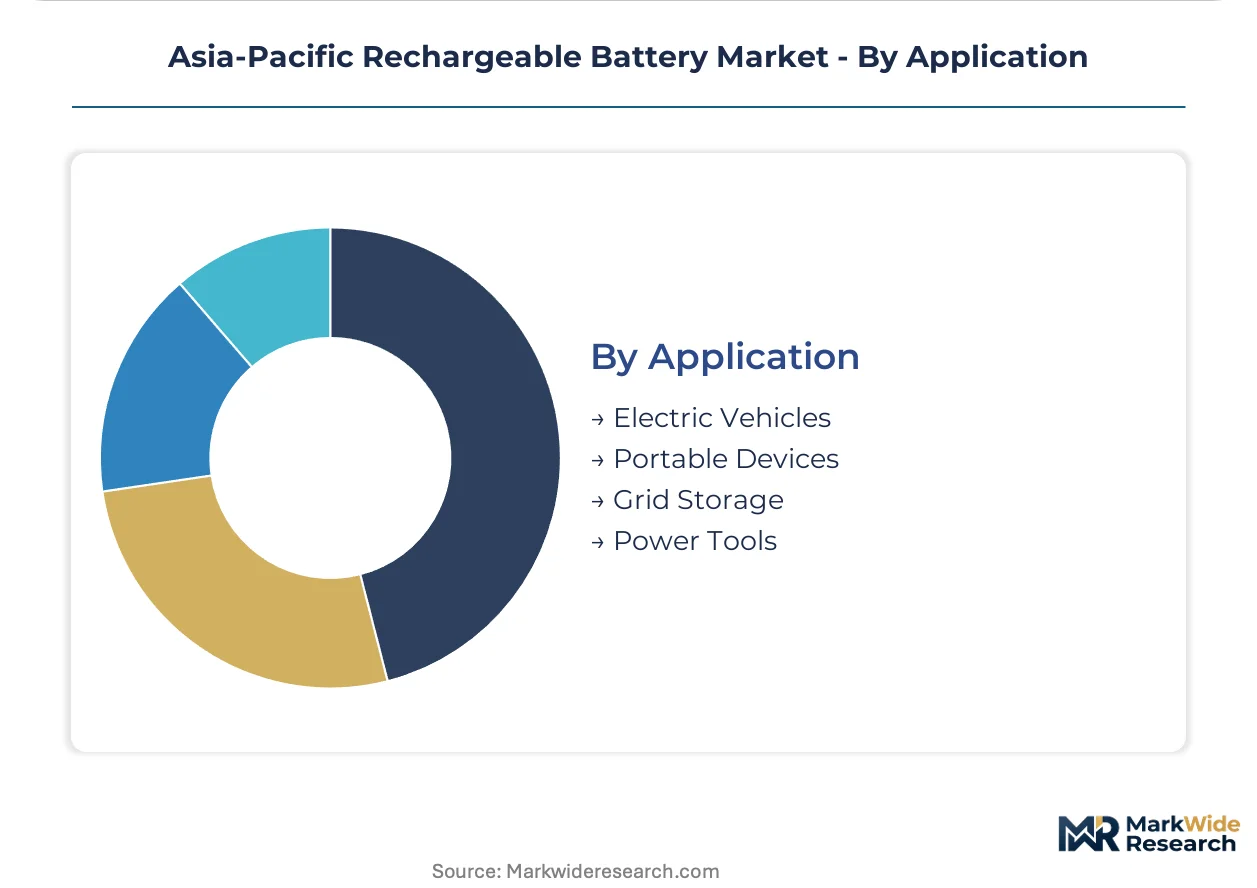
- Electric Vehicles:Passenger cars, commercial vans, and buses requiring 50 kWh to 300 kWh pack capacities with fast-charge capability and 8-year warranty cycles. China's Jiangsu province clustering places cell-to-pack lines adjacent to OEM assembly plants.
- Grid Storage:Utility-scale and commercial installations requiring 4-hour to 8-hour discharge duration with daily cycling tolerance, favoring lithium iron phosphate cost structures over nickel-manganese-cobalt alternatives.
- Portable Devices:Cylindrical and prismatic cells in 18650, 21700, and custom formats for power tools, medical devices, and consumer electronics with space-constrained integration requirements.
- Power Tools:High-discharge-rate cylindrical cells delivering burst current for cordless construction and gardening equipment, with Milwaukee and Makita specifying proprietary pack interfaces.
Electric vehicles holds the dominant volume position, with grid storage showing the steepest expansion trajectory as renewable penetration targets tighten across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Guangdong provinces anchor cell-to-pack integration capacity across the Asia-Pacific rechargeable battery supply chain. Manufacturing gravity clusters near OEM assembly plants in eastern China while regulatory divergence across national jurisdictions fragments certification requirements. Industrial policy and fleet procurement mandates are redrawing investment maps from Seoul to Maharashtra.
China
Electric vehicle fleet operators in Jiangsu province are executing binding offtake agreements for lithium-ion packs at scale. MIIT enforces GB standards for battery safety and recycling traceability that compel pack architecture redesigns for automated disassembly compliance. Contemporary Amperex Technology Co. Limited compresses unit economics through backward integration into cathode precursor production at its Ningde facilities.
South Korea
Samsung SDI and LG Energy Solution are anchoring solid-state R&D pipelines in domestic facilities ahead of post-lithium-ion chemistry transitions. MFDS coordinates with METI-aligned Japanese regulators on harmonized cell testing protocols that reduce cross-border certification friction. Busan-Ulsan industrial corridors concentrate electrolyte formulation expertise development for ceramic and polymer architectures.
India
The PLI scheme for advanced chemistry cells is redirecting foreign direct investment toward domestic gigafactory construction in Gujarat and Tamil Nadu. BIS certification mandates for lithium-ion cells are tightening import gateways and accelerating local assembly investments by foreign producers. Maharashtra's industrial zones are emerging as preferred locations for cell-to-module integration lines serving domestic automotive OEMs.
Japan
Panasonic Corporation and GS Yuasa Corporation sustain manufacturing scale through in-house vehicle-to-cell demand alignment with domestic hybrid and electric platforms. METI-aligned efficiency standards enforce stricter pack-level performance thresholds than regional competitors. Kanto and Kansai industrial belts maintain concentrated R&D spending on nickel-metal hydride systems for hybrid electric vehicle applications.
Vietnam and Thailand
Underpenetrated Southeast Asian manufacturing corridors are attracting tariff-advantaged export platform investments for cells destined for European and North American markets. Thailand's Board of Investment incentives and Vietnam's industrial zone concessions are competing for Chinese and South Korean capital. Ho Chi Minh City and Bangkok metropolitan industrial parks are positioning as alternative assembly locations to bypass escalating trade friction.
Asia-Pacific Rechargeable Battery Market Competitive Landscape
Global majors compete with regional champions across technology licensing and capacity deployment timelines. The vendor base stratifies into three tiers: integrated conglomerates with captive automotive demand, independent cell specialists serving multiple OEMs, and emerging challengers leveraging policy-supported domestic capacity. Dominant competitive moves include backward integration into cathode material production and geographic diversification of final assembly to mitigate tariff exposure.
Within the integrated conglomerate tier, BYD Company Ltd. and Samsung SDI exemplify divergent strategic postures. BYD occupies a position defined by in-house vehicle-to-cell demand alignment through its automotive division. Samsung SDI anchors premium-tier positioning via South Korean-based solid-state R&D pipelines. LG Energy Solution represents the independent specialist archetype, serving multiple automotive OEMs without captive vehicle production.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| BYD Company Ltd. |
| LG Energy Solution |
| Panasonic Corporation |
| Samsung SDI |
| GS Yuasa Corporation |
| SK Innovation |
| EVE Energy Co., Ltd. |
| Gotion High-tech |
| Others |
Pricing and Supply Chain Analysis
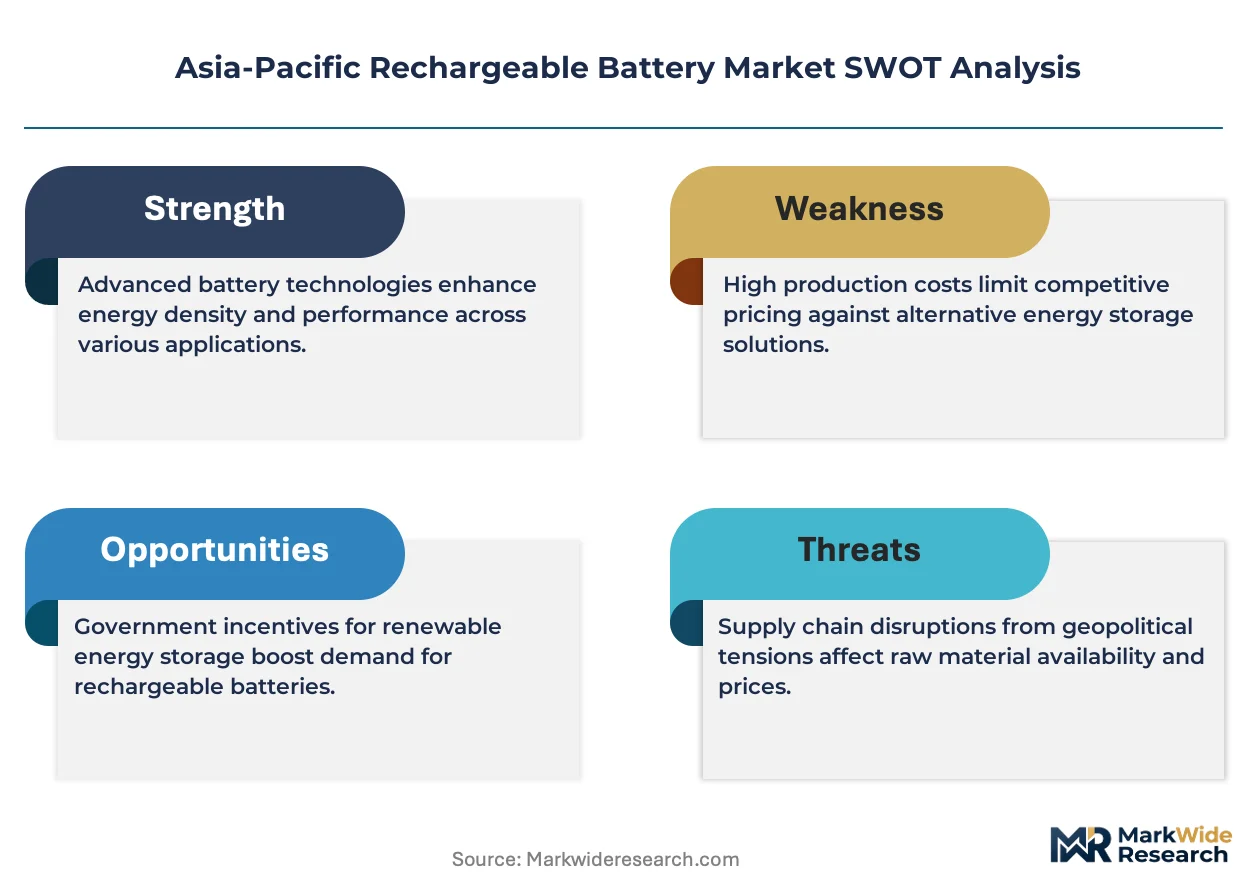
Cell chemistry certification tiers in the Asia-Pacific rechargeable battery market split procurement into premium nickel-manganese-cobalt systems and cost-optimized lithium iron phosphate alternatives, with each tier demanding distinct upstream sourcing strategies and manufacturing footprints. GB standards compliance from China's MIIT adds a third certification ladder that reshapes both cost structures and supplier qualification timelines across the region.
Pricing Analysis
Input-cost pass-through from cathode precursor markets dominates pricing formation, with nickel and cobalt price volatility flowing directly into cell quotations on quarterly contract resets. Three-tier pricing structure across premium solid-state development programs, standard lithium-ion automotive contracts, and economy lead-acid industrial backup systems reflects divergent performance specifications and warranty obligations. Pricing pressure stems from binding offtake agreements that lock in volume commitments at fixed terms, compressing spot market premiums. Fleet operators in China's Jiangsu province exhibit highest price sensitivity through consolidated procurement, while energy storage integrators accept premium positioning for thermal stability guarantees.
Supply Chain Analysis
Cathode precursor supply rests on Indonesian nickel processing parks and Chinese cobalt refining capacity, creating geographic concentration that feeds regional cell manufacturing. Lithium carbonate from Australian and Chilean extraction operations, separator films from Japanese and South Korean polymer specialists, and electrolyte salts from Chinese fluorochemical producers constitute critical input dependencies. Single-source vulnerability in Indonesian nickel sulfate refining exposes producers to export restriction risks and processing capacity bottlenecks. Distribution runs through direct OEM supply agreements for automotive volumes and distributor networks serving industrial replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific rechargeable battery market has entered a late-cycle quality phase where automotive OEMs are enforcing stricter pack-level efficiency standards and recycling traceability mandates, elevating specification premiums over pure cost competition.
For Market Incumbents: Anticipate solid-state chemistry transitions by pre-qualifying ceramic electrolyte suppliers and securing polymer formulation expertise ahead of workforce scarcity. Defend position against emerging Chinese cell-to-pack specialists through backward integration into cathode precursor production and accelerated BIS certification for Indian market access. Capacity addition in Gujarat and Tamil Nadu industrial corridors represents the priority defensive lever. For New Entrants and Emerging Players: Solid-state pilot production partnerships with South Korean research institutes offer technology-first wedge positioning without billion-dollar cathode material commitments. Target Vietnam and Thailand assembly zones as tariff-advantaged export platforms serving European and North American demand, where underpenetrated manufacturing corridors compete for Chinese and South Korean capital. Direct fleet operator relationships bypassing traditional distributor networks provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where electrolyte formulation expertise scarcity constrains solid-state transition roadmaps and workforce pipelines fail to supply ceramic and polymer specialists. Long-term viability favors vertically integrated conglomerates with captive automotive demand alignment over independent cell specialists exposed to OEM pricing leverage. Acquisition target archetype: mid-cap specialists with established BIS certification and Indian PLI scheme qualification. Watch solid-state pilot production timelines as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Pack Architecture Deployment | Eliminates module assembly steps and redirects capital toward precision welding capabilities in Jiangsu and Guangdong. |
| Cathode Precursor Backward Integration | Compresses unit economics through captive nickel sulfate and lithium carbonate supply from Indonesian and Australian sources. |
| Solid-State R&D Pipeline Investment | Positions Samsung SDI and South Korean facilities for post-lithium-ion chemistry transitions ahead of regional competitors. |
| PLI-Qualified Gigafactory Construction | Accelerates local assembly investments by foreign producers seeking Indian market access under tightened BIS certification. |
| Vehicle-to-Grid Integration Development | Creates bidirectional charging revenue streams for automotive OEMs while extending battery asset utilization cycles. |
Research Methodology
Direct dialogue with cell manufacturing executives, automotive OEM procurement leads, energy storage system integrators, and regulatory affairs specialists at MIIT and BIS anchored qualitative grounding. Secondary validation drew from customs trade data, SEC filings of listed battery producers, MIIT GB standard documentation, and PLI scheme administrative records. Bottom-up capacity deployment tracking across Jiangsu, Guangdong, Gujarat, and Tamil Nadu facilities triangulated against top-down demand modeling from electric vehicle production forecasts.
Bottom-up modeling of cell production capacity by chemistry type and format integrated with top-down absorption analysis from automotive and energy storage procurement pipelines across the analysis window. Segmentation dimensions included product type, end user industry, technology maturity stage, and application duty cycle. CAGRs were derived from installed capacity expansion timelines and binding offtake agreement volumes. Forecast inputs incorporated dry electrode coating equipment lead times and solid-state pilot production progression rates.
The model holds under stable cathode precursor supply flows and sustained PLI scheme incentive structures; deviation in Indonesian export restrictions or Indian certification timeline acceleration would shift capacity activation schedules. Forecasts reflect documented assumptions regarding cell-to-pack adoption rates and solid-state commercialization pathways. Technology transition delays, electrolyte formulation workforce constraints, and trade friction escalation represent specific risk factors warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Forklift Battery Charger Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Iron Flow Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
United Kingdom Electric Vehicle Battery Electrolyte Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Primary Lithium Battery for Industrial Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Smart Battery Charger Market
Batteries
Hybrid Flow Battery Market
Batteries
Middle East Rechargeable Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Global Coke Oven Batteries Market
Batteries
Printed Batteries Market
Batteries
Nas Battery Market
Batteries
East Africa Battery Market