
 Modular Battery Market | 2026-2036
Modular Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Battery Market Foresight
Electrochemical engineering talent is rotating from consumer electronics toward automotive and grid-scale battery programs, tightening labor availability for smaller pack integrators. Samsung SDI leverages its Korea-based R&D campus to sustain leadership in high-nickel cathode architectures. BYD Auto anchors vertical control through in-house production of blade-cell modules. Cleantron specializes in compact modular formats for European light electric vehicles, occupying a defensible niche against Asian volume producers.
A modular battery comprises standardized electrochemical cells or sub-pack units engineered for series-parallel configuration, typically employing lithium-ion chemistries with nickel-manganese-cobalt or lithium-iron-phosphate cathodes and operating voltages from 48V to 1500V depending on application scale. These systems enable scalable capacity expansion, simplified maintenance through swappable units, and reduced downtime for commercial energy storage and electric vehicle platforms. Lithium-ion modules dominate current value generation due to mature supply chains and energy density advantages, while solid-state architectures represent the fastest-growing technology segment as ceramic electrolyte manufacturing yields improve. Automotive end users command the largest absolute volume, though renewable energy deployments are expanding at the highest rate as grid operators seek buffer capacity for intermittent wind and solar assets.
The EU Battery Regulation and REACH compliance frameworks mandate supply chain due diligence, recycled material quotas, and carbon footprint labeling that reshape product design cycles for European market access. China's GB standards and MIIT industry guidelines enforce safety testing protocols and cell-to-pack integration requirements that influence export-oriented manufacturers. Japan's METI circular economy directives and JIS certification standards add another compliance layer for suppliers targeting East Asian industrial buyers. Stakeholders must monitor evolving chemistry-specific regulations and pre-position recycling partnerships before compliance deadlines tighten material sourcing constraints.
Market Dynamics
Containerized lithium-ion procurement by German grid operators is compressing design cycles and forcing pack integrators to pre-certify systems against EU Battery Regulation carbon-footprint thresholds before contract bidding.
Growth Catalysts
- EU Battery Regulation mandates:Recycled content quotas and carbon footprint declarations are accelerating qualification timelines for European market access.
- Stationary energy storage:German utilities are procuring containerized systems at scale to buffer intermittent wind and solar assets on transmission networks.
- Jiangsu province clustering:Manufacturing concentration around Envision AESC and CATL suppliers is reducing logistics costs for grid-tied deployments.
Market Restraints
- Nickel price volatility:High-nickel cathode architectures face input cost instability that compresses margin buffers for pack integrators.
- Electrochemical engineering scarcity:Talent rotation toward automotive programs is tightening labor availability for smaller stationary storage integrators.
- REACH compliance friction:Supply chain due diligence requirements add documentation burden and extend product design cycles for European-bound systems.
Strategic Opportunities
- Solid-state convergence:Ceramic electrolyte manufacturing yield improvements are opening white space in premium grid-buffer applications requiring higher energy density.
- Service unbundling:Modular swappable-unit architectures enable aftermarket maintenance revenue streams separate from initial hardware sales.
- MIIT export pathways:China's GB standards alignment with international safety protocols is streamlining certification for manufacturers targeting multiple jurisdictions.
Industry Challenges
- Cell-to-pack integration complexity:GB standards and MIIT guidelines enforce safety testing protocols that demand specialized thermal management engineering capacity.
- Recycling partnership pre-positioning:EU Battery Regulation compliance deadlines are forcing integrators to secure material recovery agreements before sourcing constraints tighten.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Battery Market |
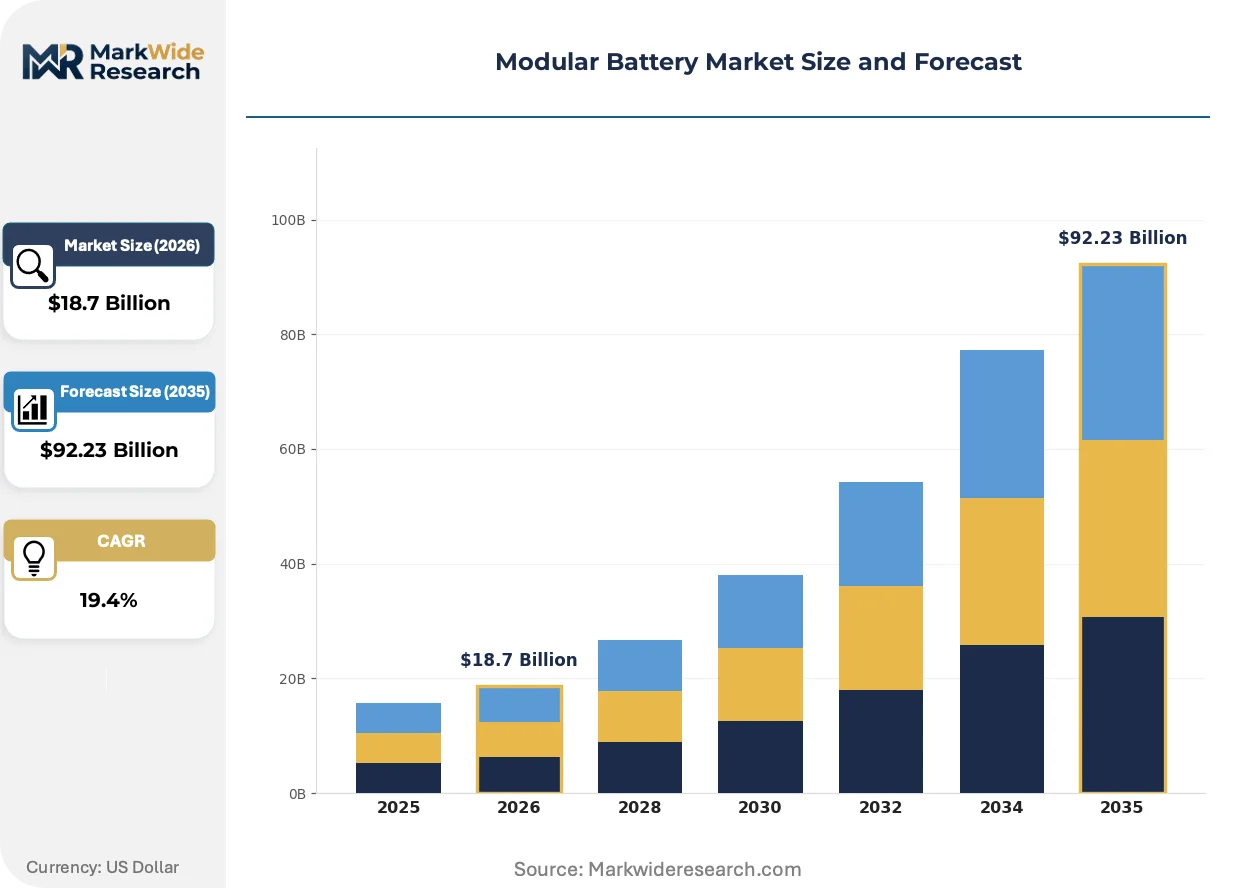
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Solid-State End User: Automotive, Renewable Energy, Consumer Electronics, Industrial Installation: Portable, Stationary, Grid-connected, Vehicle-integrated Deployment: Onshore, Off-grid, Grid-tied, Residential |
| Companies Covered | Samsung SDI, BYD Auto, A123 Systems, Envision AESC, Shenzhen Grepow Battery Co. Ltd., Changzhou Heco New Energy Technology Co., Ltd, TYVA Moduloo, Cleantron, XING Mobility, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Battery Market Shifts & Advancements
Solid-state architectures are advancing from laboratory demonstration toward pilot manufacturing, while regulatory frameworks in Europe and Asia are hardening compliance requirements that favor pre-certified system suppliers.
Ceramic electrolyte solid-state designs are displacing conventional liquid-electrolyte modules in premium stationary storage applications where thermal runaway tolerance commands price premiums. Grid operators in Germany are piloting these systems for urban substation installations. The technology is displacing incumbent lithium-ion variants in safety-critical deployments where fire suppression infrastructure costs outweigh cell-level premiums.
REACH and the EU Battery Regulation are mandating supply chain due diligence and recycled material quotas that reshape product design cycles for European market access. Industrial buyers now require carbon footprint labeling before contract award. Stationary storage integrators targeting Germany face the steepest compliance burden as procurement specifications embed these requirements.
Utility procurement departments are consolidating vendor lists around pre-qualified containerized system suppliers capable of delivering certified carbon-footprint documentation. Direct contracting with cell manufacturers is replacing distributor-mediated sourcing for large-scale German deployments. This concentration is most visible in transmission-connected buffer projects where single-source accountability reduces integration risk.
Modular Battery Market Segmentation
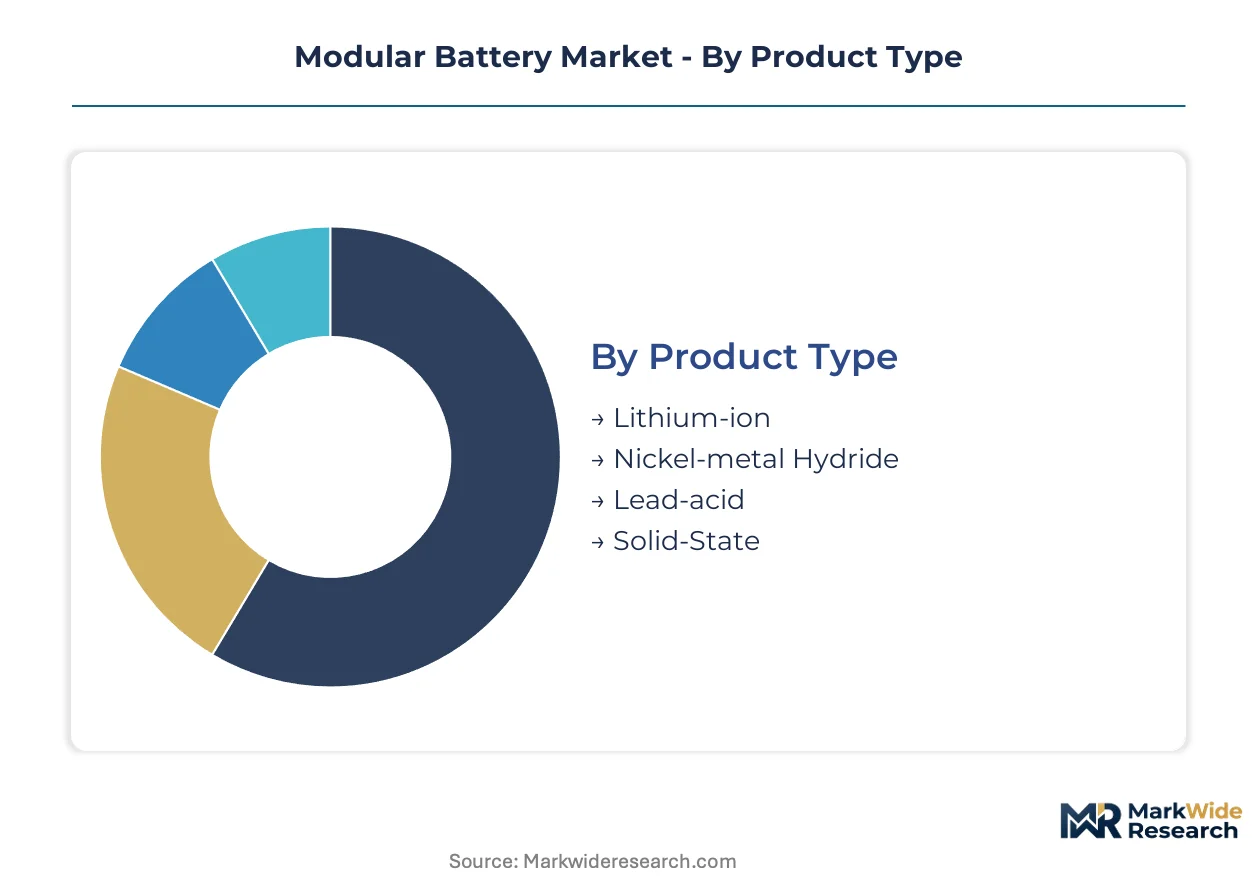
Modular battery architectures demand precise segmentation because chemistry choice, installation mode, and deployment context each trigger distinct regulatory pathways and margin structures. Product type determines carbon-footprint compliance burden under EU Battery Regulation, while end-use concentration shapes talent competition and procurement timelines.
Product Type:
REACH and EU Battery Regulation impose divergent recycled-content quotas and carbon-declaration requirements across electrochemical systems, forcing chemistry-specific qualification strategies.
- Lithium-ion:Nickel-manganese-cobalt and lithium-iron-phosphate variants dominate current procurement, with German grid operators specifying pre-certified carbon-footprint documentation before contract award. Jiangsu province manufacturing clusters supply the majority of cells for these deployments.
- Solid-State:Ceramic electrolyte architectures are displacing liquid-electrolyte modules in premium stationary storage where thermal runaway tolerance commands price premiums. German urban substation pilots are validating these systems for safety-critical infrastructure.
- Nickel-metal Hydride:Legacy chemistry retains niche presence in hybrid vehicle auxiliary power units where temperature cycling tolerance outweighs energy density requirements.
- Lead-acid:Mature technology serves price-sensitive backup power applications with minimal regulatory compliance overhead.
Lithium-ion handles the majority of throughput; solid-state is climbing the fastest on share.
End User:
Customer concentration determines engineering talent allocation and vertical integration incentives across the value chain.
- Automotive:Original equipment manufacturers anchor absolute volume demand, with BYD Auto and Samsung SDI sustaining in-house production of blade-cell modules and high-nickel cathode architectures respectively. Talent rotation from consumer electronics toward automotive programs tightens labor availability for other segments.
- Renewable Energy:German utilities are procuring containerized systems at scale to buffer intermittent wind and solar assets on transmission networks, compressing design cycles for integrators. This segment expands most quickly as grid operators seek buffer capacity.
- Consumer Electronics:Compact modular formats from specialists like Cleantron serve European light electric vehicles, occupying defensible niches against Asian volume producers.
- Industrial:Forklift and material-handling equipment fleets drive standardized 48V-80V module demand with predictable replacement cycles.
Automotive commands the largest installed base; renewable energy is gaining share fastest.
Installation:
Physical integration mode dictates thermal management complexity and service accessibility economics.
- Stationary:Containerized lithium-ion systems for German grid-tied deployments require specialized fire suppression infrastructure and climate-controlled enclosures. Procurement specifications embed EU Battery Regulation carbon-footprint thresholds.
- Vehicle-integrated:Cell-to-pack architectures under China's GB standards and MIIT guidelines enforce rigorous safety testing protocols that demand captive thermal engineering capacity.
- Portable:Swappable-unit designs enable aftermarket maintenance revenue streams separate from initial hardware sales.
- Grid-connected:Direct transmission interface requirements favor single-source accountability from pre-qualified system suppliers.
Stationary installations handle the majority of new capacity additions; vehicle-integrated systems are expanding most quickly on unit volume.
Deployment:
Grid interconnection status determines revenue model and regulatory jurisdiction for system operators.
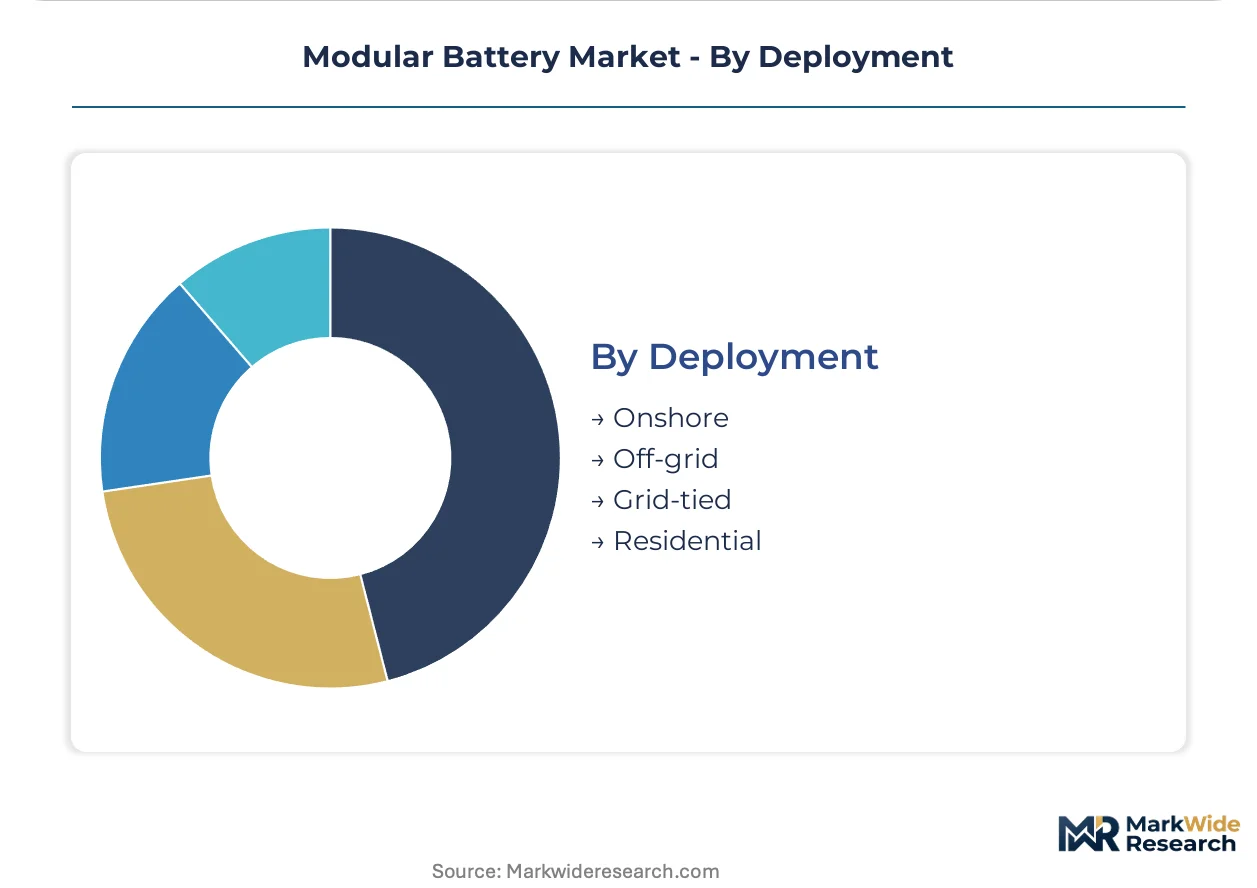
- Grid-tied:Utility procurement departments in Germany are consolidating vendor lists around pre-qualified containerized suppliers capable of delivering certified carbon-footprint documentation. Direct cell manufacturer contracting is replacing distributor-mediated sourcing.
- Off-grid:Remote industrial and residential applications prioritize modularity for simplified maintenance through swappable units, reducing downtime in locations with limited technician access.
- Onshore:Land-based renewable pairing with wind and solar assets concentrates in China's Jiangsu province where Envision AESC and CATL suppliers cluster manufacturing capacity.
- Residential:Behind-the-meter storage installations face steepest compliance burden as EU Battery Regulation deadlines tighten material sourcing constraints.
Grid-tied deployments handle the majority of megawatt-scale throughput; residential is climbing fastest on installation count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT guidelines and GB standards anchor China's regulatory framework for modular battery exports, while the EU Battery Regulation and REACH compliance reshape procurement specifications across European markets. Germany's transmission operators are consolidating vendor lists around pre-qualified containerized system suppliers.
China
Jiangsu province manufacturing clusters around Envision AESC and CATL suppliers are reducing logistics costs for grid-tied deployments. MIIT industry guidelines enforce cell-to-pack integration requirements and safety testing protocols that influence export-oriented manufacturers. Yangtze River Delta concentration enables direct contracting with cell manufacturers for large-scale stationary storage projects.
Germany
Transmission-connected buffer projects are compressing design cycles as utilities procure containerized lithium-ion systems at scale. EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape product design cycles. Urban substation installations in North Rhine-Westphalia are piloting solid-state ceramic electrolyte systems for safety-critical infrastructure.
United States
Grid operators seek buffer capacity for intermittent wind and solar assets across Texas and California interconnection queues. FERC Order 2222 enables distributed energy resource aggregation that favors modular swappable-unit architectures. Pacific Northwest battery manufacturing investments are expanding captive thermal management engineering capacity for stationary storage integrators.
South Korea
Automotive original equipment manufacturers anchor absolute volume demand through in-house production of high-nickel cathode architectures. METI circular economy directives influence East Asian industrial buyer requirements for material recovery agreements. Seoul Capital Area R&D campuses sustain leadership in electrochemical engineering talent rotation toward grid-scale programs.
Japan
JIS certification standards add compliance layers for suppliers targeting premium stationary storage applications. METI directives on circular economy pre-position recycling partnerships before material sourcing constraints tighten. Kanto region industrial buyers require carbon footprint labeling before contract award for containerized system deployments.
Modular Battery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market consolidating around pre-qualified system suppliers capable of delivering certified carbon-footprint documentation. The vendor base spans captive cell producers, independent pack integrators, and chemistry-agnostic system designers. Two strategic archetypes dominate: vertically integrated automotive-origin suppliers with in-house cathode production, and compact-format specialists occupying defensible niches in light electric vehicles. Competitive moves center on direct contracting with transmission operators and pre-certification against EU Battery Regulation thresholds before contract bidding.
Within the integrated leader tier, Samsung SDI and BYD Auto exemplify divergent approaches to captive supply chain control, while Cleantron represents the compact-format specialist archetype serving European light electric vehicle applications. Samsung SDI occupies a position anchored by Korea-based R&D investment in high-nickel architectures. BYD Auto exemplifies backward integration through in-house blade-cell module production. Cleantron sits within a defensible niche against Asian volume producers through standardized sub-pack units engineered for simplified maintenance.
| Leading Market Players |
|---|
| Samsung SDI |
| BYD Auto |
| A123 Systems |
| Envision AESC |
| Shenzhen Grepow Battery Co. Ltd. |
| Changzhou Heco New Energy Technology Co., Ltd |
| TYVA Moduloo |
| Cleantron |
| XING Mobility |
| Others |
Supply & Pricing Matrix
Ceramic electrolyte substitution for liquid-electrolyte architectures is redrawing procurement geography toward premium-tier suppliers while compressing margin buffers for nickel-dependent cathode producers. This chemistry migration simultaneously elevates EU Battery Regulation compliance costs and fragments volume-based pricing power across Jiangsu province manufacturing clusters.
Pricing Analysis
Price spreads between German transmission-connected buffer projects and Chinese export-oriented stationary systems reflect divergent certification burdens under REACH and EU Battery Regulation thresholds. Three-tier pricing structure across premium solid-state, standard high-nickel lithium-ion, and economy LFP variants tracks carbon-footprint documentation depth and thermal runaway tolerance ratings. Cost compression in standard lithium-ion tiers is intensifying because nickel price volatility erodes pack integrator margins. Renewable energy utilities exhibit highest price sensitivity due to procurement volume scale, while urban substation operators in Germany accept premium positioning for safety-critical solid-state deployments.
Supply Chain Analysis
Inventory lead times for high-nickel cathode precursors have extended as electrochemical engineering talent rotates toward automotive programs, constraining smaller stationary storage integrators. Supply concentrates in China, South Korea, and Japan for cell manufacturing, with Germany and the United States anchoring downstream system integration. Raw material dependencies center on lithium carbonate, nickel sulfate, and cobalt hydroxide feedstocks. Single-source vulnerability around Jiangsu province cathode production clusters poses concentration risk for European-bound containerized systems. Distribution runs through direct manufacturer contracting with German utilities, displacing distributor-mediated sourcing for transmission-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modular battery markets are pivoting toward service-attach revenue models where aftermarket maintenance contracts and swappable-unit replacement programs expand faster than initial hardware sales. Recurring revenue layers from carbon-footprint monitoring and recycling partnership management now command margin premiums exceeding cell manufacturing economics.
For Market Incumbents: Secure pre-qualified status under EU Battery Regulation carbon-declaration thresholds before German utility procurement windows close. Lock long-term offtake agreements with Jiangsu province cathode suppliers to hedge nickel price volatility. Vertical integration into blade-cell architectures, as demonstrated by BYD Auto's captive production model, defends margin position against independent pack integrators facing engineering talent scarcity. For New Entrants and Emerging Players: CE marking fast-track for compact modular formats targeting European light electric vehicles offers penetrable white space against Asian volume producers. Target off-grid residential deployments in regions with limited technician access where modularity commands service premiums. Position through recycling partnership pre-positioning ahead of EU Battery Regulation compliance deadline tightening. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors pre-certified system suppliers with documented carbon-footprint pathways. Solid-state ceramic electrolyte specialists with pilot manufacturing yields improving represent viable acquisition targets over the coming decade. Watch German urban substation solid-state pilot outcomes as inflection indicator for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Recycling Partnership Pre-positioning | EU Battery Regulation compliance deadlines force integrators to secure material recovery agreements before sourcing constraints tighten. |
| Direct Utility Contracting | German transmission operators are consolidating vendor lists around single-source accountable suppliers for containerized buffer systems. |
| Solid-State Pilot Manufacturing Scale-Up | Ceramic electrolyte yield improvements open premium grid-buffer applications requiring higher energy density and thermal runaway tolerance. |
| Carbon-Footprint Certification Investment | Pre-certification against EU Battery Regulation thresholds enables contract bidding for German stationary storage procurement. |
| Service Revenue Unbundling | Modular swappable-unit architectures enable aftermarket maintenance streams separate from initial hardware sales to renewable energy utilities. |
Research Methodology
Desk research of customs trade filings, MIIT industry guideline publications, and EU Battery Regulation technical documentation preceded structured interviews with stationary storage procurement officers at German utilities, pack integration engineering directors, and cathode supply chain managers. Primary fieldwork with EPC contractors and grid operators across transmission-connected buffer projects combined with secondary validation against SEC filings from listed cell manufacturers and REACH compliance databases. Bottom-up unit economics modeling triangulated against top-down market sizing from Jiangsu province production cluster assessments.
Variance decomposition across chemistry type, installation mode, and deployment context anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include electrochemical system architecture, end-use concentration between automotive and renewable energy, physical integration mode, and grid interconnection status. CAGRs derived from elasticity-adjusted demand curves incorporating nickel price volatility assumptions and EU regulatory compliance timeline impacts. Industry-specific forecast inputs encompassed electrochemical engineering talent availability indices and solid-state manufacturing yield improvement trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained EU Battery Regulation enforcement and continued Jiangsu province manufacturing concentration; material deviation in regulatory timelines or supply chain geography would warrant model refresh. Forecasts reflect base-case assumptions around ceramic electrolyte commercialization pace and REACH documentation burden stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Advanced Batteries Market
Batteries
18650 And 21700 Battery Market
Batteries
Solid-State Car Battery Market
Batteries
Nickel-Based Battery Charger Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Smart Battery Charger Market
Batteries
India Alkaline Battery Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
N-Type Battery Market
Batteries
East Africa Battery Market
Batteries
Taiwan Battery Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
Battery Cases Market
Batteries
Europe Battery Cell Market
Batteries
Asia-Pacific Consumer Battery Market