
 Europe Battery Cell Market | 2026-2036
Europe Battery Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Battery Cell Market Foresight
CE marking under the EU Battery Regulation is reorganizing which producers qualify for European automotive supply contracts. Northvolt leverages its Swedish gigafactory and renewable energy integration to anchor regional cathode supply. Automotive Cells Company (ACC) sustains French-German manufacturing scale through its Stellantis-TotalEnergies-Saft partnership structure. LG Energy Solution competes via its Polish operational base, controlling distribution into German OEM final assembly.
A battery cell is an electrochemical device converting stored chemical energy into electrical energy through reversible redox reactions, typically achieving energy densities of 250-300 Wh/kg in advanced lithium-ion formats and serving as the fundamental building block for modular battery packs in transportation and stationary storage systems. Lithium-ion chemistry dominates current production scale, though solid-state architectures are capturing R&D allocation due to their promise of higher energy density and reduced thermal runaway risk. The automotive end-user segment drives volume requirements, while renewable energy applications are expanding fastest as grid-scale storage projects multiply across Southern Europe.
The EU Battery Regulation, REACH compliance for chemical substances, and the ECHA's restricted substance protocols collectively mandate recycled content thresholds and supply chain due diligence that reshape material sourcing economics. EMA and national regulators in France and Germany are aligning clinical and industrial safety standards for transport of hazardous cell materials. Stakeholders must monitor how the EU AI Act's quality management requirements intersect with automated battery manufacturing inspection systems.
Market Dynamics
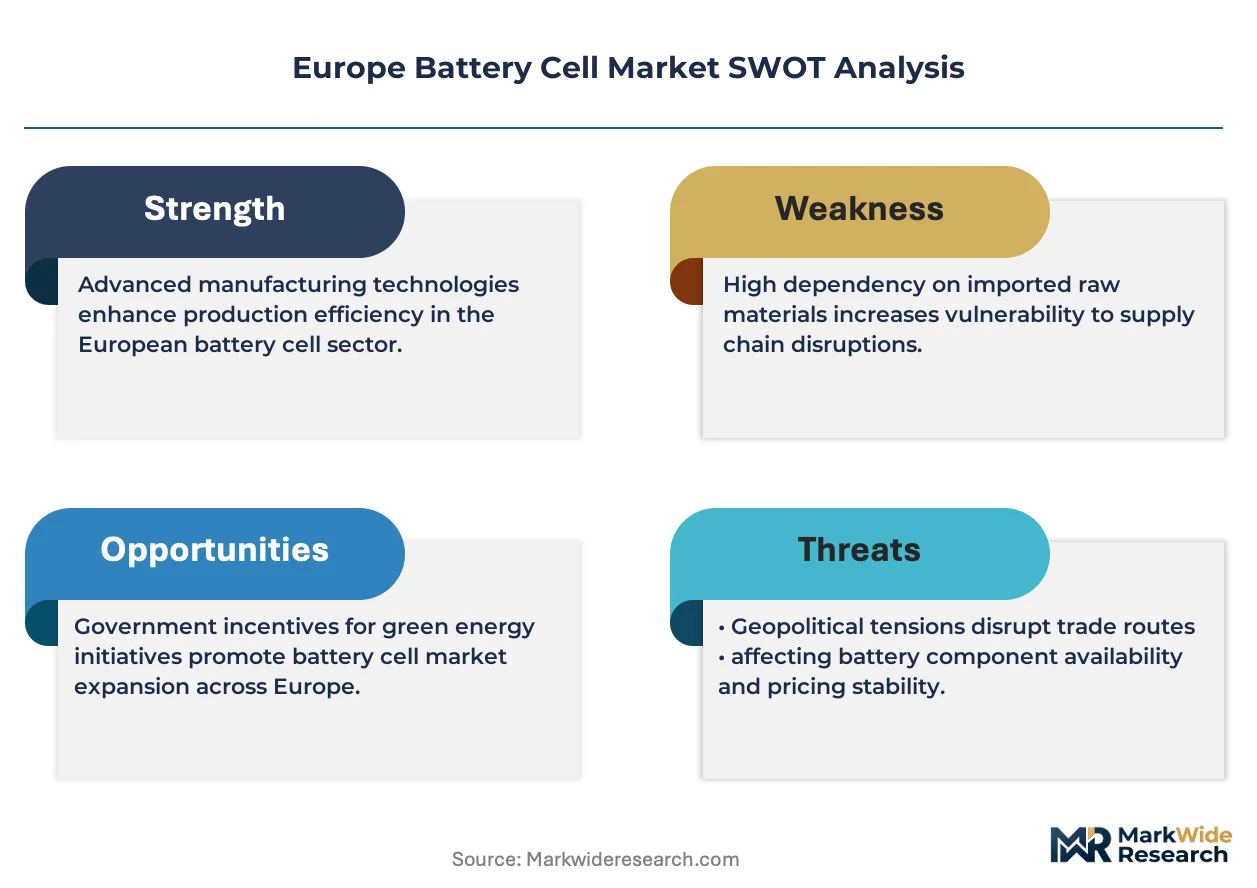
The EU Battery Regulation's carbon footprint declarations and recycled content mandates are forcing a wholesale reconfiguration of material sourcing and factory siting decisions across European cell production.
Growth Catalysts
- REACH Compliance:Chemical substance protocols under ECHA are accelerating investment in closed-loop recycling infrastructure for cathode active materials.
- Automotive Electrification:German and French OEM procurement programs are mandating local cell supply, creating guaranteed offtake for greenfield gigafactories.
- Nordic Renewable Integration:Sweden's grid composition enables producers to meet EU Battery Regulation carbon intensity thresholds that fossil-heavy grids cannot achieve.
Market Restraints
- Lithium Price Volatility:Spodumene concentrate contracts and South American brine supply disruptions create input cost instability that compresses margin planning.
- Cathode Precursor Concentration:Chinese refining dominance for nickel sulfate and cobalt hydroxide creates geopolitical exposure that European cell makers cannot fully hedge.
- Solid-State Timeline Uncertainty:Polymer and sulfide electrolyte manufacturing scalability remains unproven at automotive volumes, delaying chemistry transitions.
Strategic Opportunities
- Polish Manufacturing Corridor:Lower-cost industrial zones near German border offer logistics advantages for supplying Central European automotive assembly.
- Grid-Scale Storage Applications:Southern European renewable energy projects are creating demand for LFP cells outside automotive qualification cycles.
- EU Green Deal Funding:Innovation Fund and Just Transition Mechanism allocations are de-risking capital deployment for recycling and precursor facilities.
Industry Challenges
- Electrolyte Formulation Expertise:Shortage of electrochemists with lithium salt and additive optimization experience is constraining R&D throughput.
- CE Marking Timeline Compression:EU Battery Regulation conformity assessment procedures are extending certification cycles beyond product development schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Battery Cell Market |
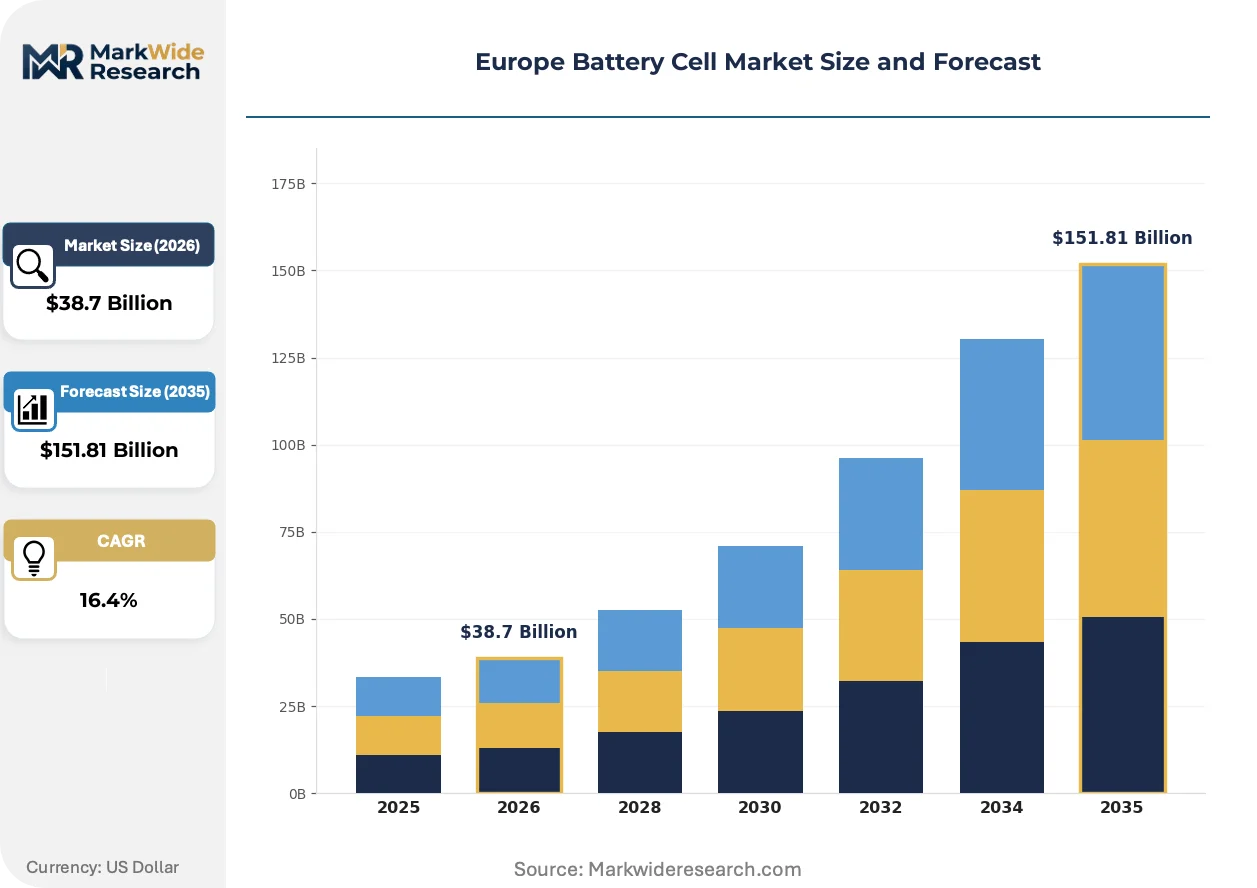
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $151.81 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Solid-state, Lead-acid End User: Automotive, Consumer Electronics, Renewable Energy, Industrial Equipment Technology: Energy Density, Fast Charging, Thermal Management, Battery Management System Form Factor: Cylindrical, Prismatic, Pouch, Custom |
| Companies Covered | Northvolt, Automotive Cells Company (ACC), Saft Groupe SA, VARTA AG, Leclanché SA, LG Energy Solution, CATL, Samsung SDI, Exide Technologies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Battery Cell Market Shifts & Advancements
Cell chemistry and manufacturing processes are diverging along performance versus cost axes, with regulatory pressure forcing faster adoption of technologies previously consigned to pilot phases.
Solid-state electrolyte development is bifurcating between oxide and sulfide technical routes. Automotive qualification programs in Germany are prioritizing sulfide systems for their ionic conductivity advantages. This chemistry split is compressing equipment supplier order books as lines must accommodate divergent thermal processing requirements.
The EU AI Act's quality management mandates are reshaping automated inspection protocols. Manufacturing lines must now document algorithmic decision trails for defect classification. Polish and Hungarian facilities are retrofitting vision systems to meet these traceability requirements ahead of enforcement timelines.
Fleet operators and energy utilities are consolidating procurement through long-term offtake agreements rather than spot market purchases. This contract structure is displacing merchant sales channels for cell output. Nordic project developers are pioneering ten-year service agreements that bundle cell supply with performance guarantees and recycling take-back.
Europe Battery Cell Market Segmentation
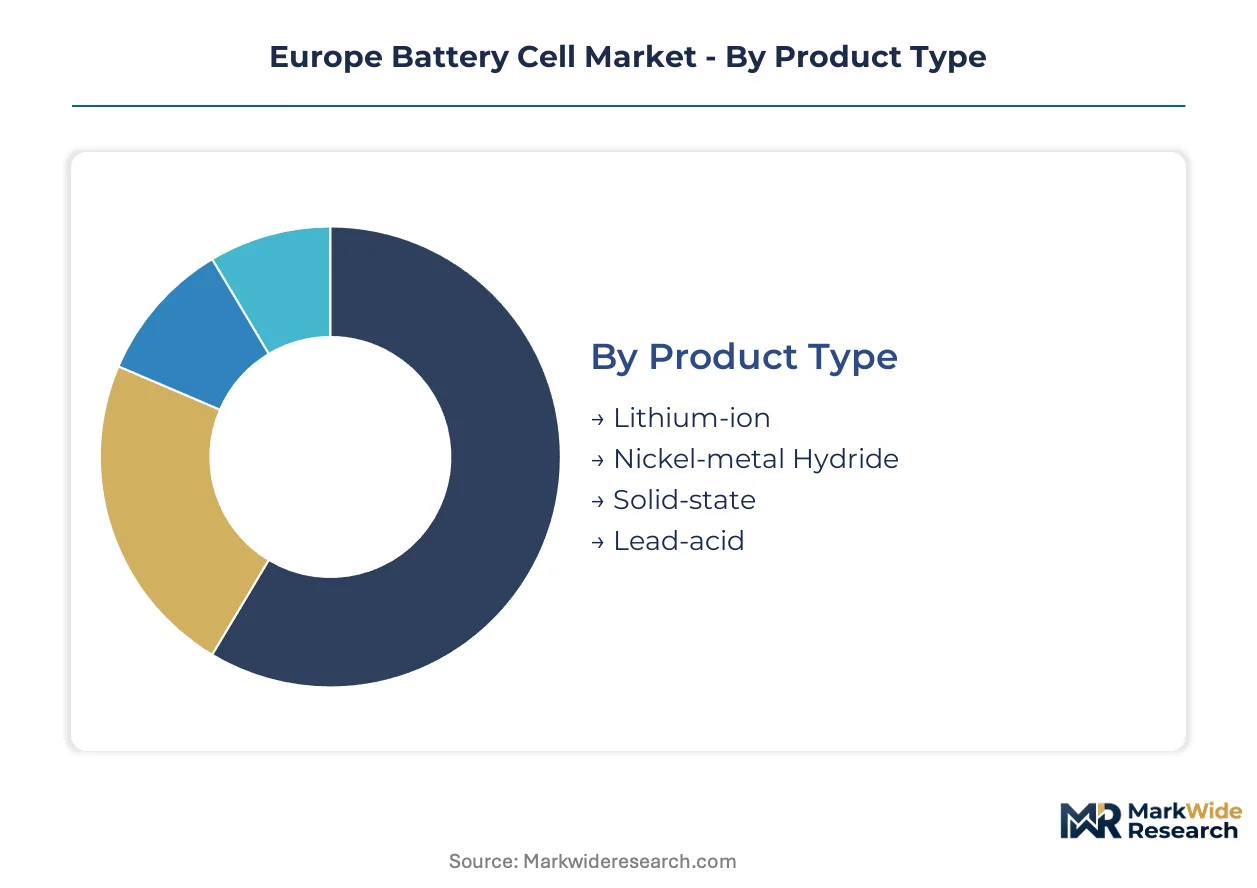
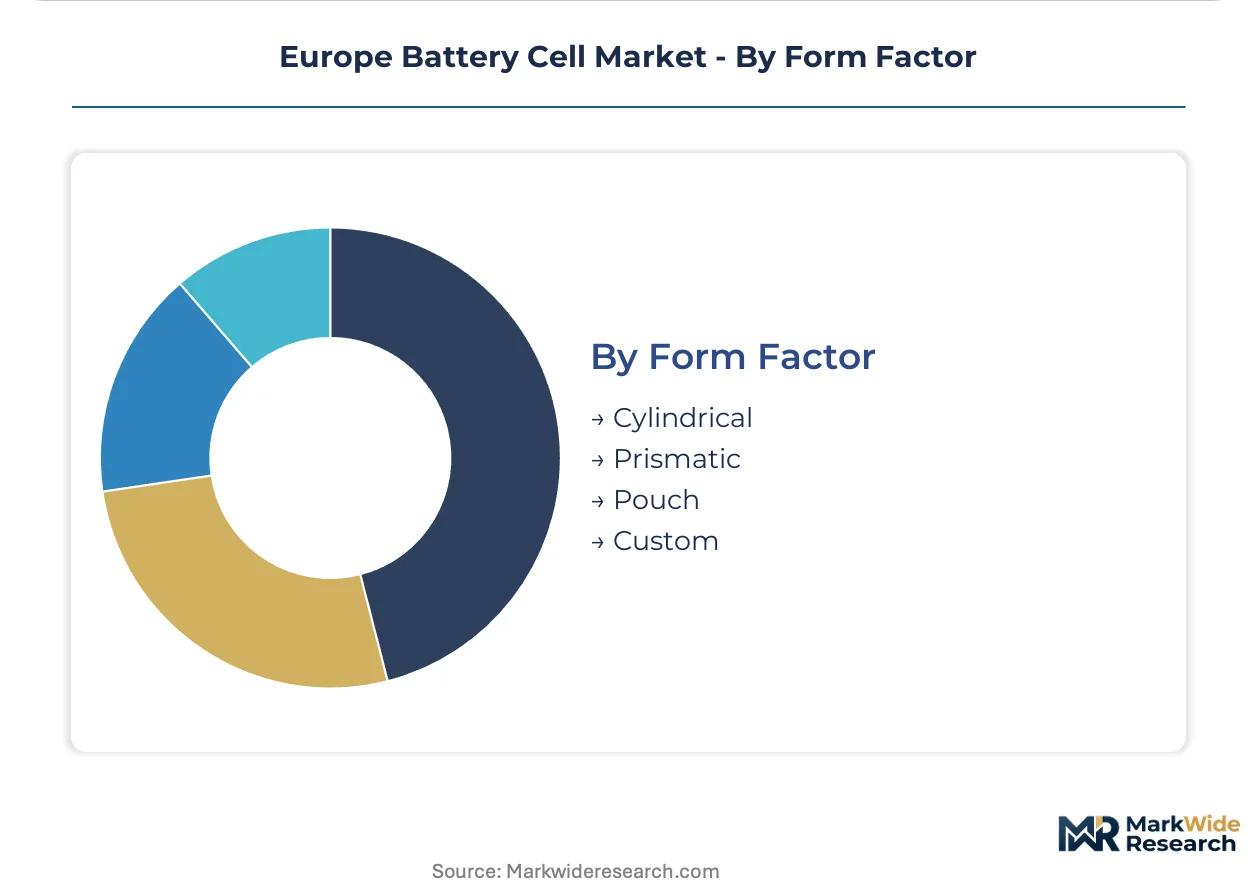
Segmentation reveals how regulatory pressure and application requirements fragment European cell procurement. Chemistry choices, form factor selection, and end-use specifications determine factory equipment configurations and margin structures across the region.
Product Type:
Substitution pressure from solid-state architectures and alternative chemistries is forcing lithium-ion incumbents to defend their automotive qualification positions.
- Lithium-ion:NMC and LFP cathode variants dominate current gigafactory output, achieving 250-300 Wh/kg energy density in automotive-qualified formats. German OEM qualification programs concentrate demand for high-nickel NMC cells in premium electric vehicle platforms.
- Solid-state:Sulfide and oxide electrolyte prototypes are advancing through automotive validation cycles in Sweden and Germany, promising 400+ Wh/kg density with reduced thermal runaway risk. Nordic producers leverage renewable-powered manufacturing to meet EU Battery Regulation carbon thresholds that solid-state production requires.
- Nickel-metal Hydride:Hybrid vehicle auxiliary systems sustain residual demand in French and Japanese transplant assembly plants.
- Lead-acid:Stationary backup and industrial starter applications persist where energy density requirements remain minimal.
Lithium-ion anchors the volume base while solid-state gains share at the steepest rate.
End User:
Cost tier divergence separates automotive qualification premiums from industrial commodity procurement.
- Automotive:Electric vehicle platforms drive cell format standardization and cathode chemistry selection across European OEM supply chains. Stellantis, Volkswagen Group, and Renault-Nissan procurement mandates for localized supply are guaranteeing offtake volumes for greenfield gigafactories in France, Germany, and Poland.
- Renewable Energy:Grid-scale storage projects across Spain, Italy, and Greece are expanding fastest outside automotive cycles, favoring LFP chemistry for cycle life and cost economics. Southern European solar-wind hybrid developments require ten-year service agreements with performance guarantees.
- Consumer Electronics:Polish and Hungarian facilities supply cylindrical formats for power tool and portable device manufacturers.
- Industrial Equipment:Forklift and material handling fleets in German logistics corridors sustain demand for standardized cell modules.
Automotive commands the premium tier while renewable energy applications expand most quickly.
Technology:
Volume concentration in fast-charging and energy density specifications is reshaping R&D allocation across European cell developers.
- Fast Charging:Silicon-anode and advanced electrolyte additive formulations enable 10-80% charge cycles under 20 minutes for premium automotive platforms. German OEM technical specifications are mandating 350 kW capable cell architectures.
- Energy Density:High-nickel cathode and dry electrode processing push gravimetric performance toward 300 Wh/kg at cell level. French-German joint development programs prioritize this metric for extended-range electric vehicle segments.
- Thermal Management:Cell-to-pack architectures eliminate module housings to improve volumetric efficiency and cooling uniformity.
- Battery Management System:Embedded sensing and predictive algorithms extend cycle life through adaptive charging protocols.
Energy density anchors the performance hierarchy while fast charging climbs the fastest.
Form Factor:
Customer type differentiation separates automotive prismatic standardization from industrial cylindrical commodity supply.
- Prismatic:Aluminum-housed cells dominate European automotive pack designs, enabling direct cooling plate integration and structural battery pack functions. German OEM platforms are converging on standardized prismatic dimensions to simplify pack assembly automation.
- Cylindrical:2170 and 4680 formats serve power tool, e-bike, and energy storage applications where automated winding equipment achieves lowest unit costs. Polish manufacturing corridors specialize in high-volume cylindrical output for consumer and industrial markets.
- Pouch:Polymer-laminated formats persist in hybrid vehicle applications and aerospace weight-critical systems.
- Custom:Specialized geometries serve defense, medical, and marine applications with low volume and high specification requirements.
Prismatic formats anchor automotive volume while cylindrical production scales fastest in Central European supply corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French automotive procurement programs concentrate buyer power across Northern Europe, while Nordic renewable integration and Central European manufacturing corridors fragment production geography across multiple national jurisdictions.
Germany
Volkswagen Group and Stellantis procurement mandates for localized cell supply are guaranteeing offtake volumes for greenfield gigafactories. The KBA aligns vehicle type approval with EU Battery Regulation carbon footprint thresholds. North Rhine-Westphalia and Lower Saxony host cathode precursor development clusters near OEM final assembly plants.
Sweden
Northvolt's gigafactory anchor creates guaranteed demand for high-nickel cathode materials and renewable-powered electrolyte processing. The Swedish Energy Agency channels EU Green Deal Innovation Fund allocations into solid-state pilot lines. Västerås and Skellefteå concentrate cell manufacturing and recycling infrastructure development.
Poland
Lower-cost industrial zones near the German border attract cylindrical cell production for consumer and industrial markets. ECHA REACH compliance protocols accelerate closed-loop recycling infrastructure investment. Lower Silesia and the Katowice special economic zone host LG Energy Solution operations distributing into Central European automotive assembly.
France
Renault-Nissan procurement programs and Saft's industrial battery heritage sustain demand for LFP and NMC cell formats. ANSM clinical safety standards intersect with EMA transport regulations for hazardous cell materials. The Hauts-de-France region anchors ACC's Stellantis-TotalEnergies-Saft manufacturing joint venture.
Hungary
Automotive supplier clustering around German OEM satellite plants creates demand for prismatic cell qualification programs. EU AI Act quality management mandates are reshaping automated inspection protocols for defect classification. Győr and Debrecen industrial zones attract battery module and pack assembly investments.
Europe Battery Cell Market Competitive Landscape
Player mix skews toward integrated European champions backed by automotive OEM partnerships, with Asian cell makers establishing manufacturing beachheads through Polish and Hungarian operational bases. Structure concentrates around three strategic archetypes: Nordic renewable-integrated producers, Franco-German automotive-aligned joint ventures, and Korean-Japanese scale players with European distribution hubs. Dominant competitive moves include strategic partnerships securing offtake volumes and capacity expansion targeting CE marking qualification timelines.
Within the integrated European champion tier, Northvolt and Automotive Cells Company exemplify the automotive-OEM partnership archetype, while Saft Groupe SA occupies a position bridging industrial and transportation applications. LG Energy Solution represents the Asian scale player model with established Polish manufacturing presence.
| Leading Market Players |
|---|
| Northvolt |
| Automotive Cells Company (ACC) |
| Saft Groupe SA |
| VARTA AG |
| Leclanché SA |
| LG Energy Solution |
| CATL |
| Samsung SDI |
| Exide Technologies |
| Others |
Supply & Pricing Matrix
Sixty-day cathode precursor inventory cycles in European gigafactories signal how lithium carbonate spot exposure and Chinese refining dominance concentrate margin pressure among Polish and Hungarian cell producers unable to hedge input volatility through long-term offtake structures.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange nickel and Fastmarkets lithium carbonate assessments dominate automotive procurement, with premium-mid-economy pricing differentiation separating CE-marked automotive qualification tiers from industrial cylindrical commodity supply. Price differentiation hinges on carbon footprint certification grade under EU Battery Regulation thresholds and volume scale in gigawatt-hour procurement bands. Cost compression in standard-tier LFP cells is intensifying because South American brine supply disruptions feed spot market volatility. Renewable energy utilities exhibit highest price sensitivity due to project finance constraints, while German OEM platform engineers accept qualification premiums for high-nickel NMC architectures.
Supply Chain Analysis
Strategic stockpiling of nickel sulfate and cobalt hydroxide precursors prevails over just-in-time cathode active material delivery as Chinese refining concentration creates single-source vulnerability European cell makers cannot diversify within qualification timelines. Supply draws from Chilean brine operations, Australian spodumene concentrators, and Finnish nickel refiners. Raw material dependencies center on lithium carbonate, high-purity graphite, and nickel-cobalt-manganese precursor sulfates. Tariff exposure on Chinese-origin cathode materials threatens margin structures for Polish cylindrical producers. Distribution runs through German OEM final assembly plants and Southern European grid-scale storage EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European lithium-ion incumbents face substitution defense against solid-state architectures advancing through German automotive qualification cycles, requiring chemistry-transition hedging and manufacturing line flexibility investments.
For Market Incumbents: Shield automotive qualification positions by securing backward integration into Finnish nickel refining and Swedish renewable-powered cathode precursor processing. Accelerate dry electrode coating capacity in North Rhine-Westphalia to defend margin structures against sulfide electrolyte competitors. Prioritize CE marking timeline compression through preemptive EU Battery Regulation conformity documentation.
For New Entrants and Emerging Players: Anchor in Southern European grid-scale storage procurement, where LFP chemistry bypasses automotive qualification barriers and ten-year service agreement structures create sticky revenue. Target Spanish solar-wind hybrid developers seeking bundled cell supply with recycling take-back. Pursue cylindrical format specialization for Polish power tool manufacturers as lowest-capital entry path.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded battery assets outside core electrification strategies. Five-to-ten-year viability hinges on cathode precursor supply security and renewable energy manufacturing integration depth. Monitor solid-state electrolyte manufacturing yield rates as inflection indicator for chemistry transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Secures nickel sulfate supply from Finnish refiners against Chinese concentration risk. |
| Renewable-Powered Manufacturing Certification | Enables Swedish producers to meet EU Battery Regulation carbon intensity thresholds. |
| Solid-State Electrolyte Pilot Line Investment | Positions German developers for sulfide chemistry automotive qualification programs. |
| Long-Term Offtake Agreement Structuring | Binds Southern European utilities to ten-year LFP supply with performance guarantees. |
| Closed-Loop Recycling Infrastructure Buildout | Supports ECHA REACH compliance for cathode active material recovery in Poland. |
Research Methodology
Operator-level perspectives from gigafactory operations directors, OEM platform procurement leads, EPC contractor project developers, and cathode precursor supply planners anchored the qualitative base for this study. Primary interview findings triangulated against secondary validation from EU Battery Regulation implementation guidance, ECHA REACH substance restriction updates, vehicle production databases, and customs trade flow records for lithium carbonate and refined nickel. Bottom-up cell production capacity aggregation and top-down automotive electrification demand modeling converged on volume estimates.
Sensitivity analysis across lithium price scenarios, solid-state manufacturing yield assumptions, and EU Green Deal funding allocation variants tested forecast robustness throughout the projection horizon. Segmentation dimensions modeled include cathode chemistry, end-use application, form factor specification, and national regulatory cluster. CAGRs derived from installed capacity ramp rates and OEM procurement mandate timelines, with input from grid-scale storage project development pipelines and renewable energy integration requirements.
Decision-makers should treat outputs as directional under base assumptions of sustained automotive electrification mandates and lithium-ion chemistry dominance; material deviation would warrant model refresh. Revision becomes warranted when solid-state electrolyte manufacturing yields cross automotive qualification thresholds or Chinese precursor export restrictions tighten supply availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Nimh Battery Market
Batteries
Wood-Based Batteries Market
Batteries
Submarine Batteries Market
Batteries
Carbon Foam Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
Battery Anode Materials Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
India Electric Vehicle Battery Electrolyte Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Battery Cell Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Stationary Lead-Acid Battery Market
Batteries
Battery Plate Market
Batteries
Europe Consumer Battery Market
Batteries
18650 And 21700 Battery Market