
 Asia-Pacific Battery Market | 2026-2036
Asia-Pacific Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Battery Market Analysis
Commercial fleet operators and stationary grid developers are bifurcating from traditional consumer electronics buyers as the dominant procurement force. CATL leverages integrated cathode-to-pack manufacturing across Fujian and Sichuan facilities to capture cost advantages at scale. BYD anchors its position through captive demand from automotive and monorail divisions, while Samsung SDI competes on premium cylindrical formats for premium electric vehicle platforms.
A battery is an electrochemical device storing and releasing energy through reversible ion transfer between anode and cathode materials, with lithium-ion variants achieving energy densities above 250 Wh/kg using nickel-manganese-cobalt oxide cathodes and graphite-silicon composite anodes. Its primary purpose is to decouple energy generation from consumption across mobility, portable electronics, and grid stabilization applications. Lithium-ion chemistry dominates product type revenue due to its superior cycle life and specific energy, while solid-state technology within the technology dimension attracts the fastest development capital as manufacturers pursue dendrite suppression and wider operating temperature ranges. The automotive end user segment commands the deepest margin pools, though renewable energy application demand for multi-hour grid storage is expanding fastest in absolute capacity terms.
China's MIIT enforces GB standards for cell safety and recycling traceability, while South Korea's MFDS and KATS coordinate battery certification with automotive homologation requirements. Japan's METI subsidizes domestic lithium refining and solid-state pilot lines under its battery supply chain resilience program. Stakeholders must monitor how India's BIS adoption of UN 38.3 testing protocols and PLI scheme localization thresholds reshape competitive access across Southeast Asian assembly markets.
Market Dynamics
Commercial fleet electrification across logistics and ride-hailing platforms is concentrating procurement power in the hands of volume buyers, compressing pricing cycles and forcing cell manufacturers toward standardized high-capacity formats. This demand concentration is restructuring supplier relationships across the Asia-Pacific value chain.
Growth Catalysts
- Dual carbon goals:China's MIIT enforcement of GB standards for cell safety and recycling traceability mandates fleet electrification timelines, accelerating procurement from domestic gigafactories.
- Stationary grid storage:Renewable energy developers across South Korea and Japan are contracting multi-hour battery systems under METI and MFDS certification frameworks, expanding absolute capacity demand.
- Solid-state pilot lines:Japan's METI battery supply chain resilience program subsidizes domestic lithium refining and next-generation cell manufacturing, attracting development capital toward dendrite-suppression technologies.
Market Restraints
- Cathode material concentration:Nickel-manganese-cobalt oxide refining capacity clusters in Chinese Fujian and Sichuan provinces, creating single-source vulnerability for regional cell producers.
- Silicon-graphite anode cost volatility:Fluctuating metallurgical-grade silicon prices from Australian and Brazilian suppliers compress margins on high-energy-density cell variants.
- Recycling compliance friction:China's GB standards for full-life-cycle traceability impose documentation burdens that smaller pack assemblers struggle to satisfy.
Strategic Opportunities
- India's PLI localization:BIS adoption of UN 38.3 testing protocols combined with production-linked incentive thresholds creates assembly market entry points for cathode-to-pack integrators.
- Southeast Asian logistics electrification:Commercial fleet operators in Vietnam and Indonesia remain underpenetrated relative to China, offering first-mover positioning for cylindrical format specialists.
- Solid-state convergence:Polymer-ceramic electrolyte interfaces combined with lithium-metal anodes enable wider operating temperature ranges for premium electric vehicle platforms.
Industry Challenges
- Electrolyte formulation expertise gap:Solid-state manufacturing requires polymer chemistry and thin-film deposition skills scarce across existing lithium-ion engineering workforces.
- UN 38.3 certification timelines:Multi-stage testing protocols for transport safety create six-to-nine-month delays between cell design completion and commercial deployment.
- Pack-to-vehicle integration complexity:Thermal management and battery management system compatibility with legacy automotive architectures demands co-development resources cell manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Battery Market |
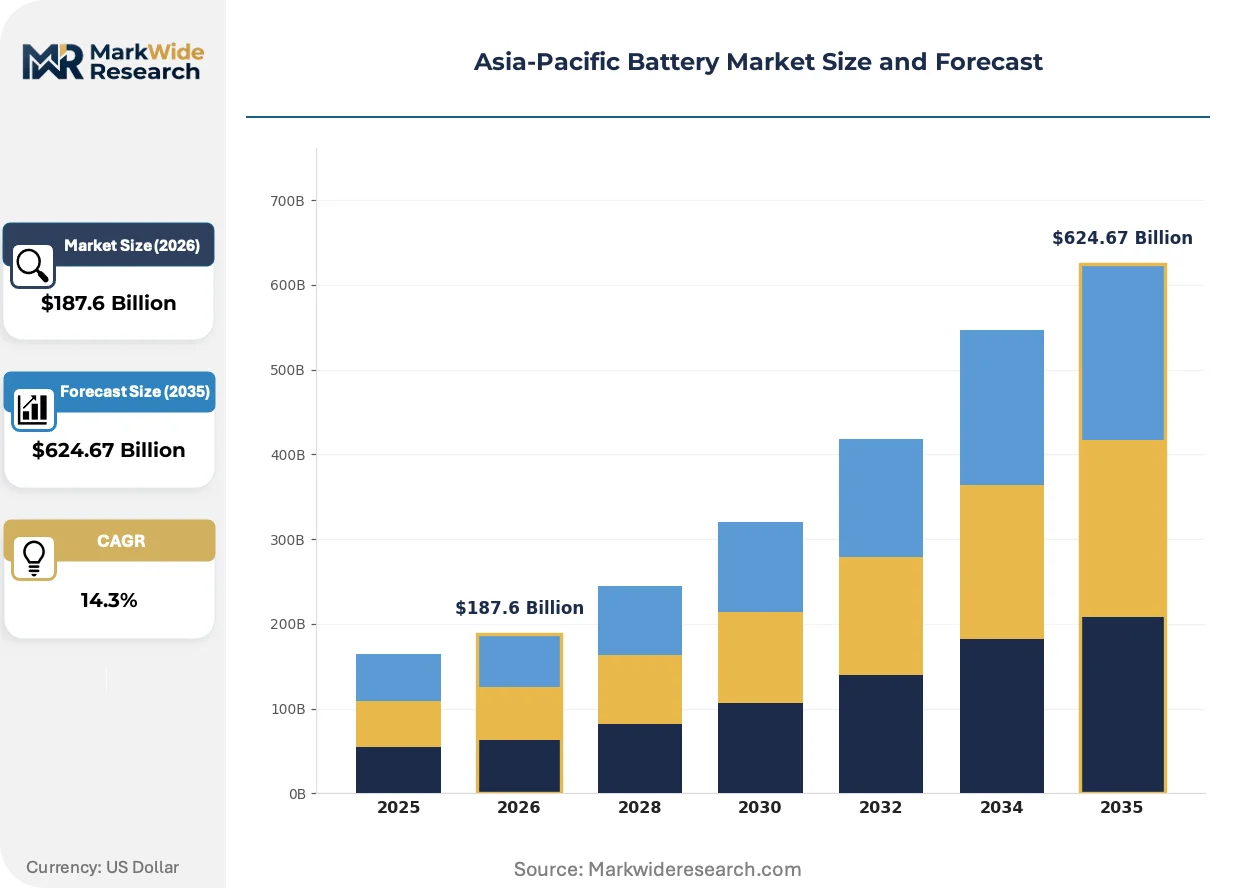
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $624.67 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead Acid, Zinc Carbon End User: Automotive, Consumer Electronics, Energy Storage, Industrial Technology: Rechargeable, Non-rechargeable, Fuel Cell, Solid State Application: Electric Vehicles, Mobile Devices, Power Tools, Renewable Energy |
| Companies Covered | Contemporary Amperex Technology Co., Ltd. (CATL), BYD Company Limited, LG Energy Solution, Samsung SDI, Panasonic Holdings Corporation, SK Innovation, GS Yuasa Corporation, EnerSys, EVE Energy Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Battery Market Emerging Trajectories
Solid-state electrolyte architectures are advancing from laboratory validation toward pilot manufacturing, while regulatory frameworks harden around carbon intensity disclosure and end-of-life accountability. These parallel developments are compressing the competitive window for incumbent liquid-electrolyte producers.
Sulfide-based solid-state electrolytes achieve ionic conductivities matching liquid counterparts while eliminating flammable organic solvents. Premium electric vehicle platforms from Japanese and South Korean automakers are qualifying these cells for 2027 model year integration. This chemistry is supplanting conventional lithium-ion configurations in applications where thermal runaway tolerance commands price premiums.
China's MIIT has expanded GB standard enforcement to mandate blockchain-based recycling traceability across cathode material supply chains. Cell manufacturers must now document cobalt and lithium provenance from mine through refining to pack assembly. South Korean exporters face the steepest compliance burden, as MFDS certification must now integrate with China's traceability infrastructure for market access.
Fleet operators are consolidating procurement through direct long-term supply agreements with cell manufacturers, bypassing traditional tiered distributor networks. Commercial logistics platforms in China and Japan now negotiate cathode-to-pack contracts with volume floors and price adjustment clauses tied to lithium carbonate indices. This disintermediation is most visible in heavy-duty truck electrification, where fleet-scale buyers extract customization concessions unavailable to automotive OEMs.
Asia-Pacific Battery Market Segmentation
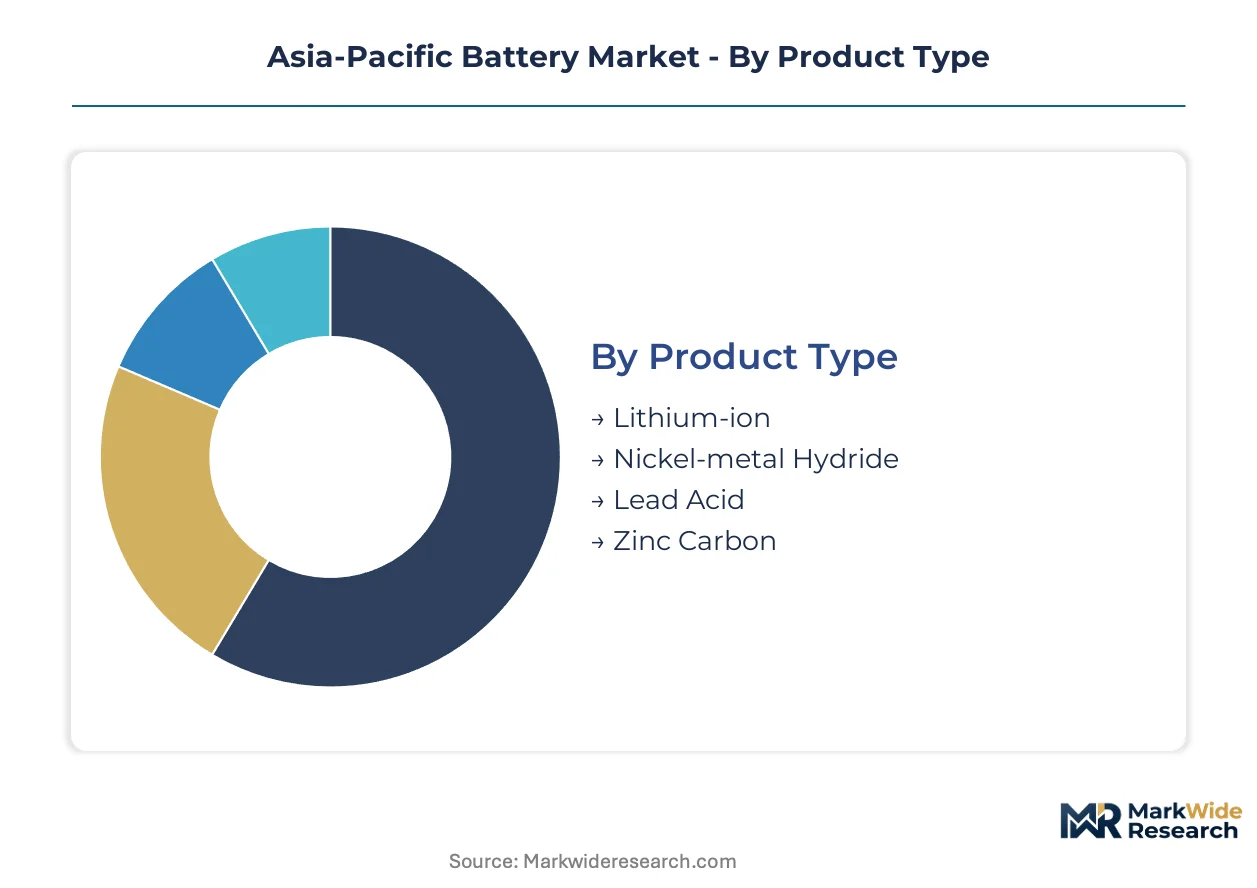
Asia-Pacific Battery Market segmentation reveals distinct channel pathways where automotive OEMs and grid developers procure through direct long-term contracts, while consumer electronics flows through tiered distributor networks. Understanding these procurement patterns exposes margin concentration and technology adoption velocity across the value chain.
Product Type:
Lithium-ion cells move predominantly through direct cathode-to-pack agreements with fleet operators and automotive platforms, while lead acid and zinc carbon variants circulate via wholesale electrical supply channels serving replacement markets.
- Lithium-ion:Nickel-manganese-cobalt oxide cathodes paired with graphite-silicon composite anodes achieve energy densities above 250 Wh/kg. Procurement concentrates with CATL and BYD supplying China's commercial logistics electrification mandates under MIIT GB standards.
- Lead Acid:Mature flooded and absorbed glass mat configurations dominate stationary backup power and two-wheeler starter applications. Demand persists across India's unorganized automotive service sector where BIS certification costs deter lithium substitution.
- Nickel-metal Hydride:Toyota's hybrid vehicle platforms in Japan sustain residual demand for this chemistry. METI supply chain resilience programs have excluded NiMH from subsidized domestic production.
- Zinc Carbon:Primary cell format for low-drain remote controls and emergency lighting across Southeast Asian retail channels. Price compression from alkaline substitution limits manufacturer investment in capacity expansion.
By volume, lead acid leads across replacement cycles and two-wheeler penetration. By growth pace, lithium-ion is expanding most quickly through electric vehicle and grid storage procurement.
End User:
Cost tier stratification separates premium automotive and grid storage buyers willing to absorb solid-state development premiums from price-sensitive consumer electronics assemblers optimizing bill-of-materials targets.
- Automotive:Electric vehicle platforms from Chinese OEMs and Japanese premium marques drive cylindrical and prismatic format demand. Samsung SDI supplies South Korean automakers under MFDS-KATS coordinated certification frameworks.
- Energy Storage:Multi-hour grid systems for renewable integration command the steepest margin pools. South Korean developers contract lithium iron phosphate variants under MFDS safety protocols for utility-scale deployment.
- Consumer Electronics:Smartphone and laptop manufacturers specify pouch cells with compressed energy density requirements. Procurement leverage concentrates with Foxconn and Pegatron assembly platforms in Vietnam and Indonesia.
- Industrial:Forklift electrification and uninterruptible power systems favor lead acid for capital cost sensitivity. China's MIIT carbon intensity disclosure rules are accelerating lithium substitution in heavy material handling.
Automotive commands revenue concentration through pack-scale contracts. Energy Storage climbs the fastest as METI and MFDS subsidy frameworks expand absolute capacity deployment.
Technology:
Application maturity separates mass-manufactured rechargeable liquid-electrolyte formats from pre-commercial solid-state architectures attracting development capital toward dendrite suppression.
- Rechargeable:Lithium-ion liquid electrolyte configurations dominate manufacturing scale across Fujian and Sichuan production clusters. Recycling compliance under China's GB standards imposes documentation burdens cell producers must integrate.
- Solid State:Sulfide-based electrolytes achieve ionic conductivities matching liquid counterparts while eliminating thermal runaway risk. Japan's METI subsidizes pilot line qualification for premium electric vehicle integration.
- Non-rechargeable:Primary alkaline and lithium metal formats serve medical device and defense applications requiring shelf stability. Procurement volumes remain constrained against rechargeable substitution economics.
- Fuel Cell:Hydrogen proton exchange membrane systems for heavy trucking pilot programs in Japan and South Korea. METI hydrogen roadmap funding supports stationary and mobility demonstration projects.
Rechargeable formats dominate installed capacity. Solid State gains share fastest through METI-backed pilot manufacturing and automotive qualification timelines.
Application:
Geography concentrates electric vehicle demand in China's coastal provinces and Japan's industrial corridors, while renewable energy applications distribute across South Korean and Australian grid interconnection zones.
- Electric Vehicles:Commercial logistics fleets and ride-hailing platforms in China negotiate cathode-to-pack contracts with volume floors. MIIT dual carbon enforcement compresses procurement cycles toward standardized high-capacity formats.
- Renewable Energy:Solar and wind developers across South Korea contract multi-hour storage under MFDS certification. Grid stabilization revenue models favor four-to-eight hour discharge duration specifications.
- Mobile Devices:Smartphone and tablet manufacturers specify energy density-optimized pouch cells. Assembly concentration in Vietnam and Indonesia creates procurement leverage for cylindrical format alternatives.
- Power Tools:Cordless construction equipment demands high-rate discharge cylindrical cells. Professional-grade tool manufacturers in Japan specify premium formats with extended cycle life warranties.
Electric Vehicles leads by absolute capacity procurement. Renewable Energy shows the steepest expansion trajectory through METI and MFDS utility-scale incentive structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet operators and grid developers concentrate procurement power across the Asia-Pacific, reshaping supplier relationships toward direct cathode-to-pack contracts with volume-adjustment clauses tied to lithium carbonate indices.
China
Commercial logistics electrification and ride-hailing fleet mandates drive cell demand through standardized high-capacity formats. MIIT enforces GB standards for blockchain-based recycling traceability across cathode material supply chains. Fujian and Sichuan production clusters host integrated cathode-to-pack manufacturing facilities capturing cost advantages at scale.
Japan
Premium electric vehicle platforms and hybrid vehicle residual demand sustain cylindrical and prismatic format procurement. METI subsidizes domestic lithium refining and solid-state pilot lines under battery supply chain resilience programs. Kanto and Kansai industrial corridors concentrate sulfide-based electrolyte qualification activities for 2027 model year integration.
South Korea
Multi-hour grid storage contracts and automotive OEM supply agreements drive lithium iron phosphate and premium cylindrical cell demand. MFDS coordinates battery certification with KATS automotive homologation requirements. Seoul Capital Area and Busan-Ulsan clusters house export-oriented cell manufacturing serving both domestic and Chinese market access.
India
Two-wheeler electrification and unorganized automotive service sector replacement cycles sustain lead acid demand while PLI thresholds accelerate lithium substitution. BIS adopts UN 38.3 testing protocols for transport safety certification. Maharashtra and Gujarat assembly markets attract cathode-to-pack integrators seeking localization compliance for government procurement.
Australia
Grid interconnection zones for renewable integration and mining sector electrification pilot programs drive stationary storage demand. The national energy regulator coordinates storage dispatch rules with state-level renewable targets. Western Australia and Queensland host lithium concentrate refining investments feeding Asian cell production clusters.
Asia-Pacific Battery Market Vendor Landscape
Player mix skews toward integrated cathode-to-pack manufacturers and captive-demand automotive suppliers, creating a tiered structure where scale advantages concentrate procurement leverage. Three archetypes dominate: gigafactory-scale cell producers with backward integration into refining, automotive conglomerates with captive battery divisions, and premium cylindrical specialists serving luxury vehicle platforms. Competitive moves center on capacity expansion in low-energy-cost provinces and strategic partnerships securing lithium concentrate offtake.
Among China-based producers, Contemporary Amperex Technology Co., Ltd. occupies a position exemplifying integrated cathode-to-pack manufacturing archetypes, while BYD Company Limited represents captive-demand structures through automotive and monorail division anchoring. Samsung SDI sits within the premium-tier vector for South Korean fabricators, qualifying cylindrical formats under MFDS-KATS coordinated certification frameworks. These three entities collectively illustrate the geographic and structural segmentation defining competitive positioning across the region.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Ltd. (CATL) |
| BYD Company Limited |
| LG Energy Solution |
| Samsung SDI |
| Panasonic Holdings Corporation |
| SK Innovation |
| GS Yuasa Corporation |
| EnerSys |
| EVE Energy Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Silicon-graphite composite anode substitution for pure graphite configurations is simultaneously shifting procurement geography toward Australian and Brazilian metallurgical-grade silicon suppliers and compressing margin structures across high-energy-density cell tiers. This input transition forces pack assemblers to renegotiate cathode-to-pack contracts with lithium carbonate indexation clauses that transfer commodity volatility risk downstream to fleet operators.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate procurement between Chinese gigafactories and commercial logistics fleets. Price differentiation separates GB-certified automotive-grade cells from industrial backup power variants lacking MIIT traceability documentation. Pricing pressure intensifies in the lead acid replacement segment as BIS-adopted UN 38.3 certification costs deter informal sector assemblers. Grid developers exhibit lowest price sensitivity, absorbing solid-state development premiums under METI subsidy frameworks.
Supply Chain Analysis
China and South Korea anchor cathode material refining and cell manufacturing across Fujian, Sichuan, and Seoul Capital Area production clusters. The regional value chain draws from Australian lithium concentrate, Indonesian nickel matte, and Chilean lithium carbonate feedstocks. Single-source vulnerability concentrates in Chinese Fujian province NMC oxide capacity. Distribution runs through direct cathode-to-pack agreements with fleet operators, bypassing traditional tiered wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific battery market constitutes a high-growth disruption where solid-state sulfide electrolyte qualification and China's blockchain-based recycling traceability mandates are compressing the competitive window for liquid-electrolyte incumbents.
For Market Incumbents: Secure captive lithium concentrate offtake from Australian and Chilean upstream assets before spot market tightness accelerates. Defend against cylindrical format specialists by accelerating prismatic cell certification under MFDS-KATS coordinated frameworks. Prioritize backward integration into NMC precursor refining to offset cathode material margin compression.
For New Entrants and Emerging Players: Lead with lithium iron phosphate assembly for India's two-wheeler electrification under PLI localization thresholds. Vietnam and Indonesian logistics fleets remain underpenetrated relative to Chinese saturation. Establish cathode-to-pack partnerships with regional ride-hailing platforms seeking volume-adjusted pricing structures.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier pack assemblers lacking GB recycling traceability infrastructure. Long-term viability favors solid-state pilot line operators with METI qualification timelines and sulfide electrolyte deposition capabilities. Watch for BIS enforcement accelerating lithium substitution in India's unorganized automotive service sector.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | Australian concentrate offtake secures supply certainty under China's dual carbon enforcement timelines. |
| Solid-State Pilot Line Qualification | METI subsidies accelerate sulfide electrolyte manufacturing for premium electric vehicle platform integration. |
| Blockchain Traceability Implementation | GB standard compliance enables market access for cathode material suppliers serving Chinese gigafactories. |
| PLI Localization Assembly | Maharashtra and Gujarat production thresholds unlock government procurement for lithium substitution in two-wheelers. |
| Direct Fleet Supply Agreements | Volume-indexed contracts with logistics operators compress pricing cycles toward standardized high-capacity formats. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with cell manufacturing executives, cathode material procurement leads, fleet electrification managers, and grid storage project developers. Secondary validation drew from MIIT GB standard filings, MFDS certification registries, lithium carbonate trade data, and METI subsidy disbursement records. Bottom-up cell shipment tallies triangulated against top-down energy storage deployment forecasts.
The projection horizon spans product type, end user, technology, and application dimensions across country-level regulatory clusters. CAGRs were derived from segment-level capacity buildout trajectories and substitution elasticity modeling. Key inputs include commercial fleet electrification mandates under China's dual carbon goals and solid-state manufacturing yield assumptions from METI-backed pilot line disclosures.
The analysis sits within stated boundaries; outcomes outside sustained lithium carbonate supply expansion or accelerated solid-state yield improvements would require recalibration. Forecasts reflect documented assumptions regarding cathode material refining capacity commissioning and recycling compliance cost trajectories. Recalibration cycles align with material shifts in MIIT enforcement intensity and METI subsidy program extensions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
North America Consumer Battery Market
Batteries
Nimh Battery Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Battery Materials Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Redox Flow Battery Market
Batteries
Battery Cell Market
Batteries
West Africa Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Breathing Battery Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Japan Battery Market
Batteries
Solid-State Batteries for Electric Vehicles Market
Batteries
Zinc Carbon Battery Market