
 Lithium Solid-State Battery Market | 2026-2036
Lithium Solid-State Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Solid-State Battery Market Intelligence
The EU Battery Regulation is consolidating the cost-of-entry calculus for solid-state cell manufacturers by mandating recycled-content thresholds and supply-chain due diligence. Toyota Motor Corporation leverages its three-decade patent portfolio in sulfide electrolytes to sustain manufacturing readiness ahead of commercial launches. Samsung SDI Co., Ltd. competes through oxide-based platforms designed for high-voltage cathode pairing. Solid Power, Inc. anchors its position via in-house production of lithium-metal anodes and sulfide electrolyte films.
Lithium solid-state batteries replace flammable liquid electrolytes with ceramic, glass, or polymer ionic conductors to achieve energy densities above 400 Wh/kg and eliminate thermal runaway risks. Bulk-type cells dominate prototype roadmaps for electric vehicles due to scalable roll-to-roll processing, while thin-film architectures occupy niche medical and aerospace applications where form-factor constraints override cost sensitivity. Sulfide-based technology leads R&D investment for its room-temperature ionic conductivity, though oxide-based platforms differentiate through air stability and simpler dry-room handling. Polymer-based segments navigate lower energy-density ceilings by targeting consumer electronics manufacturers seeking incremental safety gains.
FDA scrutiny of implantable medical devices and NHTSA crash-test protocols for electric vehicle battery packs shape validation requirements for solid-state formats entering regulated end-uses. The EU Green Deal's critical raw-material benchmarks and China's dual carbon goals from MEE constrain cathode chemistry choices and carbon-intensity thresholds. Stakeholders must monitor which electrolyte technology achieves automotive qualification first, as this determines which manufacturing footprint and supplier base captures the initial wave of OEM sourcing commitments.
Market Dynamics
The sulfide-versus-oxide electrolyte race is compressing qualification timelines as automotive OEMs pre-source pilot volumes before chemistry dominance crystallizes. This technology bifurcation forces manufacturers to place parallel bets on incompatible processing equipment.
Growth Catalysts
- EU Battery Regulation recycled-content mandates:The regulation's carbon-footprint thresholds and due diligence requirements are accelerating OEM qualification of solid-state cells over incumbent lithium-ion packs.
- Electric vehicle platform electrification:Premium automotive OEMs are replacing conventional battery architectures with solid-state designs to achieve energy density above 400 Wh/kg and eliminate thermal propagation risks.
- Germany manufacturing cluster concentration:BMW and Volkswagen pre-sourcing commitments in Bavaria and Lower Saxony are pulling sulfide electrolyte supply chains toward Central European production bases.
Market Restraints
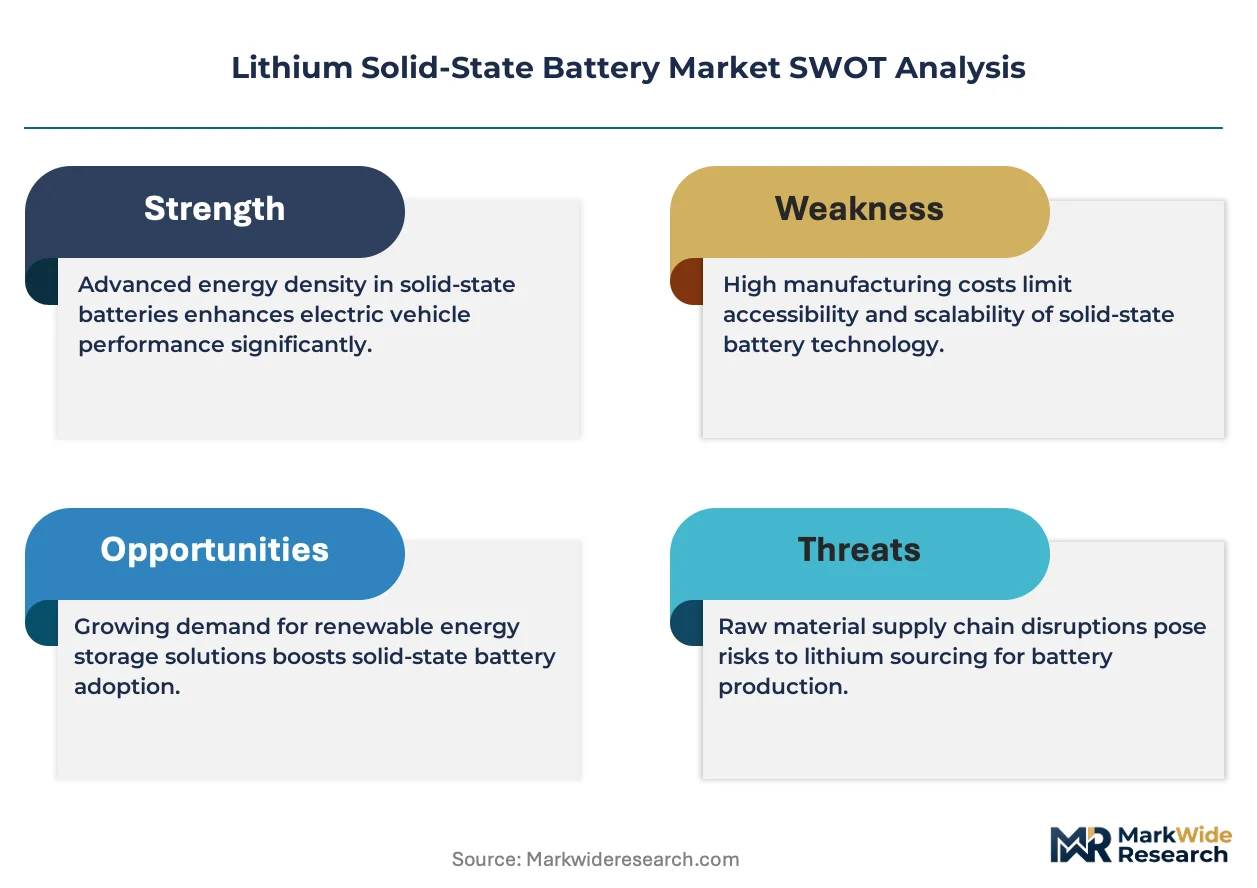
- Lithium metal anode cost volatility:Thin lithium foil production remains concentrated among Japanese and Korean suppliers, exposing cell manufacturers to input price swings and allocation constraints.
- Sulfide electrolyte air stability limitations:Moisture-sensitive processing requires sub-ppm dry room infrastructure, inflating capital intensity versus oxide-based alternatives.
- GB standards compliance friction:China's safety certification protocols for new energy vehicles impose additional validation cycles that extend time-to-revenue for foreign cell suppliers.
Strategic Opportunities
- Aviation propulsion electrification:Thin-film solid-state architectures are penetrating regional aircraft battery systems where form-factor constraints and safety premiums override cost sensitivity.
- Medical implant power sources:FDA Class III device pathways favor solid-state formats for implantable neurostimulators and drug pumps requiring decade-plus service life.
- Japan METI battery supply chain reshoring incentives:Domestic manufacturing subsidies for next-generation cell production are attracting sulfide electrolyte pilot lines to Kyushu and Kansai industrial corridors.
Industry Challenges
- Multiphysics simulation talent scarcity:Solid-state cell design requires integrated ionic-electronic-thermal modeling expertise that outpaces current university pipeline output.
- Interface engineering certification delays:Cathode-electrolyte interphase stability validation under NHTSA crash-test protocols extends automotive qualification timelines beyond liquid electrolyte benchmarks.
- Roll-to-roll manufacturing yield ramp:Sulfide electrolyte film casting defect rates during scale-up compress margin structures before volume learning curves materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Solid-State Battery Market |
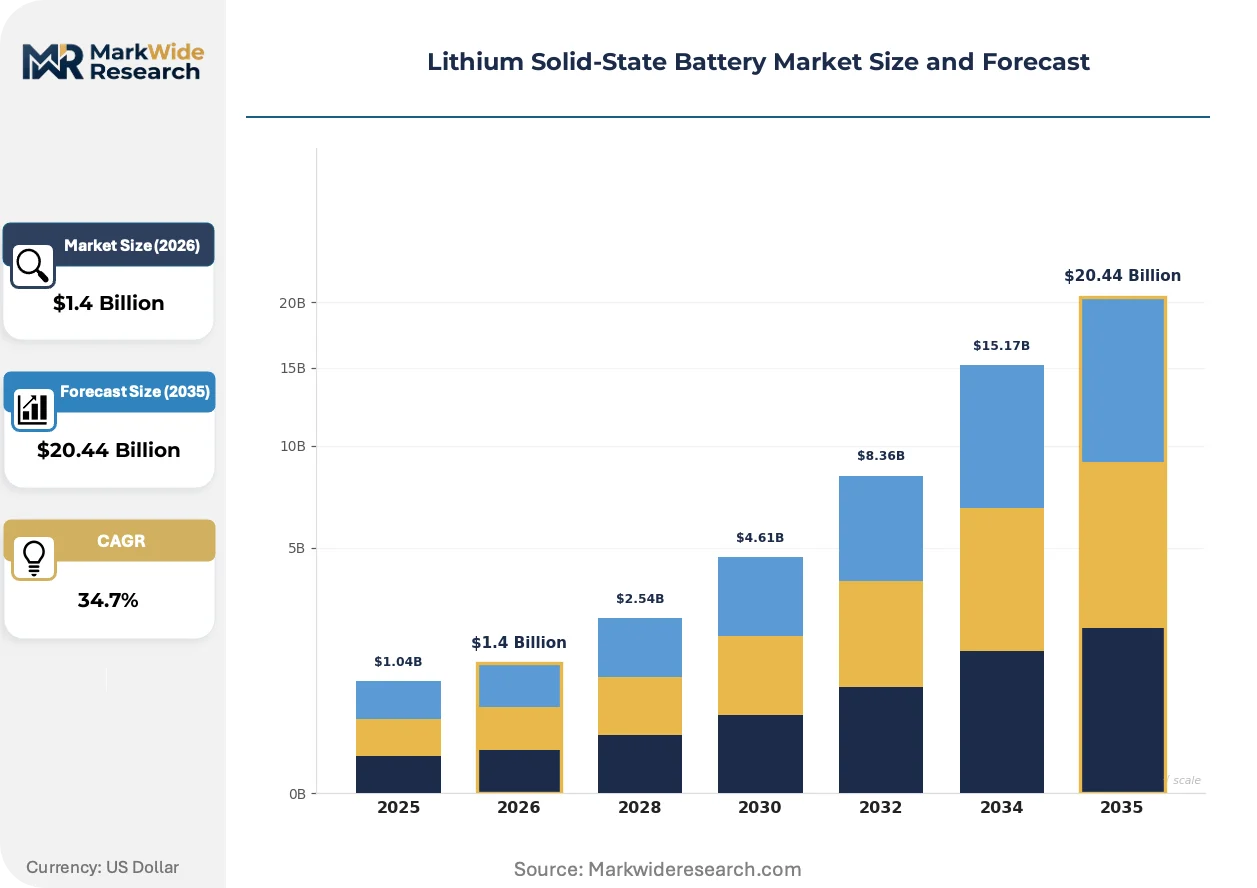
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $20.44 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk-Type, Thin-Film, Tubular, Sheet, Composite Technology: Sulfide-Based, Oxide-Based, Polymer-Based, Halide-Based, Garnet-Based Application: Electric Vehicles, Consumer Electronics, Aerospace, Military, Energy Storage Systems End User: OEMs, Energy Providers, Defense Contractors, Electronics Manufacturers, Aviation Companies |
| Companies Covered | QuantumScape Corporation, Solid Power, Inc., ProLogium Technology Co., Ltd., Factorial Energy, Blue Solutions, CATL, Toyota Motor Corporation, Ilika plc, Samsung SDI Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Solid-State Battery Market Strategic Shifts & Innovations
Processing equipment and materials science advances are converging to enable pilot-scale production of cells previously confined to laboratory environments. The transition from batch to continuous manufacturing is rewriting cost structures across the value chain.
Sulfide glass-ceramic composite electrolytes are rewriting the manufacturability calculus for room-temperature ionic conductors. Automotive OEMs in Germany and Japan are qualifying these materials for 2027 platform launches. The technology is rewriting the geographic distribution of pilot production capacity toward dry-room infrastructure clusters.
The EU Green Deal's critical raw-material benchmarks are forcing cathode chemistry selections toward nickel-reduced or manganese-rich formulations. Cell manufacturers must document supply-chain due diligence across extraction, refining, and active material synthesis. European OEM sourcing committees are most affected, responding by pre-qualifying dual-source cathode suppliers outside traditional cobalt-dominant channels.
After-sales service unbundling is separating battery health monitoring from vehicle maintenance contracts. Fleet operators and leasing companies are procuring solid-state packs with standalone performance guarantees decoupled from OEM service networks. This pattern is most visible in German commercial vehicle segments, where independent battery asset managers are emerging as primary procurement decision-makers.
Lithium Solid-State Battery Market Segmentation
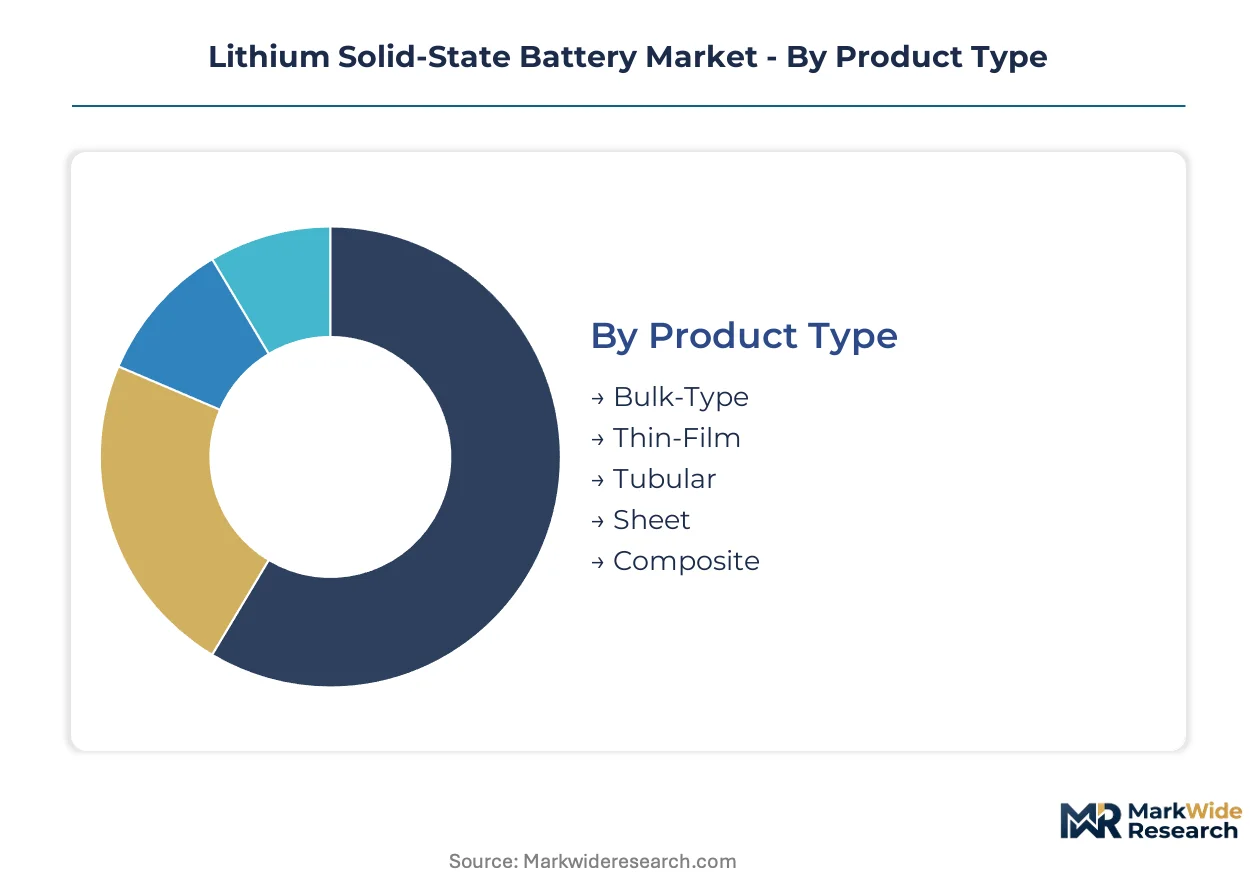
Segmentation in the Lithium Solid-State Battery Market reveals how capital deployment, technical risk, and customer procurement power concentrate across incompatible manufacturing footprints. Each dimension carries distinct qualification timelines and margin structures that determine competitive positioning.
Product Type:
Capital intensity varies sharply across form factors, with dry-room infrastructure requirements and tooling amortization driving break-even thresholds.
- Bulk-Type:Roll-to-roll processed cells with sulfide or oxide electrolyte layers laminated between electrodes. German automotive OEMs in Bavaria and Lower Saxony are pre-sourcing pilot volumes for 2027 platform launches, though defect rates during scale-up compress early margins.
- Thin-Film:Vacuum-deposited ceramic electrolytes on micrometer-scale substrates. Regional aircraft battery systems and implantable medical devices in the US FDA pathway absorb output where safety premiums override cost sensitivity.
- Tubular:Cylindrical architectures suited for thermal management in confined spaces.
- Sheet:Flexible substrates targeting consumer electronics form-factor constraints.
- Composite:Hybrid structures combining polymer mechanical compliance with ceramic ionic conductivity.
Most installed capacity flows through Bulk-Type. Expansion is steepest in Thin-Film.
Technology:
Process chemistry choices lock manufacturers into irreversible equipment commitments and incompatible supply chains.
- Sulfide-Based:Glass-ceramic composites achieving room-temperature ionic conductivity above 10 mS/cm. Japan METI subsidies are pulling pilot lines toward Kyushu and Kansai industrial corridors, though sub-ppm moisture control inflates capital intensity versus alternatives.
- Oxide-Based:Air-stable ceramics enabling simpler dry-room handling and high-voltage cathode pairing. Samsung SDI Co., Ltd. anchors development for automotive platforms where manufacturing yield stability outweighs conductivity advantages.
- Polymer-Based:Lower energy-density ceilings accepted by consumer electronics manufacturers seeking incremental safety gains without process retooling.
- Halide-Based:Emerging chemistry with enhanced oxidation stability for high-voltage operation.
- Garnet-Based:Oxide structures with lithium-metal compatibility but high-temperature sintering requirements.
Volume leadership sits with Sulfide-Based. Technology transition risk is highest in Halide-Based.
Application:
End-use qualification protocols create divergent margin profiles and customer concentration risk.
- Electric Vehicles:NHTSA crash-test validation and OEM platform integration cycles extending beyond liquid electrolyte benchmarks. EU Battery Regulation carbon-footprint mandates are accelerating qualification timelines for premium German and French automotive platforms.
- Aerospace:FAA certification for regional aircraft propulsion systems where form-factor constraints and thermal runaway elimination justify cost premiums.
- Consumer Electronics:Incremental safety upgrades for smartphones and wearables with shorter procurement cycles.
- Military:Defense contractor specifications prioritizing supply security over unit economics.
- Energy Storage Systems:Grid-scale installations with extended cycle life requirements.
Procurement scale concentrates in Electric Vehicles. Margin premiums are highest in Aerospace.
End User:
Customer type determines contract structure, performance guarantee terms, and after-sales service unbundling patterns.
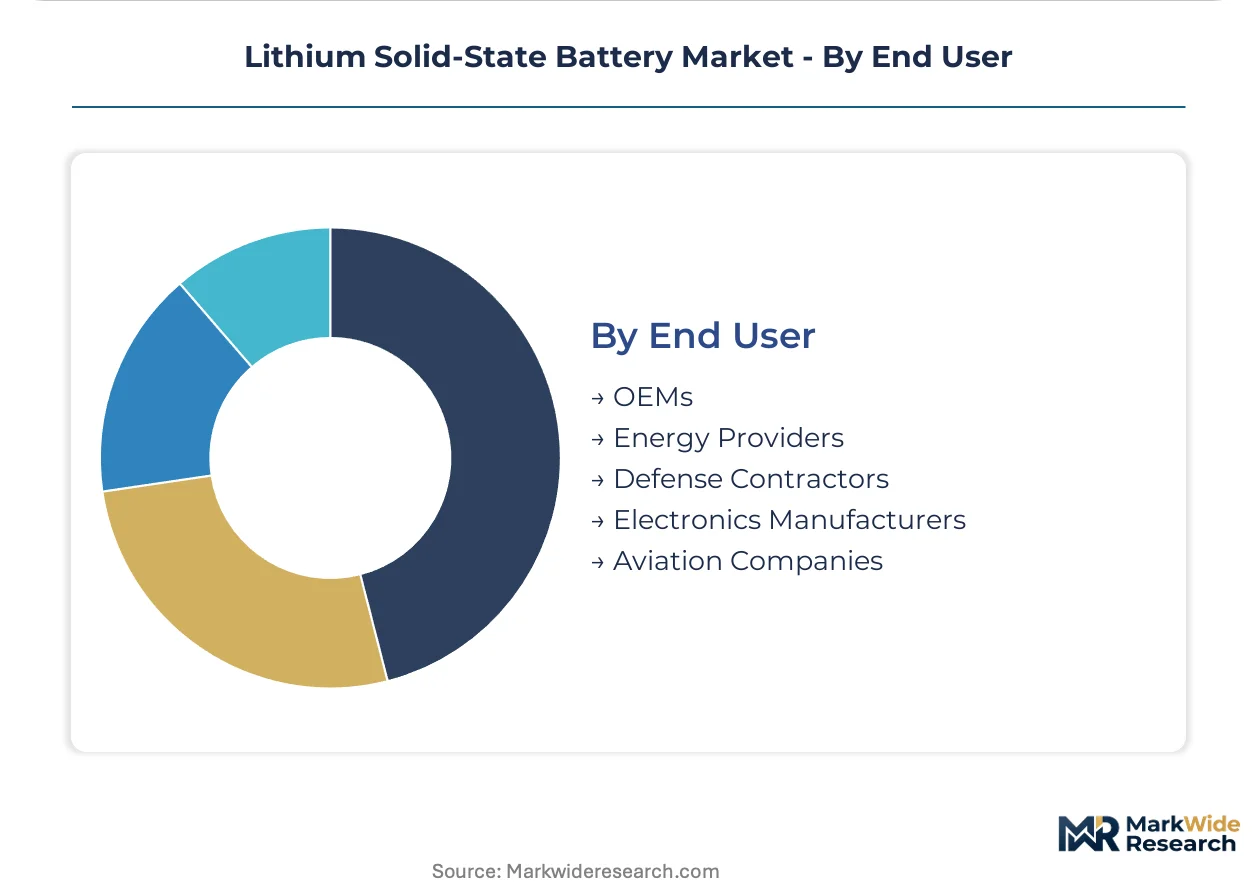
- OEMs:Automotive and aviation manufacturers integrating cells into platform-specific pack architectures with decade-plus service life requirements. German commercial vehicle segments are seeing independent battery asset managers emerge as primary procurement decision-makers.
- Defense Contractors:US Department of Energy and NATO-aligned programs with classified supply chain audit requirements.
- Energy Providers:Utility procurement with standalone performance guarantees decoupled from OEM service networks.
- Electronics Manufacturers:Consumer device brands with annual volume commitments and rapid product refresh cycles.
- Aviation Companies:Regional carriers and urban air mobility operators with weight-critical specifications.
Contract duration is longest with OEMs. Payment terms are most favorable with Defense Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solid-state battery development traces its industrial lineage to Japan's 1990s sulfide electrolyte research programs, with commercial scaling now dispersing across German automotive corridors, Chinese manufacturing hubs, and US venture-backed clusters.
Germany
BMW and Volkswagen pre-sourcing commitments anchor demand for 2027 platform launches. The EU Battery Regulation's carbon-footprint thresholds and recycled-content mandates compress qualification timelines for sulfide-based cell suppliers. Bavaria and Lower Saxony host pilot production facilities pulling electrolyte supply chains toward Central European dry-room infrastructure clusters.
China
CATL and domestic OEMs drive volume demand for next-generation cell architectures. GB standards on new energy vehicle safety impose additional validation cycles that extend time-to-revenue for foreign suppliers. Yangtze River Delta manufacturing bases concentrate oxide-based platform development for high-voltage cathode pairing.
Japan
Toyota Motor Corporation leverages three decades of sulfide electrolyte patents to sustain manufacturing readiness. METI battery supply chain reshoring incentives attract pilot production lines to Kyushu and Kansai industrial corridors. Domestic subsidies target next-generation cell production for automotive export platforms.
United States
Venture-backed developers scale thin-film architectures for aviation and medical applications where safety premiums override cost sensitivity. NHTSA crash-test protocols for electric vehicle battery packs shape validation requirements for solid-state formats entering regulated end-uses. California and Massachusetts clusters concentrate multiphysics simulation talent for cathode-electrolyte interphase engineering.
South Korea
Samsung SDI Co., Ltd. competes through oxide-based platforms designed for high-voltage cathode pairing. Domestic OEM sourcing committees prioritize manufacturing yield stability over conductivity advantages. Seoul Capital Area research parks host interface engineering programs targeting automotive qualification benchmarks.
Lithium Solid-State Battery Market Key Industry Players
The competitive structure tilts toward technology-differentiated specialists rather than diversified conglomerates. Player concentration remains moderate, with sulfide-oxide chemistry bifurcation preventing single-dominant architectures. Two strategic archetypes define positioning: electrolyte-materials specialists controlling core intellectual property, and integrated cell manufacturers securing OEM platform commitments. Parallel capacity expansion and strategic pre-sourcing partnerships constitute the dominant competitive moves as automotive qualification timelines compress.
Within the electrolyte-materials tier, QuantumScape Corporation and Solid Power, Inc. exemplify venture-scaled developers pursuing sulfide-based automotive qualification. Samsung SDI Co., Ltd. occupies a position among diversified electronics conglomerates leveraging oxide-platform manufacturing stability. Toyota Motor Corporation anchors the incumbent automotive archetype, converting decades of patent accumulation into production readiness ahead of commercial launches.
| Leading Market Players |
|---|
| QuantumScape Corporation |
| Solid Power, Inc. |
| ProLogium Technology Co., Ltd. |
| Factorial Energy |
| Blue Solutions |
| CATL |
| Toyota Motor Corporation |
| Ilika plc |
| Samsung SDI Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Roll-to-roll processing scale-up is compressing unit economics while concentrating supply chain leverage among dry-room infrastructure owners in Germany and Japan. This manufacturing transition simultaneously elevates capital barriers for new entrants and shifts pricing power toward electrolyte-materials specialists with captive lithium-metal anode production.
Pricing Analysis
Battery health monitoring unbundling from vehicle service contracts is restructuring pricing models across German commercial vehicle segments. Contract structures now stratify across premium, standard, and economy tiers based on performance guarantee duration and cathode chemistry certification grade. Cost compression in sulfide-based cell production is intensifying because sub-ppm dry-room infrastructure amortization dominates fixed costs. Fleet operators and leasing companies exhibit highest price sensitivity, while aviation OEMs absorbing thin-film architectures show least.
Supply Chain Analysis
Specialized freight logistics for moisture-sensitive sulfide electrolytes are inflating landed costs and constraining supplier radius to regional dry-room clusters. Lithium foil production concentrates in Japan and South Korea, with cathode active materials sourcing from Chinese and Indonesian refining bases. Single-source vulnerability runs through Japanese lithium-metal anode suppliers. Distribution feeds from integrated cell manufacturers directly to automotive OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in solid-state batteries rests on sulfide electrolyte yield improvement and premium-tier qualification for aviation propulsion systems. Defect rate reduction during roll-to-roll scale-up is the primary cost-down driver enabling sustainable profitability.
For Market Incumbents: Anticipate oxide-based platform competition from Samsung SDI and Korean suppliers by securing exclusive lithium-metal anode offtake agreements with Japanese producers. Defend position through backward integration into sulfide glass-ceramic composite electrolyte synthesis and accelerated NHTSA crash-test validation timelines. Priority lever centers on cathode-electrolyte interphase engineering talent retention.
For New Entrants and Emerging Players: EU Battery Regulation recycled-content mandates in Germany open a window for qualified sulfide-cell suppliers to capture BMW and Volkswagen pre-sourcing commitments. Target thin-film architectures for FDA Class III medical implants where safety premiums override manufacturing scale disadvantages. Go-to-market angle emphasizes decade-plus service life guarantees decoupled from OEM maintenance networks.
For Investors and Strategic Acquirers: Valuations sit cheapest among oxide-platform specialists with automotive qualification timelines trailing sulfide leaders. Long-term viability over the next decade hinges on which electrolyte chemistry achieves first-mover OEM platform integration. Acquisition target archetype: electrolyte-materials specialists with patent-protected glass-ceramic formulations. Signal to monitor: Japan METI subsidy disbursement rates for Kyushu pilot production lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Sulfide Electrolyte Pilot Line Expansion | German automotive OEM pre-sourcing commitments in Bavaria anchor demand concentration. |
| Lithium-Metal Anode Backward Integration | In-house foil production insulates cell manufacturers from Japanese supplier allocation constraints. |
| Aviation Thin-Film Certification | FAA pathway for regional aircraft propulsion unlocks margin premiums above automotive benchmarks. |
| EU Battery Regulation Compliance Investment | Recycled-content documentation systems satisfy BMW and Volkswagen sourcing committee requirements. |
| Cathode-Electrolyte Interphase R&D Partnership | Multiphysics simulation collaboration with Massachusetts technical clusters accelerates automotive qualification. |
Research Approach
Direct dialogue with solid-state cell engineering directors, automotive OEM platform procurement leads, dry-room infrastructure operators, and sulfide electrolyte materials scientists grounded qualitative findings. Secondary validation drew from SEC 10-K filings of listed battery developers, Japan METI subsidy disbursement records, EU Battery Regulation implementation guidance, and NHTSA battery safety test protocols. Bottom-up cell production capacity modeling triangulated against top-down automotive platform electrification forecasts.
Top-down demand estimation from electric vehicle production schedules and aviation electrification roadmaps cross-checked bottom-up electrolyte materials supply capacity. Segmentation modeling spanned product type, technology chemistry, application end-use, and customer archetype across the projection horizon. CAGRs derived from learning curve assumptions for roll-to-roll manufacturing yield improvement and lithium-metal anode cost trajectories. Forecast inputs incorporated EU Green Deal critical raw-material benchmarks and China GB standards compliance friction.
Revisions become necessary when sulfide electrolyte air stability breakthroughs materialize or automotive OEM platform launch schedules shift. Forecasts reflect assumptions regarding dry-room infrastructure buildout rates and cathode chemistry selection patterns. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Automotive 48-Volt Lithium Ion Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
EV All-Solid-State Battery Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Ion Energy Accumulator Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Silicon Anode Battery Market