
 Elastic Battery Binders Market | 2026-2036
Elastic Battery Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Elastic Battery Binders Market Foresight
A capital-intensity divergence between players is unwinding as integrated petrochemical giants outspend specialty chemical challengers on polymer synthesis infrastructure. Arkema leverages its fluoropolymer heritage to dominate high-voltage cathode binder supply. Solvay anchors European demand through backward integration into PVDF precursor production. Zeon Corporation competes on synthetic rubber expertise adapted for silicon-anode compatibility.
Elastic battery binders are polymeric adhesion agents, typically fluorinated or elastomeric compounds with glass transition temperatures below minus 20 degrees Celsius, that mechanically stabilize active material layers during lithium-ion charge cycling. Their primary purpose is accommodating electrode volume expansion, particularly in silicon-blend anodes where particle swelling exceeds 300 percent. Water-based binders are capturing share fastest as OEMs eliminate N-methyl-2-pyrrolidone solvent recovery costs. Polymer binders still occupy the largest margin pool due to formulation customization for solid-state cell architectures. Electric vehicle applications lead volume offtake as cylindrical and prismatic cell formats multiply.
FDA scrutiny of fluoropolymer biocompatibility in wearable energy devices intersects with EPA reporting obligations on per- and polyfluoroalkyl substance releases from binder manufacturing. REACH registration requirements in Europe and China's MEE enforcement on volatile organic compound emissions are reshaping formulation chemistry roadmaps. Battery manufacturers must decide whether captive binder synthesis or long-term supply agreements better secure qualification timelines as cell designs proliferate.
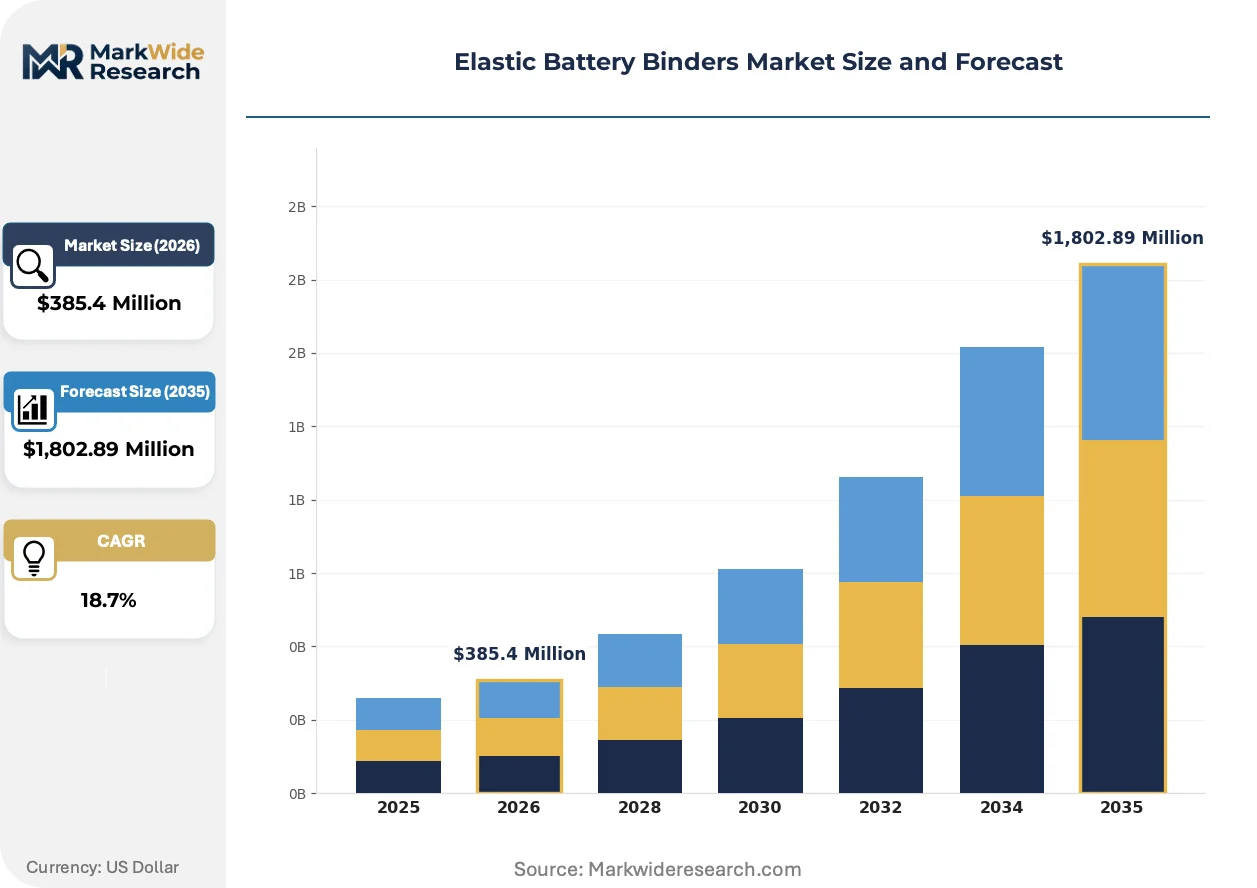
Market Dynamics
Water-based binder formulations are compressing solvent recovery infrastructure requirements as electric vehicle cell designs proliferate, forcing specialty chemical suppliers to retool polymer synthesis lines or cede position to integrated petrochemical operators with captive fluoropolymer capacity.
Growth Catalysts
- China's dual carbon targets:NMPA accelerated approval timelines for water-based electrode formulations reduce qualification cycles for domestic battery manufacturers expanding silicon-anode production.
- Silicon-blend anode penetration:Automotive OEMs specifying binders accommodating 300 percent particle swelling during charge cycling are pulling elastomeric polymer demand ahead of conventional PVDF.
- South Korean battery cluster concentration:LG Chem and SK On supply chain localization requirements are generating dedicated binder qualification programs for cylindrical and prismatic cell formats.
Market Restraints
- Fluoropolymer precursor supply concentration:Backward integration into vinylidene fluoride monomer production sits with a limited set of integrated chemical conglomerates, constraining independent binder specialists.
- REACH registration cost burden:ECHA compliance timelines for novel polymer chemistries extend 18-24 months, freezing formulation innovation pipelines for mid-cap European entrants.
- Acrylic binder performance ceiling:Water-based acrylic alternatives exhibit inferior adhesion strength above 4.3V cathode potentials, limiting substitution in high-voltage cell architectures.
Strategic Opportunities
- Solid-state cell architecture transition:Polymer binder customization for sulfide and oxide electrolyte interfaces represents uncaptured margin pools as prototype lines scale toward pilot production.
- India's PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives are creating first-mover qualification windows for binder suppliers establishing local technical service presence.
- EU F-Gas Regulation phase-down:Fluoropolymer manufacturing process emissions constraints are accelerating process innovation toward closed-loop synthesis systems with patentable IP positions.
Industry Challenges
- Polymer-electrolyte interface characterization:Solid-state cell developers lack standardized test protocols for binder compatibility, forcing bilateral qualification agreements that fragment technical roadmaps.
- Silicon-anode binder IP thickets:Patent estates covering carboxymethyl cellulose and polyacrylic acid composite formulations are generating licensing disputes between Japanese synthetic rubber specialists and Korean battery material suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastic Battery Binders Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Binders, Solvent-Free Binders, Water-Based Binders, Conductive Binders Application: Energy Storage, Electric Vehicles, Consumer Electronics, Industrial Applications End User: OEMs, Aftermarket Suppliers, Battery Manufacturers, Research Institutions Technology: Coating Techniques, Mixing Methods, Processing Techniques, Formulation Strategies |
| Companies Covered | Arkema, Solvay, Zeon Corporation, LG Chem, KUREHA CORPORATION, BASF SE, Daikin Industries, DuPont, The Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastic Battery Binders Market Shifts & Advancements
Formulation chemistry is pivoting toward solvent-free and aqueous systems as regulatory pressure on N-methyl-2-pyrrolidone emissions intersects with OEM cost reduction mandates, compressing the viable technology window for conventional fluoropolymer solutions.
Self-healing elastomeric binders incorporating dynamic covalent bonds are supplanting conventional thermoplastic fluoropolymers in silicon-dominant anode designs. Automotive cell manufacturers in Germany and South Korea are qualifying these materials for 2027 platform launches. The structural consequence is a margin squeeze on standard PVDF suppliers unable to license or develop crosslinking polymer architectures.
REACH authorization requirements for per- and polyfluoroalkyl substances are tightening disclosure thresholds for fluoropolymer binder imports into European battery gigafactories. ECHA enforcement is forcing reformulation roadmaps toward shorter-chain fluorinated compounds or fully fluorine-free alternatives. High-voltage cathode applications are most affected, with suppliers accelerating water-based acrylic and polyurethane hybrid development.
Long-term offtake agreements with fixed pricing mechanisms are displacing spot procurement for binder raw materials as battery manufacturers seek supply security amid polymer feedstock volatility. Tier-one cell producers in Japan and the United States are locking five-year contracts directly with vinylidene fluoride monomer producers. This behavior is most visible in cylindrical cell supply chains serving electric vehicle platforms with committed production schedules.
Elastic Battery Binders Market Segmentation
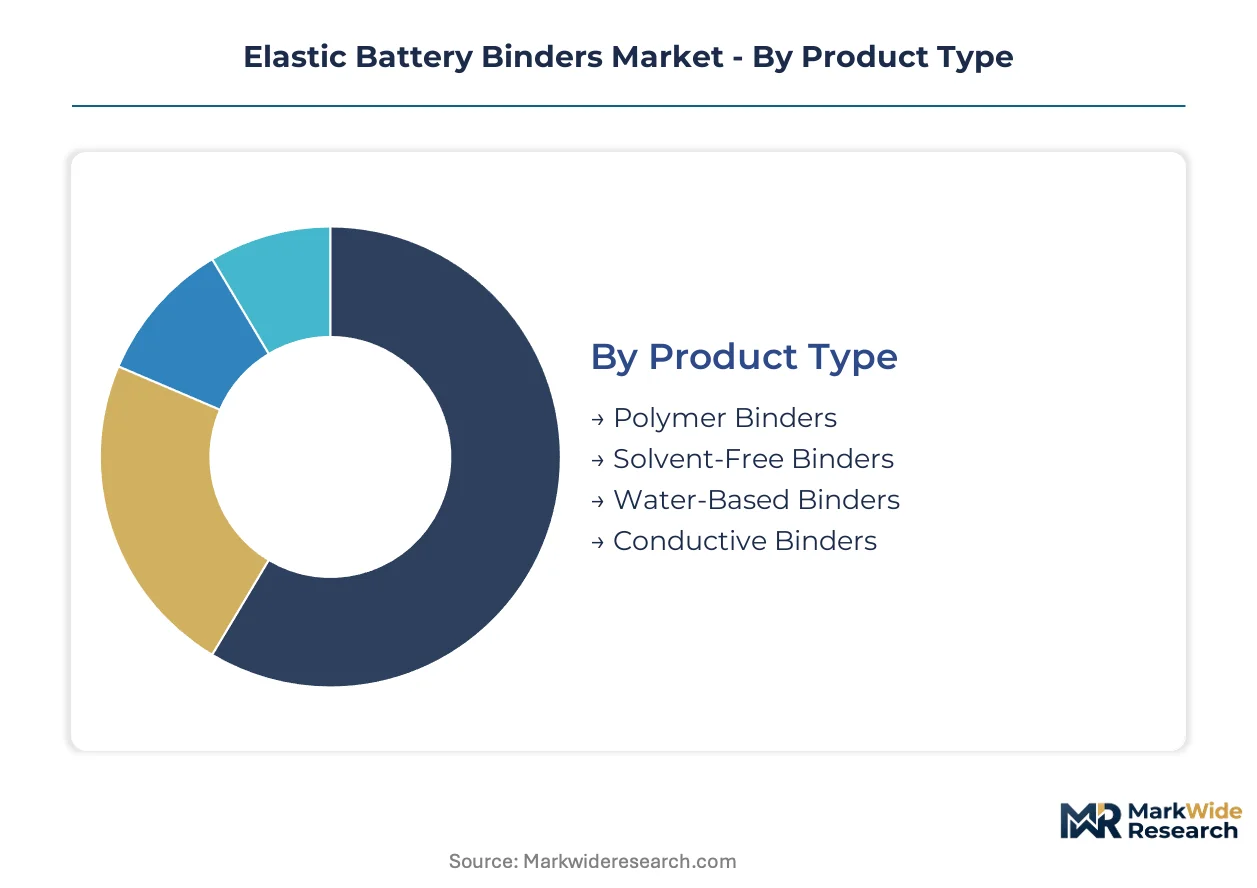
Elastic battery binders segment across formulation chemistry, end-use intensity, and manufacturing integration depth. Each dimension carries distinct margin profiles and qualification barriers that reshape procurement patterns as cell architectures evolve.
Product Type:
Water-based formulations face the most intense substitution pressure from solvent-free alternatives as N-methyl-2-pyrrolidone recovery costs collapse the economic case for conventional fluoropolymer solutions.
- Polymer Binders:Fluorinated and elastomeric compounds with sub-minus-20-degree Celsius glass transition temperatures anchor high-voltage cathode applications. Automotive OEMs in Germany and South Korea specify these materials for silicon-blend anodes where particle swelling exceeds 300 percent during charge cycling.
- Water-Based Binders:Acrylic and polyurethane dispersions eliminate solvent recovery infrastructure. China's NMPA accelerated approval timelines compress qualification cycles for domestic battery manufacturers expanding silicon-anode production lines.
- Solvent-Free Binders:Hot-melt and UV-curable systems target solid-state cell architectures.
- Conductive Binders:Carbon-black-loaded formulations address high-rate discharge applications.
Polymer binders anchor the volume base while water-based alternatives gain share at the steepest rate.
Application:
Cost tier stratification separates premium automotive specifications from commodity energy storage tenders, with qualification timelines stretching longest for electric vehicle platforms.
- Electric Vehicles:Cylindrical and prismatic cell formats multiply procurement volumes for elastomeric binders accommodating extreme electrode expansion. LG Chem and SK On supply chain localization requirements in South Korea generate dedicated qualification programs with fixed pricing mechanisms.
- Energy Storage:Grid-scale battery installations prioritize cost-minimized acrylic formulations over fluoropolymer performance. India's PLI scheme for advanced chemistry cells creates first-mover qualification windows for suppliers establishing local technical service presence.
- Consumer Electronics:Wearable devices face FDA scrutiny of fluoropolymer biocompatibility.
- Industrial Applications:Forklift and stationary power systems tolerate wider performance variance.
Electric vehicle applications command the premium tier while energy storage expands most quickly as grid deployment accelerates.
End User:
Customer type determines captive synthesis incentives versus long-term supply agreement preferences as battery manufacturers internalize polymer expertise.
- Battery Manufacturers:Tier-one cell producers in Japan and the United States lock five-year contracts directly with vinylidene fluoride monomer producers. This procurement behavior concentrates in cylindrical cell supply chains serving electric vehicle platforms with committed production schedules.
- OEMs:Automotive assemblers increasingly specify binder chemistries rather than delegating material selection. REACH registration requirements extend 18-24 months for novel polymer chemistries, freezing formulation innovation pipelines for mid-cap European entrants without captive synthesis capacity.
- Aftermarket Suppliers:Replacement cell producers compete on reformulation speed.
- Research Institutions:Prototype lines drive experimental binder qualification.
Battery manufacturers dominate procurement volume while OEMs capture specification authority fastest.
Technology:
Process maturity separates established coating infrastructure from emerging formulation strategies that reshape competitive barriers.
- Formulation Strategies:Self-healing elastomeric architectures incorporating dynamic covalent bonds supplant conventional thermoplastic fluoropolymers. Automotive cell manufacturers in Germany and South Korea qualify these materials for next-generation platform launches, squeezing margins on standard PVDF suppliers unable to license crosslinking polymer expertise.
- Processing Techniques:Extrusion and calendering parameters determine binder distribution uniformity. EU F-Gas Regulation phase-down constraints on fluoropolymer manufacturing process emissions accelerate closed-loop synthesis system development with patentable IP positions.
- Coating Techniques:Slot-die and comma coating methods dominate electrode fabrication.
- Mixing Methods:High-shear dispersion controls active material distribution.
Processing techniques anchor current production while formulation strategies attract R&D investment fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery manufacturers in South Korea and Japan accept premium pricing for fluoropolymer binders with guaranteed qualification timelines, while Chinese and Indian buyers drive hard bargains on water-based formulations where supplier switching costs remain low.
China
Domestic cell producers are scaling silicon-anode production lines at unprecedented speed. NMPA accelerated approval timelines for water-based electrode formulations compress qualification cycles from 24 months to under 12. The Yangtze River Delta cluster around Changzhou and Suzhou hosts the densest concentration of binder qualification programs serving CATL and BYD supply chains.
South Korea
LG Chem and SK On have imposed strict supply chain localization requirements on foreign binder suppliers. MFDS enforcement on volatile organic compound emissions from electrode manufacturing is pushing reformulation toward solvent-free alternatives. The Ulsan-Gwangju corridor anchors the country's battery material ecosystem with dedicated technical service centers from major polymer suppliers.
Germany
Automotive OEMs are specifying binder chemistries directly rather than delegating to cell producers. ECHA REACH registration requirements for novel polymer chemistries extend 18-24 months, freezing mid-cap European entrants without captive synthesis capacity. The Baden-Württemberg and Bavaria regions concentrate prototype qualification activity for 2027 electric vehicle platform launches.
United States
Tier-one cell producers are locking five-year contracts directly with vinylidene fluoride monomer producers to secure supply amid feedstock volatility. EPA reporting obligations on per- and polyfluoroalkyl substance releases from binder manufacturing are tightening disclosure thresholds. The Michigan-Ohio battery corridor and Texas gigafactory clusters represent the primary demand centers for cylindrical cell binders.
India
The PLI scheme for advanced chemistry cells is creating first-mover qualification windows for suppliers establishing local technical service presence. BIS certification requirements for imported battery materials add 6-9 months to market entry timelines. Gujarat and Tamil Nadu are emerging as the dominant sub-regions for domestic battery manufacturing investment.
Elastic Battery Binders Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on formulation customization and qualification speed. Integrated petrochemical conglomerates with captive fluoropolymer capacity control upstream vinylidene fluoride monomer supply, constraining independent binder specialists who must secure long-term feedstock agreements. Three archetypes populate the market: backward-integrated chemical giants, synthetic rubber specialists adapting elastomer expertise for battery applications, and regional formulation houses serving localized qualification programs. Dominant competitive moves include capacity expansion in high-voltage cathode binder production and strategic partnerships with solid-state cell developers for sulfide-electrolyte interface materials.
Within the integrated chemical tier, Arkema and Solvay occupy positions that exemplify divergent geographic anchoring strategies. Arkema leverages its fluoropolymer heritage to serve high-voltage cathode applications, while Solvay anchors European demand through upstream control over PVDF precursor production. Zeon Corporation represents the synthetic rubber specialist archetype, adapting elastomer expertise developed in tire manufacturing for silicon-anode compatibility requirements.
| Leading Market Players |
|---|
| Arkema |
| Solvay |
| Zeon Corporation |
| LG Chem |
| KUREHA CORPORATION |
| BASF SE |
| Daikin Industries |
| DuPont |
| The Lubrizol Corporation |
| Others |
Supply & Pricing Matrix
Captive fluoropolymer capacity among integrated petrochemical conglomerates creates scale thresholds that independent binder specialists cannot match, compressing price floors for water-based formulations while sustaining premiums on high-voltage cathode grades. This concentration simultaneously constrains feedstock access for mid-tier players and amplifies procurement leverage for battery manufacturers with committed cylindrical cell programs.
Pricing Analysis
After-sales technical service and qualification support generate lifetime value that exceeds raw material margins by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels separates automotive OEM-specified elastomeric binders from commodity acrylic dispersions serving grid storage tenders. Cost compression in water-based tiers is intensifying because Chinese domestic manufacturers are eliminating solvent recovery infrastructure entirely. Energy storage buyers exhibit highest price sensitivity, while German and South Korean automotive cell producers accept sustained premiums for guaranteed silicon-anode compatibility.
Supply Chain Analysis
Vinylidene fluoride monomer production chokepoints in China, Japan, and the United States tether global fluoropolymer binder output to a handful of integrated chemical operators. The supply chain draws from petroleum-derived feedstocks, specialized polymerization catalysts, and high-purity N-methyl-2-pyrrolidone solvent stocks. Single-source vulnerability concentrates in VDF precursor supply, where backward-integrated conglomerates control allocation priorities. Distribution runs through long-term offtake agreements with tier-one battery manufacturers rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized polymer synthesis expertise sits with a narrowing cohort of suppliers capable of qualifying novel chemistries across multiple regulatory jurisdictions simultaneously. This capability compression rewards incumbents with captive infrastructure while raising barriers for challengers dependent on toll manufacturing arrangements.
For Market Incumbents: Consolidate position by expanding captive VDF monomer capacity in South Korea and Germany ahead of silicon-anode qualification waves. Lock five-year supply agreements with CATL and LG Chem before secondary entrants secure tolling relationships with Chinese petrochemical operators. For New Entrants and Emerging Players: Technical service gaps in India's PLI scheme battery corridors offer first-mover windows for suppliers establishing localized formulation laboratories. Target Gujarat and Tamil Nadu manufacturing clusters with water-based acrylic customization capabilities that domestic incumbents under-serve. Pursue qualification partnerships with solid-state cell developers lacking standardized binder-electrolyte interface protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic rubber specialists with elastomer IP adaptable to silicon-anode swelling requirements. Five-to-ten year viability favors targets with crosslinking polymer patent estates rather than commodity PVDF tollers. Watch ECHA REACH authorization timelines for per- and polyfluoroalkyl substances as the inflection signal for fluoropolymer valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VDF Monomer | Arkema and Solvay anchor European supply security through captive precursor production. |
| Water-Based Formulation Expansion | Chinese manufacturers exploit NMPA accelerated timelines to compress qualification cycles. |
| Solid-State Interface Customization | Polymer binders for sulfide electrolytes represent uncaptured margin pools in pilot production. |
| Regional Technical Service Buildout | India's PLI scheme rewards first movers establishing Gujarat and Tamil Nadu service centers. |
| Closed-Loop Synthesis Investment | EU F-Gas Regulation compliance generates patentable IP positions in emissions-constrained manufacturing. |
Research Methodology
A spread of perspectives from polymer R&D directors, battery manufacturer procurement leads, electrode fabrication engineers, and fluorochemical regulatory specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, ECHA registration databases, SEC chemical sector filings, and Korean MFDS emission disclosure records. Bottom-up capacity assessments and top-down demand modeling triangulated on volume estimates.
Segmentation dimensions modeled include formulation chemistry tier, end-use intensity across electric vehicle and energy storage applications, manufacturing integration depth, and regional regulatory cluster. CAGRs were derived from slope analysis of historical qualification timelines projected across the analysis window. Forecast inputs incorporated silicon-anode penetration curves, solid-state cell pilot line announcements, and REACH authorization phase-down schedules.
Forecasts assume regulatory continuity in EU REACH, China MEE enforcement, and South Korea MFDS emission standards; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as ECHA per- and polyfluoroalkyl substance disclosure thresholds and China's dual carbon implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Molten Salt Battery Market
Batteries
China Battery Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Printed Batteries Market
Batteries
Rear Rack Battery Market
Batteries
Zinc-Manganese Oxide Printed Battery Market
Batteries
Battery Light Towers Market
Batteries
Aluminum Based Battery Market
Batteries
Military Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
Disposable Batteries Market
Batteries
Asia Power Tool Batteries Market
Batteries
Battery Pack for Marine Hybrid and Full Electric Propulsion Market
Batteries
Seawater Battery Market
Batteries
Battery Maintainer Market
Batteries
North America NMC Battery Pack Market