
 Styrene-Butadiene-Styrene Block Copolymer Market | 2026-2036
Styrene-Butadiene-Styrene Block Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Styrene-Butadiene-Styrene Block Copolymer Market Intelligence
Footwear soling is pivoting toward SBS-based formulations as brands seek alternatives to PVC and traditional vulcanized rubber. TSRC leverages its Taiwan production base to supply thermoplastic elastomer grades across Southeast Asian shoe factories. Kraton Corporation differentiates through hydrogenated SBS variants that deliver enhanced UV stability for outdoor footwear applications. Kumho Petrochemical Co., Ltd. anchors Korean domestic demand while extending exports to Chinese sole compounders.
Styrene-butadiene-styrene block copolymer is a thermoplastic elastomer synthesized via anionic polymerization, typically containing 30-40% styrene content arranged in triblock architecture that yields rubber-like elasticity at service temperatures with thermoplastic processability. Its primary commercial purpose centers on replacing conventional vulcanized rubber in applications requiring injection molding or extrusion without curing stages. Thermoplastic elastomer formulations command the dominant volume position due to their compatibility with existing plastics processing infrastructure. Adhesive applications represent the fastest-expanding segment as hot-melt pressure-sensitive formulations displace solvent-based systems in packaging and hygiene products. SBR grades remain mature with margin pools concentrated in tire modification and asphalt binder modification for road construction.
China's MEE enforces GB standards on volatile organic compound emissions from SBS production facilities, while REACH in Europe mandates registration and restriction protocols for styrene monomer residuals in imported elastomer compounds. The EU F-Gas Regulation indirectly shapes SBS demand by accelerating polymer-based sealant substitution for fluorinated products in HVAC and automotive systems. Stakeholders must monitor feedstock volatility in butadiene contract pricing and assess backward integration options into styrene monomer production to secure margin stability.
Market Dynamics
Footwear soling manufacturers are pivoting procurement toward SBS thermoplastic elastomers as PVC phase-outs and vulcanized rubber substitution accelerate across Asian production clusters. This demand rotation is compressing traditional rubber supply chains while elevating styrene-butadiene-styrene block copolymer specifications for injection-molded sole applications.
Growth Catalysts
- GB Standards Compliance:China's MEE enforcement of volatile organic compound limits on petrochemical processing is disqualifying legacy solvent-based adhesive formulations, redirecting volume toward SBS hot-melt systems in packaging and hygiene product manufacturing.
- Footwear Manufacturing Migration:Southeast Asian shoe factories are consolidating thermoplastic elastomer procurement as brands relocate production from coastal China to Vietnam and Indonesia, concentrating SBS demand in Ho Chi Minh City and Jakarta industrial zones.
- Dual Carbon Goals:Beijing's emissions intensity targets for 2030 are forcing petrochemical complexes in Zhejiang province to upgrade butadiene recovery systems, indirectly tightening SBS feedstock quality benchmarks for export-grade material.
Market Restraints
- Butadiene Price Volatility:Contract pricing for C4 feedstock fluctuates with naphtha cracking economics in South Korea and Taiwan, compressing margin stability for non-integrated SBS compounders lacking captive butadiene supply.
- REACH Registration Burden:European importers face extended compliance timelines for styrene monomer residual documentation under ECHA protocols, creating friction for Asian exporters targeting German and French adhesive markets.
- Hydrogenated SBS Substitution:SEBS grades with superior UV resistance are capturing premium outdoor footwear segments, constraining growth ceilings for unhydrogenated SBS in performance soling applications.
Strategic Opportunities
- Asphalt Modification White Space:Road construction authorities in India are piloting polymer-modified binders for highway durability, opening SBS specification opportunities in Mumbai and Delhi infrastructure projects.
- EU F-Gas Displacement:The regulation's phase-down of fluorinated sealants is accelerating HVAC and automotive polymer adoption, with SBS-based formulations penetrating climate-control system gaskets across German and Italian manufacturing.
- Recycling Infrastructure Convergence:Mechanical reprocessing of post-industrial SBS scrap with compatibilizer technology is enabling closed-loop thermoplastic elastomer recovery in Taiwanese compounding operations.
Industry Challenges
- Anionic Polymerization Expertise Scarcity:The specialized skill set for living polymerization process control is concentrated among veteran technicians at legacy Taiwan and South Korean facilities, constraining new plant commissioning in emerging production regions.
- Multi-Jurisdictional Certification Complexity:Simultaneous compliance with China's GB standards, REACH registration, and FDA indirect food contact requirements for pressure-sensitive adhesives extends product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrene-Butadiene-Styrene Block Copolymer Market |
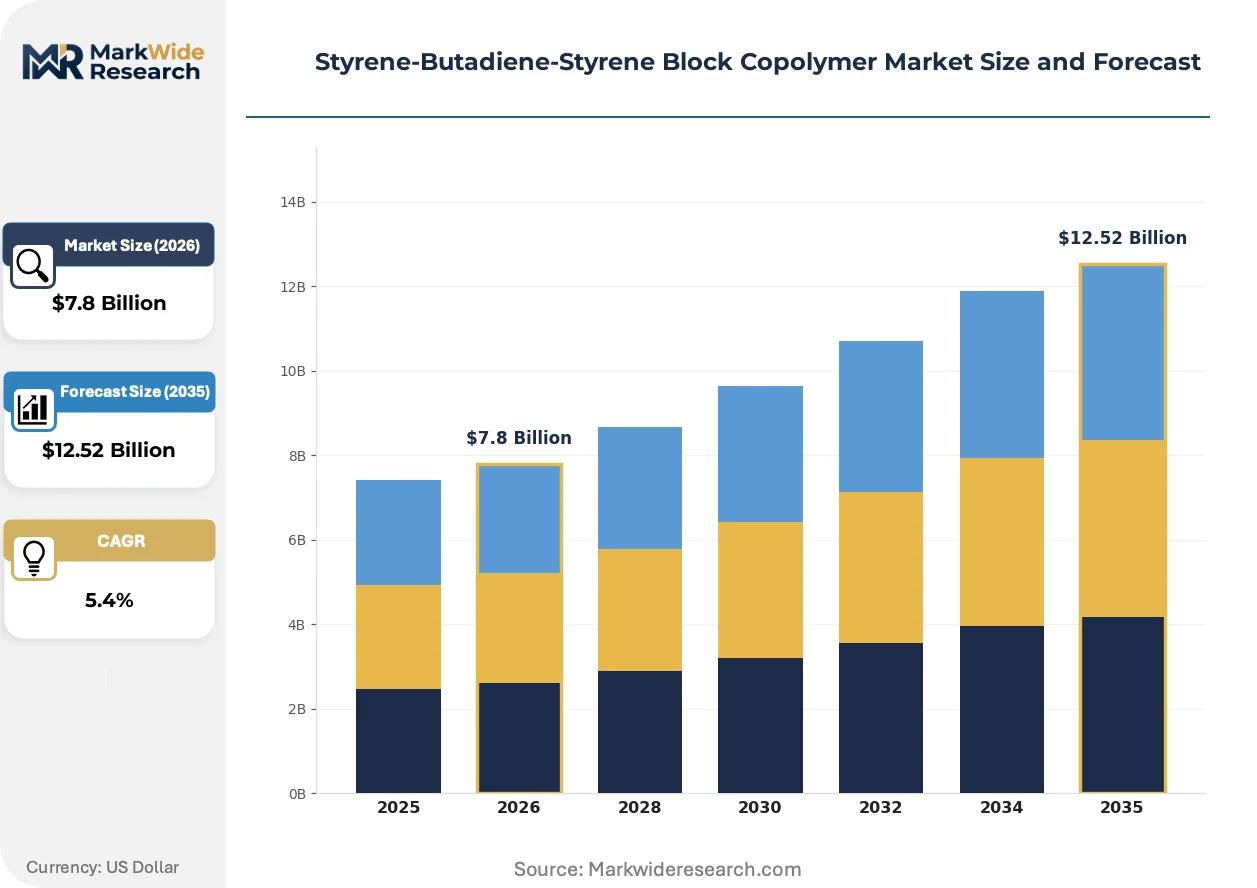
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene-Butadiene-Rubber, Thermoplastic Elastomer, Adhesive, Coating Application: Automotive, Construction, Footwear, Consumer Goods End User: Manufacturers, OEMs, Industrial, Retail Formulation: Block Copolymer, Blends, Compounds, Others |
| Companies Covered | TSRC, Trinseo, Kraton Corporation, Kumho Petrochemical Co., Ltd., Formosa Petrochemical Corporation, Sinopec, Dynasol Group, JSR Corporation, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrene-Butadiene-Styrene Block Copolymer Market Strategic Shifts & Innovations
Reactive extrusion and hydrogenation process refinements are reshaping SBS grade architectures, enabling property profiles that encroach on thermoset rubber territories while preserving thermoplastic process economics.
Partial hydrogenation technology is absorbing mid-tier outdoor footwear specifications previously reserved for SEBS and vulcanized rubber compounds. Vietnamese sole manufacturers are adopting these grades at accelerating rates for hiking and athletic shoe lines. The technology is absorbing volume from higher-cost saturated elastomers without requiring retooling of existing injection molding assets.
REACH restriction proposals on styrene monomer residuals are tightening documentation requirements for imported elastomer compounds entering EU adhesive markets. German packaging converters are demanding certified low-residual SBS grades to preempt supply chain disruption. Hot-melt pressure-sensitive formulation segments are responding by qualifying alternative hydrogenated grades with cleaner analytical profiles.
Compounders are consolidating procurement relationships around integrated petrochemical suppliers offering bundled styrene-butadiene feedstock packages. Direct mill-to-compounder contracts are displacing traditional distributor intermediaries in Zhejiang and Guangdong provinces. This concentration is most visible among large-scale footwear sole producers seeking volume guarantees and technical service proximity.
Styrene-Butadiene-Styrene Block Copolymer Market Segmentation
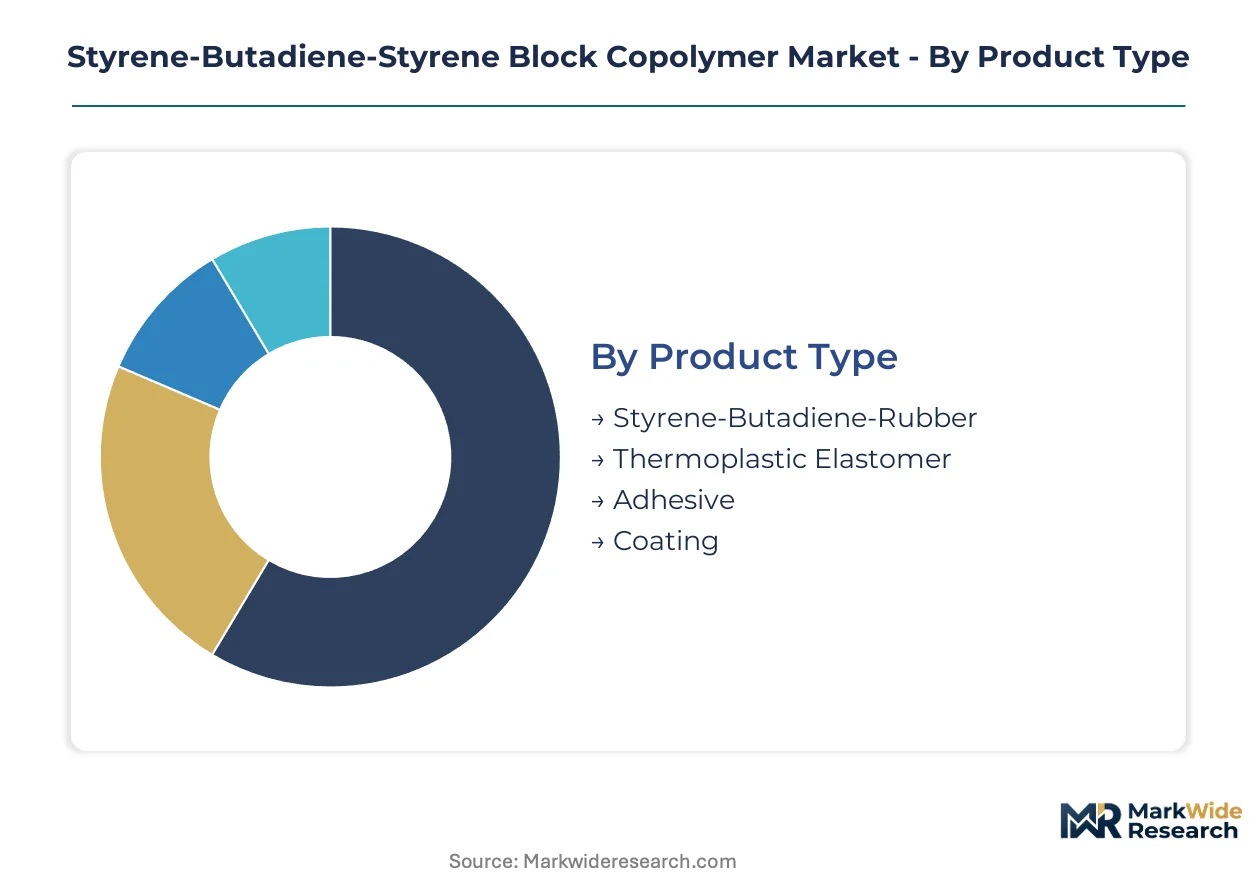
SBS block copolymer specifications diverge sharply across processing methods and performance requirements. Product architecture determines compatibility with injection molding, extrusion, or adhesive compounding lines.
Product Type:
Thermoplastic elastomer grades dominate procurement volumes due to their compatibility with standard plastics processing infrastructure.
- Thermoplastic Elastomer:Triblock architecture with 30-40% styrene content delivers rubber-like elasticity without vulcanization. Demand concentrates in injection-molded footwear soling across Vietnamese and Indonesian manufacturing clusters as brands phase out PVC.
- Adhesive:Hot-melt pressure-sensitive formulations displace solvent-based systems in packaging and hygiene products. MEE enforcement of GB volatile organic compound limits is redirecting procurement toward SBS hot-melt systems in Chinese manufacturing.
- Styrene-Butadiene-Rubber:Mature grades serve tire modification and asphalt binder applications with concentrated margin pools in road construction.
- Coating:Specialized formulations penetrate protective and decorative surface applications with niche specification requirements.
Thermoplastic elastomer leads on scale; adhesive leads on momentum.
Application:
End-use specifications vary by durability, weathering, and processing temperature requirements.
- Footwear:Injection-molded sole applications absorb expanding SBS volumes as vulcanized rubber substitution accelerates. TSRC supplies thermoplastic elastomer grades across Southeast Asian shoe factories from its Taiwan production base.
- Construction:Polymer-modified asphalt binders for highway durability are piloting across Indian infrastructure projects. SBS specifications penetrate Mumbai and Delhi road construction tenders.
- Automotive:Climate-control system gaskets adopt SBS-based formulations as EU F-Gas Regulation phases down fluorinated sealants in German and Italian manufacturing.
- Consumer Goods:Pressure-sensitive adhesive applications in packaging and personal care products drive specification diversity.
Footwear leads on scale; construction leads on momentum.
End User:
Procurement patterns split between specification-controlled OEM channels and price-sensitive industrial bulk purchasing.
- Manufacturers:Footwear sole producers and adhesive compounders consolidate procurement around integrated petrochemical suppliers offering bundled feedstock packages. Direct mill-to-compounder contracts displace distributor intermediaries in Zhejiang and Guangdong provinces.
- OEMs:Automotive and appliance manufacturers impose strict residual styrene documentation under REACH protocols, extending Asian exporter compliance timelines.
- Industrial:Road construction authorities and packaging converters purchase on volume contracts with technical service requirements.
- Retail:Small-scale adhesive and coating distributors serve fragmented regional markets with limited specification control.
Manufacturers lead on scale; OEMs lead on momentum.
Formulation:
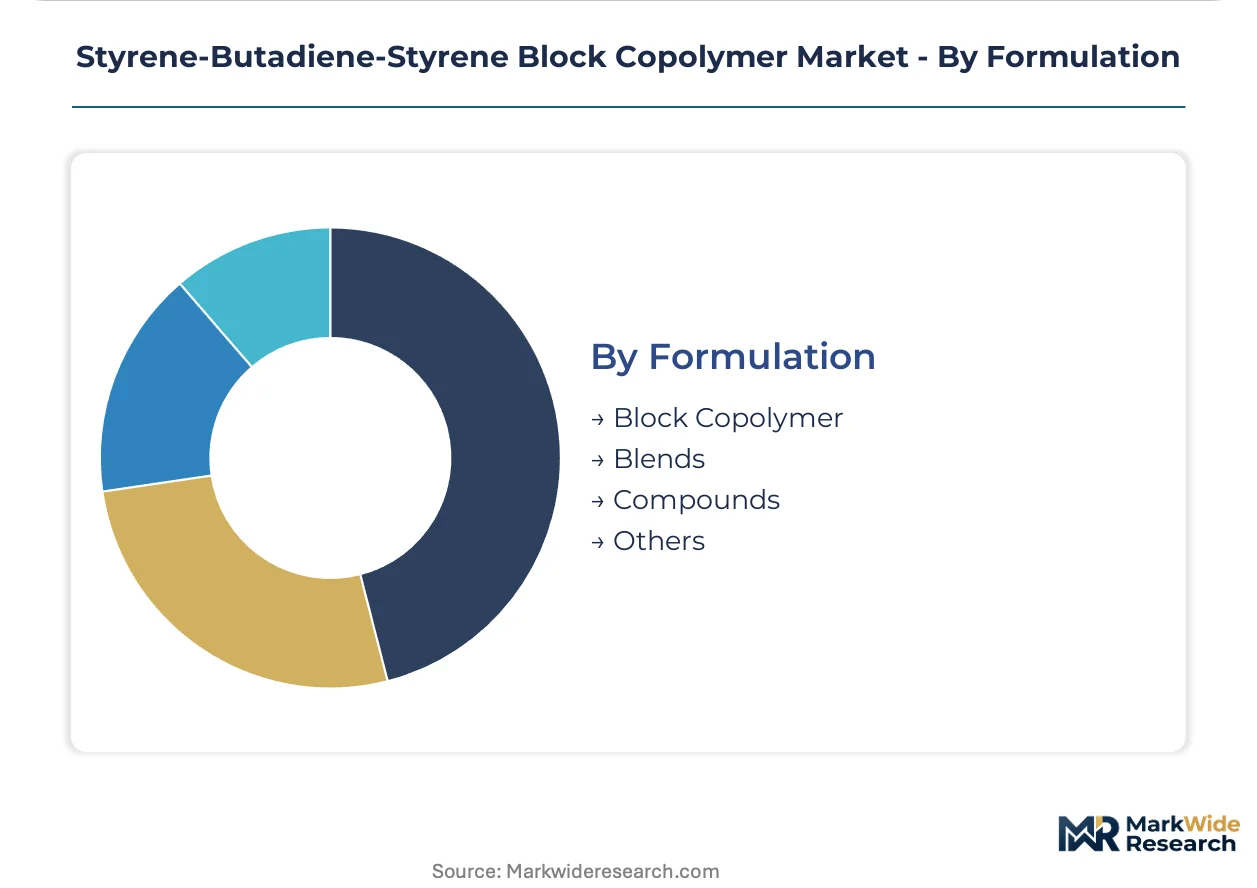
Polymer architecture determines reprocessability, compatibility with fillers, and end-use performance ceilings.
- Block Copolymer:Standard triblock SBS dominates thermoplastic elastomer applications with established anionic polymerization supply chains. Partial hydrogenation variants absorb mid-tier outdoor footwear specifications from higher-cost SEBS grades.
- Blends:Mechanical mixtures with polyolefins or other elastomers adjust hardness and processability for specific molding equipment.
- Compounds:Pre-formulated grades with additives, fillers, and stabilizers reduce downstream processing steps for footwear manufacturers.
- Others:Experimental and specialty formulations serve niche specification requirements outside standard commercial grades.
Block copolymer leads on scale; compounds lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province anchors regional production concentration as China's petrochemical complexes upgrade butadiene recovery systems to meet tightening emissions benchmarks. Footwear manufacturing migration from coastal China to Southeast Asia is redrawing procurement patterns across East Asian supply chains. Regulatory divergence between China's GB standards and EU REACH protocols is fragmenting compliance requirements for export-oriented compounders.
China
Footwear sole compounders in Guangdong province are consolidating procurement around integrated suppliers offering bundled styrene-butadiene feedstock packages. MEE enforcement of GB volatile organic compound limits is disqualifying legacy solvent-based adhesive formulations, redirecting volume toward SBS hot-melt systems. Zhejiang province's petrochemical complexes are upgrading butadiene recovery infrastructure to satisfy Beijing's dual carbon goals for 2030.
South Korea
Ulsan petrochemical complex anchors Korean domestic SBS demand while extending exports to Chinese sole compounders. Contract pricing for C4 feedstock fluctuates with naphtha cracking economics, compressing margin stability for non-integrated compounders lacking captive butadiene supply. Korean facilities concentrate anionic polymerization expertise that constrains new plant commissioning in emerging production regions.
Vietnam
Southeast Asian shoe factories are consolidating thermoplastic elastomer procurement as brands relocate production from coastal China. Ho Chi Minh City industrial zones absorb expanding SBS volumes for injection-molded sole applications. TSRC leverages its Taiwan production base to supply thermoplastic elastomer grades across Vietnamese manufacturing clusters.
Indonesia
Jakarta industrial zones concentrate footwear manufacturing migration from China, elevating SBS specifications for local sole producers. Brands phase out PVC and vulcanized rubber in favor of thermoplastic elastomer formulations compatible with existing injection molding assets. Indonesian compounders face multi-jurisdictional certification complexity spanning China's GB standards and EU REACH registration protocols.
Germany
German packaging converters demand certified low-residual SBS grades to preempt supply chain disruption under REACH restriction proposals on styrene monomer residuals. EU F-Gas Regulation accelerates polymer-based sealant substitution for fluorinated products in HVAC and automotive climate-control systems. German and Italian manufacturing adopt SBS-based formulations for climate-control system gaskets.
Styrene-Butadiene-Styrene Block Copolymer Market Key Industry Players
Capacity expansion dominates the current landscape as integrated petrochemical suppliers upgrade butadiene recovery systems and extend direct mill-to-compounder contracts. The vendor base splits between legacy Taiwan and South Korean facilities with anionic polymerization expertise and emerging compounders in Southeast Asian manufacturing clusters. Two strategic archetypes prevail: integrated petrochemical suppliers offering bundled feedstock packages, and specialized thermoplastic elastomer compounders serving footwear sole manufacturers. Competitive intensity centers on backward integration into styrene monomer production and geographic proximity to Vietnamese and Indonesian shoe factories.
Within the integrated petrochemical tier, TSRC and Kumho Petrochemical Co., Ltd. exemplify suppliers leveraging established production bases to serve migrating footwear manufacturing. Kraton Corporation occupies a position among hydrogenated SBS specialists addressing premium outdoor footwear segments with enhanced UV stability requirements. These three companies represent divergent strategic postures: regional supply chain anchoring, integrated feedstock control, and performance-grade specialization.
| Leading Market Players |
|---|
| TSRC |
| Trinseo |
| Kraton Corporation |
| Kumho Petrochemical Co., Ltd. |
| Formosa Petrochemical Corporation |
| Sinopec |
| Dynasol Group |
| JSR Corporation |
| LG Chem |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers in South Korea and Taiwan anchor feedstock supply discipline, translating captive butadiene access into pricing power over non-integrated compounders across Southeast Asian manufacturing clusters. Direct mill-to-compounder contracts in Zhejiang and Guangdong provinces compress distributor margins while elevating volume-commitment discounts for footwear sole manufacturers.
Pricing Analysis
Distributor margin compression defines the channel structure as direct contracts displace traditional intermediaries. Contract-based long-term offtake dominates procurement relationships, with price differentiation resting on hydrogenation grade and REACH certification status. Cost compression in standard SBS grades is intensifying because Vietnamese compounders qualify partial-hydrogenation alternatives without retooling. Small-scale Indonesian distributors exhibit highest price sensitivity; German packaging converters with REACH documentation requirements show lowest.
Supply Chain Analysis
Post-industrial scrap reprocessing flows through Taiwanese mechanical recycling facilities, feeding closed-loop thermoplastic elastomer recovery. Feedstock supply concentrates in South Korea, Taiwan, and China's Zhejiang province. Production draws from naphtha-derived butadiene and styrene monomer inputs. Single-source vulnerability persists around anionic polymerization expertise concentrated at legacy Taiwan and South Korean facilities. Distribution runs through integrated petrochemical suppliers offering bundled feedstock packages to footwear compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The SBS market functions as a geographic-arbitrage play between China's tightening MEE emissions enforcement and Vietnam's lagging regulatory infrastructure, rewarding producers who relocate compounding capacity southward while maintaining feedstock integration northward.
For Market Incumbents: Hedge against hydrogenated SBS substitution by qualifying partial-hydrogenation grades for mid-tier outdoor footwear specifications. Secure captive butadiene supply through backward integration into Zhejiang petrochemical complexes before Beijing's dual carbon goals tighten feedstock access. Channel control through direct mill-to-compounder contracts in Ho Chi Minh City industrial zones defends margin position against emerging Indonesian compounders. For New Entrants and Emerging Players: Reactive extrusion technology-first wedges open specification opportunities in Indian asphalt modification tenders where polymer-modified binder piloting lacks established supplier relationships. Target Mumbai and Delhi infrastructure authorities with technical service proximity absent from incumbent Southeast Asian-focused operations. Pursue joint development agreements with Vietnamese sole manufacturers seeking SEBS alternatives without injection molding retooling. For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated compounders lacking captive butadiene supply and facing margin compression from Korean naphtha cracking economics. Long-term viability over a five-to-ten year horizon hinges on regulatory compliance infrastructure spanning REACH, GB standards, and FDA indirect food contact requirements. Monitor ECHA restriction proposals on styrene monomer residuals as inflection indicator for certified low-residual grade premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene | Captive C4 feedstock supply secures margin stability against naphtha cracking volatility in South Korea. |
| Partial Hydrogenation Capacity Addition | Mid-tier outdoor footwear specifications absorb volume from higher-cost SEBS grades in Vietnamese factories. |
| REACH Certification Investment | Low-residual documentation preempts supply chain disruption for German packaging converters under ECHA protocols. |
| Direct Mill-to-Compounder Contracts | Volume guarantees with technical service proximity displace distributor intermediaries in Zhejiang province. |
| Post-Industrial Scrap Recycling Infrastructure | Mechanical reprocessing with compatibilizer technology enables closed-loop recovery in Taiwanese operations. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Taiwan and South Korean anionic polymerization facilities, procurement leads at Vietnamese footwear OEMs, distribution channel partners in Guangdong province, and technical R&D directors at adhesive compounders with secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed petrochemical suppliers, and MEE enforcement bulletins on GB volatile organic compound limits. Bottom-up volume estimates from grade-level production tracking triangulated against top-down demand aggregation across footwear, construction, and adhesive end-uses.
Segment-weighting approaches modeled thermoplastic elastomer, adhesive, SBR, and coating product types alongside footwear, construction, automotive, and consumer goods applications. CAGRs were derived from elasticity-adjusted demand projections across the analysis window, incorporating butadiene contract pricing volatility, footwear manufacturing migration patterns from coastal China to Vietnam and Indonesia, and regulatory compliance cost differentials between GB standards and REACH protocols. Industry-specific inputs included anionic polymerization capacity utilization rates and hydrogenation technology adoption curves.
The model holds under stable naphtha cracking economics and continued MEE enforcement intensity; deviation in butadiene feedstock supply disruptions or ECHA restriction implementation timelines would shift volume and value trajectories. Practitioners should monitor Korean petrochemical complex maintenance schedules and German packaging converter certification requirements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Neoprene Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Green Polyols Market
Polymers & Resins
Soft PVC Sealing Strip Market