
 Global Butadiene Market | 2026-2036
Global Butadiene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Butadiene Market Analysis
REACH compliance is pivoting European producers toward lower-carbon butadiene supply chains. INEOS leverages its North Sea cracker integration to sustain cost-advantaged output for derivative exports. Sinopec anchors Asia-Pacific supply through refinery-chemical complexes along China's eastern coast. Shell Chemicals competes on feedstock flexibility, routing ethylene cracker co-products into butadiene extraction.
Butadiene is a conjugated diene hydrocarbon produced primarily via steam cracking of naphtha or extraction from C4 streams, with a purity specification typically exceeding 99.5% for polymer-grade applications. Its primary industrial purpose centers on synthetic rubber production and ABS resin feedstock for automotive and consumer durables. Polybutadiene and styrene-butadiene rubber dominate volume flows, with the former commanding premium pricing in high-performance tire formulations. Steam cracking technology leads installed capacity, though extraction routes from refinery streams gain traction where ethylene plant economics tighten.
The EPA enforces emissions thresholds for US Gulf Coast petrochemical complexes, while China's MEE implements dual carbon goals that constrain new coal-to-chemical butadiene routes. ECHA's REACH framework and the EU F-Gas Regulation collectively elevate compliance costs for European derivative manufacturers. Stakeholders must monitor feedstock substitution economics as renewable naphtha and bio-butadiene pilot projects advance toward commercial scale.
Market Dynamics
Steam cracker economics are tightening across major producing regions as naphtha-naphtha spreads compress and co-product credit values from butadiene extraction determine facility run rates. This feedstock-margin sensitivity is redirecting investment toward C4 stream recovery units and bio-based pilot routes.
Growth Catalysts
- EU Green Deal emissions benchmarks:Carbon-border adjustments and renewable content mandates are pulling tire manufacturers toward certified lower-carbon butadiene supply chains for electric vehicle platforms.
- Polybutadiene rubber formulations:High-performance tire specifications for heavier battery-electric vehicles are expanding demand for solution-polymerized grades with enhanced wear resistance.
- China's refinery-chemical integration:New steam cracker and FCC-based C4 extraction capacity along the eastern coast is expanding regional derivative availability for ABS and synthetic rubber producers.
Market Restraints
- Naphtha feedstock volatility:Crude oil price swings transmit directly into steam cracker variable costs, compressing butadiene extraction margins during downstream polymer demand troughs.
- US Gulf Coast supply concentration:EPA emissions thresholds constrain capacity expansions at existing petrochemical complexes, limiting domestic response to derivative demand surges.
- Styrene-butadiene substitution pressure:Natural rubber price competitiveness in commodity tire segments limits butadiene-based synthetic rubber volume growth in emerging markets.
Strategic Opportunities
- India's automotive manufacturing expansion:Domestic ABS and tire production growth under PLI scheme incentives is creating demand for imported butadiene and derivative capacity localization.
- Bio-butadiene fermentation routes:Renewable feedstock technologies from agricultural waste sugars are approaching pilot-scale demonstration for polymer-grade specifications.
- Carbon capture integration:Steam cracker operators are retrofitting post-combustion capture to qualify for EU ETS free allocation and green hydrogen co-production economics.
Industry Challenges
- Process control engineering talent:C4 fractionation and extraction unit optimization requires specialized expertise that is scarce as veteran operators retire from Gulf Coast and European facilities.
- REACH registration timelines:ECHA's extended data requirements for bio-based butadiene novel substances are delaying commercial rollout of renewable supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Butadiene Market |
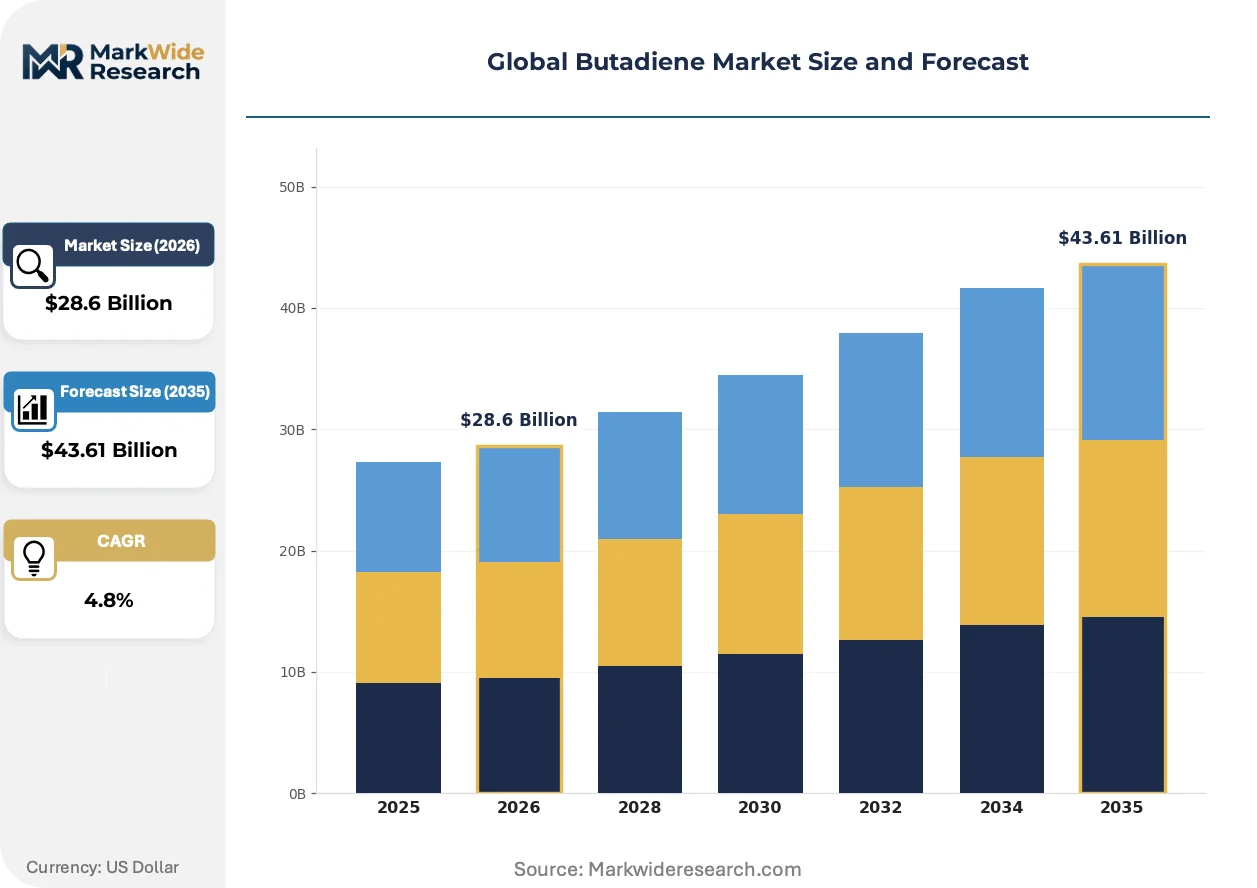
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
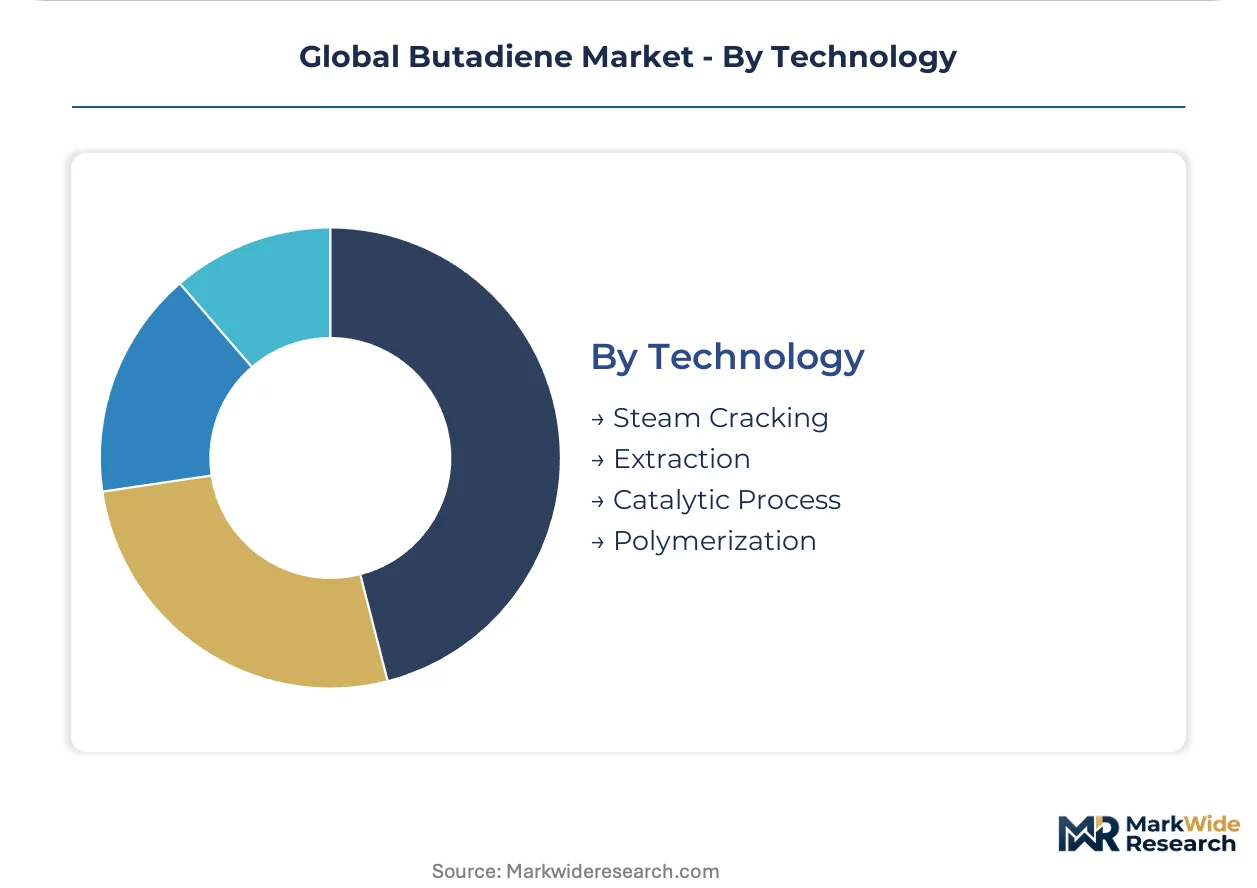
| Segmentation | Product Type: Butadiene Rubber, Styrene-Butadiene Rubber, Acrylonitrile-Butadiene Styrene, Polybutadiene End User: Automotive, Plastics, Chemicals, Footwear Application: Adhesives, Coatings, Sealants, Elastomers Technology: Steam Cracking, Extraction, Catalytic Process, Polymerization |
| Companies Covered | INEOS, TPC Group, Sinopec, China National Petroleum Corp, Shell Chemicals, LyondellBasell Industries Holdings BV, LG Chem, Versalis, BASF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Butadiene Market Emerging Trajectories
Process intensification and digital control systems are compressing unit operating envelopes across butadiene extraction and purification trains. Equipment suppliers and licensors are embedding predictive analytics into turnaround planning.
Advanced extractive distillation sequences with ionic liquid solvents are modularizing separation train footprints for brownfield C4 complex expansions. Mid-scale derivative producers in Germany and Texas are piloting these retrofits to debottleneck existing fractionation capacity without greenfield land acquisition. The technology is modularizing project execution risk and enabling phased capacity additions.
EPA's updated National Emission Standards for Hazardous Air Pollutants are tightening benzene and butadiene fugitive emission limits at US Gulf Coast petrochemical complexes. Facilities must install enhanced leak detection and repair protocols with optical gas imaging requirements. Synthetic rubber producers serving domestic tire manufacturers are absorbing compliance capital costs while evaluating alternative supply arrangements.
Tire manufacturers are consolidating procurement specifications around certified mass-balance chain-of-custody standards for synthetic rubber feedstocks. Long-term offtake contracts with fixed renewable content tiers are displacing spot-market purchasing for premium vehicle platforms. This specification tightening is most visible in Germany and South Korea where original equipment manufacturers have embedded sustainability requirements into supplier scorecards.
Global Butadiene Market Segmentation
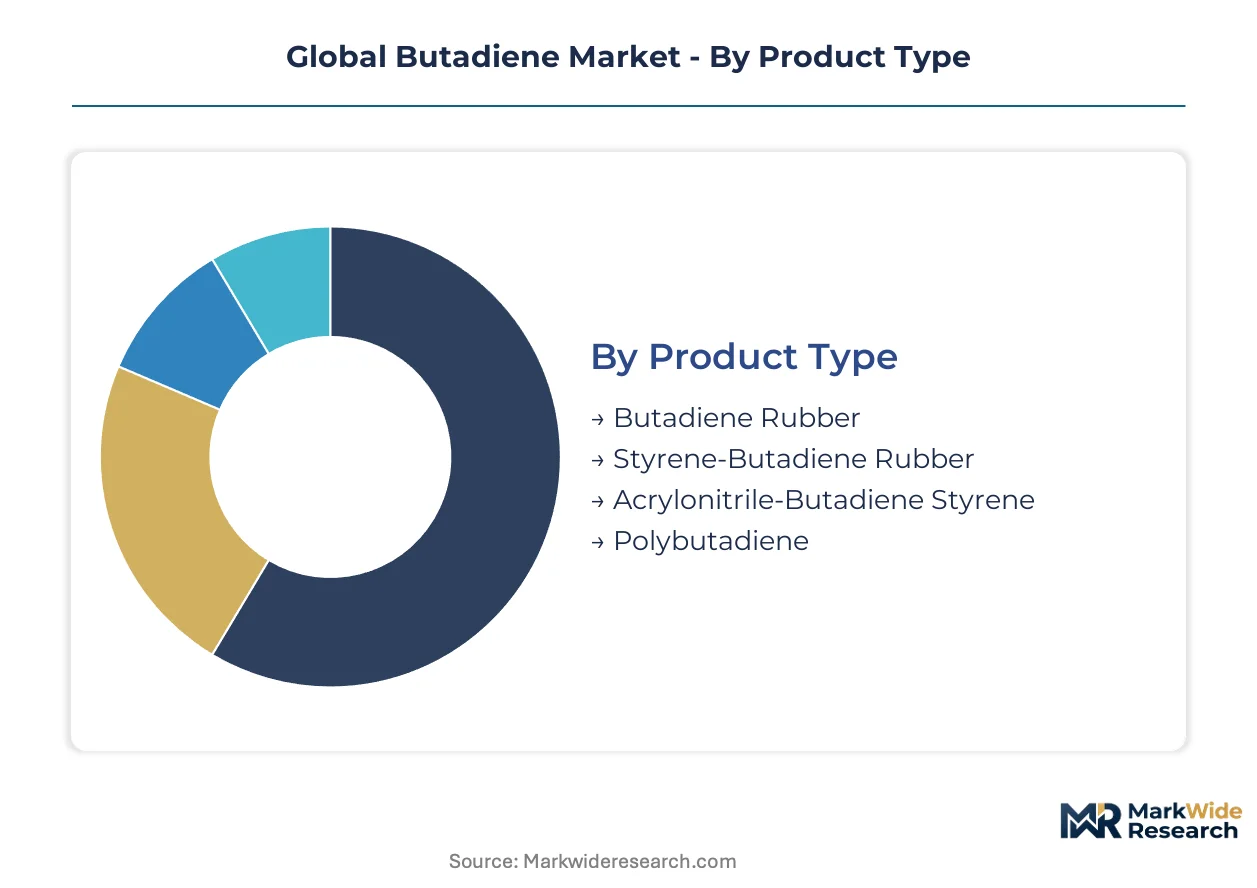
Butadiene derivatives serve markedly different performance requirements across tire manufacturing, automotive interiors, and industrial adhesives. Segmentation clarity exposes where specification premiums command pricing power versus commodity substitution risks.
Product Type:
Buyers differentiate primarily by elasticity modulus and thermal stability specifications in their compound formulations.
- Butadiene Rubber:High-cis polybutadiene delivers superior resilience and abrasion resistance for heavy-duty tire treads. Tire manufacturers in Germany and South Korea specify this grade for electric vehicle platforms where battery weight accelerates tread wear.
- Styrene-Butadiene Rubber:Random copolymer architecture balances processability with wet-grip performance, dominating all-season tire formulations. China's domestic tire brands are expanding SBR offtake as radial tire production localizes under PLI scheme incentives.
- Acrylonitrile-Butadiene Styrene:Terpolymer combining rigidity with impact resistance for automotive interior panels and consumer electronics housings.
- Polybutadiene:Solution-polymerized grades with tailored vinyl content serve golf ball cores and industrial belting applications.
Volume sits with Styrene-Butadiene Rubber; growth tilts toward Butadiene Rubber.
End User:
Procurement scale and specification stringency separate large compounders from dispersed specialty buyers.
- Automotive:OEM tire contracts and interior trim specifications drive polymer-grade purity requirements above 99.5%. Battery-electric vehicle weight profiles are expanding demand for high-performance tread formulations in Germany, China, and the United States.
- Plastics:ABS resin processors require consistent butadiene content for impact modifier performance in appliance housings and automotive dashboards.
- Chemicals:Intermediate producers of adiponitrile and other derivatives source butadiene for nylon-6,6 precursor chains.
- Footwear:Soling compound manufacturers utilize SBR and polybutadiene blends for abrasion-resistant outsoles in athletic and industrial boots.
Automotive absorbs the largest volume share; specialty chemicals procurement is climbing fastest on nylon precursor demand.
Application:
Performance thresholds for temperature resistance and adhesion strength determine grade selection and pricing tiers.
- Adhesives:Pressure-sensitive and structural adhesive formulations leverage SBR latex emulsions for tack and cohesive strength. Construction and packaging sectors in Japan and the United States specify these grades for bonding dissimilar substrates under variable humidity.
- Coatings:Protective and decorative coatings incorporate butadiene-based binders for flexibility and corrosion resistance on metal substrates.
- Sealants:Caulks and gasket compounds utilize liquid polybutadiene for low-temperature elasticity in automotive and building applications.
- Elastomers:Vulcanized rubber goods including hoses, belts, and molded components require precise Mooney viscosity control for processing consistency.
Adhesives command the steepest expansion trajectory on packaging and construction demand; elastomers retain the volume base.
Technology:
Capital intensity and feedstock flexibility separate integrated petrochemical operators from standalone extraction facilities.
- Steam Cracking:Naphtha-fed ethylene crackers generate C4 streams as co-products, with butadiene extraction economics tied to ethylene demand cycles. INEOS and Sinopc operate integrated complexes on the US Gulf Coast and China's eastern coast.
- Extraction:Dedicated C4 fractionation units recover butadiene from refinery FCC streams or purchased mixed C4 feeds, offering margin insulation from ethylene market volatility.
- Catalytic Process:Dehydrogenation and oxidative dehydrogenation routes convert butane or butene feeds, historically marginal against steam cracking economics.
- Polymerization:Solution and emulsion polymerization technologies convert monomer to derivative rubbers and resins, with catalyst systems determining microstructure and performance properties.
Steam cracking underpins installed capacity; extraction routes are gaining project finance attention for feedstock diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta free-trade zones concentrate the majority of new butadiene derivative capacity, with bonded chemical parks offering 15-year tax holidays for integrated refinery-petrochemical investments.
United States
Gulf Coast petrochemical complexes process naphtha and ethane feedstocks for butadiene extraction, with derivative demand from domestic tire manufacturers rising on electric vehicle production scaling. EPA emissions thresholds under the National Emission Standards for Hazardous Air Pollutants constrain capacity expansions at existing facilities. Houston-Beaumont-Port Arthur corridor hosts INEOS and Shell Chemicals operations serving synthetic rubber and ABS resin markets.
China
Refinery-chemical integration projects along the eastern coast expand C4 extraction capacity for domestic ABS and tire production. MEE dual carbon goals redirect investment away from coal-to-chemical routes toward steam cracker and FCC-based recovery units. Ningbo-Zhoushan and Shanghai chemical zones anchor Sinopec and China National Petroleum Corp capacity serving Asia-Pacific derivative demand.
Germany
Automotive OEM sustainability scorecards drive certified lower-carbon butadiene procurement for electric vehicle tire platforms. ECHA REACH compliance and EU Green Deal carbon-border adjustments elevate feedstock traceability requirements. Ludwigshafen and Marl chemical parks concentrate BASF and Versalis operations with pipeline integration to downstream rubber compounders.
South Korea
Domestic tire manufacturers specify solution-polymerized polybutadiene grades for premium electric vehicle tread formulations. MFDS chemical safety assessments and carbon footprint disclosure mandates shape import sourcing decisions. Yeosu and Ulsan industrial complexes host LG Chem operations with dedicated butadiene extraction from naphtha crackers.
India
Automotive manufacturing expansion under PLI scheme incentives creates demand for ABS resin and synthetic rubber feedstocks. BIS quality standards and DGFT import tariff structures influence domestic derivative investment timelines. Gujarat and Maharashtra chemical zones attract butadiene extraction capacity proposals serving tire and plastics processors.
Global Butadiene Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the butadiene value chain, with integrated petrochemical groups commanding feedstock cost advantages and standalone extraction operators pursuing margin insulation through C4 stream flexibility. Market structure tilts toward consolidation at the monomer extraction tier and fragmentation across derivative rubber and resin production. Three archetypes dominate: integrated refinery-chemical operators with captive C4 supply, regional extraction specialists serving merchant markets, and downstream polymer producers with backward integration into monomer sourcing. Competitive dynamics center on capacity expansion timing and strategic partnerships for bio-based feedstock development.
Within the integrated operator tier, INEOS and Sinopec exemplify scale-driven positioning through refinery-chemical complex ownership, while Shell Chemicals occupies a position emphasizing feedstock routing flexibility across ethylene cracker co-product streams. LG Chem anchors the Asia-Pacific specialist segment with Korean chemical park concentration.
| Leading Market Players |
|---|
| INEOS |
| TPC Group |
| Sinopec |
| China National Petroleum Corp |
| Shell Chemicals |
| LyondellBasell Industries Holdings BV |
| LG Chem |
| Versalis |
| BASF |
| Others |
Supply Flow & Price Mechanics
Naphtha feedstock costs cascade through steam cracker economics into polymer-grade butadiene pricing tiers, with naphtha-naphtha spreads compressing margins for extraction-dependent operators and redirecting procurement toward C4 stream recovery alternatives in China and the United States.
Pricing Analysis
Short lead-time premiums for spot butadiene deliveries command substantial markups over contract offtake arrangements, particularly when ethylene cracker turnarounds constrain C4 stream availability. Contract-based long-term offtake dominates tire manufacturer procurement, with price differentiation driven by polymer-grade purity certification and volume scale commitments. Pricing pressure stems from naphtha volatility transmitting into variable costs, compressing extraction margins during downstream synthetic rubber demand troughs. Commodity tire compounders exhibit highest price sensitivity, while electric vehicle platform suppliers absorb premiums for certified lower-carbon feedstock grades.
Supply Chain Analysis
Butadiene supply rests on naphtha-fed steam cracker operations concentrated in China, the United States, and Germany, with refinery-chemical integration complexes anchoring regional derivative availability. C4 fractionation units draw from mixed feed streams including FCC off-gases and ethylene co-product streams, with acetonitrile and N-methylpyrrolidone solvents enabling extractive distillation. Single-source vulnerability intensifies around specialized C4 recovery catalysts and ionic liquid separation technologies controlled by limited equipment licensors. Distribution runs through pipeline networks serving integrated rubber compounders, supplemented by rail and barge movements for merchant market deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Butadiene Market functions as a cost-of-compliance arena where ECHA REACH registration timelines and EU Green Deal carbon-border adjustments erect barrier-to-entry moats favoring incumbent operators with established data packages and certified lower-carbon supply chains.
For Market Incumbents: Anchor market position through captive C4 stream integration at refinery-chemical complexes along China's eastern coast and the US Gulf Coast, insulating margin structures from naphtha volatility. Defend against bio-butadiene fermentation entrants by accelerating REACH registration for renewable feedstock grades and securing long-term offtake contracts with tire manufacturers embedding sustainability scorecards. For New Entrants and Emerging Players: Launch via extraction-focused C4 recovery units serving India's automotive manufacturing expansion under PLI scheme incentives, where domestic ABS and tire production growth outpaces local butadiene capacity. Target merchant market supply to specialty chemicals producers seeking nylon-6,6 precursor chains, leveraging modular ionic liquid separation retrofits to minimize capital intensity against greenfield steam cracker competition. For Investors and Strategic Acquirers: First commercial bio-butadiene offtake agreements with European tire manufacturers are the leading indicator that renewable feedstock economics have crossed threshold viability for scaled deployment. Acquisition focus should center on regional extraction specialists with C4 stream flexibility and established relationships with downstream rubber compounders, monitoring EPA emissions threshold tightening as a signal for distressed asset availability in the Houston-Beaumont-Port Arthur corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Recovery | Captive feedstock supply from refinery streams insulates INEOS and Sinopec from ethylene demand cycle volatility. |
| Green Manufacturing Transition | Bio-butadiene fermentation from agricultural waste sugars positions operators for EU ETS free allocation qualification. |
| Long-term Supply Agreement | Fixed renewable content tiers in tire manufacturer contracts displace spot purchasing for electric vehicle platforms. |
| Joint Venture | Refinery-chemical integration partnerships in China's Yangtze River Delta zones leverage bonded chemical park tax holidays. |
| Capacity Expansion | Modular extractive distillation retrofits in Germany and Texas debottleneck existing fractionation without greenfield land acquisition. |
Methodological Framework
Independent corroboration across plant manager interviews, procurement leads at tire and ABS resin OEMs, and technical R&D directors at extraction technology licensors underwrites the qualitative findings in this study. Secondary validation draws from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from petrochemical conglomerates, and EPA emissions compliance disclosures. Bottom-up capacity and utilization estimates triangulate against top-down demand segmentation across automotive, plastics, and specialty chemicals end-uses.
Historical reference periods spanning pre-pandemic baseline, demand disruption, and recovery phases anchor the forecast window across the analysis window. The analytical framework models segmentation dimensions including polymer grade tier, end-use industry, technology route, and regional production hub. CAGRs derive from trend extrapolation adjusted for capacity addition timelines and regulatory constraint scenarios, with naphtha-naphtha spreads and electric vehicle production scaling as primary industry-specific forecast inputs.
Feedstock substitution economics, regulatory timeline slippage, and bio-based route commercialization delays are the dominant revision risks to projection assumptions. Forecasts reflect documented assumptions on capacity utilization rates and demand elasticity parameters. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petrochemicals
Propane Market
Petrochemicals
Bioisobutene Market
Petrochemicals
Chemical and Petroleum Containers Market
Petrochemicals
Global Perfluorocarbons Market
Petrochemicals
Malaysia Chemical and Petrochemical Market
Petrochemicals
Propylene Carbonate Market
Petrochemicals
Pentane Market
Petrochemicals
Alkylate Market
Petrochemicals
Olefin Derivatives Market
Petrochemicals
Tert Butyl Hydroperoxide Market
Petrochemicals
Basic Petrochemical Market
Petrochemicals
Synthetic and Biobased Butadiene Market
Petrochemicals
Alkylate Isooctane Market
Petrochemicals
Pentaerythritol Market
Petrochemicals
Anthracene Oil Market
Petrochemicals
Flame-Retardant Polypropylene (PP) Market