
 Green Polyols Market | 2026-2036
Green Polyols Market Size, Share, and Industry Trends Forecast 2026-2036
Green Polyols Market Outlook
Europe is reshaping competitive dynamics in green polyols through dedicated biorefinery investments and policy-backed offtake agreements. Covestro AG leverages its integrated polyether pilot lines in Germany to anchor regional supply for automotive OEMs. BASF SE sustains R&D intensity across bio-succinic acid routes, competing on feedstock diversification rather than scale alone. Cargill extends its oilseed crush network into oleochemical polyol precursors, controlling upstream biomass flows that rivals cannot easily replicate.
Green polyols are polymeric alcohols derived from renewable feedstocks such as soy, castor, or sugar-based intermediates, typically exhibiting hydroxyl values between 28 and 700 mg KOH/g and designed as reactive components in polyurethane synthesis. These materials replace petroleum-derived counterparts in foam, coating, and adhesive systems where carbon footprint reduction carries procurement weight. Polyether polyols dominate current volume due to established flexible foam demand in furniture and bedding, though renewable polyols capture expanding margin pools as automotive brands mandate bio-content thresholds in seating and interior trim. Bio-based polyols occupy a narrower but defensible niche in rigid foam insulation for construction, where LEED certification and national building codes amplify specification pull.
The EU Green Deal and REACH frameworks enforce disclosure of petrochemical content and restrict certain isocyanate precursors, pushing formulators toward certified bio-based polyol streams. EPA bio-preferred labeling and California Air Resources Board volatile organic compound rules extend similar pressure in North American specification markets. Stakeholders must monitor feedstock certification integrity and regional biorefinery build-out timelines to secure position before supply agreements tighten around committed capacity.
Market Dynamics
Automotive OEMs are mandating bio-content thresholds in seating and interior trim, forcing polyurethane formulators to secure certified renewable polyol streams ahead of committed biorefinery capacity. This procurement pressure is reshaping supplier qualification timelines and feedstock certification requirements across the value chain.
Growth Catalysts
- EU Green Deal chemical disclosure mandates:REACH frameworks enforce petrochemical content limits in consumer goods, pulling formulators toward certified bio-based polyol streams for foam and coating applications.
- Automotive seating bio-content mandates:OEM procurement specifications now require minimum renewable content in polyurethane cushioning, concentrating demand around suppliers with verified mass-balance certification.
- Castor oil biorefinery clustering in Gujarat:Dedicated crushing and refining infrastructure for oleochemical polyol precursors is securing upstream biomass flows that petroleum-based rivals cannot replicate.
Market Restraints
- Soybean oil price volatility:Feedstock cost swings for the dominant North American oilseed crush input compress margins for polyol producers without long-term grower contracts.
- German pilot production concentration:Covestro and BASF facilities near Leverkusen and Ludwigshafen control early commercial volumes, creating geographic supply risk before scale-up elsewhere.
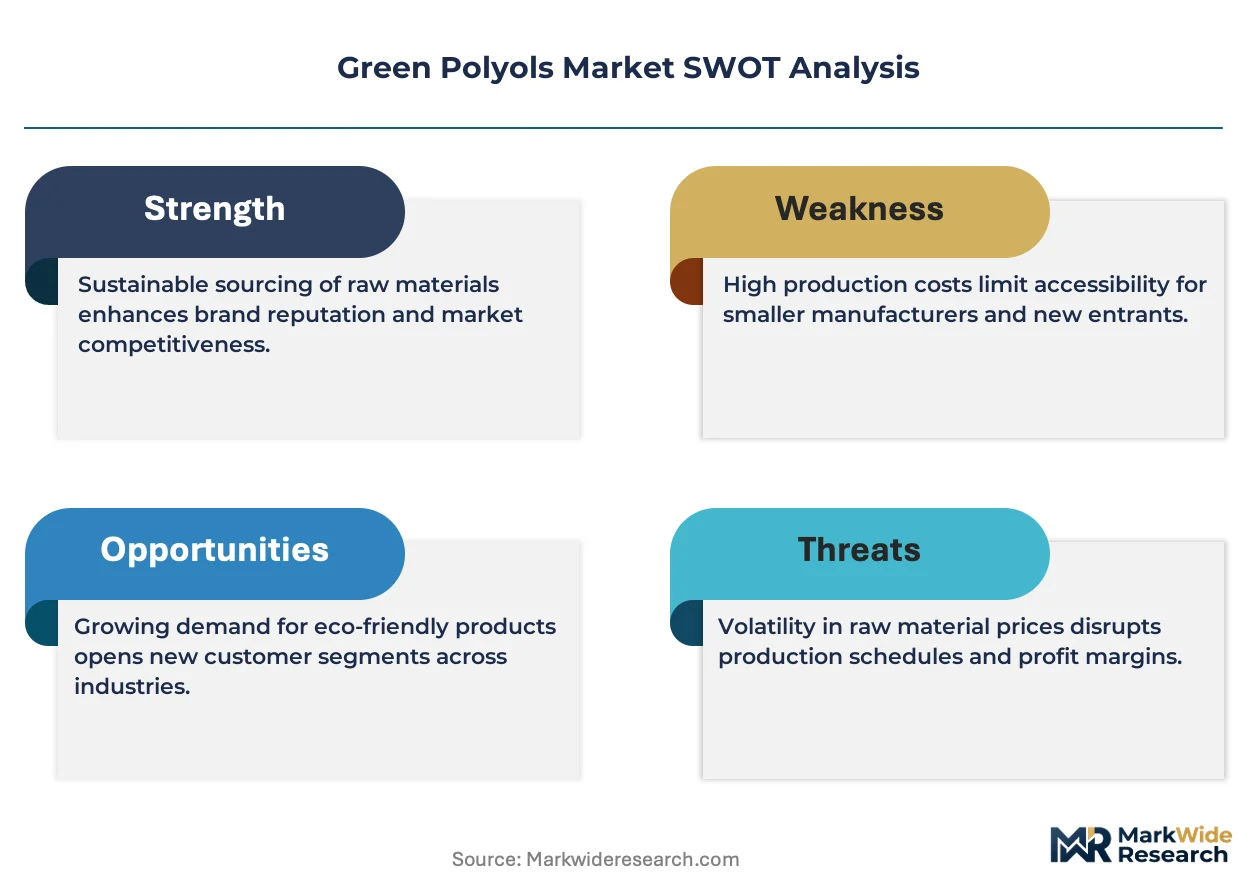
- Performance gaps in rigid foam insulation:Bio-based polyols exhibit lower thermal stability than petroleum counterparts in certain construction-grade spray foam applications.
Strategic Opportunities
- India construction sector underpenetration:LEED certification adoption in commercial building projects creates specification pull for rigid foam insulation using certified renewable polyols.
- Carbon accounting software integration:Converging blockchain traceability with lifecycle assessment tools enables premium pricing for verified low-carbon polyol batches.
- USDA BioPreferred program expansion:Federal procurement preference for bio-based products opens institutional purchasing channels for furniture and bedding foam manufacturers.
Industry Challenges
- Mass-balance certification complexity:ISCC PLUS and RSB chain-of-custody audits require 12-18 month implementation timelines that delay supplier qualification.
- Polyurethane formulation requalification:Switching from petroleum to renewable polyols demands extensive automotive OEM testing cycles for seating durability and emissions compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Polyols Market |
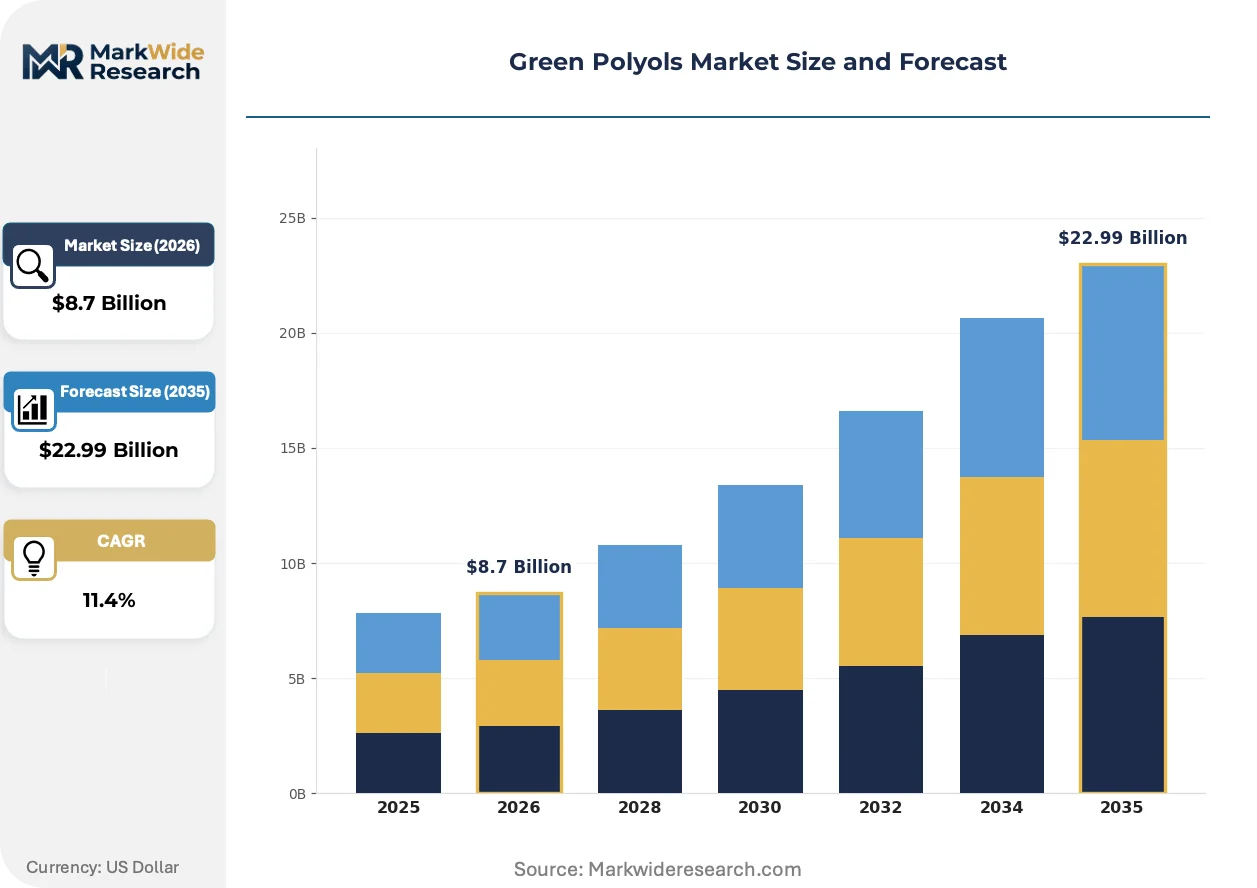
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether Polyols, Polyester Polyols, Renewable Polyols, Bio-Based Polyols Application: Flexible Foam, Rigid Foam, Adhesives, Coatings End Use Industry: Furniture, Automotive, Construction, Electronics Form: Liquid, Solid, Gel, Powder |
| Companies Covered | BASF SE, Covestro AG, The Dow Chemical Company Inc, Cargill, Arkema, Emery Oleochemicals, Huntsman International LLC, Mitsui Chemicals Inc, Jayant Agro-Organics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Polyols Market Strategic Shifts
Process intensification in biorefinery operations is collapsing capital requirements for renewable polyol production. These advances are compressing the scale threshold for commercial viability and opening entry paths for specialized producers.
Second-generation sugar-based polyether technology is collapsing the cost premium versus petroleum-derived counterparts. Flexible foam manufacturers in furniture and bedding are adopting these materials at accelerating rates. The structural consequence is eroding the price barrier that has constrained bio-based polyol penetration in mid-market applications.
REACH chemical restriction updates are tightening isocyanate precursor disclosure requirements for polyurethane formulators. Industrial consequence includes mandatory substitution planning for certain aromatic amine catalysts. Rigid foam insulation producers in Germany and France are responding by accelerating qualification of aliphatic bio-based polyol systems.
Automotive OEMs are consolidating supplier panels around vertically integrated polyol producers with captive bio-feedstock access. Tier-2 foam molders face displacement unless they secure direct offtake agreements with certified renewable polyol sources. This consolidation is most visible in Germany, where BMW and Mercedes-Benz seating programs now specify mass-balance documentation from raw material through finished component.
Green Polyols Market Segmentation
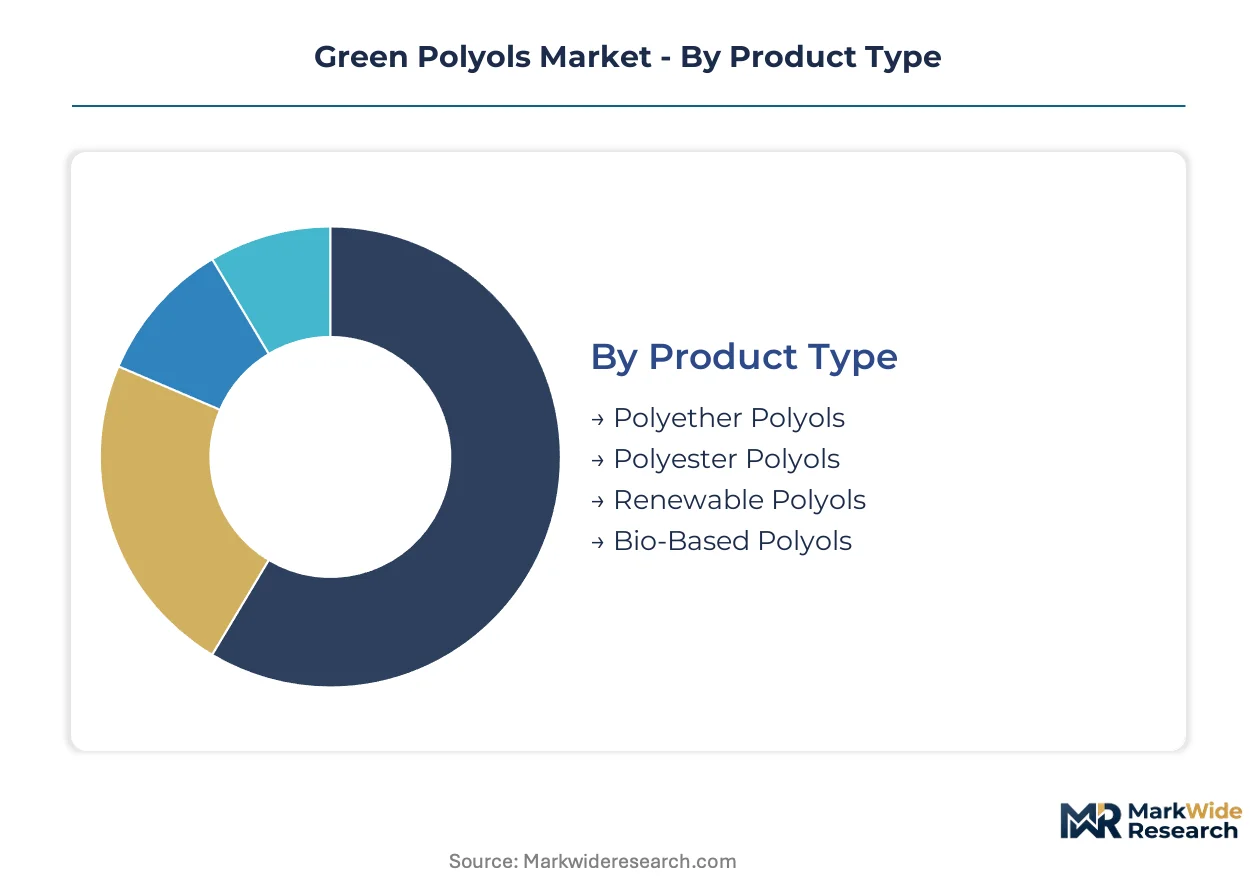
Segmentation in green polyols reveals divergent procurement rhythms across product categories. Polyether systems turn on automotive program cycles while construction-grade rigid foams align with building permit timelines. Understanding these cadences sharpens capacity planning and feedstock contracting strategies.
Product Type:
Polyether polyols rotate through specification cycles fastest due to automotive seating refresh rates, while polyester systems lock into longer furniture and bedding contracts. Bio-based variants exhibit the longest development timelines tied to certification and OEM qualification protocols.
- Polyether Polyols:These materials feature hydroxyl values between 28 and 700 mg KOH/g with primary hydroxyl termination for rapid isocyanate reactivity in polyurethane synthesis. Demand concentrates in Germany where BMW and Mercedes-Benz seating programs enforce mass-balance documentation requirements. REACH chemical disclosure mandates pull formulators toward certified renewable streams.
- Renewable Polyols:Second-generation sugar-based polyether technology is collapsing cost premiums versus petroleum-derived counterparts. Furniture and bedding manufacturers in North America are adopting these materials at accelerating rates as USDA BioPreferred procurement preferences open institutional channels.
- Polyester Polyols:Ester-linked backbone structures provide hydrolytic stability in coating and adhesive applications where durability specifications dominate.
- Bio-Based Polyols:Derived from soy, castor, or sugar intermediates with certified carbon footprint credentials for LEED-compliant construction projects.
Polyether polyols dominate installed base. Renewable polyols are where expansion concentrates.
Application:
Cost tier segmentation separates specification-grade automotive foams from commodity construction insulation. Premium applications command certified bio-content documentation while mid-market flexible foams compete on reformulation economics.
- Flexible Foam:Open-cell polyurethane structures with density ranges of 15-80 kg/m³ for cushioning and comfort applications. Demand clusters in automotive seating where OEM bio-content thresholds now require minimum renewable percentages in polyurethane cushioning systems.
- Rigid Foam:Closed-cell structures with superior thermal insulation properties for construction and appliance applications. Spray foam contractors in Germany and France are accelerating qualification of aliphatic bio-based polyol systems ahead of REACH isocyanate precursor restriction updates.
- Adhesives:Reactive polyurethane systems bonding dissimilar substrates in packaging and assembly operations.
- Coatings:Protective and decorative films leveraging polyol-isocyanate crosslinking chemistry for abrasion resistance.
Flexible foam commands the largest volume position. Rigid foam insulation carries the steepest expansion trajectory as building codes tighten energy efficiency requirements.
End Use Industry:
Customer type segmentation distinguishes specification-driven automotive procurement from price-sensitive furniture manufacturing. Construction occupies an intermediate position where LEED certification creates pull for certified materials without mandating premium pricing.
- Automotive:Seating, interior trim, and acoustic management components with OEM-mandated bio-content thresholds and durability testing protocols. BMW and Mercedes-Benz programs now require mass-balance documentation from raw material through finished component.
- Construction:Rigid foam insulation, spray foam systems, and structural panels where national building codes and LEED certification amplify specification pull for renewable content.
- Furniture:Mattress cushioning, upholstered seating, and bedding foam manufacturing serving retail and institutional procurement channels.
- Electronics:Encapsulation, potting compounds, and thermal management materials for device protection and heat dissipation.
Automotive anchors premium pricing power. Construction is gaining share fastest as commercial building certification expands.
Form:
Supply concentration shapes competitive access across physical states. Liquid systems concentrate around integrated petrochemical and biorefinery producers while solid and powder forms fragment across specialized compounders.
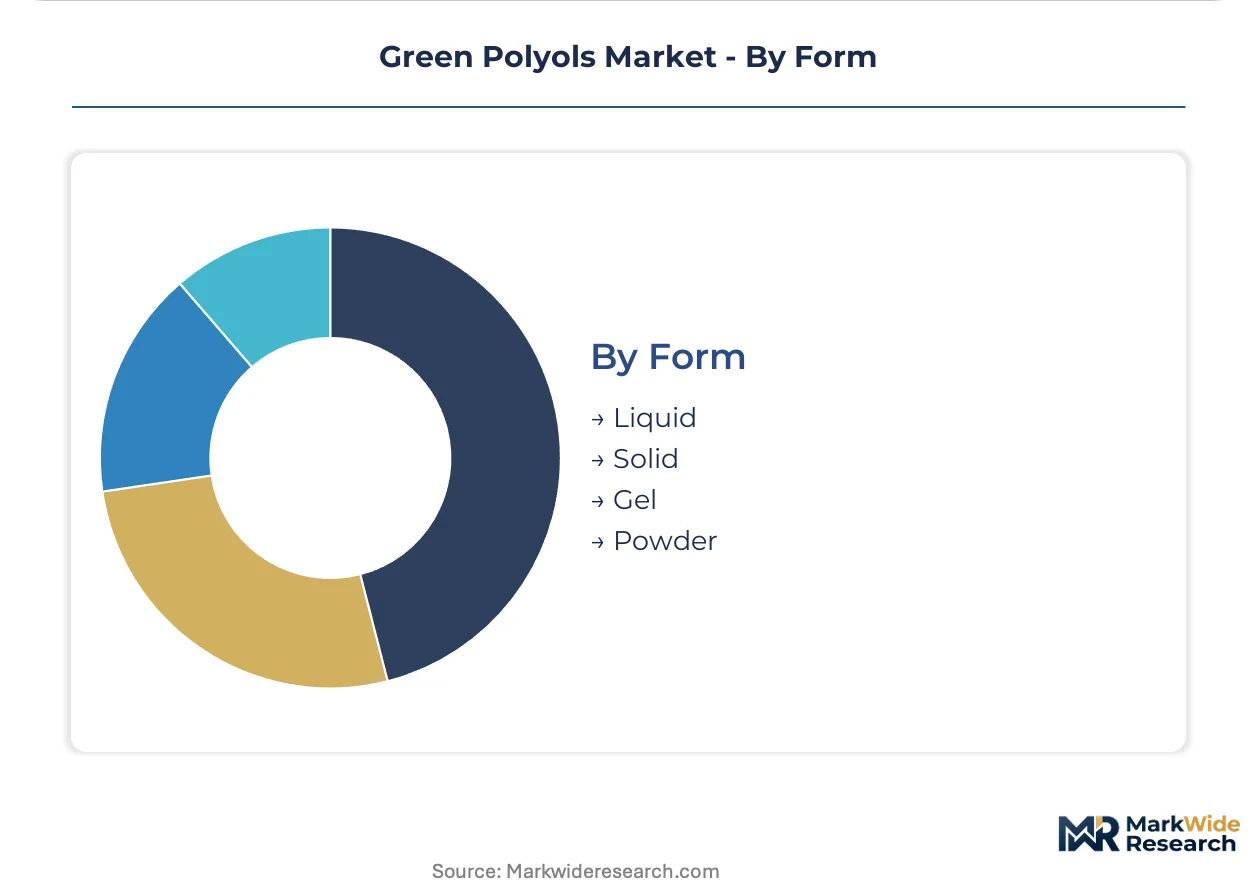
- Liquid:Pumpable polyol systems with controlled viscosity for continuous foam production lines and spray application equipment. Covestro and BASF pilot facilities near Leverkusen and Ludwigshafen control early commercial volumes of liquid renewable polyether systems.
- Solid:Castable or extrudable forms for molding operations and thermoplastic polyurethane compounding.
- Gel:Thixotropic systems for gap-filling and vibration damping applications in transportation and electronics.
- Powder:Free-flowing particulates for reactive hot-melt adhesives and powder coating formulations.
Liquid forms dominate installed base. Solid and gel variants are where formulation innovation concentrates for specialized end-uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Early commercial volumes concentrate in German pilot facilities, with Covestro and BASF controlling capacity near Leverkusen and Ludwigshafen before broader geographic scale-up. This clustering creates supply risk while other regions accelerate biorefinery investments to diversify procurement sources.
Germany
Automotive seating programs at BMW and Mercedes-Benz enforce mass-balance documentation from raw material through finished component. REACH chemical disclosure mandates pull polyurethane formulators toward certified renewable polyether streams. Pilot production facilities near Leverkusen and Ludwigshafen anchor European supply for automotive OEM qualification cycles.
United States
USDA BioPreferred procurement preferences open institutional purchasing channels for furniture and bedding foam manufacturers. EPA bio-preferred labeling extends pressure on formulators to certify bio-based content in specification markets. Soybean oil crush networks in the Midwest feed oleochemical polyol precursor production for regional flexible foam supply.
India
LEED certification adoption in commercial building projects creates specification pull for rigid foam insulation using certified renewable polyols. Castor oil biorefinery clustering in Gujarat secures upstream biomass flows through dedicated crushing and refining infrastructure. The country's national chemical regulator enforces disclosure requirements that align with international certification standards.
France
Spray foam contractors accelerate qualification of aliphatic bio-based polyol systems ahead of REACH isocyanate precursor restriction updates. The national building code tightens energy efficiency requirements for commercial construction, amplifying demand for rigid foam insulation. Industrial chemical producers in the Lyon corridor develop bio-succinic acid routes for polyester polyol diversification.
China
Dual carbon goals drive state-backed investment in sugar-based polyether technology for cost-competitive renewable polyol production. The Ministry of Ecology and Environment encloses stricter carbon accounting for chemical manufacturing, pushing domestic formulators toward bio-based feedstocks. Yangtze River Delta chemical clusters integrate biorefinery capacity into existing polyurethane supply chains.
Green Polyols Market Competitive Environment
Integrated petrochemical conglomerates and specialized oleochemical processors split the market between scale-driven polyether supply and feedstock-diversified niche positioning. Three archetypes dominate: diversified chemical majors with captive R&D pipelines, agribusiness-anchored players controlling upstream oilseed flows, and regional biorefinery specialists leveraging local biomass access. Competitive moves center on backward integration into bio-feedstock cultivation and strategic partnerships for mass-balance certification coverage.
Within the diversified chemical major tier, BASF SE and Covestro AG exemplify integrated players with pilot-scale renewable polyether infrastructure. Cargill occupies a distinct position as an agribusiness-anchored participant with oilseed crush network extension into oleochemical polyol precursors. These three entities represent contrasting pathways to securing qualified supply for automotive and construction specification markets.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| The Dow Chemical Company Inc |
| Cargill |
| Arkema |
| Emery Oleochemicals |
| Huntsman International LLC |
| Mitsui Chemicals Inc |
| Jayant Agro-Organics Limited |
| Others |
Value Chain & Pricing Dynamics
German pilot production concentration near Leverkusen and Ludwigshafen anchors premium pricing tiers, while soybean oil feedstock volatility in North America compresses margins for non-integrated producers. Mass-balance certification costs flow downstream to automotive OEMs as qualification overhead, concentrating margin pools with vertically integrated suppliers.
Pricing Analysis
EU REACH chemical disclosure mandates dictate the pricing tier structure across specification-grade automotive polyols, commodity construction foams, and uncertified industrial grades. Certification tier and volume scale drive price differentiation, with ISCC PLUS documentation commanding premiums over uncertified streams. Pricing pressure stems from second-generation sugar-based polyether technology eroding historical bio-premiums. Automotive seating manufacturers exhibit lowest price sensitivity due to mandated bio-content thresholds, while furniture foam producers face acute margin compression.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for oleochemical precursor flows. Production concentrates in Germany, India, and the United States, with raw material dependencies on soybean oil, castor seed crush, and sugar-based intermediates. Single-source vulnerability around Covestro and BASF pilot facilities creates geographic concentration risk before broader scale-up. Distribution runs through integrated chemical distributors serving automotive Tier 1s and construction spray foam contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green polyols constitute a high-growth materials disruption anchored by EU Green Deal regulatory inflection and automotive OEM bio-content mandates. Second-generation biorefinery technology is collapsing cost premiums and reshaping competitive access.
For Market Incumbents: Insulate qualified supply positions by accelerating mass-balance certification coverage ahead of tightening automotive supplier panel consolidation. Secure long-term castor and soy crush offtakes to neutralize feedstock volatility threats from agribusiness traders. Prioritize R&D investment in rigid foam thermal stability to close performance gaps blocking construction market expansion. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated LEED-certified construction insulation segment before incumbent biorefinery capacity scales. Target regional automotive foam molders displaced by OEM vertical integration demands. Deploy carbon accounting software integration as a differentiated go-to-market angle commanding premium positioning. For Investors and Strategic Acquirers: Capital is best deployed toward agribusiness-anchored processors with captive oilseed crush infrastructure and existing ISCC PLUS certification coverage. Long-term viability hinges on feedstock security rather than formulation chemistry alone. Watch for automotive OEM mass-balance documentation mandates tightening to exclude non-integrated suppliers as the key inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Feedstock Cultivation | Covestro and Cargill secure upstream biomass flows that rivals cannot replicate. |
| Mass-Balance Certification Investment | ISCC PLUS coverage opens automotive OEM supplier panels requiring documentation. |
| Joint Venture for Regional Biorefinery Scale-Up | India construction demand attracts partnerships targeting LEED-certified rigid foam. |
| Long-Term Supply Agreement with Automotive Tier 1 | BMW and Mercedes-Benz seating programs lock in committed renewable polyol volumes. |
| Green Manufacturing Transition | Second-generation sugar-based polyether technology collapses cost premiums versus petroleum. |
Study Parameters
The analysis maps polyether polyols, renewable polyols, polyester systems, and bio-based variants, each validated through procurement leads at automotive OEMs, polyurethane formulators, biorefinery operators, and certification auditors. Primary interviews with plant managers, downstream OEM procurement directors, and technical R&D heads combined with secondary validation from customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH regulatory databases. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Assumptions held fixed include EU Green Deal enforcement trajectory and automotive bio-content mandate adoption rates across German OEMs, while feedstock cost volatility and biorefinery build-out timelines were varied across sensitivity bands. Segmentation dimensions modeled encompass product chemistry, application type, end-use industry, and regional production hub. CAGRs derived from installed base growth rates and replacement demand calculations, with specific inputs including automotive seating refresh cycles and construction permit timelines for rigid foam insulation.
Stress conditions across soybean oil price swings, REACH restriction update timing, and automotive OEM supplier consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on policy continuity and technology cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Polytrimethylene Terephthalate Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Global Resin Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market