
 Polycaprolactone Polyols Market | 2026-2036
Polycaprolactone Polyols Market Size, Share, and Industry Trends Forecast 2026-2036
Polycaprolactone Polyols Market Intelligence
ISO 13485 certification for medical-grade materials is reorganizing the supply landscape for specialized polycaprolactone polyols. This standard creates a high barrier to entry, favoring established producers with stringent quality control systems. Perstorp Holding AB specializes in high-purity grades for demanding applications like thermoplastic polyurethanes. Daicel Corporation leverages its extensive polymer chemistry expertise to develop functionalized polyols for niche segments. Meanwhile, BASF SE operates with significant manufacturing scale, influencing cost structures in the industrial grade market.
Polycaprolactone (PCL) polyols are a class of aliphatic polyester polyols produced through the ring-opening polymerization of caprolactone monomer. These materials are valued for their superior hydrolysis resistance, low-temperature flexibility, and inherent biodegradability. Their primary industrial purpose is to serve as a soft segment in the production of high-performance polyurethanes. Linear polycaprolactone products command the largest volume share, primarily for elastomer production. The coatings and adhesives application segments, however, represent the fastest-growing areas due to demand for durable and weather-resistant formulations.
The market operates under a complex web of international and national regulations. The European Chemicals Agency's (ECHA) REACH framework governs substance registration and safety data for market access in Europe. In the United States, the FDA sets guidelines for polymers intended for food contact applications, affecting packaging uses. China's GB standards impose specific requirements on industrial chemicals, impacting imports and local production. Future material selection will hinge on balancing the performance benefits of PCL polyols with evolving sustainability mandates and cost pressures.
Market Dynamics
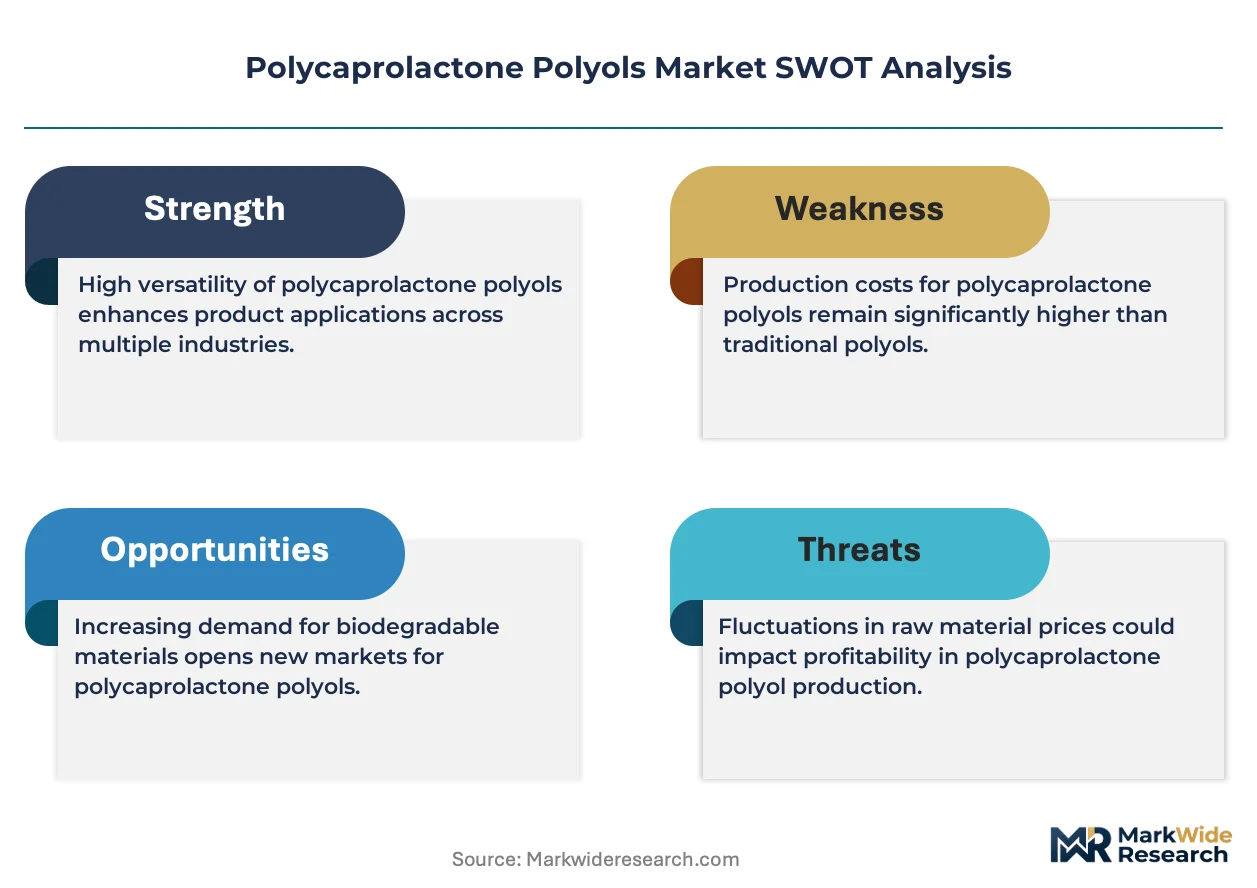
The central force shaping the polycaprolactone polyols market is the divergence between specialized, high-margin applications and commoditized industrial segments. This split is driven by stringent regulatory frameworks like ISO 13485 and cost pressures from large-scale manufacturing in specific regions.
Growth Catalysts
- Footwear Sector Expansion:Sustained growth in athletic and casual footwear manufacturing, particularly in Asia, increases demand for PCL-based thermoplastic polyurethanes for durable soles.
- Sustainability Mandates:European Union policies promoting biodegradable materials in single-use items create pull-through demand for PCL in niche packaging and compostable plastic applications.
- Industrial Concentration in China:Demand is increasingly concentrating within China's industrial hubs for use in textiles, adhesives, and packaging, requiring high-performance polymers.
Market Restraints
- Feedstock Price Volatility:The market is sensitive to price fluctuations of caprolactone monomer, a key raw material whose cost impacts overall PCL polyol production economics.
- Substitution Threat:In cost-sensitive applications like general-purpose adhesives, PCL polyols face competition from lower-priced alternatives such as polyethylene adipate (PEA) polyols.
- Processing Cycle Times:The relatively slower crystallization rate of PCL compared to some other polyesters can be a limitation in high-speed manufacturing processes like injection molding.
Strategic Opportunities
- 3D Printing Filaments:The unique properties of PCL, including its low melting point and biocompatibility, create opportunities for developing specialized filaments for medical and prototype 3D printing.
- Biomedical Applications:Increasing demand for long-term implantable devices and drug delivery systems in markets like Japan and Germany opens avenues for high-purity, ISO 13485-certified grades.
- Bio-based Feedstocks:Developing commercially viable routes to bio-based caprolactone monomers would allow producers to offer a fully renewable PCL polyol, meeting corporate sustainability goals.
Industry Challenges
- Medical-Grade Certification:The extensive time and capital required to achieve and maintain ISO 13485 certification for medical-grade materials creates a significant operational hurdle for producers.
- Supply Chain Purity:Ensuring lot-to-lot consistency and preventing contamination across the supply chain is a constant challenge, especially for grades destined for electronics and medical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycaprolactone Polyols Market |
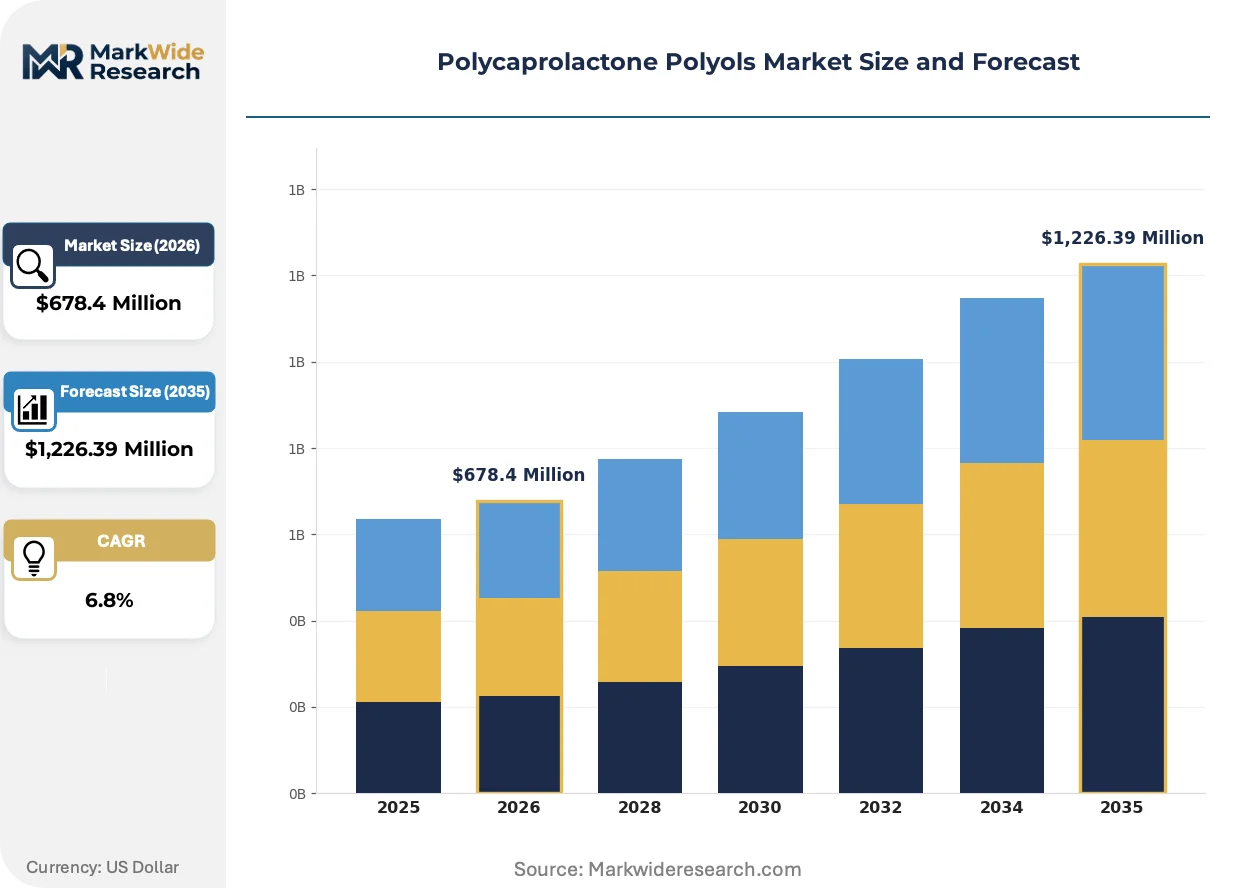
| Market Size in 2026 | $678.4 Million |
| Market Size in 2035 | $1,226.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Polycaprolactone, Branched Polycaprolactone, Crosslinked Polycaprolactone, Functionalized Polyols Grade: Standard Grade, High Purity Grade, Medical Grade, Industrial Grade, Specialty Grade Application: Elastomers, Coatings, Adhesives, Sealants, Textile Finishing End User Industry: Footwear Manufacturing, Packaging Producers, Paints & Coatings, Textile Mills, Composite Fabricators |
| Companies Covered | Perstorp Holding AB, Esun Industrial Co., Ltd., Ingevity Corporation, Sinopec Shanghai Gaoqiao Company, Juren, Daicel Corporation, Stepan Company, Shell Chemicals Ltd., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycaprolactone Polyols Market Strategic Shifts & Innovations
Market evolution is defined by a distinct bifurcation between high-value, certified grades and cost-competitive industrial polyols. This dynamic influences everything from material innovation and regulatory strategy to how end-users structure their supply agreements.
Functionalized PCL polyols introduce specific chemical groups to the polymer backbone for tailored reactivity and performance. Specialty formulators in adhesives and coatings are adopting these materials to achieve unique properties. This development is fragmenting the standard linear polyol market into a series of high-performance, application-specific niches with distinct value propositions.
The European Union's REACH regulation governs substance registration, evaluation, and authorization for chemicals sold within the bloc. This framework imposes significant data generation and compliance costs on manufacturers and importers. The coatings and adhesives segments are most affected, often reformulating products to align with safety dossiers and avoid restricted substances.
A notable shift in purchasing behavior involves prioritizing material certification over pure cost metrics in specific sectors. Buyers of medical-grade and food-contact polymers now require suppliers to provide extensive documentation proving compliance with FDA or ISO standards. This trend is most pronounced in North America and Europe, altering supplier selection criteria.
Polycaprolactone Polyols Market Segmentation
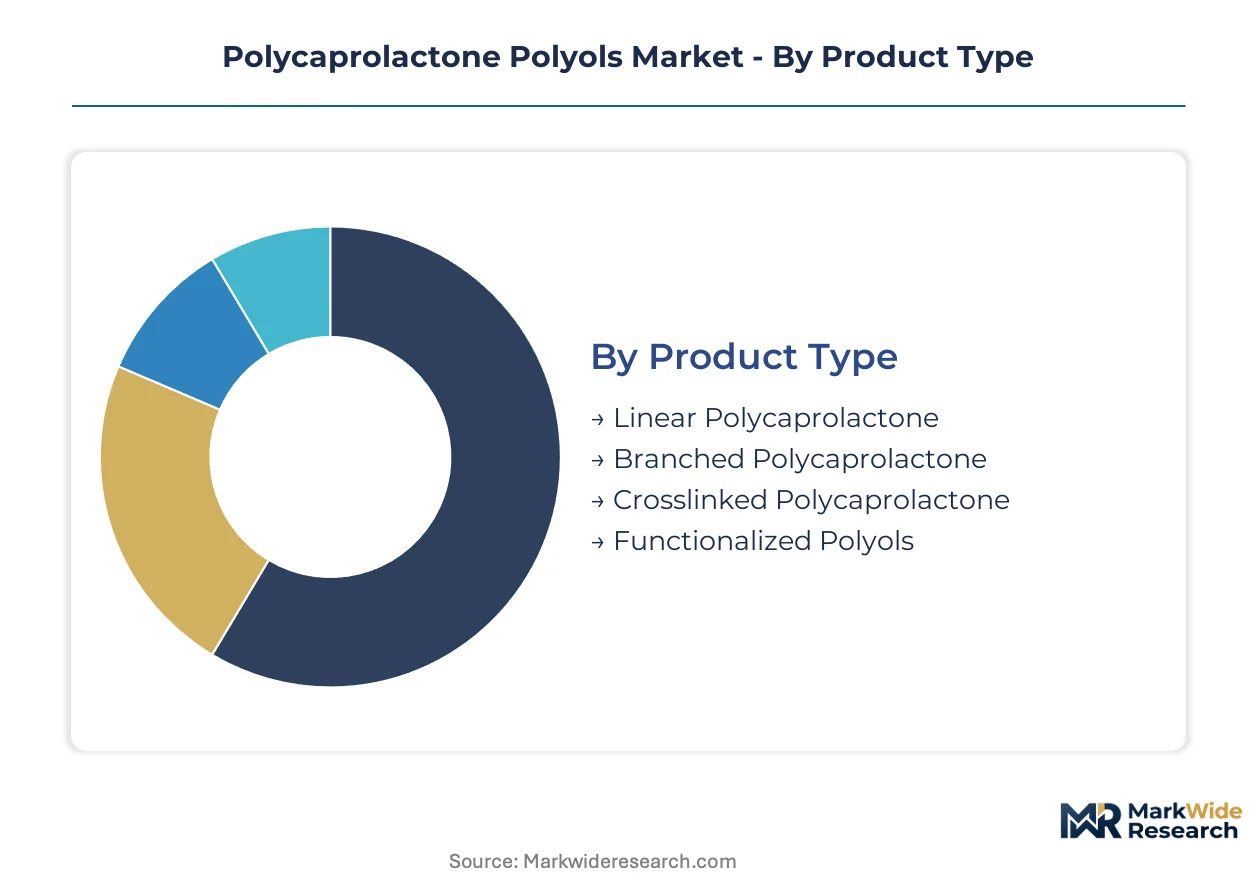
The polycaprolactone polyols market exhibits clear segmentation across product types, grades, applications, and end-user industries. Understanding these distinctions is crucial for identifying specific demand drivers and regulatory influences shaping market dynamics. Each segment responds differently to technological advancements and evolving sustainability mandates.
Product Type:
Regulatory differentiation significantly impacts the product type segment, particularly concerning material safety and environmental compliance.
- Linear Polycaprolactone:This product type consists of straight polymer chains, offering excellent flexibility and mechanical properties. Demand concentrates in elastomer production across Asia, driven by its use in high-performance footwear components.
- Functionalized Polyols:These polyols incorporate specific chemical groups for tailored reactivity, enhancing performance in specialized formulations. Specialty formulators in Germany and Japan increasingly adopt these materials for advanced adhesives and coatings.
- Branched Polycaprolactone:Branched structures influence viscosity and reactivity, making them suitable for specific polyurethane applications requiring different flow characteristics.
- Crosslinked Polycaprolactone:These polyols form three-dimensional networks, providing enhanced durability and chemical resistance in demanding industrial uses.
Linear polycaprolactone handles the majority of throughput; functionalized polyols are the fastest mover on share.
Grade:
Cost tiering shapes the grade segment, with specific performance requirements dictating material selection and pricing structures.
- Medical Grade:These materials meet stringent biocompatibility and purity standards, often requiring ISO 13485 certification. Demand for medical-grade PCL polyols is strong in Japan and Germany for implantable devices and drug delivery systems.
- Industrial Grade:Produced at significant manufacturing scale, industrial grades serve high-volume applications where cost-effectiveness is paramount. Large-scale polyurethane manufacturing in China extensively utilizes industrial-grade polycaprolactone polyols.
- Standard Grade:Standard grades represent a balance of performance and cost, suitable for general-purpose applications that do not require extreme specifications.
- High Purity Grade:These grades offer enhanced purity beyond standard industrial specifications, critical for electronics and sensitive coating applications.
- Specialty Grade:Specialty grades are formulated for niche applications, providing unique properties such as enhanced biodegradability or specific processing characteristics.
High-purity grades command premium pricing, while industrial grades drive overall market volume.
Application:
End-use performance drives differentiation across application segments, with specific properties tailored for diverse industrial requirements.
- Coatings:PCL polyols impart durability, flexibility, and weather resistance to coating formulations. The automotive and construction sectors in Europe demand these for long-lasting, protective finishes.
- Adhesives:These materials enhance bond strength, flexibility, and hydrolysis resistance in adhesive systems. Packaging and textile industries in China increasingly use PCL-based adhesives for improved product integrity.
- Elastomers:PCL polyols serve as soft segments in thermoplastic polyurethanes, providing excellent low-temperature flexibility and tear strength.
- Sealants:In sealant formulations, PCL polyols contribute to elasticity and adhesion, particularly in demanding environmental conditions.
- Textile Finishing:PCL polyols improve the feel, durability, and water resistance of textiles, especially in performance apparel.
Elastomers maintain significant volume, but coatings and adhesives exhibit the steepest expansion trajectory.
End User Industry:
Specific market drivers influence demand patterns across end-user industries, reflecting varying needs for PCL polyol properties.
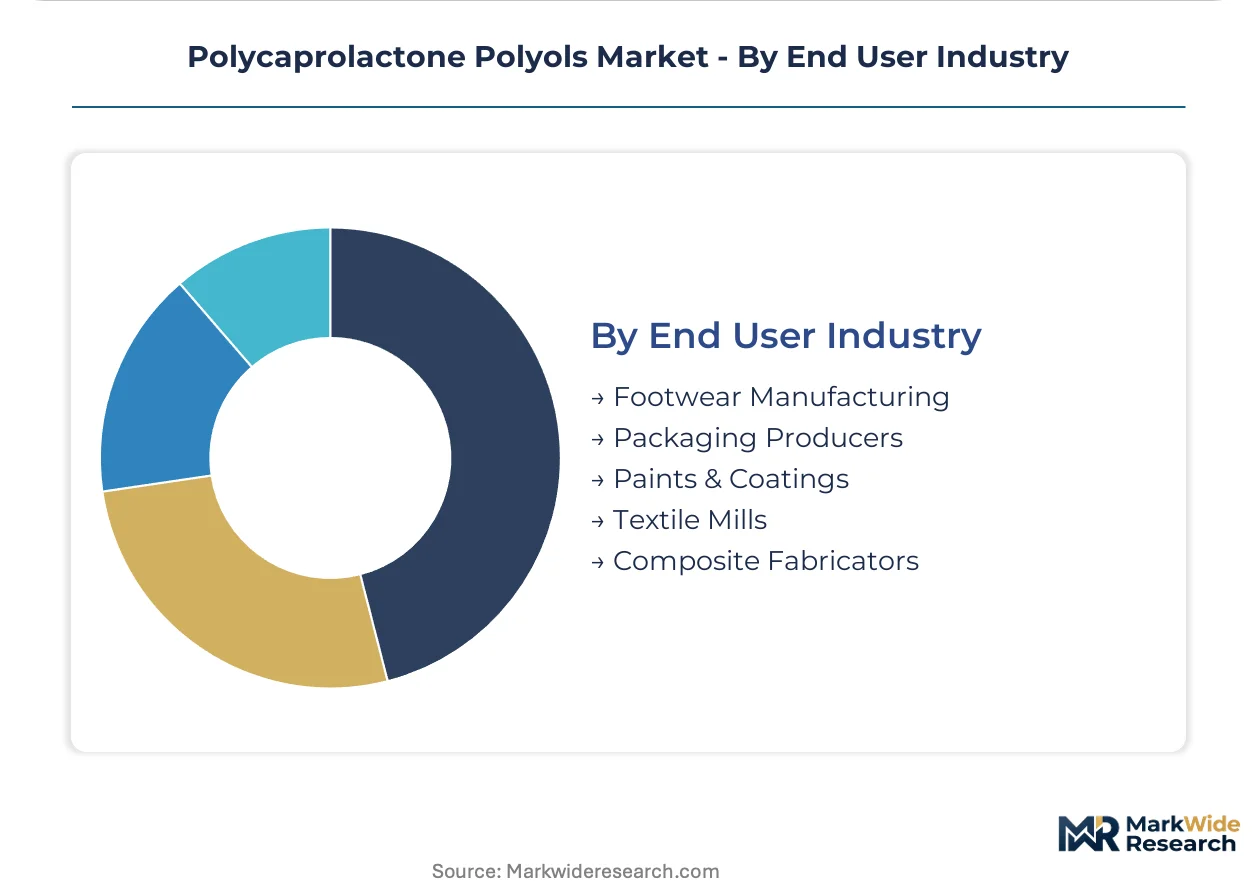
- Footwear Manufacturing:This sector utilizes PCL-based thermoplastic polyurethanes for durable and flexible soles, particularly in athletic footwear. Growth in footwear production across Southeast Asia directly boosts demand for PCL polyols.
- Packaging Producers:PCL polyols are incorporated into biodegradable films and coatings for sustainable packaging solutions. European Union sustainability mandates drive demand for PCL in compostable plastic applications.
- Paints & Coatings:The paints and coatings industry values PCL polyols for their contribution to weather-resistant and flexible formulations.
- Textile Mills:Textile mills use PCL polyols in finishes to enhance fabric properties like softness, strength, and water repellency.
- Composite Fabricators:PCL polyols can be integrated into composite materials to improve impact resistance and flexibility.
Footwear manufacturing remains a primary consumer, with packaging producers showing substantial growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European Union sustainability mandates, particularly those promoting biodegradable materials, significantly influence the global polycaprolactone polyols market. These policies create specific pull-through demand for PCL in niche packaging and compostable plastic applications across member states. Regional regulatory frameworks and industrial concentrations drive varied growth trajectories for high-performance polymers.
United States
Demand for PCL polyols in the United States stems from the growing medical device sector and specialized packaging. The FDA's guidelines for polymers in food contact applications shape material selection for packaging uses. Industrial clusters in California and Massachusetts drive innovation in biomedical applications and high-purity grades.
Germany
Germany's market for PCL polyols benefits from its robust automotive and advanced materials industries, requiring durable coatings and adhesives. ECHA's REACH framework governs substance registration, influencing product development for European market access. The Rhine-Ruhr region, a major chemical manufacturing hub, sees significant production and application development for industrial grades.
China
China's industrial hubs concentrate demand for PCL polyols in textiles, adhesives, and packaging applications. The country's GB standards impose specific requirements on industrial chemicals, impacting local production and imports. Manufacturing centers in the Yangtze River Delta actively utilize industrial-grade polycaprolactone polyols for large-scale polyurethane production.
Japan
Japanese demand for PCL polyols is strong in biomedical applications and functionalized polyols for niche segments. METI regulations support advanced materials research and development, fostering innovation in polymer chemistry. Companies in the Kanto region leverage extensive polymer chemistry expertise to develop specialized polyols for high-performance coatings.
India
India's expanding footwear manufacturing sector and growing packaging industry drive demand for PCL-based thermoplastic polyurethanes. BIS standards influence material quality and safety for various industrial applications. Textile mills and footwear production facilities in states like Tamil Nadu are increasing their consumption of PCL polyols for durable products.
Polycaprolactone Polyols Market Key Industry Players
Player mix skews toward established chemical giants and specialized polymer producers, creating a tiered competitive structure. The market sees a clear distinction between companies focusing on high-volume industrial grades and those targeting niche, high-purity applications. Strategic archetypes include large-scale industrial chemical suppliers, specialty polymer innovators, and vertically integrated material science firms. Competitive moves often involve capacity expansion in industrial grades and strategic partnerships for specialized product development.
On the premium-tier vector, Perstorp Holding AB occupies a position as a specialist in high-purity grades for demanding applications like thermoplastic polyurethanes. Daicel Corporation, a Japanese-based chemical company, exemplifies an innovator leveraging extensive polymer chemistry expertise to develop functionalized polyols for niche segments. BASF SE, a German multinational chemical company, anchors the scale-driven end, operating with significant manufacturing capacity that influences cost structures in the industrial grade market.
| Leading Market Players |
|---|
| Perstorp Holding AB |
| Esun Industrial Co., Ltd. |
| Ingevity Corporation |
| Sinopec Shanghai Gaoqiao Company |
| Juren |
| Daicel Corporation |
| Stepan Company |
| Shell Chemicals Ltd. |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Substitution threats from lower-priced polyethylene adipate (PEA) polyols simultaneously reshape supply chain geography and pricing economics for general-purpose applications. This dynamic forces PCL polyol producers to differentiate through performance or cost efficiency.
Pricing Analysis
Certification level (ISO 13485 for medical-grade) creates the primary spread in polycaprolactone polyols pricing. The dominant pricing model is contract-based long-term offtake for industrial volumes, supplemented by transactional spot pricing for smaller, specialized orders. Price differentiation stems from both the specific quality grade and the volume scale of the purchase. Pricing softness arises from feedstock volatility of caprolactone monomer and competition from substitute materials. Buyers of industrial-grade polyols are most price-sensitive, while medical device manufacturers prioritize compliance over cost.
Supply Chain Analysis
Port congestion and container availability impact inbound logistics costs for caprolactone monomer, a critical raw material. Supply concentration for PCL polyols centers on manufacturing hubs in China, Germany, and Japan. The supply chain relies heavily on caprolactone monomer, creating a structural risk from feedstock price volatility. Downstream distribution runs through direct sales channels for large industrial customers and specialized distributors for niche, high-purity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market growth for high-performance polycaprolactone polyols reveals a capability gap in achieving and maintaining specialized certifications like ISO 13485. This gap presents a significant barrier for new entrants but also an opportunity for established players.
For Market Incumbents: Fortify existing market positions by investing heavily in ISO 13485 certification processes and expanding R&D into bio-based caprolactone monomers. This protects against substitution threats from lower-cost alternatives and addresses evolving sustainability mandates. Consolidate market share in industrial grades through capacity additions in strategic Asian manufacturing hubs to leverage economies of scale.
For New Entrants and Emerging Players: Technical service support for specialized functionalized polyols represents a service-layer gap that incumbents often under-serve. Target niche applications in 3D printing filaments and advanced biomedical devices, focusing on materials with unique processing characteristics. A direct sales approach, coupled with strong technical advisory for specialized formulators, offers a viable go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized polymer producers with proven regulatory compliance and innovation capabilities. Long-term viability is strong for companies deeply embedded in high-value applications like medical devices and advanced coatings. Acquire mid-sized firms possessing proprietary functionalization technologies or established ISO 13485-certified production facilities. Watch for the commercial viability of bio-based caprolactone monomers as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Industrial Grades | Increases cost competitiveness and market share in high-volume polyurethane manufacturing in China. |
| Green Manufacturing Transition | Allows producers to offer fully renewable PCL polyols, aligning with corporate sustainability goals. |
| Long-term Supply Agreements for Monomer | Mitigates feedstock price volatility and ensures consistent production for PCL polyols. |
| Joint Ventures in Functionalized Polyols | Accelerates development of specialized materials for advanced adhesives and coatings applications. |
| Investment in ISO 13485 Certification | Opens access to high-margin medical and biomedical applications in Japan and Germany. |
Research Approach
Operator-level perspectives from R&D directors, procurement leads, plant managers, and regulatory affairs specialists anchored the qualitative base. This primary fieldwork was triangulated with extensive secondary research, including ECHA REACH filings, FDA guidelines, China's GB standards, and corporate financial reports. Bottom-up and top-down approaches ensured comprehensive data validation.
Sensitivity analysis framed the quantitative model, projecting market dynamics across the analysis window. The framework segmented the market by product type, grade, application, end-user industry, and regional regulatory clusters. Compound annual growth rates were derived based on historical trends, projected market drivers, and key forecast inputs like caprolactone monomer pricing and footwear manufacturing growth rates.
Forecasts assume regulatory continuity in European Union, US, and Chinese regimes; material policy shifts would require re-modeling. These projections reflect documented assumptions, acknowledging that unforeseen changes in environmental regulations or feedstock supply disruptions could revise outcomes. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market