
 Soft PVC Sealing Strip Market | 2026-2036
Soft PVC Sealing Strip Market Size, Share, and Industry Trends Forecast 2026-2036
Soft PVC Sealing Strip Market Insights
Multi-source procurement among tier-one automotive suppliers is consolidating around extrusion specialists with captive polymer compounding capabilities. Saint-Gobain leverages its European compounding network to supply OEM-specified grades directly to assembly plants. Trelleborg anchors its position through marine and infrastructure applications where salt-water resistance differentiates product lines. Frost King competes primarily in retail channels, sustaining volume through hardware store distribution and contractor loyalty programs.
Soft PVC sealing strip denotes a flexible thermoplastic extrusion, typically formulated with 40-60 phr plasticizer content and Shore A hardness between 55 and 85, produced via single-screw extrusion with downstream calibration and cooling. These strips function primarily as compressible barriers against air, moisture, dust, and acoustic transmission in assembled joints. Self-adhesive variants command premium positioning in retrofit construction where installer labor cost drives specification, while foam-backed grades capture expanding share in automotive NVH applications. Custom solutions concentrate margin pools in aerospace and medical equipment sealing where lot traceability and compound certification requirements limit supplier eligibility.
REACH restrictions on phthalate plasticizers and the EU F-Gas Regulation governing insulating glass units shape compound reformulation roadmaps across European manufacturing bases. China's GB standards for building products and SAMR quality supervision protocols determine market access for domestic and imported strip producers. India's BIS certification requirements for PVC construction materials create compliance thresholds that favor established extruders with testing laboratory partnerships. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant certification investments.
Market Dynamics
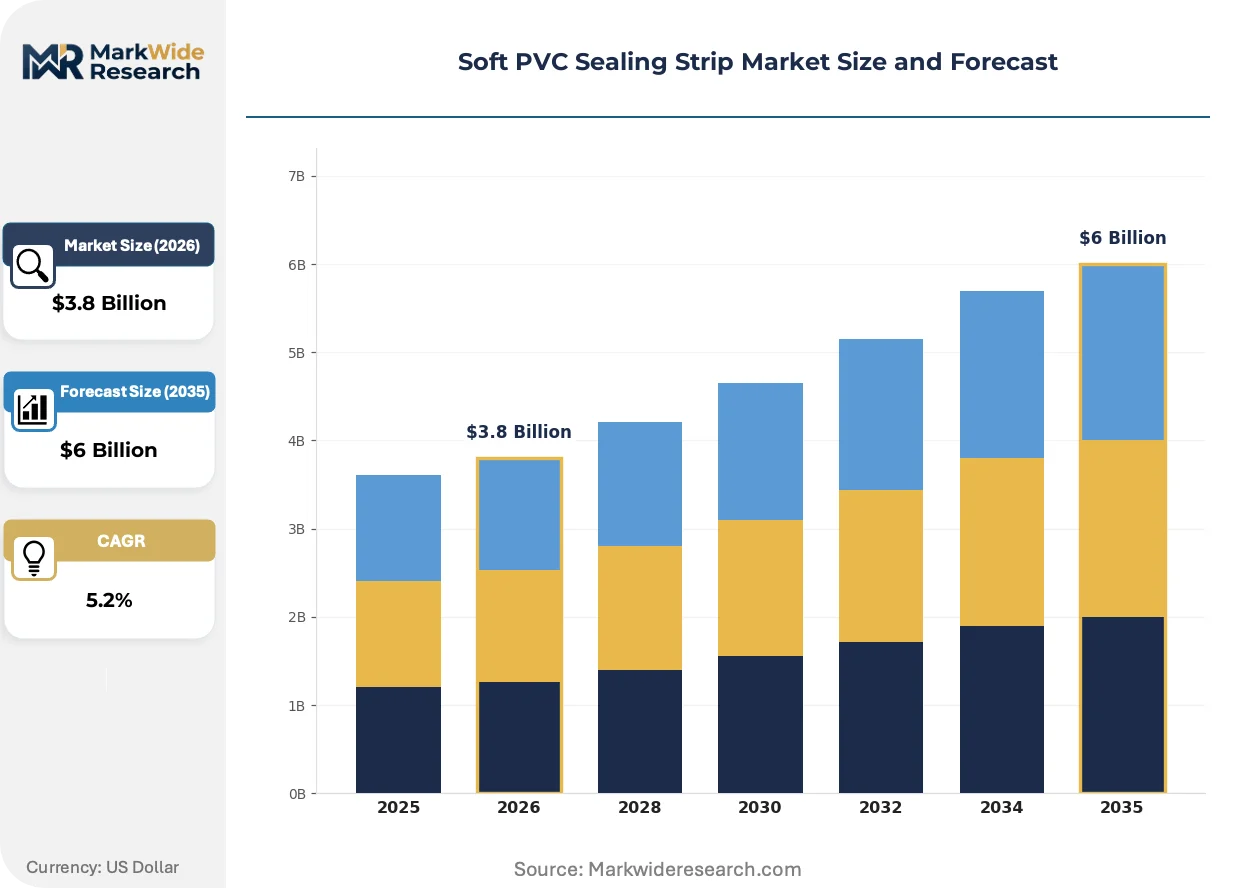
Automotive NVH mandates and phthalate-free reformulation pressures are compressing supplier margins while rewarding extruders with captive compounding and multi-jurisdiction certification capabilities. The tension between REACH compliance costs and OEM price pressure is restructuring procurement relationships around integrated supply partnerships rather than spot purchasing.
Growth Catalysts
- REACH phthalate restrictions:European ECHA enforcement is accelerating migration to bio-based plasticizers, creating first-mover advantage for compounders with validated alternative formulations.
- Automotive cabin noise regulations:Germany's KBA and China's MIIT are tightening NVH standards, pulling foam-backed sealing strip volumes into assembly plant direct supply agreements.
- Shanghai-Guangzhou manufacturing corridor concentration:East Asian automotive and appliance OEM clustering is generating localized demand density that favors regional extrusion specialists with just-in-sequence delivery capability.
Market Restraints
- Plasticizer cost volatility:Epoxidized soybean oil and DINCH alternatives trade at premiums to legacy phthalates, compressing compounder margins during raw material price spikes.
- East Asian supply concentration:Resin and additive production clusters in Zhejiang and Jiangsu provinces create geographic risk exposure for European and North American strip converters.
- Thermoplastic elastomer substitution:TPV and TPE materials are capturing specification share in premium automotive sealing where compression set performance exceeds PVC capabilities.
Strategic Opportunities
- Indian BIS certification pathway:Construction material standards enforcement is creating compliance barriers that favor established extruders with Mumbai and Delhi testing laboratory partnerships.
- Medical equipment sealing:Lot traceability and USP Class VI compound certification requirements limit supplier eligibility, concentrating margin pools among qualified compounders.
- Self-adhesive retrofit channel:Hardware store and contractor direct distribution is bypassing traditional distribution markups in residential window and door replacement markets.
Industry Challenges
- Multi-jurisdiction formulation management:Maintaining parallel compound portfolios for REACH-compliant European grades, GB-standard Chinese grades, and FDA-acceptable medical grades strains R&D bandwidth and inventory working capital.
- Single-screw extrusion equipment obsolescence:Precision tolerance requirements for automotive direct supply are forcing capital replacement cycles among mid-tier extruders lacking twin-screw co-extrusion capability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft PVC Sealing Strip Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
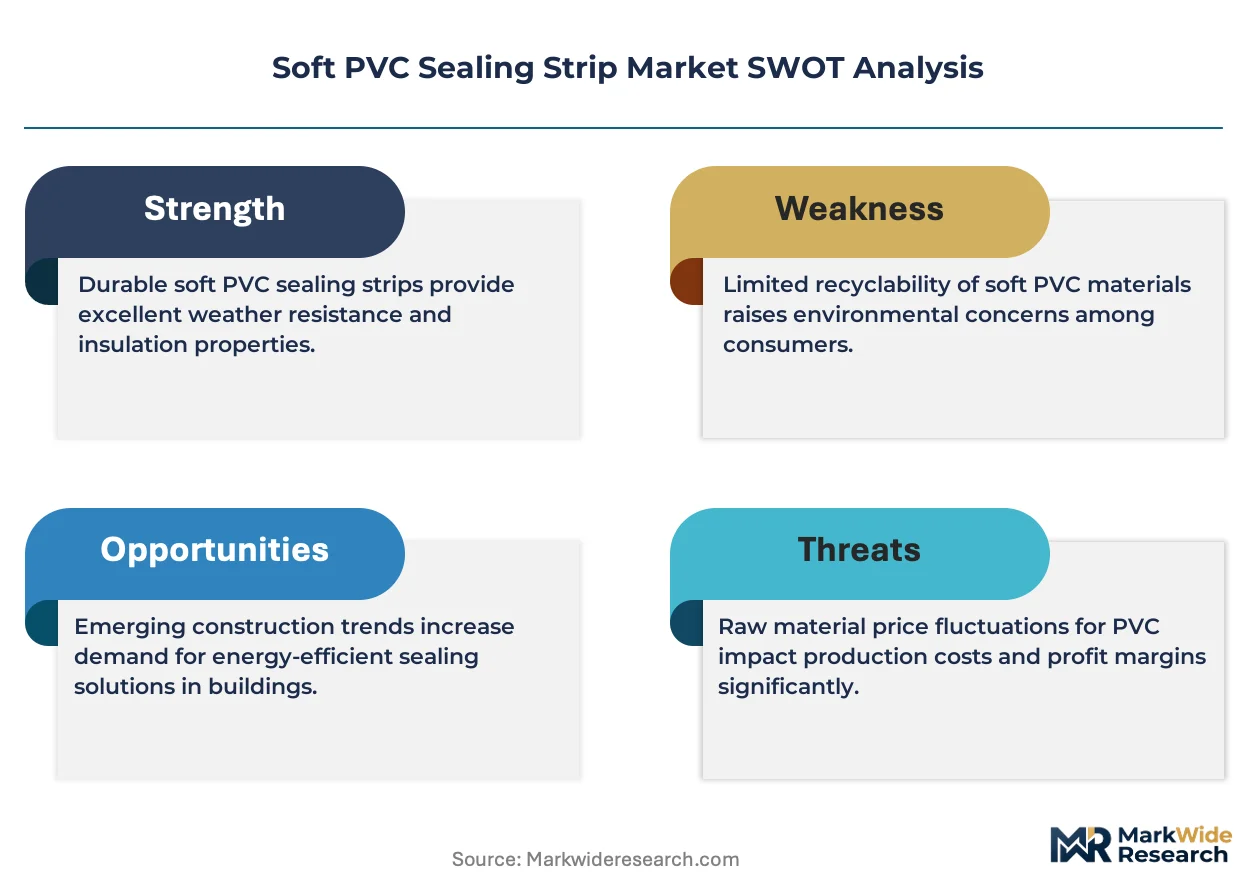
| Segmentation | Product Type: Self-Adhesive, Non-Adhesive, Foam-Backed, Custom Solutions End User: Automotive, Construction, Electronics, Appliances Application: Window Sealing, Door Sealing, HVAC Systems, Insulation Thickness: 1mm, 2mm, 3mm, 5mm |
| Companies Covered | SealTech, Saint-Gobain, M-D Building Products, Schlegel International, Trelleborg, Frost King, 3M, Greiner Extrusion, Royal Building Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft PVC Sealing Strip Market Trends and Innovations
Reformulation chemistry and extrusion process control are converging to enable thinner-wall, higher-performance sealing geometries that reduce material intensity per meter while maintaining compression seal reliability. The competitive frontier is shifting from commodity volume toward certified compound stewardship and application engineering.
Co-extrusion with integrated foam backing is integrating acoustic damping layers directly into the PVC substrate during single-pass extrusion, eliminating secondary lamination steps. Tier-one automotive suppliers in Stuttgart and Wolfsburg are specifying these integrated constructions for A-pillar and door seal applications. The technology is integrating NVH performance with assembly plant line speed requirements, compressing the traditional foam-tape supply chain into captive extrusion cell operations.
EU F-Gas Regulation phase-down schedules are pressuring insulating glass unit manufacturers to verify thermal break performance of perimeter sealing compounds. ECHA substance evaluation protocols are extending documentation requirements to plasticizer migration rates in building product applications. French window and facade system manufacturers are responding with pre-certified compound specifications that lock supplier relationships before tendering.
Specification authority is migrating from distributor sales forces to OEM material engineering departments with direct compound qualification protocols. Hardware store chains and building merchant cooperatives are losing influence over contractor product selection as automotive and appliance OEMs consolidate procurement through approved vendor lists. This concentration is most visible in the Rhine-Ruhr industrial region where facade system manufacturers have reduced active sealing strip suppliers from twelve to four qualified compounders.
Soft PVC Sealing Strip Market Segmentation
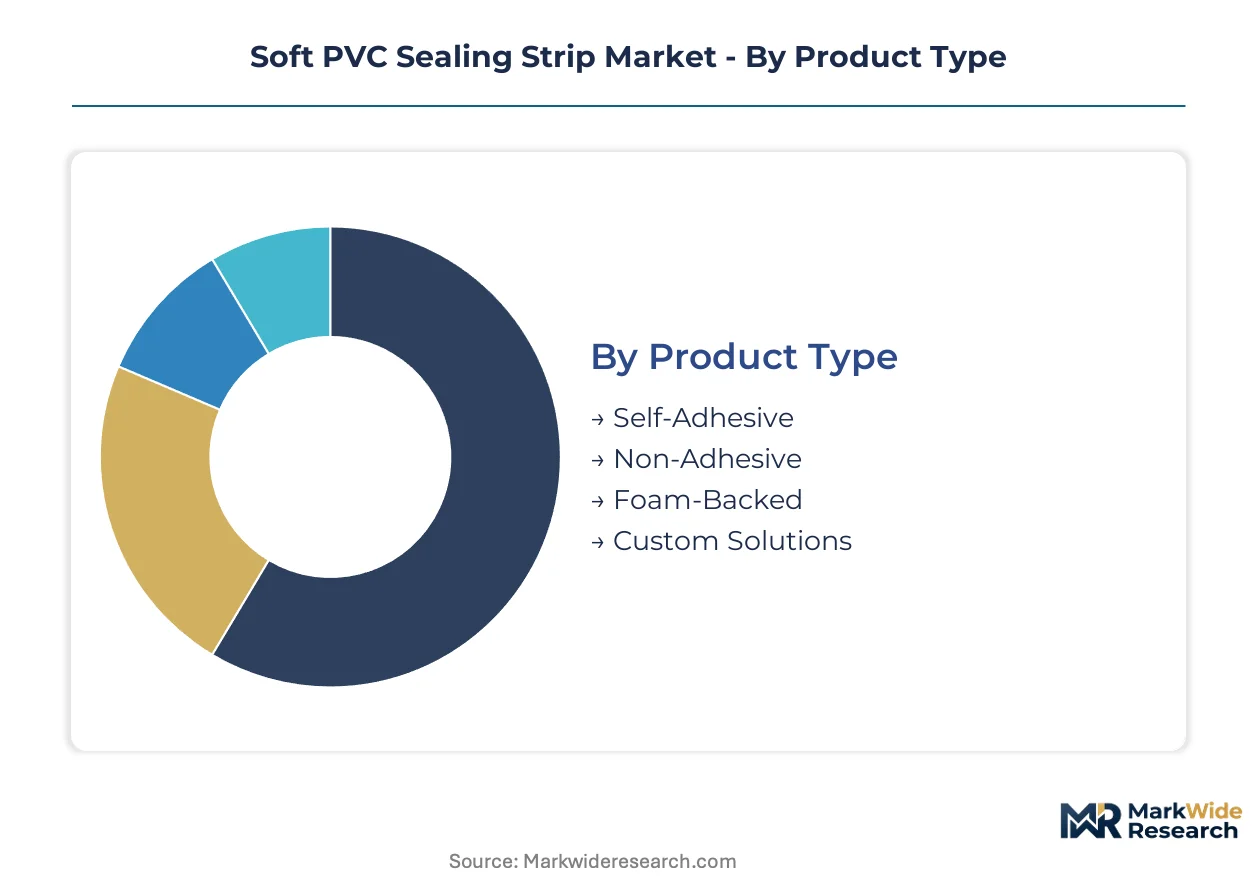
Segmentation in the Soft PVC Sealing Strip Market reflects divergent technical requirements across upgrade cycles. Automotive NVH mandates and building energy retrofit programs are pulling demand toward specialized formulations that command specification authority through certified compound stewardship.
Product Type:
Replacement decisions in this category track the tension between installer labor economics and performance durability in demanding environments.
- Self-Adhesive:Pre-applied pressure-sensitive adhesive layers eliminate field-applied bonding steps, capturing premium positioning in residential window retrofit channels where contractor labor cost drives specification. Demand concentrates in North American hardware store distribution and European building merchant cooperatives serving replacement construction.
- Foam-Backed:Integrated cellular PVC or PE foam substrates deliver acoustic damping and thermal break performance, pulling volumes into automotive A-pillar and door seal applications. Germany's KBA and China's MIIT are tightening cabin noise regulations that favor these constructions in direct OEM supply agreements.
- Non-Adhesive:Compression-fit profiles rely on interference fit or mechanical retention in assembled joints, serving industrial equipment and infrastructure applications where adhesive degradation poses reliability risks.
- Custom Solutions:Lot-traceable compounds with USP Class VI or aerospace certification command concentrated margin pools in medical equipment and aircraft sealing where supplier eligibility remains restricted.
Non-Adhesive sits at the top of the volume ranking, with Foam-Backed climbing the fastest.
End User:
Cost tier differentiation separates specification-grade supply relationships from spot-purchased commodity volumes across end-use sectors.
- Automotive:NVH-compliant foam-backed grades with Shore A hardness between 55 and 85 serve cabin sealing applications. Stuttgart and Wolfsburg assembly plants are consolidating procurement around extruders with captive compounding and just-in-sequence delivery capability.
- Construction:Window and facade perimeter sealing dominates volume, with EU F-Gas Regulation phase-down schedules pressuring insulating glass unit manufacturers toward verified thermal break compounds. French system manufacturers are locking supplier relationships through pre-certified specifications.
- Electronics:Dust and moisture ingress protection for enclosures and cable management systems favors thin-wall extrusions with tight dimensional tolerance.
- Appliances:Door gasket and vibration isolation applications in white goods manufacturing concentrate demand in East Asian appliance production corridors around Shanghai and Guangzhou.
Construction commands the largest revenue pool, while Automotive is expanding most quickly.
Application:
Volume concentration in this category maps directly to building stock age and regulatory enforcement intensity across jurisdictions.
- Window Sealing:Perimeter compression seals for insulating glass units and frame interfaces serve both new construction and energy retrofit programs. ECHA substance evaluation protocols are extending documentation requirements to plasticizer migration rates in building product applications.
- Door Sealing:Threshold and jamb profiles balance air infiltration control with operational durability in high-cycle commercial entrances.
- HVAC Systems:Ductwork and air handling unit gasketing demands flame-retardant formulations meeting localized fire safety codes.
- Insulation:Thermal break and vapor barrier applications in building envelopes favor closed-cell foam-backed constructions.
Window Sealing generates the highest shipment volumes, with Insulation gaining share fastest.
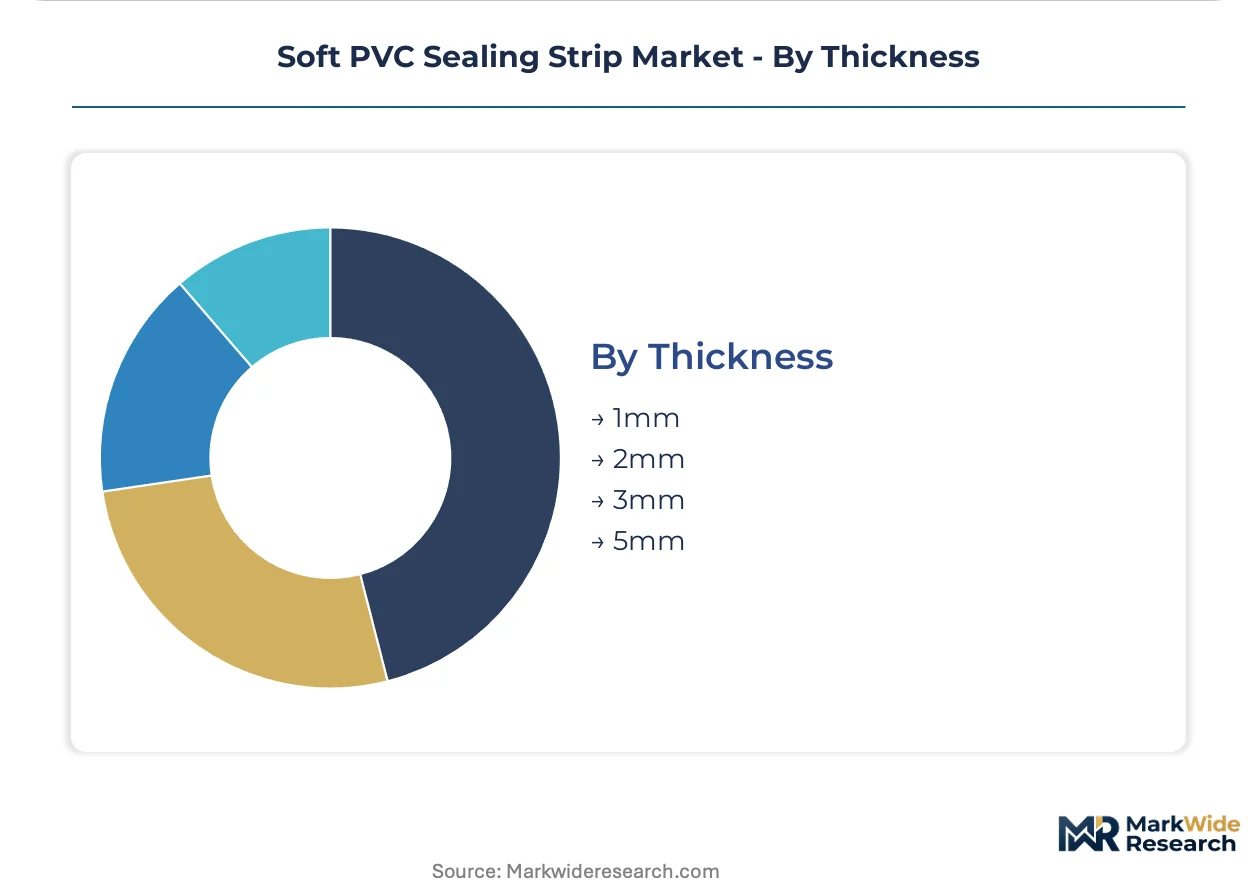
Thickness:
Supply concentration in this category reflects equipment capability thresholds and raw material efficiency optimization among extrusion specialists.
- 3mm:Balanced compression set and material economy makes this the default specification across automotive and construction applications. Single-screw extrusion lines achieve reliable dimensional control at this gauge.
- 5mm:Heavy-duty profiles for industrial equipment and infrastructure sealing require twin-screw co-extrusion capability that limits qualified supplier pools.
- 1mm:Precision electronics and medical device sealing demands tight tolerance control that forces capital replacement cycles among mid-tier extruders.
- 2mm:Intermediate gauge serving appliance gasketing and light commercial applications where material cost sensitivity moderates specification.
3mm dominates production tonnage, with 1mm showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Guangzhou manufacturing corridor anchors Soft PVC Sealing Strip Market demand, pulling compound volumes into automotive assembly plants and appliance production hubs across East Asia, Western Europe, and North America.
China
MIIT cabin noise mandates and SAMR quality supervision protocols are tightening specification requirements for automotive NVH grades. GB standard updates for building products are phasing out legacy plasticizer formulations in construction applications. Zhejiang and Jiangsu resin clusters supply feedstock to extrusion specialists serving the Yangtze River Delta automotive corridor.
Germany
KBA enforcement of stricter cabin noise regulations is accelerating foam-backed sealing strip adoption in Stuttgart and Wolfsburg assembly plants. REACH phthalate restrictions through ECHA are forcing compound reformulation toward bio-based plasticizers. The Rhine-Ruhr industrial region has consolidated active suppliers from twelve to four qualified compounders with captive polymer capabilities.
United States
Residential window retrofit programs and hardware store distribution networks sustain self-adhesive strip volumes. EPA and state-level building energy codes are pressuring insulating glass unit manufacturers toward verified thermal break compounds. Midwest automotive belt production around Michigan and Ohio pulls specialized NVH grades into direct OEM supply agreements.
India
BIS certification requirements for PVC construction materials are creating compliance barriers that favor established extruders with Mumbai and Delhi testing laboratory partnerships. Construction material standards enforcement is accelerating in metropolitan building retrofit programs. Gujarat and Maharashtra industrial corridors are attracting regional extrusion capacity to serve domestic appliance and automotive component manufacturing.
France
ANSM and CNIL protocols alongside EU F-Gas Regulation phase-down schedules are pressuring window and facade system manufacturers toward pre-certified compound specifications. ECHA substance evaluation documentation requirements are extending to plasticizer migration rates in building products. French system manufacturers are locking supplier relationships before tendering to secure compliant material streams.
Soft PVC Sealing Strip Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue phthalate-free formulation certification and medical-grade compound stewardship. The market structure concentrates around extrusion specialists with captive polymer compounding capabilities and multi-jurisdiction certification portfolios. Three archetypes dominate: integrated compounder-extruders serving direct OEM supply, regional extruders with distribution channel leverage, and specialty compounders qualified for medical and aerospace applications. Competitive moves center on backward integration into resin formulation and strategic partnerships with testing laboratories for accelerated certification pathways.
Within the integrated compounder-extruder tier, Saint-Gobain leverages its European compounding network to supply OEM-specified grades directly to assembly plants, while Trelleborg anchors its position through marine and infrastructure applications where salt-water resistance differentiates product lines. Frost King occupies a position in retail channels, sustaining volume through hardware store distribution and contractor loyalty programs. These three represent the competitive archetypes of captive supply integration, application-specific differentiation, and channel-driven volume capture.
| Leading Market Players |
|---|
| SealTech |
| Saint-Gobain |
| M-D Building Products |
| Schlegel International |
| Trelleborg |
| Frost King |
| 3M |
| Greiner Extrusion |
| Royal Building Products |
| Others |
Pricing and Supply Chain Analysis
Extruder technician concentrations in Zhejiang and Jiangsu provinces anchor labor-cost differentials that widen pricing-tier spreads between captive-compounding specialists and toll-extrusion converters serving spot markets.
Pricing Analysis
Input-cost pass-through from epoxidized soybean oil and DINCH plasticizer premiums compresses margins at compounders lacking backward integration into resin formulation. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified automotive grades from hardware-store self-adhesive strips and unbranded construction commodity volumes. Cost compression in standard-tier construction grades is intensifying because Zhejiang resin clusters feed multiple competing extruders. Automotive OEM procurement teams show least price sensitivity, while residential retrofit contractors through hardware store channels exhibit highest elasticity.
Supply Chain Analysis
Workforce availability constraints in German extrusion hubs and East Asian manufacturing corridors concentrate qualified compounder-extruder capacity across China, Germany, and the United States. Feedstock dependencies draw from Zhejiang resin production, Jiangsu additive formulation, and European bio-based plasticizer development. Single-source vulnerability runs through Zhejiang and Jiangsu clusters where geographic concentration creates weather and logistics disruption exposure. Distribution runs through direct OEM supply agreements for automotive grades, building merchant cooperatives for construction channels, and hardware store retail networks for retrofit applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by automotive cabin noise mandates pulling specification authority toward foam-backed NVH grades with certified compound stewardship.
For Market Incumbents: Anchor market position through captive polymer compounding investments in the Yangtze River Delta and Rhine-Ruhr corridors. Consolidate supplier relationships with Stuttgart and Wolfsburg assembly plants before TPV substitution accelerates in premium automotive sealing. Deepen testing laboratory partnerships in Mumbai and Delhi to preempt BIS certification barriers for Indian construction retrofits.
For New Entrants and Emerging Players: Building merchant cooperatives in France and Germany represent the most penetrable channel for REACH-compliant phthalate-free formulations. Medical equipment sealing with USP Class VI certification requirements offers white-space targeting given restricted supplier eligibility. Pursue accelerated compound qualification through OEM material engineering departments rather than distributor sales forces.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional extruders with distribution channel leverage but lacking captive compounding or multi-jurisdiction certification portfolios. Long-term viability centers on compound stewardship capabilities rather than extrusion equipment scale. Monitor ECHA enforcement intensity on phthalate restrictions as inflection indicator for bio-based plasticizer adoption curves.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin formulation locks margin pools away from Zhejiang commodity suppliers. |
| Multi-Jurisdiction Certification Investment | Parallel REACH, GB standard, and BIS portfolios open automotive and construction procurement channels. |
| Co-Extrusion Capability Expansion | Twin-screw equipment enables integrated foam-backed constructions for KBA and MIIT NVH mandates. |
| Testing Laboratory Partnership Formation | Mumbai and Delhi laboratory access accelerates BIS pathway for Indian construction material standards. |
| Direct OEM Supply Agreement Negotiation | Just-in-sequence delivery capability captures procurement consolidation in Stuttgart and Wolfsburg assembly plants. |
Research Methodology
Multiple input streams — extrusion plant manager interviews, OEM procurement lead discussions, polymer compounding technical director consultations, and regulatory affairs specialist exchanges — were reconciled against customs trade data, ECHA substance evaluation protocols, SEC 10-K filings from listed compounders, and automotive production databases. Primary fieldwork with tier-one automotive supplier material engineers and building merchant cooperative category buyers validated secondary sourcing from GB standard update notices and BIS certification registries. Bottom-up volume modeling across product types and end-use segments was triangulated against top-down market sizing from resin consumption patterns.
Data-stream reconciliation employed segment-level elasticity modeling across product type, end user, application, thickness, and regional manufacturing hub dimensions. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory enforcement timelines and OEM procurement consolidation patterns. Forecast inputs incorporated MIIT cabin noise mandate implementation schedules, REACH phthalate restriction phase-down calendars, and BIS certification enforcement intensity curves across Indian metropolitan markets.
Revisions become necessary when ECHA enforcement actions accelerate bio-based plasticizer adoption beyond modeled curves, when TPV substitution rates in automotive sealing exceed compression set performance thresholds, or when Zhejiang resin cluster disruptions propagate through East Asian supply chains. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Polyvinyl Alcohol Resins Market