
 Global Corrosion Resistant Resin Market | 2026-2036
Global Corrosion Resistant Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Corrosion Resistant Resin Market Foresight
Project finance tied to infrastructure resilience bonds is fragmenting competitive access across the corrosion resistant resin value chain. Huntsman International LLC leverages its integrated epoxy intermediates position to sustain margin capture in marine coating feedstocks. BASF SE anchors European supply through its Ludwigshafen phenolic resin complex, while Ashland competes on specialty unsaturated polyester formulations for chemical storage tanks.
Corrosion resistant resins comprise thermoset polymer matrices engineered with cross-linked molecular architectures, typically achieving glass transition temperatures above 120°C and exhibiting tensile elongation under 5% in fully cured states. These materials function primarily as barrier layers that isolate steel and concrete substrates from electrochemical degradation in acidic, saline, or solvent-laden environments. Epoxy systems dominate protective coatings applications due to their adhesion strength and chemical inertness, whereas vinyl ester resins command premium positioning in chemical processing and marine coatings where blister resistance and hydrolytic stability determine specification. Powder-form phenolic resins occupy a mature niche in high-temperature power generation applications where thermal endurance outweighs ease of application.
The US EPA enforces stringent volatile organic compound limits under NESHAP standards that compel coating formulators toward higher-solids and waterborne resin technologies. REACH registration requirements in Europe restrict certain aromatic amine curing agents, redirecting R&D investment toward aliphatic and bio-based alternatives. China's MEE implements dual carbon goals that tighten emissions permits for solvent-based resin production in the Yangtze Delta. Stakeholders must monitor regulatory divergence between these jurisdictions to anticipate which chemistries will retain multi-region eligibility and which will face stranded-asset risk in specific national markets.
Market Dynamics
Project finance tied to infrastructure resilience bonds is fragmenting competitive access across the corrosion resistant resin value chain, concentrating specification power in the hands of EPC contractors and asset owners who bundle coating procurement into multi-year maintenance agreements.
Growth Catalysts
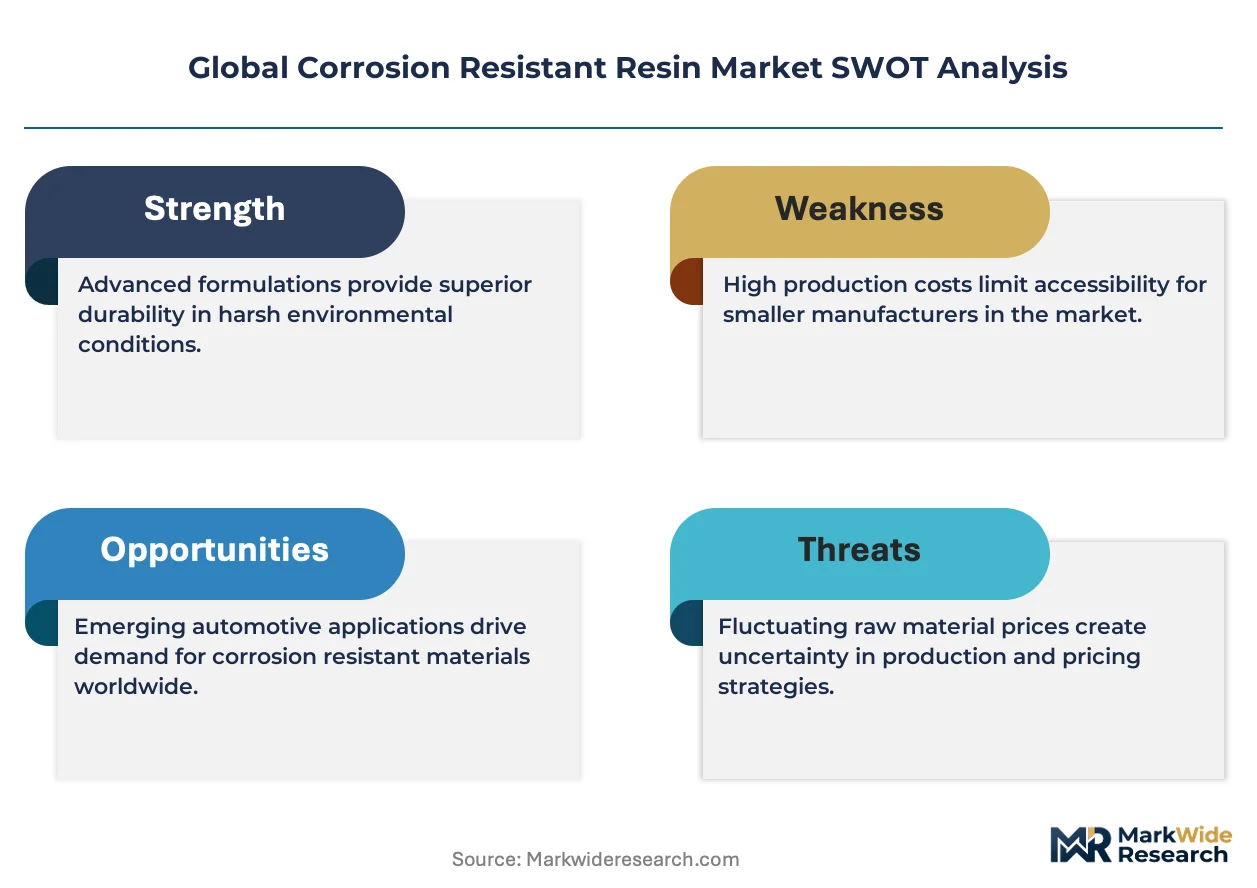
- US EPA NESHAP standards:Volatile organic compound limits compel coating formulators toward higher-solids and waterborne resin technologies, expanding addressable market for compliant epoxy systems.
- Chemical processing facilities:Aggressive acid service environments are expanding adoption of vinyl ester linings as alternatives to failing rubber and brick linings.
- China's coastal petrochemical clusters:Concentrated demand from integrated refining and chemical complexes drives specification standardization and volume procurement.
Market Restraints
- Bisphenol A price volatility:Epoxy resin feedstock costs fluctuate with crude oil and phenol markets, compressing formulation margins during upstream spikes.
- REACH registration requirements:European restrictions on aromatic amine curing agents force reformulation cycles that strand existing inventory and delay product launches.
- Thermoplastic substitution:Polyvinylidene fluoride and fluoropolymer coatings capture premium applications where thermal cycling resistance exceeds thermoset capabilities.
Strategic Opportunities
- India's specialty chemicals corridor:Underpenetrated storage tank and pipeline infrastructure creates first-mover positioning for unsaturated polyester and vinyl ester systems.
- EU Green Deal chemistry mandates:Bio-based epoxy precursors from lignin and plant-derived phenols qualify for green procurement preferences in public infrastructure tenders.
- Digital coating specification platforms:EPC contractors are adopting AI-driven material selection tools that bypass traditional distributor relationships and favor resin producers with granular technical data.
Industry Challenges
- Formulation chemist scarcity:Cross-linked polymer expertise is concentrating at major producers, leaving mid-tier competitors dependent on external technical service.
- API 652 and NACE SP0169 certification timelines:Tank lining qualification protocols require 12-18 month field exposure testing, delaying new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Corrosion Resistant Resin Market |
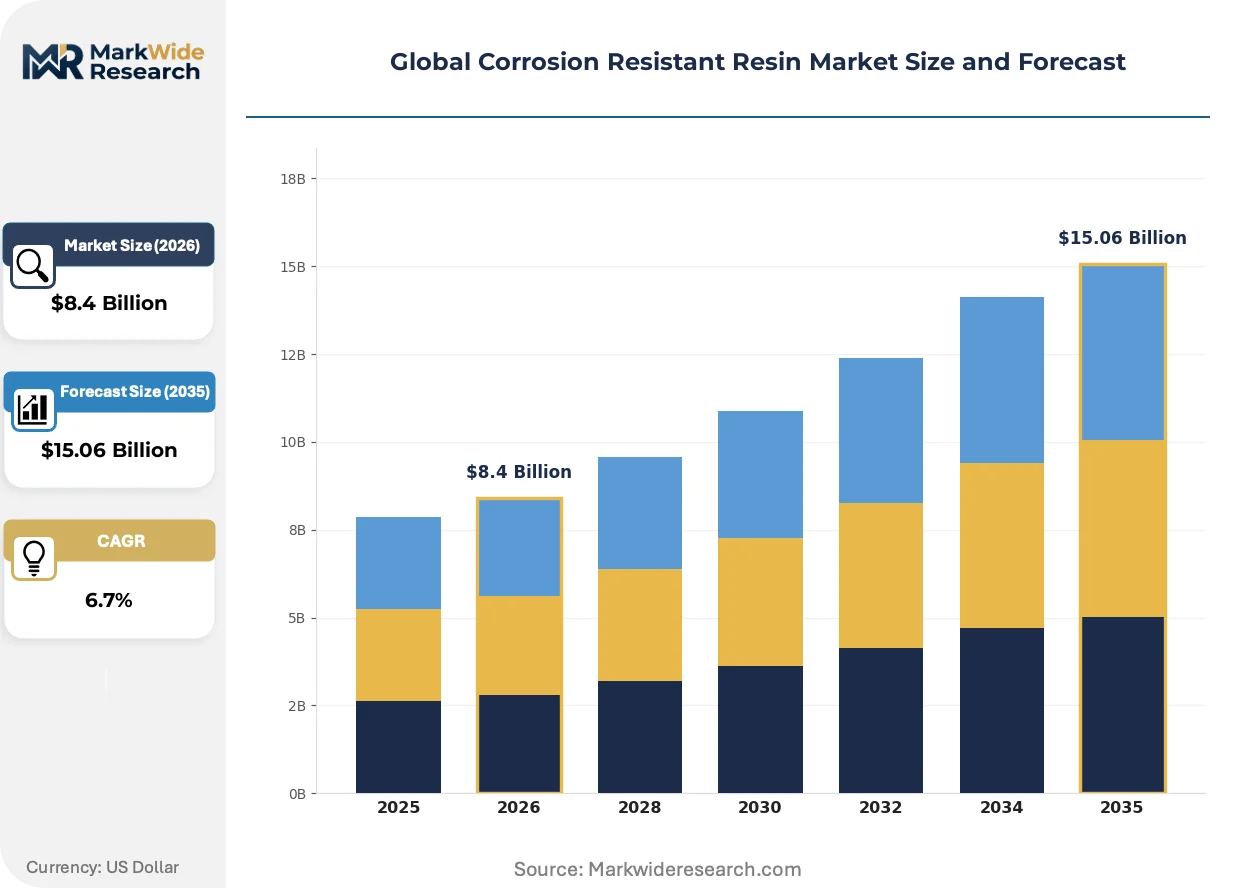
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyester, Vinyl Ester, Phenolic, Polyurethane, Acrylic Application: Protective Coatings, Adhesives, Sealants, Electrical Insulation, Marine Coatings, Chemical Processing End User Industry: Oil & Gas, Water Treatment, Power Generation, Mining, Aerospace, Infrastructure Form: Liquid, Solid, Powder, Film, Gel |
| Companies Covered | Ashland, Huntsman International LLC, Hexion Inc., BASF SE, Sino Polymer Co., Ltd., Eastman Chemical Company, Reichhold LLC, Scott Bader Company Limited, Aditya Birla Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Corrosion Resistant Resin Market Shifts & Advancements
Formulation science is converging with digital specification tools and bio-based feedstock engineering to compress product development cycles and redirect R&D investment toward compliance-first design.
Smart coating systems embedded with corrosion potential sensors are digitizing asset monitoring for offshore platforms and chemical storage terminals. Major operators in the US Gulf Coast and North Sea are piloting these systems to shift from calendar-based maintenance to condition-based intervention, compressing service contract margins for traditional inspection providers while opening recurring revenue streams for resin suppliers with integrated hardware partnerships.
REACH chemical restrictions in Europe are redirecting R&D investment toward aliphatic and bio-based curing agents as aromatic amine alternatives face registration barriers. Formulators serving marine and industrial coating segments are accelerating qualification of cycloaliphatic diamines and phenalkamine systems, with German and Dutch coating producers leading the technical validation work to retain multi-region product eligibility.
Buyer concentration among integrated EPC contractors is disintermediating traditional distributor networks in favor of direct procurement relationships with resin producers. Chinese state-owned engineering groups and US refinery maintenance consortia are consolidating coating specifications into master service agreements, favoring suppliers with captive production of both base resins and formulated systems over blenders dependent on merchant feedstocks.
Global Corrosion Resistant Resin Market Segmentation
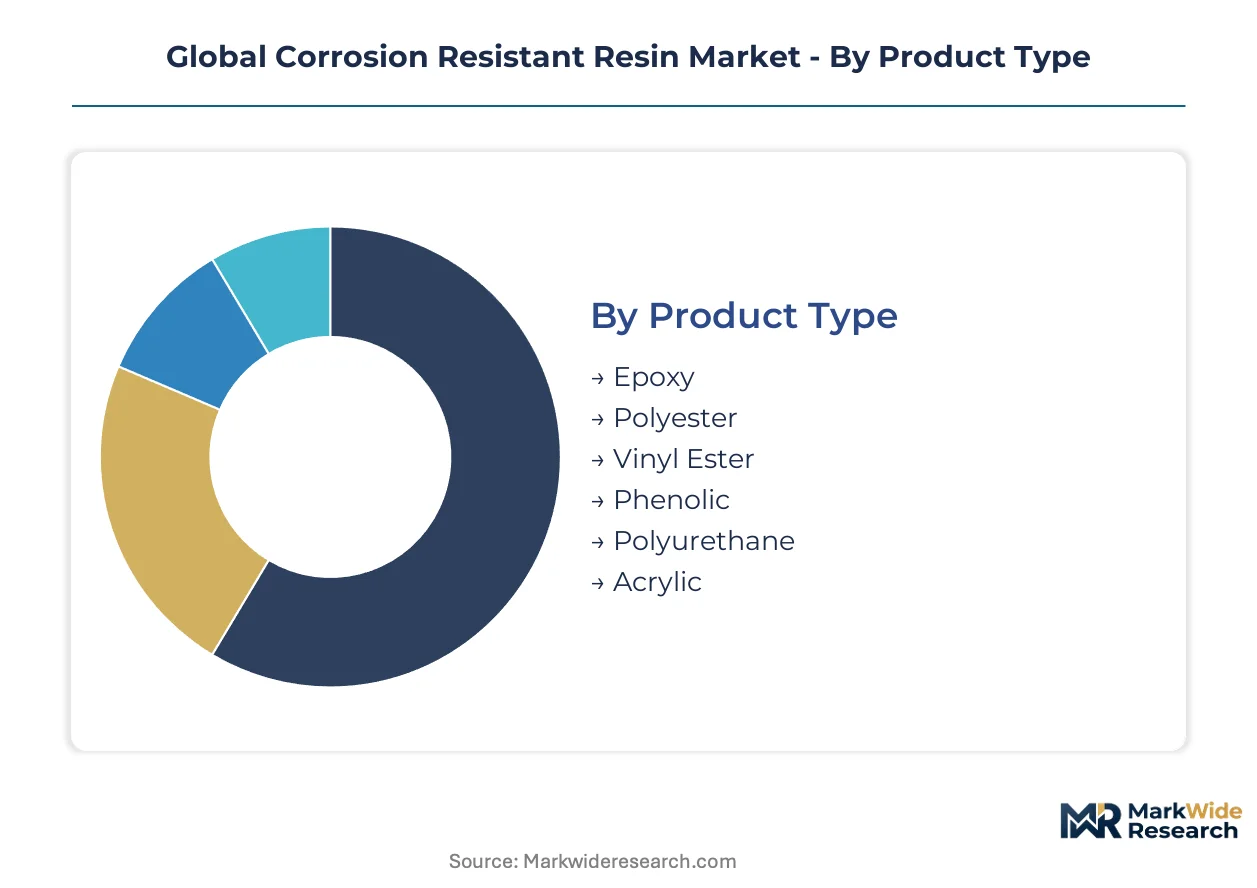
Corrosion resistant resin segmentation reveals how molecular architecture, application environment, and supply chain configuration fragment procurement decisions across industrial buyers. Specification power concentrates with EPC contractors who bundle material selection into multi-year infrastructure maintenance agreements.
Product Type:
Use-case spectrum spans barrier coatings for atmospheric exposure to immersion-grade linings for aggressive chemical service.
- Epoxy:Cross-linked thermoset systems deliver superior substrate adhesion and chemical inertness for protective coatings. Demand concentrates in marine coatings serving the US Gulf Coast refinery corridor where NESHAP compliance drives higher-solids formulation.
- Vinyl Ester:Hybrid polyester-epoxy backbone achieves hydrolytic stability and blister resistance in acidic environments. China's coastal petrochemical clusters specify these linings for sulfuric acid storage tanks as alternatives to failing rubber systems.
- Polyester:Unsaturated formulations cost less than epoxy for atmospheric corrosion protection.
- Phenolic:Thermoset networks withstand continuous exposure above 150°C in power generation exhaust systems.
- Polyurethane:Aliphatic isocyanate variants provide UV-stable topcoats for infrastructure weathering protection.
- Acrylic:Thermoplastic emulsions serve waterborne coating formulations with lower VOC profiles.
Established volume favors Epoxy; emerging adoption favors Vinyl Ester.
Application:
Cost tier segmentation separates specification-driven immersion service from commodity atmospheric protection.
- Protective Coatings:Barrier layers isolate steel and concrete from electrochemical degradation in saline or industrial atmospheres. Oil & gas pipeline operators in the Permian Basin and North Sea specify high-build epoxy systems for external corrosion control.
- Chemical Processing:Immersion-grade linings resist concentrated acids, solvents, and thermal cycling in reactor vessels. REACH restrictions on aromatic amine curing agents force European formulators toward aliphatic alternatives for tank lining qualification.
- Marine Coatings:Anticorrosive primers and antifouling systems protect hulls and offshore platforms.
- Adhesives:Structural bonding compounds join dissimilar substrates in infrastructure rehabilitation.
- Sealants:Elastomeric formulations accommodate joint movement in concrete containment structures.
- Electrical Insulation:Encapsulation compounds protect windings and busbars in power equipment.
Specification premiums concentrate in Chemical Processing; volume scale dominates Protective Coatings.
End User Industry:
Customer type fragmentation separates asset owners with captive engineering from project-based procurement.
- Oil & Gas:Midstream pipeline operators and downstream refiners drive demand for high-performance linings. Integrated majors in the US Gulf Coast and China's Ningbo-Zhoushan petrochemical hub consolidate coating procurement into master service agreements.
- Infrastructure:Bridge decks, wastewater treatment plants, and coastal structures require durable protection. India's specialty chemicals corridor creates first-mover positioning for storage tank and pipeline coating systems.
- Power Generation:Coal, gas, and nuclear facilities specify thermal-resistant phenolic and epoxy formulations.
- Water Treatment:Municipal and industrial facilities protect concrete basins and steel piping from chlorinated water attack.
- Mining:Heap leach pads and processing equipment face acidic ore exposure.
- Aerospace:Fuel tank sealants and composite matrix resins require certification to stringent flame resistance standards.
Procurement consolidation favors Oil & Gas; project fragmentation characterizes Infrastructure.
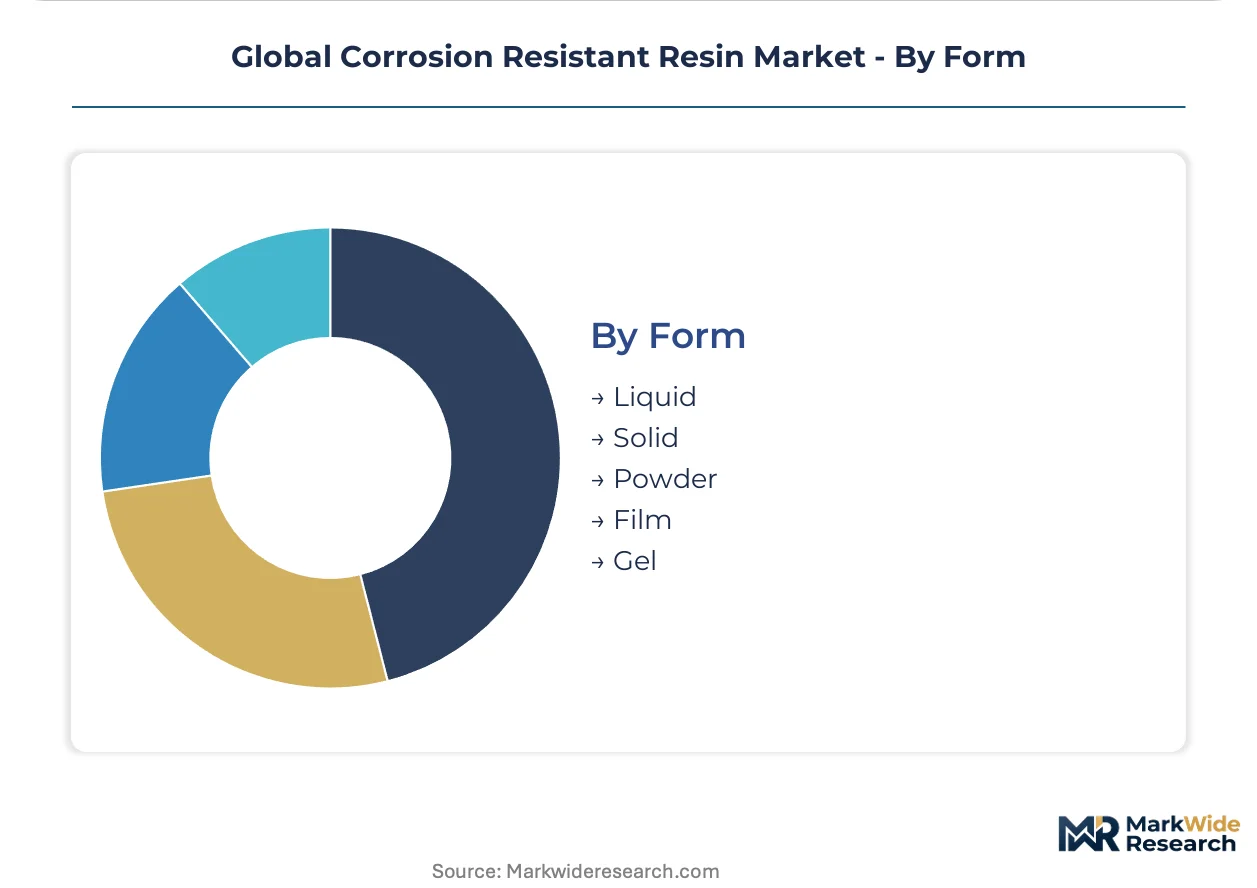
Form:
Supply concentration separates integrated resin producers from formulation blenders.
- Liquid:Solvent-borne and waterborne systems dominate spray-applied protective coatings. China's MEE dual carbon goals tighten emissions permits for solvent-based production in the Yangtze Delta.
- Solid:B-stage prepreg and molding compounds serve composite fabrication for chemical storage tanks.
- Powder:Thermoset phenolic and epoxy powders coat high-temperature power generation components.
- Film:Adhesive-backed corrosion protection tapes wrap pipeline girth welds and field joints.
- Gel:Thixotropic compounds fill voids and seal complex geometries in marine applications.
Volume manufacturing concentrates in Liquid; specialty margin capture concentrates in Gel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in corrosion resistant resins favor established manufacturing bases with captive feedstock access. The United States maintains a structural surplus in epoxy intermediates, while China balances domestic consumption against specialty resin imports from European and Japanese producers.
United States
US Gulf Coast refineries and chemical processors drive specification of vinyl ester tank linings for sulfuric acid service. EPA NESHAP standards enforce volatile organic compound limits that compel formulators toward higher-solids epoxy systems. Houston-Beaumont-Port Arthur corridor concentrates procurement through integrated EPC contractors bundling coating supply into multi-year maintenance agreements.
Germany
German industrial coating formulators lead REACH-compliant reformulation of aliphatic curing agents to replace restricted aromatic amines. ECHA registration barriers redirect R&D investment toward cycloaliphatic diamine systems. Ludwigshafen-Cologne industrial complex anchors European phenolic resin supply for high-temperature power generation applications.
China
China's coastal petrochemical clusters in Ningbo-Zhoushan and Yangtze Delta drive concentrated demand for immersion-grade linings. MEE dual carbon goals tighten emissions permits for solvent-based resin production. State-owned engineering groups consolidate coating procurement into master service agreements favoring domestic producers with integrated resin and formulation capabilities.
India
India's specialty chemicals corridor generates first-mover positioning for unsaturated polyester storage tank systems. BIS standards for chemical process equipment create compliance pathways for imported resin technologies. Gujarat-Maharashtra industrial belt attracts investment in pipeline and tank farm infrastructure requiring protective coating specifications.
Saudi Arabia
Saudi downstream expansion at Jubail and Yanbu integrated sites creates demand for high-performance linings in acid handling units. The country's national environmental regulator enforces air quality standards affecting solvent-borne coating application. Eastern Province petrochemical complexes specify premium vinyl ester systems for aggressive chemical service environments.
Global Corrosion Resistant Resin Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in base resin and curing agent supply. The market structures around three tiers: integrated chemical majors with captive epoxy and phenolic production, regional formulation houses blending merchant feedstocks, and niche specialists in high-performance vinyl ester and bio-based systems. Competitive moves concentrate on backward integration into bisphenol A and epichlorohydrin feedstocks, and on direct procurement relationships with EPC contractors that disintermediate traditional distributor networks.
Within the integrated chemical major tier, BASF SE anchors European phenolic resin supply through its Ludwigshafen complex, while Huntsman International LLC exemplifies margin capture through captive epoxy intermediates production. Ashland occupies a position in specialty unsaturated polyester formulations for chemical storage tank applications. These three represent distinct archetypes: feedstock-integrated multinational, regional formulation leader, and application-specific technology specialist.
| Leading Market Players |
|---|
| Ashland |
| Huntsman International LLC |
| Hexion Inc. |
| BASF SE |
| Sino Polymer Co., Ltd. |
| Eastman Chemical Company |
| Reichhold LLC |
| Scott Bader Company Limited |
| Aditya Birla Chemicals |
| Others |
Supply & Pricing Matrix
Undercapacity in European aromatic amine curing agent production is compressing formulation margins and forcing buyers toward aliphatic alternatives. This utilization gap feeds directly into pricing power concentration among integrated resin producers with captive feedstock positions.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure that separates REACH-compliant premium formulations from standard epoxy systems and economy-grade polyester alternatives. Price differentiation hinges on certification grade for tank lining applications and volume scale for marine coating procurement. Cost compression in standard epoxy tiers is intensifying because bisphenol A volatility feeds through from upstream phenol markets. Mid-tier blenders dependent on merchant feedstocks exhibit highest price sensitivity, while integrated majors with captive intermediates production maintain pricing discipline.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for epoxy intermediates procurement. Production concentrates in China, the United States, and Germany, with bisphenol A, epichlorohydrin, and phenol serving as critical raw material dependencies. Single-source vulnerability in specialty vinyl ester monomers sourced from Japanese producers creates qualification bottlenecks for tank lining formulators. Distribution runs through integrated EPC contractors consolidating procurement into master service agreements, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrosion resistant resin market is experiencing high-growth disruption as EPA NESHAP standards and REACH chemical restrictions force simultaneous reformulation across multiple regulatory jurisdictions.
For Market Incumbents: Harden specification control through backward integration into bisphenol A and epichlorohydrin feedstocks to defend against margin compression from upstream volatility. Invest in cycloaliphatic diamine qualification to preempt REACH registration barriers on aromatic amine curing agents.
For New Entrants and Emerging Players: Establish a beachhead in India's specialty chemicals corridor where underpenetrated storage tank infrastructure creates first-mover positioning for unsaturated polyester systems. Pursue direct procurement relationships with state-owned engineering groups bypassing established distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among resin suppliers with integrated hardware partnerships for smart coating monitoring systems. Long-term viability favors targets with captive production of both base resins and formulated systems. Monitor API 652 certification timelines as an inflection indicator for product commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Intermediates | Captive bisphenol A production insulates Huntsman from phenol market volatility. |
| REACH-Compliant Curing Agent Qualification | German formulators lead cycloaliphatic diamine validation to retain European market access. |
| Direct EPC Contractor Relationships | Chinese state-owned engineering groups consolidate procurement into master service agreements. |
| Smart Coating Hardware Partnerships | US Gulf Coast operators pilot corrosion sensors creating recurring revenue streams. |
| India Storage Tank Infrastructure Entry | Gujarat-Maharashtra industrial belt attracts coating specification for new tank farm builds. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with resin plant managers, EPC procurement leads, downstream OEM coating formulators, and technical R&D directors; and secondary validation against customs/trade data, ACC/Cefic industry reports, SEC 10-K filings, and EPA regulatory dockets. Bottom-up and top-down triangulation reconciled volume estimates across product type, application environment, end-use industry, and regional production hub segmentation.
Forecast inputs considered resin grade tier, end-use industry concentration, packaging format, and regional regulatory cluster across the analysis window. CAGRs were derived from modeled demand elasticity for immersion-grade linings versus atmospheric protective coatings, incorporating EPA NESHAP compliance timelines and China's MEE dual carbon permit restrictions as industry-specific forecast inputs.
Stress conditions across bisphenol A price volatility bands, REACH registration denial scenarios, and EPC contractor consolidation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory implementation pace and feedstock market stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Bio-Sourced Nylon Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Resin Dispersion Market