
 Singapore Adhesives Market | 2026-2036
Singapore Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Adhesives Market Analytics
Electronics assembly is decoupling from traditional construction as the dominant adhesive demand vertical in Singapore. Henkel AG & Co. KGaA leverages its specialty epoxy portfolio to anchor high-reliability bonding for semiconductor packaging operations. Dow competes through advanced acrylic formulations optimized for tropical humidity resistance. Sika AG dominates the infrastructure repair segment with polyurethane systems engineered for marine-environment concrete rehabilitation.
Adhesives are non-metallic substances capable of surface attachment through chemical or physical bonding mechanisms, typically formulated with base polymers, tackifiers, and curing agents that achieve lap shear strengths exceeding ten megapascals in structural grades. Their primary industrial purpose is to distribute stress across joined substrates while eliminating mechanical fasteners in weight-sensitive or thermally constrained assemblies. Epoxy and acrylic chemistries lead the product type landscape, with epoxy commanding premium positioning in electronics and aerospace bonding due to thermal stability, while acrylic gains share in packaging and signage applications where rapid room-temperature cure offsets lower ultimate strength. Liquid formulations remain the default across automated dispensing lines in electronics and automotive plants, though film adhesives occupy a growing niche in aerospace composite layup where thickness control determines aerodynamic tolerances.
Singapore's National Environment Agency enforces volatile organic compound emission standards that restrict solvent-based adhesive use in industrial facilities, redirecting procurement toward waterborne and radiation-curable alternatives. The country's Workplace Safety and Health Council mandates chemical hazard communication and respiratory protection protocols for adhesive handling in confined manufacturing environments, elevating compliance costs for smaller contractors. Buyers and formulators must monitor how the Carbon Pricing Act and anticipated product stewardship regulations reshape raw material sourcing economics for petrochemical-derived binders.
Market Dynamics
Electronics miniaturization is compressing bond-line tolerances below 50 microns, forcing adhesive formulators to abandon conventional dispensing in favor of jetting and stamping technologies that eliminate squeeze-out on semiconductor substrates.
Growth Catalysts
- NEA VOC regulations:Singapore's National Environment Agency emission limits are redirecting industrial procurement toward waterborne acrylic and UV-curable epoxy systems for electronics assembly.
- Semiconductor packaging:Flip-chip and system-in-package architectures are consuming high-purity underfill adhesives for thermal cycling resistance in Jurong Island fabrication facilities.
- Tuas Port construction:Marine infrastructure expansion is generating structural bonding demand for carbon-fiber reinforced polymer repairs in salt-air environments.
Market Restraints
- Petrochemical feedstock volatility:Bisphenol-A and epoxy resin prices fluctuate with naphtha cracking economics at Jurong Island refineries, compressing formulation margins.
- Specialty monomer import dependence:Photoinitiators and aliphatic urethane precursors concentrate in German and Japanese chemical suppliers, exposing formulators to currency and shipping risk.
- Acrylic humidity performance ceiling:Tropical moisture absorption limits structural acrylics to non-load-bearing applications, reserving premium electronics slots for epoxies.
Strategic Opportunities
- Woodlands aerospace cluster:MRO facilities servicing narrow-body fleets are adopting film adhesives for composite panel bonding, creating specification entry points for qualified suppliers.
- Bio-based epoxy feedstocks:Epichlorohydrin from glycerol refining is qualifying for NEA green procurement preferences in public infrastructure tenders.
- UV-LED curing convergence:Semiconductor fabs are retrofitting mercury lamp lines with 395nm LED arrays, demanding adhesives with tailored photoinitiator packages.
Industry Challenges
- Formulation chemist scarcity:Singapore's tight labor market limits access to specialists capable of balancing reactivity, viscosity, and regulatory compliance in custom adhesive development.
- Dual-cure validation timelines:Electronics customers require 2,000-hour thermal cycling data for moisture-cure/UV hybrids, extending qualification cycles to 18 months.
- Legacy solvent system phase-out:Converting rubber-to-metal bonding lines from MEK-based contact cements requires capital for spray booth ventilation and wastewater treatment upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Adhesives Market |
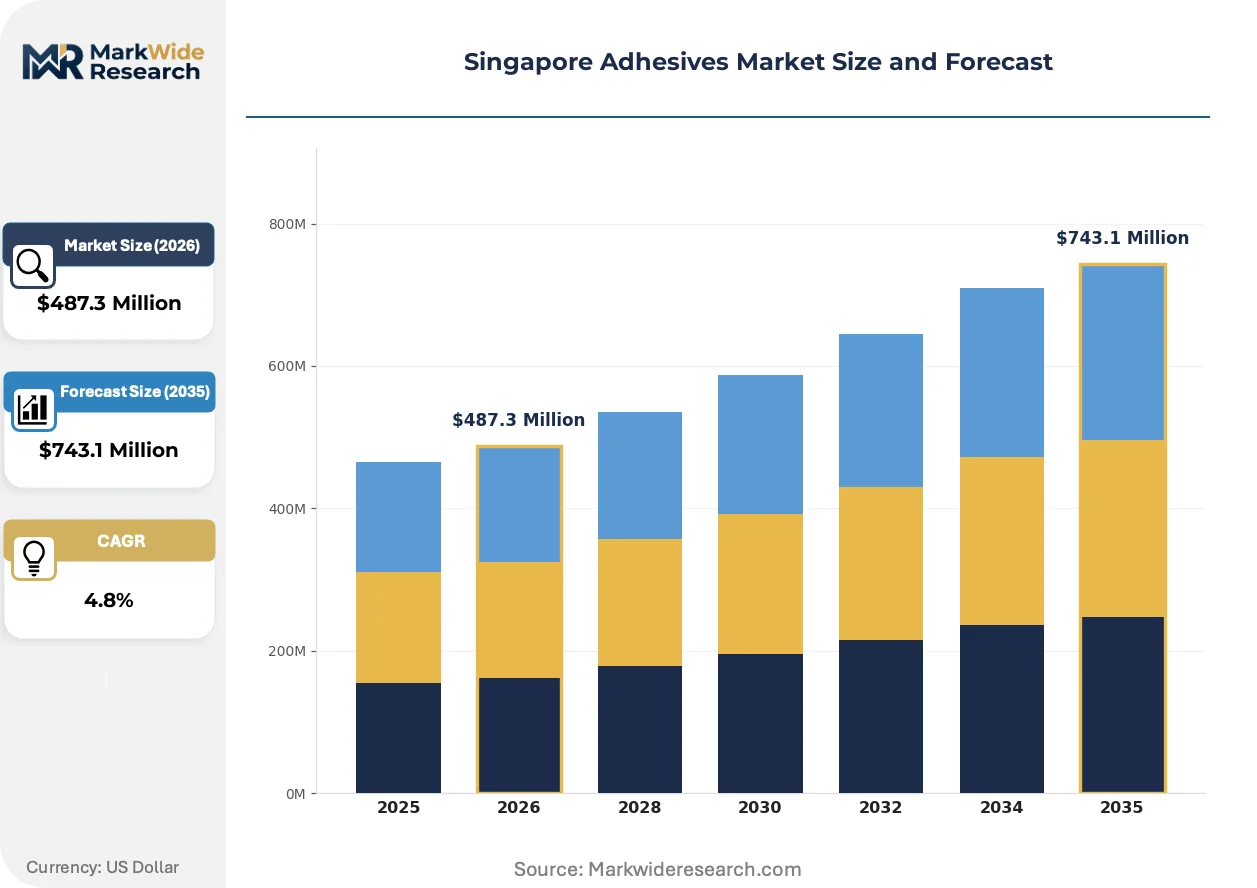
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Silicone Application: Construction, Automotive, Packaging, Electronics Form: Liquid, Solid, Paste, Film End User: Manufacturers, Contractors, Retailers, Distributors |
| Companies Covered | Dymax, Dow, 3M, H.B. Fuller Company, Huntsman International LLC, Henkel AG & Co. KGaA, Avery Dennison Corporation, Sika AG, Arkema Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Adhesives Market Evolving Landscape
Adhesive functionality is bifurcating between ultra-high-reliability electronics grades and cost-optimized construction formulations, with manufacturing automation dictating viscosity and cure-speed specifications across both tiers.
UV-LED curable adhesives is overtaking mercury-cure systems in Singapore's semiconductor backend facilities. Assembly lines at Woodlands precision component plants are retrofitting dispensing heads for 395nm wavelength compatibility. The shift is compressing energy consumption and eliminating mercury waste disposal liabilities while demanding reformulated photoinitiator packages from raw material suppliers.
Singapore's National Environment Agency is tightening volatile organic compound emission thresholds for industrial adhesive users. Facilities exceeding 10 tons annual solvent consumption must install regenerative thermal oxidizers or switch to compliant chemistries. Electronics contract manufacturers in Tuas are accelerating waterborne polyurethane evaluations to preempt enforcement actions.
Specification authority is migrating from procurement departments to reliability engineering teams in aerospace and semiconductor accounts. Buyers now require thermal cycling data, ionic purity certificates, and outgassing test results before contract award. Formulators serving Singapore's Jurong Island petrochemical maintenance sector are building in-house analytical laboratories to compress response times for technical queries.
Singapore Adhesives Market Segmentation
Adhesive procurement patterns in Singapore diver sharply between precision electronics fabrication and heavy infrastructure maintenance, with formulators optimizing viscosity, cure kinetics, and regulatory compliance for each vertical's distinct operational constraints.
Product Type:
Supply concentration among specialty resin manufacturers on Jurong Island favors epoxy and polyurethane scale economies, while acrylic and silicone production relies more heavily on imported intermediates.
- Epoxy:Formulated from bisphenol-A and epichlorohydrin precursors, these thermosetting systems achieve glass transition temperatures exceeding 150°C. Semiconductor packaging operations on Jurong Island specify high-purity grades for flip-chip underfill, where thermal cycling resistance determines device reliability.
- Polyurethane:Isocyanate-terminated prepolymers cure through moisture or catalyst activation to form elastomeric bonds with excellent peel strength. Marine infrastructure contractors specify these systems for carbon-fiber reinforced polymer repairs at Tuas Port, where salt-air exposure demands hydrolytic stability.
- Acrylic:Free-radical curing formulations dominate signage and packaging applications with rapid room-temperature cure, though tropical humidity absorption constrains structural load-bearing use.
- Silicone:Polydimethylsiloxane-based systems offer service temperatures from -60°C to 230°C, finding niche adoption in aerospace gasketing and high-temperature electronics potting.
Epoxy absorbs the bulk of installed capacity; acrylic is expanding most quickly in packaging automation lines.
Application:
Cost tier stratification separates specification-grade electronics bonding from commodity construction adhesives, with procurement budgets diverging tenfold per kilogram between these verticals.
- Construction:Structural bonding, waterproofing membranes, and tile fixing consume bulk volumes in commercial and residential building maintenance. Sika AG's polyurethane systems anchor this segment through specification relationships with civil engineering consultants.
- Electronics:Die attach, underfill, and conformal coating demand ionic purity below 10 ppm and outgassing compliance to aerospace standards. Miniaturization trends compress bond-line tolerances below 50 microns in Woodlands precision component plants.
- Automotive:Lightweighting initiatives drive structural adhesive bonding of aluminum and composite body panels, though Singapore's limited vehicle assembly constrains volume relative to electronics.
- Packaging:Hot-melt and pressure-sensitive formulations serve high-speed labeling and carton sealing operations, with waterborne acrylics gaining share under NEA VOC enforcement.
Construction retains the largest volume footprint; electronics commands the steepest expansion trajectory as semiconductor packaging capacity scales.
Form:
Customer type dictates formulation delivery—automated electronics lines demand pumpable liquids with tight viscosity windows, while maintenance contractors prefer trowelable pastes and pre-cut films for field application flexibility.
- Liquid:Low-to-medium viscosity formulations designed for automated dispensing, spray application, or brush/roller coating. Electronics contract manufacturers in Tuas specify thixotropic grades to prevent sag on vertical substrates during cure.
- Paste:High-viscosity systems incorporating fillers for gap-filling and structural bonding. Marine repair contractors favor these for overhead and vertical applications where flow control is critical.
- Solid:Hot-melt adhesives supplied as pellets, slats, or glue sticks for melt dispensing equipment. Packaging lines favor these for instant green strength and solvent-free operation.
- Film:Unsupported or supported adhesive layers with precise thickness control for aerospace composite layup. Woodlands MRO facilities specify these for secondary bonding of carbon fiber panels where aerodynamic tolerances matter.
Liquid formulations dominate automated manufacturing; film adhesives are climbing the fastest on aerospace qualification activity.
End User:
Margin structures vary dramatically across the value chain—manufacturers capture specification premiums through direct technical service, while distributors compete on inventory availability and logistics responsiveness.
- Manufacturers:Original adhesive formulators producing custom and standard grades for direct sale to industrial accounts. Henkel and Dow maintain technical service laboratories in Singapore to support semiconductor and automotive qualification programs.
- Contractors:Construction and maintenance firms purchasing adhesives as part of project material budgets. These buyers prioritize local stock availability and application training over formulation innovation.
- Distributors:Industrial chemical distributors holding inventory for just-in-time delivery to smaller manufacturing accounts. These intermediaries face margin compression as larger buyers shift to direct manufacturer relationships.
- Retailers:Hardware stores and e-commerce platforms serving consumer DIY and small trade customers. This channel concentrates in general-purpose cyanoacrylates, epoxies, and construction adhesives with lower technical complexity.
Manufacturers absorb the bulk of installed capacity; distributors are gaining share fastest among mid-tier electronics subcontractors seeking inventory flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jurong Island's Pioneer Certificate Incentive and Development and Expansion Incentive anchor petrochemical and precision manufacturing investment, concentrating adhesive demand in Singapore's southwestern industrial corridor alongside Woodlands aerospace and Tuas marine infrastructure clusters.
Central Region
Semiconductor packaging operations in Woodlands precision component plants consume high-purity underfill adhesives for flip-chip and system-in-package architectures. The National Environment Agency enforces volatile organic compound emission thresholds that redirect procurement toward waterborne acrylic and UV-curable epoxy systems. Jurong Island fabrication facilities anchor thermal cycling-resistant adhesive demand for advanced packaging.
North Region
Woodlands aerospace MRO facilities servicing narrow-body fleets adopt film adhesives for composite panel bonding, creating specification entry points for qualified suppliers. The Workplace Safety and Health Council mandates chemical hazard communication protocols for adhesive handling in confined manufacturing environments. Aerospace maintenance clusters concentrate specification authority with reliability engineering teams demanding thermal cycling data and outgassing compliance.
West Region
Tuas Port marine infrastructure expansion generates structural bonding demand for carbon-fiber reinforced polymer repairs in salt-air environments. The Carbon Pricing Act reshapes raw material sourcing economics for petrochemical-derived binders used in marine construction. Tuas electronics contract manufacturers accelerate waterborne polyurethane evaluations to preempt NEA enforcement actions on solvent consumption.
North-East Region
Packaging automation lines in Seletar aerospace and logistics parks favor hot-melt and pressure-sensitive formulations for high-speed labeling and carton sealing operations. Anticipated product stewardship regulations pressure formulators to monitor bio-based feedstock qualification for public infrastructure tenders. Smaller manufacturing accounts in this corridor rely on distributor inventory for just-in-time adhesive delivery.
Singapore Adhesives Market Competitive Landscape
Top-tier vendors anchor premium specification-grade supply, while mid-tier regional distributors compete on inventory availability and logistics responsiveness. The Singapore adhesives market exhibits tiered concentration with multinational formulators commanding semiconductor and aerospace qualification programs, and local intermediaries serving construction contractors and smaller electronics subcontractors. Three strategic archetypes dominate: integrated resin manufacturers with Jurong Island feedstock access, specialty electronics formulators with in-house analytical laboratories, and industrial chemical distributors holding buffer stock for JIT delivery. Competitive moves center on technical service laboratory expansion for qualification support and distributor direct-relationship bypass strategies among larger manufacturing accounts.
Among multinational formulators with Singapore technical presence, Henkel AG & Co. KGaA, Dow, and Sika AG exemplify distinct competitive positioning archetypes. Henkel occupies a position representing high-reliability electronics bonding specialists leveraging specialty epoxy portfolios. Dow exemplifies advanced acrylic formulation capabilities optimized for tropical humidity resistance. Sika AG anchors infrastructure repair segments through polyurethane systems engineered for marine-environment concrete rehabilitation. These three entities collectively represent the premium-tier vendor structure serving Singapore's divergent electronics fabrication and heavy infrastructure maintenance verticals.
| Leading Market Players |
|---|
| Dymax |
| Dow |
| 3M |
| H.B. Fuller Company |
| Huntsman International LLC |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| Sika AG |
| Arkema Group |
| Others |
Value Network & Pricing Analysis
UV-LED curing retrofits across Singapore's semiconductor backend facilities are compressing energy costs while demanding reformulated photoinitiator packages, simultaneously concentrating procurement power among formulators with in-house analytical laboratories and squeezing margins for distributors dependent on legacy mercury-cure inventory.
Pricing Analysis
Short lead-time premiums dominate electronics procurement, with Jurong Island semiconductor packaging operations paying substantial markups for qualified underfill adhesives available within 48 hours versus standard 4-week contract pricing. Three-tier pricing structure across qualification-grade, production-grade, and maintenance-grade levels separates aerospace film adhesives from construction polyurethanes and DIY retail epoxies. Price differentiation hinges on ionic purity certification and tropical humidity validation data, with cost compression in standard-grade acrylics intensifying due to Chinese import competition. Electronics contract manufacturers exhibit lowest price sensitivity given qualification lock-in, while construction contractors negotiate aggressively on volume.
Supply Chain Analysis
Regional distribution centers in Singapore, Shanghai, and Tokyo anchor hub-and-spoke patterns serving Southeast Asian electronics clusters. Specialty monomer supply concentrates in Germany, Japan, and South Korea for photoinitiators and aliphatic urethane precursors. Raw material dependencies span bisphenol-A from Jurong Island petrochemical crackers, epichlorohydrin from glycerol refining, and tackifier resins from Indonesian pine forests. Single-source vulnerability for high-purity epoxy resins exposes formulators to naphtha cracking economics volatility. Distribution runs through manufacturer-direct relationships for tier-one semiconductor accounts and distributor networks for mid-tier packaging subcontractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as formulators pursue captive production of photoinitiators and specialty monomers to escape currency and shipping risk from German and Japanese chemical suppliers.
For Market Incumbents: Anticipate NEA enforcement timelines by accelerating waterborne polyurethane qualification ahead of solvent system phase-out deadlines. Secure backward integration into epichlorohydrin from glycerol refining to capture green procurement preferences in public infrastructure tenders. Defend semiconductor account relationships through in-house thermal cycling laboratories that compress 18-month qualification cycles. For New Entrants and Emerging Players: Singapore's NEA VOC regulations open a window for waterborne acrylic specialists to displace solvent-based incumbents in packaging automation lines. Target Tuas electronics contract manufacturers seeking inventory flexibility outside Henkel and Dow direct relationships. Enter through distributor partnerships that buffer working capital requirements while building qualification track records. For Investors and Strategic Acquirers: Re-rating potential sits with specialty electronics formulators possessing in-house analytical laboratories given UV-LED curing convergence and semiconductor packaging capacity expansion. Long-term viability favors upstream-integrated players over pure distributors. Monitor photoinitiator supply agreements as inflection indicators for margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Glycerol-derived feedstocks qualify for NEA green procurement preferences in public tenders. |
| UV-LED Photoinitiator Reformulation | 395nm compatibility secures specification wins in Woodlands semiconductor backend facilities. |
| Thermal Cycling Laboratory Buildout | In-house 2,000-hour validation capability compresses qualification cycles for aerospace accounts. |
| Waterborne Polyurethane Scale-Up | Preemptive capacity addresses NEA enforcement risk in Tuas electronics contract manufacturing. |
| Film Adhesive Aerospace Qualification | Thickness-controlled bonding systems penetrate Woodlands MRO composite panel specifications. |
Research Methodology
Independent corroboration across adhesive formulator technical directors, semiconductor packaging procurement leads, and marine infrastructure project engineers underwrites the qualitative findings. Primary interviews with NEA compliance officers, distributor inventory managers, and Jurong Island plant operators combined with secondary validation from Singapore Customs trade data, ACC solvent consumption reports, and SEC 10-K chemical segment disclosures. Bottom-up demand modeling from end-use application volumes triangulates against top-down resin production capacity estimates.
Rate-of-change decomposition separates volume effects from mix-shift and pricing components across the projection horizon. Segmentation dimensions modeled include chemistry type, form factor, application vertical, and end-user tier alongside regional production hub clustering. CAGRs derive from adhesive consumption intensity ratios applied to semiconductor packaging, marine construction, and aerospace MRO output forecasts. Key inputs span flip-chip underfill penetration rates and UV-LED retrofit adoption curves.
Caveats apply where NEA VOC threshold tightening, Jurong Island petrochemical feedstock disruptions, or photoinitiator supply chain shocks could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Elastic Bonding Adhesive and Sealant Market
Adhesives & Sealants
Fibrin Glue Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Laminating Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Germany Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives Market
Adhesives & Sealants
United States Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Europe Epoxy Adhesive Market
Adhesives & Sealants
UV-Curable Adhesives Market