
 ASEAN Ethylene Vinyl Acetate (EVA) Resins Market | 2026-2036
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market Insights
Buyer concentration in ASEAN footwear and solar encapsulant sectors is consolidating around tier-one OEMs with multi-year supply agreements. DOW Inc. leverages its integrated ethylene infrastructure across Singapore and Thailand to serve these consolidated buyers. Hanwha Chemical Co, Ltd. anchors the regional solar value chain through its specialized EVA formulations for photovoltaic modules. ExxonMobil Corporation competes on low-density grades optimized for high-clarity packaging films across Indonesia and Malaysia.
Ethylene Vinyl Acetate (EVA) resins comprise copolymers of ethylene and vinyl acetate monomer, typically containing 10-40% vinyl acetate content by weight, produced via high-pressure autoclave or tubular reactor processes. These resins deliver flexibility, optical clarity, and adhesive properties for hot-melt formulations, solar encapsulation, and foamed midsoles. Low Density EVA dominates packaging applications where seal strength and transparency command premium positioning, while Copolymers capture expanding share in photovoltaic encapsulants as module efficiency standards tighten. The Footwear application segment sustains mature volume through Vietnam and Indonesia manufacturing hubs, though Adhesives represents the fastest-growing margin pool driven by automotive lightweighting trends.
Thailand's Board of Investment, Indonesia's Ministry of Industry, and Vietnam's Ministry of Natural Resources and Environment shape regional demand through local content rules, carbon intensity benchmarks, and chemical facility permitting. These frameworks push foreign resin suppliers toward joint ventures or localized compounding operations to maintain market access. Stakeholders must monitor evolving ASEAN harmonized chemical classification standards and solar module domestic content thresholds to anticipate procurement route shifts.
Market Dynamics
Thailand's Board of Investment incentives for electric vehicle and solar manufacturing are redirecting resin procurement toward localized supply chains, compressing lead times and reshaping supplier-buyer relationships across the region.
Growth Catalysts
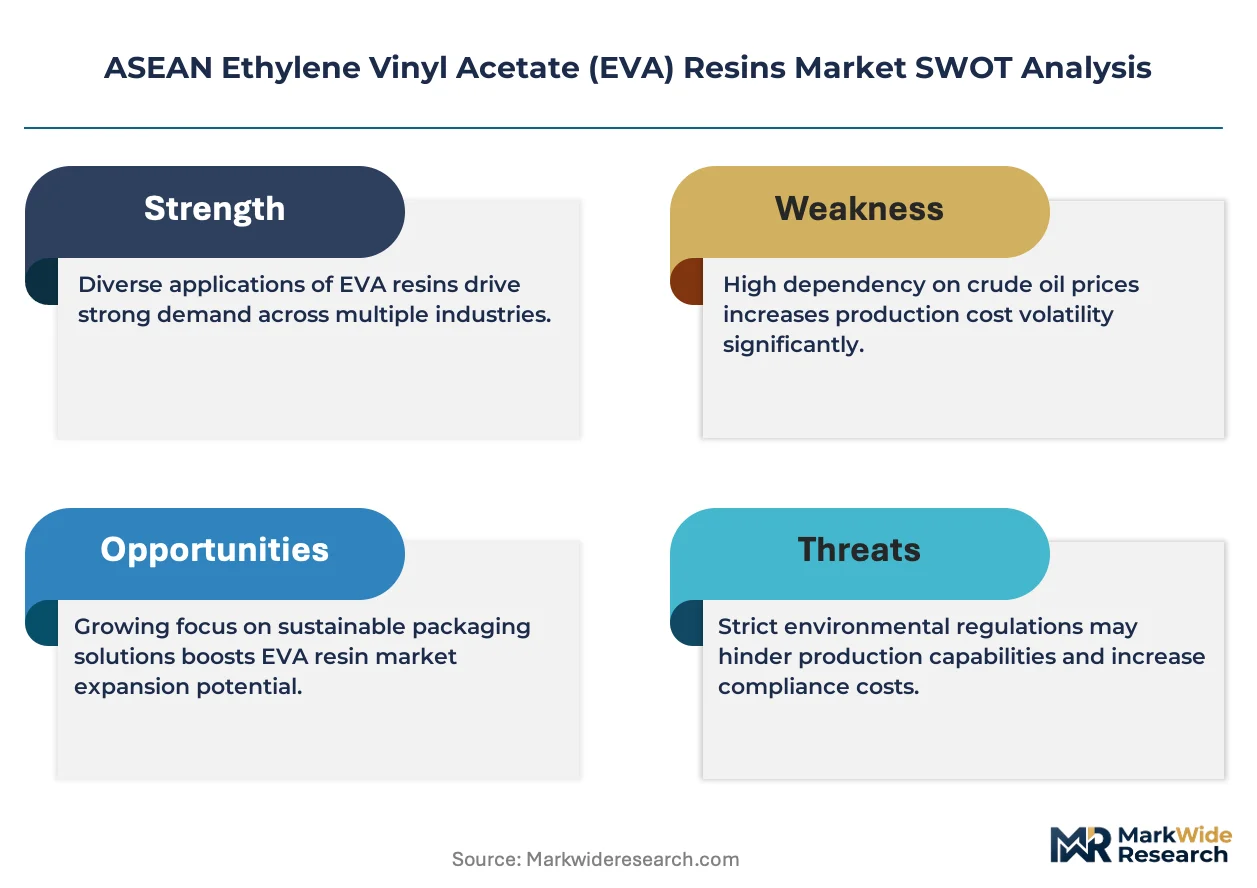
- Solar photovoltaic expansion:ASEAN nations are scaling renewable energy capacity, driving demand for specialized EVA encapsulant formulations in module production.
- Thailand BOI incentives:Tax holidays and import duty exemptions for EV and solar manufacturing are accelerating domestic compounding facility investments.
- Footwear manufacturing clustering:Vietnam's northern industrial corridor around Haiphong and Bac Ninh provinces concentrates OEM demand for foamed midsole grades.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings directly compress resin margins, as naphtha-cracker economics determine regional EVA cost floors.
- Singapore-Thailand supply concentration:Integrated ethylene infrastructure centers on two production hubs, creating geographic vulnerability to disruptions.
- Polyolefin elastomer substitution:Metallocene-based plastomers are capturing flexible packaging share where seal strength requirements moderate.
Strategic Opportunities
- Indonesia domestic content rules:Ministry of Industry mandates for solar module local sourcing create captive demand for Indonesian compounding ventures.
- Automotive lightweighting adhesives:Hot-melt EVA formulations for interior bonding represent an underpenetrated margin pool as vehicle assembly expands.
- Carbon intensity benchmarking:Vietnam's Ministry of Natural Resources and Environment emission standards favor low-carbon resin suppliers with verified supply chains.
Industry Challenges
- Specialized polymer engineering talent:Formulation chemists with photovoltaic encapsulant expertise remain scarce across ASEAN technical institutes.
- ASEAN harmonized chemical classification delays:Divergent national implementation timelines complicate cross-border product registration and labeling compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Ethylene Vinyl Acetate (EVA) Resins Market |
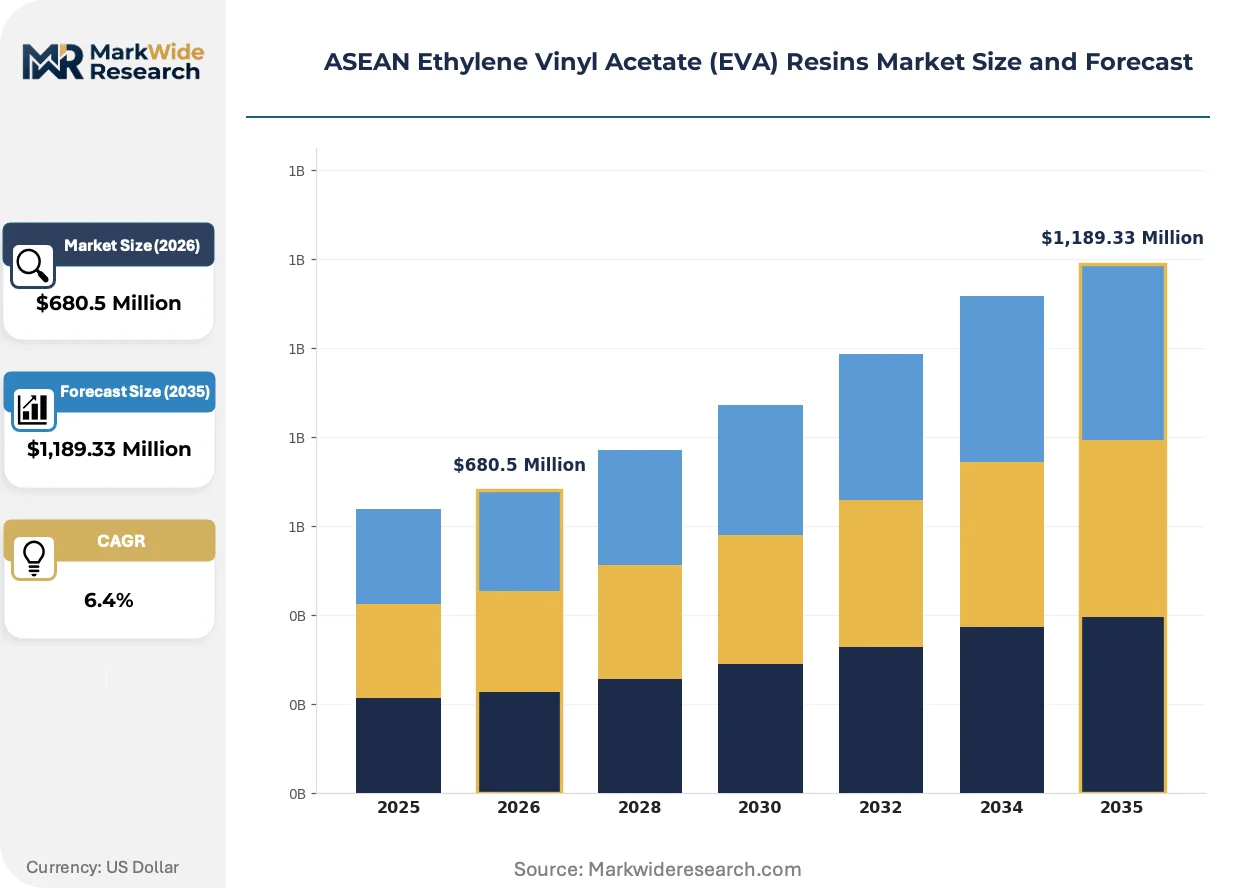
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $1,189.33 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Density EVA, High Density EVA, Medium Density EVA, Copolymers Application: Packaging, Footwear, Adhesives, Coatings End User: Automotive, Construction, Consumer Goods, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | ExxonMobil Corporation, Arkema S.A., DOW Inc., Lyondell Basell Industries N.V., Hanwha Chemical Co, Ltd., Braskem S.A., Formosa Plastics Corporation, Total SA, Celanese Corporation, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market Trends and Innovations
Photovoltaic module efficiency standards and automotive lightweighting mandates are forcing material specification upgrades faster than traditional resin development cycles permit.
Metallocene-catalyzed EVA copolymers with narrow molecular weight distribution are absorbing premium solar encapsulant volume. Tier-one module manufacturers in Vietnam and Thailand are specifying these grades for 25-year warranty compliance. The technology is absorbing market share from conventional autoclave-processed resins by delivering superior UV resistance and dimensional stability.
Thailand's Board of Investment revised incentive frameworks now require 40% local value-add for full tax benefit eligibility. This industrial consequence forces foreign resin suppliers into joint venture structures or standalone compounding investments. The solar encapsulant segment is most affected, with Korean and Japanese suppliers accelerating Thai facility construction to maintain tariff-free market access.
Consolidated footwear OEMs are compressing supplier rosters and demanding multi-year formula lock agreements with volume guarantees. Direct mill relationships are displacing traditional distributor channels in Vietnam's northern provinces. This concentration is most visible in Bac Ninh, where three multinational athletic brands now source 80% of EVA midsole requirements through nominated compounders with captive resin supply.
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market Segmentation
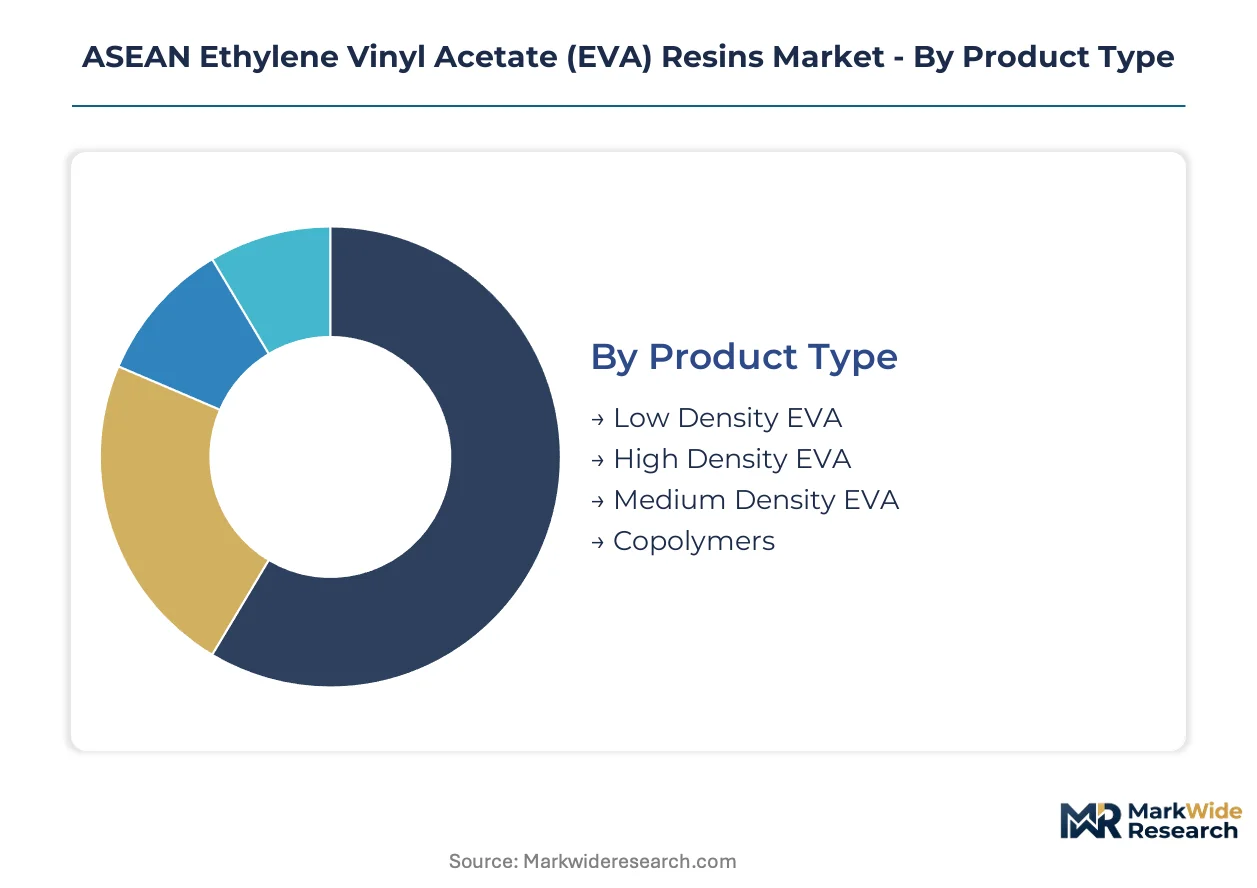
Segmentation in ASEAN EVA resins reveals how supply chain configuration shapes competitive access. Product density grades, application specifications, and procurement channels each concentrate around distinct manufacturing clusters and regulatory thresholds across Thailand, Vietnam, and Indonesia.
Product Type:
Supply concentration around Singapore and Thai integrated crackers directly determines which density grades achieve cost-competitive scale in ASEAN markets.
- Low Density EVA:These grades contain 18-28% vinyl acetate content, delivering the flexibility and optical clarity required for high-performance packaging films. Demand clusters in Indonesia and Malaysia where food-grade seal strength specifications command premium positioning against polyolefin alternatives.
- Copolymers:Metallocene-catalyzed formulations with narrow molecular weight distribution dominate photovoltaic encapsulant applications. Thai and Vietnamese module manufacturers specify these grades for 25-year warranty compliance, absorbing premium volume as renewable energy capacity expands.
- High Density EVA:Stiffer grades with 10-18% vinyl acetate serve industrial adhesive and wire-cable jacketing applications across ASEAN manufacturing zones.
- Medium Density EVA:Intermediate flexibility grades balance cost and performance for general-purpose foaming and extrusion in Vietnam's footwear corridor.
Low Density EVA absorbs the bulk of installed capacity; Copolymers are expanding most quickly.
Application:
Margin structure across applications follows the technical specification intensity required by end-use certification standards.
- Adhesives:Hot-melt EVA formulations for automotive interior bonding and packaging assembly represent an underpenetrated margin pool. Thailand's expanding vehicle assembly capacity and Indonesia's domestic content rules for manufacturing are accelerating specification upgrades in this segment.
- Footwear:Foamed midsole grades sustain mature volume through Vietnam's northern industrial corridor around Haiphong and Bac Ninh provinces. Three multinational athletic brands now consolidate procurement through nominated compounders with captive resin supply, compressing traditional distributor channels.
- Packaging:Clarity and seal strength requirements in Indonesian and Malaysian food packaging sustain steady demand for low-density grades.
- Coatings:Specialized EVA dispersions serve protective and decorative applications across ASEAN construction and consumer goods manufacturing.
Footwear maintains volume concentration in Vietnam; Adhesives is climbing the fastest as automotive lightweighting mandates spread.
End User:
Customer procurement sophistication varies sharply across sectors, with automotive and electronics OEMs demanding multi-year formula lock agreements that reshape supplier relationships.
- Electronics:Solar photovoltaic module manufacturers in Vietnam and Thailand drive specialized encapsulant demand. These customers specify metallocene-catalyzed copolymers with verified carbon intensity credentials to meet procurement standards from Vietnam's Ministry of Natural Resources and Environment.
- Automotive:Assembly plants in Thailand leverage Board of Investment incentives to localize adhesive and interior component supply chains. Tier-one suppliers demand hot-melt formulations with consistent viscosity profiles and documented feedstock provenance.
- Construction:Waterproofing membranes and sealant applications sustain steady demand for medium and high-density grades across ASEAN infrastructure projects.
- Consumer Goods:Footwear, toys, and household products manufacturers in Vietnam and Indonesia prioritize cost-competitive foaming grades with reliable supply continuity.
Electronics commands premium formulation development; Automotive is gaining share fastest as Thailand's BOI incentives redirect procurement patterns.
Distribution Channel:
Channel structure reflects the consolidation pressure from tier-one OEMs seeking supply security and formula consistency across multi-year horizons.
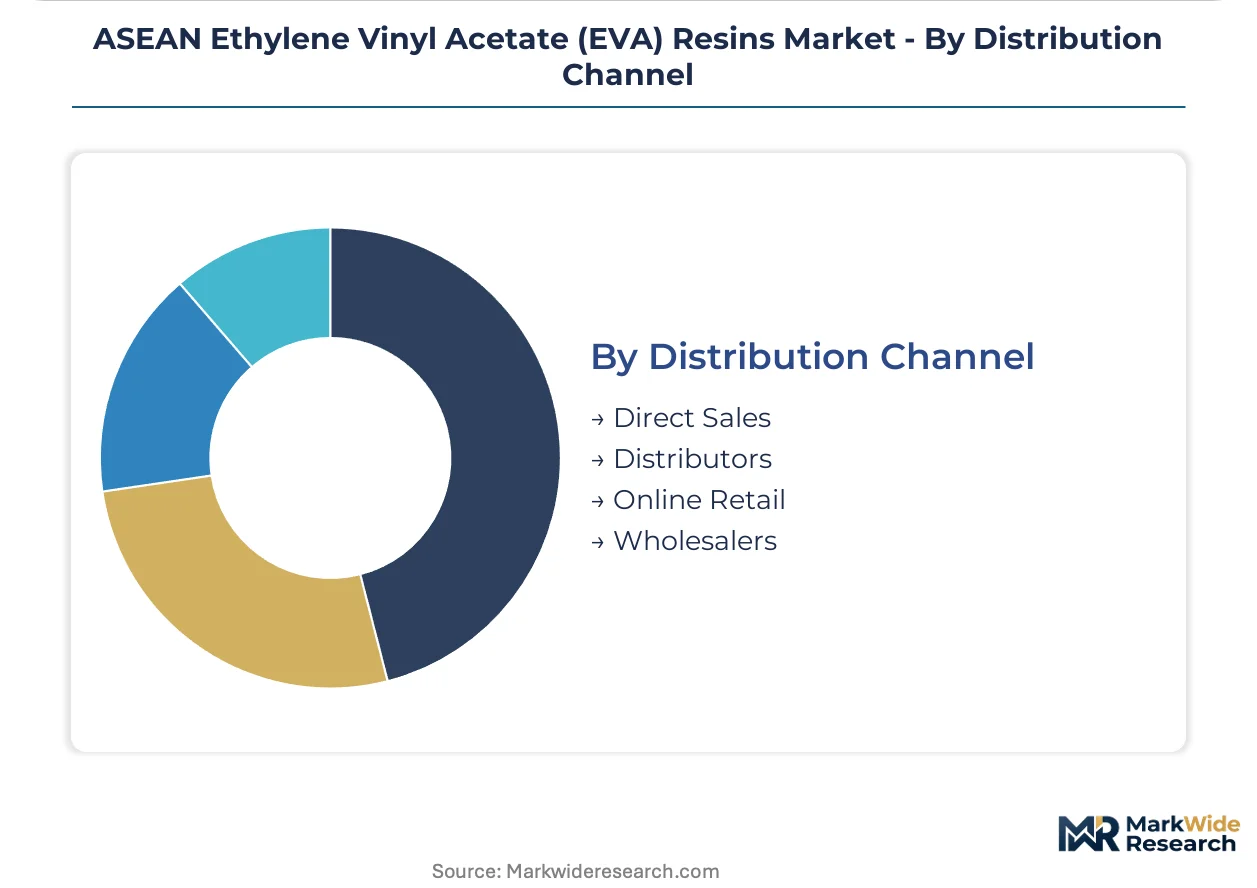
- Direct Sales:Integrated producers DOW Inc. and Hanwha Chemical Co, Ltd. serve consolidated solar and footwear OEMs through nominated account relationships. These arrangements bypass traditional distribution margins and enable collaborative formulation development for warranty-critical applications.
- Distributors:Regional compounders and resin traders maintain relevance in fragmented packaging and construction segments where order sizes and technical service requirements vary.
- Wholesalers:Bulk volume aggregation serves mid-tier processors in Indonesia and Vietnam with standardized grade requirements and price-sensitive procurement.
- Online Retail:Digital platforms capture limited share in specialized industrial resin markets where technical consultation and logistics coordination remain essential.
Direct Sales captures the bulk of value-added volume; Distributors are contracting most quickly as OEM consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for EVA resins concentrates in Thailand and Vietnam where solar module assembly and footwear manufacturing cluster around specialized industrial zones. Thailand's Board of Investment incentives and Vietnam's northern industrial corridor shape procurement patterns across the region. Indonesia's domestic content rules and Singapore's integrated petrochemical infrastructure complete the supply chain map.
Thailand
Solar photovoltaic module manufacturing and electric vehicle assembly drive EVA demand in Thailand's Eastern Economic Corridor. The Board of Investment offers tax holidays and import duty exemptions for EV and solar manufacturing, redirecting resin procurement toward localized supply chains. Rayong and Chonburi provinces host compounding facilities established by Korean and Japanese suppliers seeking tariff-free market access.
Vietnam
Footwear OEMs and electronics manufacturers dominate EVA consumption in Vietnam's northern industrial corridor. The Ministry of Natural Resources and Environment enforces carbon intensity benchmarks that favor low-carbon resin suppliers with verified supply chains. Haiphong and Bac Ninh provinces concentrate multinational athletic brands that source foamed midsole grades through nominated compounders with captive resin supply.
Indonesia
Packaging film producers and construction material manufacturers sustain steady EVA demand across Indonesian manufacturing zones. The Ministry of Industry mandates domestic content rules for solar module local sourcing, creating captive demand for Indonesian compounding ventures. Java's industrial belt around Jakarta and Surabaya hosts processors seeking cost-competitive foaming grades with reliable supply continuity.
Singapore
Integrated ethylene crackers anchor regional EVA supply from Singapore's Jurong Island petrochemical complex. The Economic Development Board supports advanced materials investments that serve ASEAN downstream markets. Jurong's infrastructure enables DOW Inc. and other integrated producers to serve consolidated solar and footwear OEMs through nominated account relationships.
Malaysia
Food-grade packaging manufacturers in Malaysia's Klang Valley and Penang corridor consume low-density EVA grades for seal strength applications. The Malaysian Investment Development Authority promotes chemical sector investments that align with halal certification requirements for food contact materials. Penang's electronics manufacturing services sector generates secondary demand for adhesive and encapsulant formulations.
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market Competitive Landscape
US and European chemical conglomerates anchor one tier; Korean and Japanese specialists hold differentiated positions in solar encapsulant formulations. The market structure reflects consolidation around integrated ethylene producers with autoclave or tubular reactor capabilities. Three archetypes dominate: integrated petrochemical majors with captive feedstock, regional compounders with formulation expertise, and photovoltaic specialists with metallocene-catalyzed product lines. Capacity expansion and joint venture structures represent the dominant competitive moves as suppliers respond to localization mandates.
Among integrated petrochemical majors, ExxonMobil Corporation and DOW Inc. occupy positions shaped by their ethylene infrastructure across Singapore and Thailand. Hanwha Chemical Co, Ltd. represents the photovoltaic specialist archetype, with its Korean corporate structure indicating regional supply chain integration. These three companies exemplify how geographic positioning and feedstock integration determine competitive access in a market where procurement is consolidating around tier-one OEMs.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Arkema S.A. |
| DOW Inc. |
| Lyondell Basell Industries N.V. |
| Hanwha Chemical Co, Ltd. |
| Braskem S.A. |
| Formosa Plastics Corporation |
| Total SA |
| Celanese Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive ethylene infrastructure across Singapore and Thailand anchors both supply security and pricing power for integrated producers serving ASEAN module manufacturers and footwear OEMs. Naphtha-cracker economics tether resin cost floors to regional feedstock volatility while local content mandates from Thailand's Board of Investment reshape procurement premiums.
Pricing Analysis
Volume concentration in low-density packaging grades compresses margins while metallocene-catalyzed copolymers for photovoltaic encapsulants command premium positioning. Price differentiation hinges on vinyl acetate precision and carbon intensity certification under Vietnam's Ministry of Natural Resources and Environment benchmarks. Pricing pressure stems from polyolefin elastomer substitution in flexible packaging segments. Packaging processors in Indonesia exhibit highest price sensitivity; solar module manufacturers prioritize warranty-grade consistency over unit cost.
Supply Chain Analysis
Thailand's Board of Investment domestic content rules and Indonesia's Ministry of Industry solar sourcing mandates are forcing Korean and Japanese suppliers into joint venture structures and standalone Thai compounding investments. Feedstock draws from Singapore's Jurong Island crackers and Rayong-based ethylene infrastructure. Naphtha, vinyl acetate monomer, and metallocene catalysts constitute critical input dependencies. Single-source vulnerability concentrates around Singapore-Thailand ethylene corridor disruptions. Distribution runs through nominated direct sales relationships with tier-one OEMs, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream ethylene control and downstream compounding presence determine competitive access. Players are pursuing captive resin supply to meet Thailand's Board of Investment 40% local value-add thresholds.
For Market Incumbents: Anchor market position through backward integration into Thai ethylene infrastructure or joint venture compounding facilities in Rayong and Chonburi provinces. Polyolefin elastomer substitution in packaging films threatens volume share; defend through metallocene R&D investment for solar-grade copolymers. Lock multi-year formula agreements with Vietnamese footwear OEMs in Bac Ninh to compress distributor channel relevance.
For New Entrants and Emerging Players: Enter via automotive hot-melt adhesive formulations in Thailand's Eastern Economic Corridor, the most penetrable white-space segment as vehicle assembly expands. Indonesia's domestic content rules for solar module manufacturing create captive demand for localized compounding ventures. Pursue technical partnership routes with tier-one module manufacturers seeking carbon-verified supply chains.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Korean or Japanese petrochemical majors seeking Thai production footholds. Long-term viability favors compounders with metallocene formulation expertise and verified low-carbon credentials. Monitor Vietnam's carbon intensity benchmark enforcement as inflection signal for premium grade demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Cracking | Captive feedstock supply secures margin stability against naphtha volatility for Thai producers. |
| Joint Venture Compounding Facility | Thai Board of Investment tax eligibility requires 40% local value-add for resin suppliers. |
| Metallocene Catalyst Technology Licensing | Photovoltaic warranty compliance demands narrow molecular weight distribution copolymers. |
| Carbon Intensity Certification Program | Vietnam's Ministry of Natural Resources and Environment benchmarks favor verified low-carbon supply chains. |
| Long-term Supply Agreement with Footwear OEMs | Bac Ninh and Haiphong manufacturers consolidate procurement through nominated compounder relationships. |
Research Methodology
Independent corroboration across resin procurement leads at Vietnamese footwear OEMs, technical directors at Thai solar module manufacturers, and Singapore-based petrochemical plant managers underwrites the qualitative findings. Secondary validation draws from customs trade data, ASEAN chemical association reports, and Board of Investment incentive disclosures. Bottom-up demand modeling across density grades and top-down ethylene capacity assessment triangulate volume estimates.
Comparable historical periods anchored the forecast window to pre-incentive and post-incentive procurement patterns across the analysis window. Segmentation dimensions modeled include vinyl acetate content tiers, end-use applications, and country-specific regulatory clusters. CAGRs derive from ethylene capacity expansion timelines and solar installation trajectories. Feedstock cost curves and domestic content threshold implementation schedules constitute key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under crude oil price shocks or delays in ASEAN harmonized chemical classification implementation. Assumptions reflect current incentive frameworks and carbon benchmark enforcement trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Hydrogenated Styrene Block Copolymers Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Polycide Market