
 Global Rubber Vulcanization Market | 2026-2036
Global Rubber Vulcanization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rubber Vulcanization Market Foresight
Asian accelerator producers is realigning capacity toward high-efficiency sulfur donors to serve tire makers. Eastman Chemical Company leverages its integrated bisphenol and resin portfolio to control specialty curing agent supply. LANXESS anchors European demand through backward integration into rubber chemicals. China Sunsine Chemical Holdings Ltd. dominates bulk accelerator output from Shandong province.
Rubber vulcanization denotes the cross-linking of elastomer chains via sulfur, peroxide, or resin systems to impart tensile strength, elasticity, and thermal resistance, typically requiring temperatures between 140°C and 200°C under controlled pressure. The process transforms raw rubber into durable materials for load-bearing industrial and transportation applications. Synthetic rubber commands the largest volume share among product types due to its tunable properties for tire treads and engine mounts. Sulfur vulcanization remains the most entrenched method, though peroxide curing is gaining traction in sealing systems where heat resistance and low compression set are critical specifications. Tire manufacturing absorbs the dominant share of vulcanized rubber output, while conveyor belts represent a mature, replacement-driven segment with stable margin pools.
EPA emissions standards in the United States restrict volatile organic compound releases from curing operations, compelling facility upgrades. REACH and the EU F-Gas Regulation in Europe mandate substitution of certain accelerators and blowing agents, reshaping formulation choices for exporters. China's MEE enforces wastewater and air quality thresholds around rubber chemical clusters. Stakeholders must monitor regulatory divergence across these three jurisdictions to avoid compliance-driven supply disruptions.
Market Dynamics
The rubber vulcanization market is undergoing a fundamental recalibration as regulatory pressure on curing emissions intersects with tire makers' demand for higher-efficiency sulfur systems. This collision is compressing formulation cycles and forcing accelerator suppliers to revalidate portfolios under REACH and EPA frameworks simultaneously.
Growth Catalysts
- EU F-Gas Regulation:The mandate to phase down hydrofluorocarbon blowing agents in rubber foams is accelerating adoption of water-based and CO2-based curing alternatives across European automotive sealing applications.
- China's tire production dominance:Integrated chemical supply chains in Shandong and Jiangsu provinces are lowering input costs for sulfur donors and peroxide initiators, pulling global accelerator procurement eastward.
- Peroxide curing systems:Heat-resistant sealing specifications in aerospace and industrial hydraulics are displacing sulfur-based methods in niche high-performance segments.
Market Restraints
- Accelerator supply concentration:Bulk thiazole and sulfenamide output clusters heavily in eastern China, exposing buyers to logistics disruptions and trade policy volatility.
- Petrochemical feedstock volatility:Benzene and aniline price swings directly compress margin pools for rubber chemical producers, particularly in specialty bisphenol resin curing agents.
- REACH substance restrictions:ECHA's accelerating scrutiny of certain thiuram and carbamate accelerators is forcing costly reformulation cycles ahead of sunset dates.
Strategic Opportunities
- India's tire capacity expansion:Domestic OEM localization mandates and PLI scheme incentives are creating demand for localized vulcanization chemical production to serve Apollo, MRF, and JK Tyre.
- Bio-based sulfur donors:Convergence of renewable feedstock chemistry and tire maker ESG targets is opening formulation partnerships between agricultural processors and rubber chemical specialists.
- Digital curing control systems:IoT-enabled press monitoring and predictive maintenance platforms are creating aftermarket service revenue streams for equipment retrofit in mature tire plants.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in sulfur-peroxide hybrid curing balances is retiring faster than universities and technical institutes can replenish pipelines.
- Legacy press fleet compatibility:Tier-2 and tier-3 tire manufacturers in Southeast Asia face capital constraints upgrading steam-heated curing presses to accommodate low-emission accelerator systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rubber Vulcanization Market |
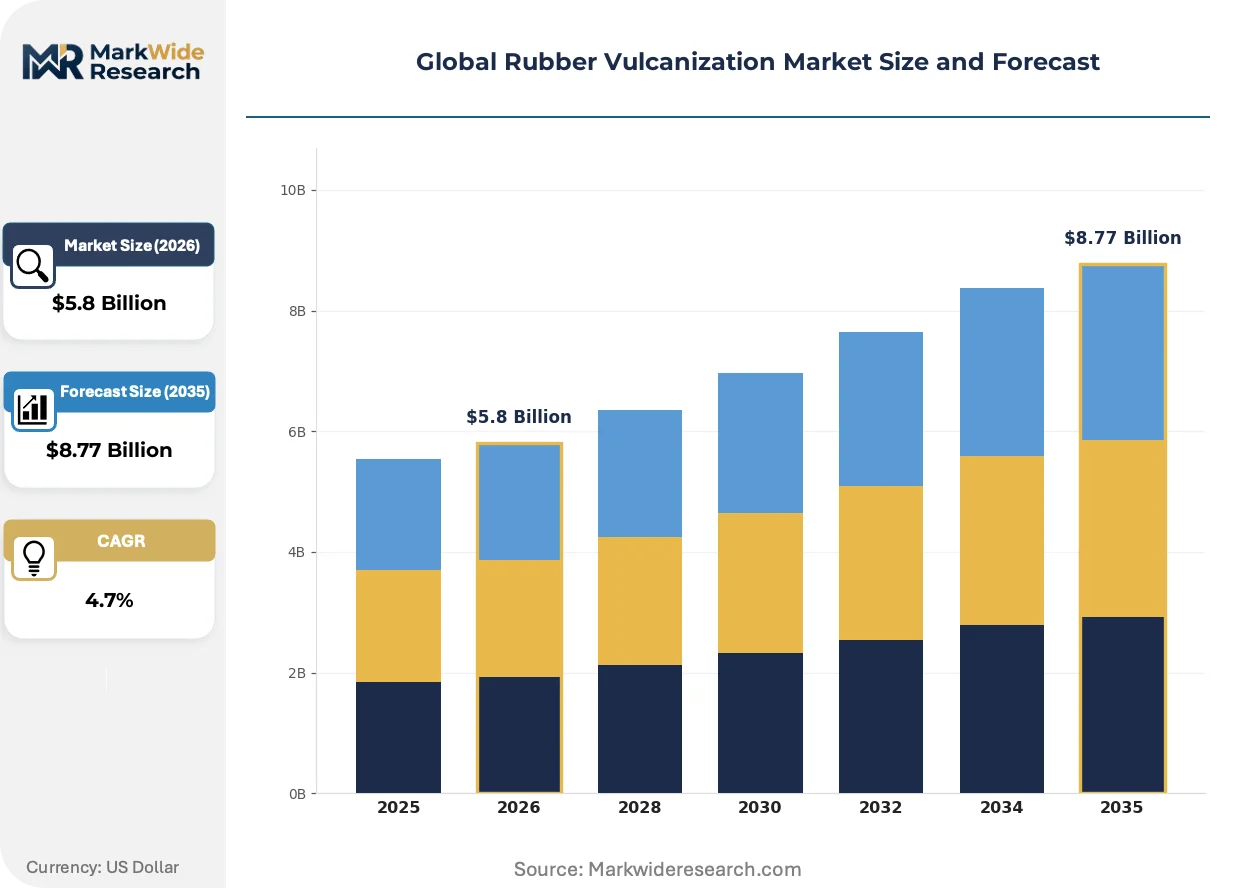
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.77 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Butyl Rubber, Chloroprene Rubber, Silicone Rubber Vulcanization Method: Accelerated Vulcanization, Peroxide Vulcanization, Sulfur Vulcanization, Radiation Vulcanization, Resin Vulcanization Application: Tire Manufacturing, Industrial Hoses, Conveyor Belts, Sealing Systems, Adhesive Products End User Industry: Construction Firms, Electronics Manufacturers, Footwear Producers, Automotive Component Makers, Sporting Goods Suppliers |
| Companies Covered | Eastman Chemical Company, China Sunsine Chemical Holdings Ltd., LANXESS, Shandong Stair Chemical & Technology Co., Ltd, Duslo, a.s., BASF SE, Kumho Petrochemical, Sumitomo Chemical Co., Ltd, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rubber Vulcanization Market Shifts & Advancements
Automation and regulatory stringency are converging to reshape how vulcanization chemistry is specified, monitored, and validated across tire and industrial rubber plants. The market is pivoting from commodity sulfur systems toward precision-controlled curing architectures.
Closed-loop nitrogen curing press technology is automating temperature and pressure modulation in tire manufacturing. Bridgestone and Michelin are retrofitting European plants with these systems to compress cycle times and reduce energy intensity. The technology is automating quality variance reduction that previously required manual press intervention, enabling consistent cure state across high-volume production runs.
REACH authorization requirements for certain thiuram accelerators are forcing systematic substitution with safer alternatives. Tire makers serving EU export markets must revalidate entire tread compounds under compressed timelines. The regulation is most acutely affecting winter tire specialists in Germany and Poland, who are accelerating partnerships with accelerator suppliers holding SVHC-free portfolios.
Specification-driven procurement consolidation is compressing supplier lists among tier-1 tire makers. Buyers are unbundling compound development from raw material supply, contracting directly with accelerator specialists rather than through integrated rubber compounders. This pattern is most visible in Japan, where Toyota and Honda tier suppliers are demanding full chemical disclosure and batch traceability from vulcanization additive vendors.
Global Rubber Vulcanization Market Segmentation
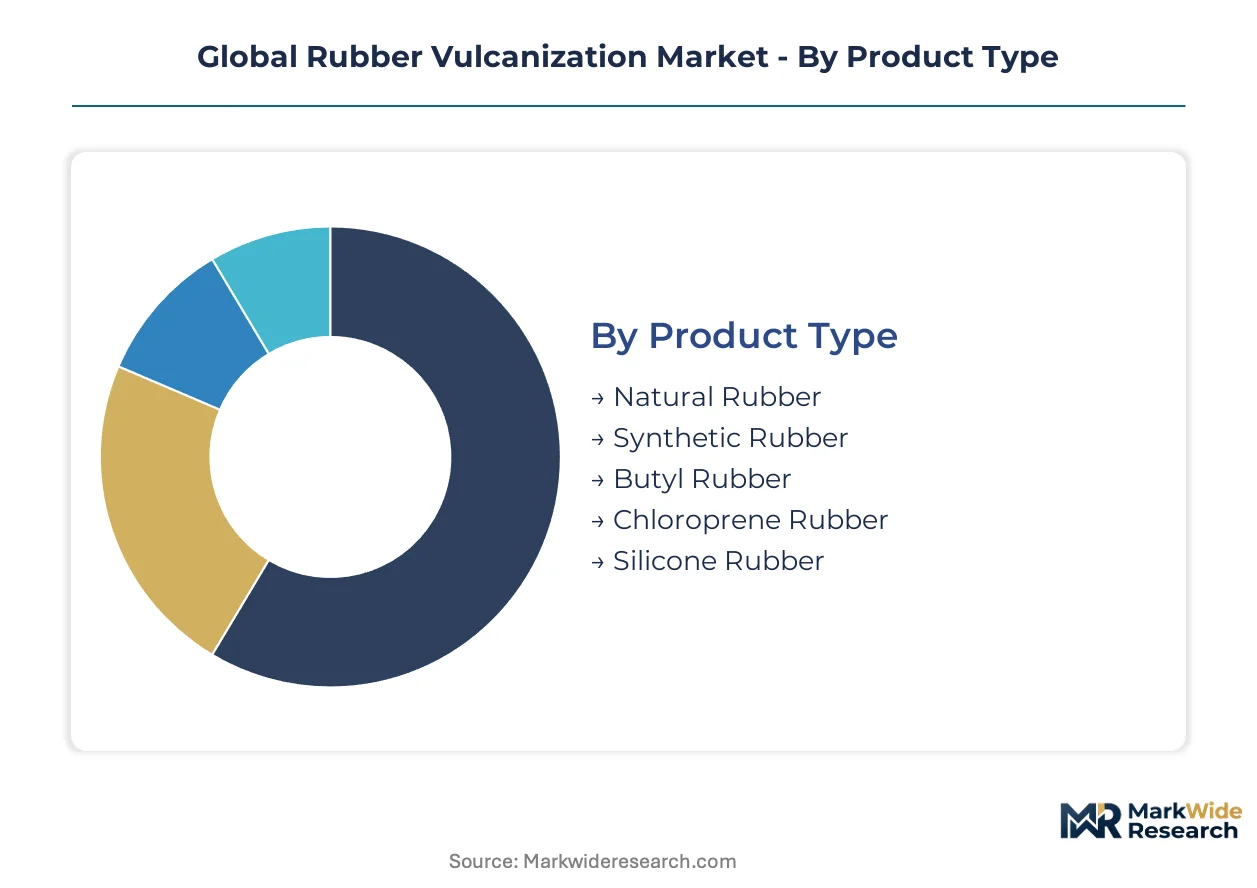
Segmentation in rubber vulcanization reveals how formulation choices lock into specific performance specifications and regulatory compliance tiers. Buyers select across product chemistry, curing architecture, and end-use demands with limited substitutability between tiers.
Product Type:
Cost tier differentiation separates commodity elastomers from specialty grades commanding formulation premiums.
- Synthetic Rubber:Polymer chains engineered through petrochemical feedstocks deliver tunable hardness, abrasion resistance, and thermal stability. Tire tread compounds in China and Thailand concentrate demand for styrene-butadiene and polybutadiene variants amid OEM fuel-efficiency mandates.
- Natural Rubber:Hevea brasiliensis latex yields superior tensile strength and low heat buildup for heavy-load applications. Southeast Asian plantation supply chains serve truck and bus tire makers requiring dynamic fatigue resistance under sustained stress cycles.
- Silicone Rubber:Siloxane backbone polymers withstand temperature extremes from -60°C to 230°C for aerospace gaskets and medical tubing.
- Butyl Rubber:Isobutylene-isoprene copolymer delivers exceptional gas impermeability for inner tubes and pharmaceutical stoppers.
- Chloroprene Rubber:Chlorinated polychloroprene resists weathering, ozone, and flame spread in industrial belting and protective equipment.
Volume sits with Synthetic Rubber; growth tilts toward Silicone Rubber.
Vulcanization Method:
Application temperature requirements and compression set specifications dictate curing system selection.
- Sulfur Vulcanization:Cross-linking via elemental sulfur and organic accelerators remains the dominant industrial protocol. Tire plants in Germany, Poland, and the United States run continuous steam-heated presses optimized for thiazole and sulfenamide accelerator packages.
- Peroxide Vulcanization:Organic peroxide initiators generate carbon-carbon bonds without accelerator residues. Automotive sealing systems and aerospace gaskets in Japan and South Korea specify peroxide curing for heat resistance above 150°C and minimal compression set under sustained load.
- Accelerated Vulcanization:Ultra-fast sulfur systems with guanidine or thiuram boosters compress cycle times for high-volume conveyor belt production.
- Resin Vulcanization:Phenolic and bisphenol resins cure butyl and halobutyl rubbers for pharmaceutical closure applications demanding extractable-free surfaces.
- Radiation Vulcanization:Electron beam or gamma irradiation cross-links without chemical curatives for medical devices and wire insulation requiring absolute purity.
Volume concentrates with Sulfur Vulcanization; Peroxide Vulcanization gains share fastest in heat-critical segments.
Application:
Customer type determines volume scale versus margin structure across replacement and OEM channels.
- Tire Manufacturing:Tread, sidewall, and inner liner compounds consume the dominant share of vulcanization chemicals. Integrated tire makers in China, India, and the United States specify accelerator packages validated under REACH, EPA, and domestic emissions frameworks simultaneously.
- Sealing Systems:O-rings, gaskets, and hydraulic seals demand precise cure state control for dimensional stability. Japanese and German automotive tier suppliers enforce batch traceability and full chemical disclosure from vulcanization additive vendors.
- Conveyor Belts:Steel-cord and fabric-reinforced belting for mining and bulk material handling runs mature replacement cycles with stable margin pools.
- Industrial Hoses:Oil-resistant nitrile and chloroprene constructions serve hydraulic and pneumatic power transmission.
- Adhesive Products:Pressure-sensitive and structural adhesives leverage vulcanized rubber tackifiers for construction and automotive assembly.
Volume anchors with Tire Manufacturing; Sealing Systems expands most quickly on aerospace and EV thermal management demand.
End User Industry:
Supply concentration varies sharply between fragmented construction procurement and consolidated automotive specification.
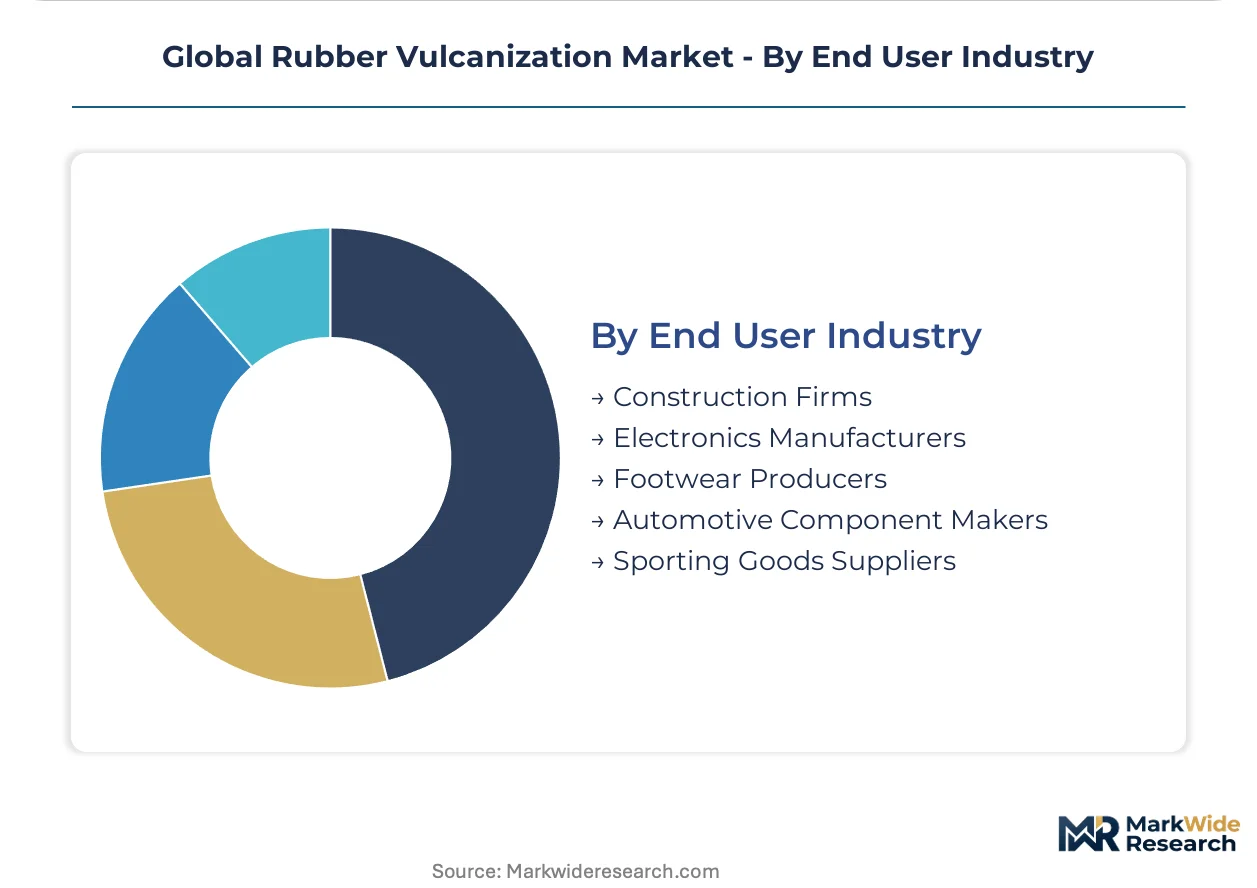
- Automotive Component Makers:Engine mounts, bushings, seals, and hoses face simultaneous pressure for lightweighting and durability. Toyota, Honda, and Volkswagen tier suppliers in Japan, Germany, and Mexico contract directly with accelerator specialists rather than compound intermediaries.
- Construction Firms:Roofing membranes, expansion joints, and waterproofing sheets specify EPDM and chloroprene vulcanizates for weathering resistance. Project-based procurement across dispersed contractors limits supplier concentration.
- Electronics Manufacturers:Connector seals, keypad membranes, and cable jacketing specify silicone and fluoroelastomer vulcanizates for dielectric stability.
- Footwear Producers:Soling compounds blend natural and synthetic rubbers for abrasion resistance and flex fatigue performance.
- Sporting Goods Suppliers:Golf ball cores, racket grips, and equipment padding leverage vulcanized rubber rebound characteristics.
Volume concentrates with Automotive Component Makers; Electronics Manufacturers shows steepest expansion trajectory on miniaturization and thermal management trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province's petrochemical corridor supplies the sulfur donors and accelerator intermediates that feed tire plants across East Asia. Germany's Rhineland chemical clusters refine specialty curing agents for automotive sealing specifications. The United States Gulf Coast provides butadiene feedstocks for synthetic rubber polymerization serving domestic tire makers.
China
Tire manufacturing capacity in Shandong and Jiangsu provinces consumes bulk thiazole and sulfenamide accelerators from integrated chemical parks. MEE enforcement of wastewater discharge limits around rubber chemical clusters is forcing facility upgrades in Zibo and Weifang. Qingdao's port infrastructure exports vulcanized rubber compounds to Southeast Asian tire assembly plants.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify low-emission curing systems for engine mounts and transmission seals. REACH authorization timelines for thiuram accelerators are compressing reformulation cycles at compounders serving Volkswagen and BMW tier suppliers. Cologne-Leverkusen chemical corridor hosts backward-integrated producers of specialty bisphenol curing resins.
United States
EPA emissions standards restrict volatile organic compound releases from curing presses at tire plants in South Carolina and Ohio. NHTSA fuel-efficiency mandates drive demand for lightweight vulcanized rubber components in Detroit-area automotive assembly. Houston-Galveston petrochemical complex supplies butadiene and styrene monomers for SBR polymerization.
Japan
Peroxide curing specifications from Toyota and Honda tier suppliers in Aichi and Shizuoka prefectures demand heat-resistant sealing compounds. METI industrial standards govern accelerator residue limits in automotive rubber parts. Osaka-Kobe chemical corridor produces guanidine and thiuram boosters for high-efficiency conveyor belt manufacturing.
India
Apollo Tyres and MRF expansion in Tamil Nadu and Gujarat is pulling accelerator procurement toward domestic chemical production. PLI scheme incentives for automotive component localization support vulcanization chemical manufacturing in Maharashtra. Chennai-Ennore industrial belt hosts emerging rubber chemical compounding facilities serving OEM tire contracts.
Global Rubber Vulcanization Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based sulfur donor chemistry and digital curing control architectures. The supplier base concentrates around three strategic archetypes: integrated petrochemical conglomerates with captive accelerator supply, specialty chemical houses focused on REACH-compliant curing agents, and regional bulk producers serving cost-sensitive tire markets. Competitive positioning hinges on backward integration into aniline and benzene feedstocks, plus simultaneous multi-jurisdictional regulatory validation.
Among integrated chemical specialists, Eastman Chemical Company exemplifies the petrochemical conglomerate archetype with bisphenol and resin portfolio control. LANXESS anchors European demand patterns through Rhineland-based rubber chemical production. China Sunsine Chemical Holdings Ltd. represents the scale-driven bulk accelerator segment with Shandong province manufacturing concentration. These three entities occupy distinct competitive positions without direct segment overlap, reflecting market stratification between specialty and commodity curing system supply.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| China Sunsine Chemical Holdings Ltd. |
| LANXESS |
| Shandong Stair Chemical & Technology Co., Ltd |
| Duslo, a.s. |
| BASF SE |
| Kumho Petrochemical |
| Sumitomo Chemical Co., Ltd |
| Arkema |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap accelerator specialists in Shandong province operate with minimal external financing, hoarding benzene and aniline inventories during feedstock dips to weaponize cost advantages against multinational compounders. This ownership pattern tightens supply discipline during petrochemical volatility while compressing margin pools for buyers lacking equivalent upstream control.
Pricing Analysis
Warranty and technical service bundling separates premium bisphenol resin suppliers from unbundled commodity sulfur donor traders. Three-tier pricing structure across premium, standard, and economy levels tracks REACH certification status and batch traceability depth. Pricing pressure stems from benzene feedstock volatility eroding specialty curing agent margins. Tier-2 tire manufacturers in Southeast Asia exhibit highest price sensitivity, while Japanese automotive tier suppliers prioritize chemical disclosure compliance over unit cost.
Supply Chain Analysis
India's PLI scheme localization mandates and domestic-content rules for automotive component procurement are pulling accelerator sourcing toward Maharashtra and Tamil Nadu chemical parks. Bulk thiazole and sulfenamide output concentrates in China, with secondary clusters in Germany and South Korea. The supply chain rests on aniline, benzene, and sulfur feedstocks. Single-source vulnerability runs through Shandong province's integrated chemical corridors. Distribution runs through direct contracts between accelerator specialists and tier-1 tire makers, bypassing traditional rubber compounder intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty bisphenol resin capacity constraints in the Cologne-Leverkusen corridor prop pricing discipline for REACH-compliant curing agents, framing this as a supply-constrained market where backward-integrated producers capture disproportionate value.
For Market Incumbents: Cement control over aniline and benzene feedstocks through captive production or long-term offtake agreements to defend against petrochemical volatility. Accelerate SVHC-free accelerator portfolio revalidation ahead of ECHA sunset dates to lock in Volkswagen and BMW tier supply contracts. Prioritize digital curing control system integration with European tire press retrofits to capture aftermarket service revenue streams. For New Entrants and Emerging Players: REACH authorization timelines for thiuram accelerators in Europe open a window for bio-based sulfur donor partnerships with agricultural processors serving tire maker ESG procurement mandates. Target India's domestic OEM localization requirements under PLI scheme incentives for Apollo Tyres and MRF supply contracts. Lead with full chemical disclosure and batch traceability capabilities to differentiate against opaque commodity traders. For Investors and Strategic Acquirers: Bridgestone and Michelin nitrogen curing press retrofit announcements across European plants are the leading indicator that digital curing control architectures will consolidate equipment and chemical supply relationships. Five-to-ten year viability favors specialty chemical houses with simultaneous EPA, REACH, and METI regulatory validation rather than single-jurisdiction bulk producers. Monitor ECHA thiuram accelerator sunset date enforcement as the inflection signal for SVHC-free formulation substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aniline Feedstocks | Captive benzene conversion secures margin pools against petrochemical volatility for LANXESS and Eastman. |
| SVHC-Free Accelerator Portfolio Revalidation | Pre-emptive ECHA compliance locks in Volkswagen and BMW tier supply contracts ahead of sunset dates. |
| Nitrogen Curing Press Retrofit Deployment | Bridgestone and Michelin installations compress cycle times and create chemical-automation bundling opportunities. |
| Bio-Based Sulfur Donor Partnership | Agricultural processor alliances with China Sunsine address tire maker ESG targets while diversifying feedstock risk. |
| PLI Scheme Localization in India | Maharashtra chemical park investments serve Apollo Tyres and MRF expansion with domestic accelerator procurement. |
Research Methodology
SEC 10-K filings, Cefic rubber chemical industry reports, and customs trade data formed the secondary backbone for supply chain mapping and competitive positioning assessment. Primary interviews with plant managers at Shandong and Rhineland chemical facilities, procurement leads at Japanese automotive tier suppliers, and technical R&D directors at accelerator specialists validated formulation substitution timelines and digital curing adoption patterns. Bottom-up volume modeling across tire manufacturing, sealing systems, and conveyor belt applications triangulated against top-down petrochemical feedstock demand projections.
Historical trendline analysis of sulfur donor and peroxide initiator consumption patterns established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product chemistry grade tiers, end-use industry concentration, regional production hub clustering, and regulatory compliance tier stratification. CAGRs were derived from elasticity-adjusted demand curves calibrated to OEM fuel-efficiency mandate intensity and REACH authorization timeline compression. Industry-specific forecast inputs included tire plant capacity utilization rates and accelerator residue limit evolution under METI industrial standards.
The model assumes a particular technology adoption path for closed-loop nitrogen curing press deployment; alternative pathways for steam-heated press retrofit with emission control add-ons would alter the outlook for digital control system penetration. Forecasts reflect assumptions regarding ECHA enforcement consistency, MEE wastewater discharge compliance trajectory, and PLI scheme incentive continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Cast Elastomers Market
Rubber
Silica for S-SBR Market
Rubber
Isobutylene Market
Rubber
Rubber Foam Materials Market
Rubber
Rubber Compound Market
Rubber
Butyl Reclaimed Rubber Market
Rubber
Butyl Rubber Market
Rubber
Rubber Ropes Market
Rubber
Liquid Polybutadiene Market
Rubber
Nitrile Butadiene Rubber (NBR) Powder Market
Rubber
Polybutadiene Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Hydroxyl Terminated Polybutadiene Market
Rubber
Synthetic Rubber Market
Rubber
Acrylic Rubber Market
Rubber
Global Rubber Coated Fabrics Market