
 Ethylene Vinyl Acetate (EVA) Market | 2026-2036
Ethylene Vinyl Acetate (EVA) Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Vinyl Acetate (EVA) Market Foresight
Polyolefin elastomers is repositioning EVA in select footwear midsole applications by offering comparable resilience at lower densities. Dow Inc. leverages its integrated ethylene chain to sustain cost leadership across high vinyl acetate grades. Hanwha Chemical Corporation anchors Asian supply for solar encapsulant films through dedicated Korean production lines. Exxon Mobil Corporation differentiates via proprietary metallocene catalyst technology that tightens molecular weight distribution.
Ethylene vinyl acetate is a random copolymer synthesized through high-pressure radical polymerization of ethylene and vinyl acetate monomer, with VA content typically ranging from 2% to 40% by weight dictating flexibility, clarity, and adhesion properties. The material functions primarily as a thermoplastic sealant, impact modifier, and adhesive layer in laminated structures requiring optical transparency or low-temperature toughness. Solar panel encapsulation within the application dimension commands premium pricing due to photovoltaic-grade purity requirements and 25-year performance warranties. High vinyl acetate grades in the grade dimension absorb disproportionate R&D investment as formulators target hot-melt adhesive displacement of solvent-based systems. Films in the product type dimension occupy mature volume positions in agricultural greenhouse cladding where UV stabilization technology determines replacement cycles.
The EPA regulates volatile organic compound emissions from EVA-based adhesive formulations under Clean Air Act Title I, pushing manufacturers toward higher-solids or reactive hot-melt systems. REACH restricts phthalate plasticizer migration in consumer-contact applications, compelling footwear producers to certify EVA compounds through ECHA-registered testing protocols. OSHA workplace exposure limits for vinyl acetate monomer residual concentrations shape plant ventilation investments and quality control sampling frequency. Stakeholders must monitor biobased ethylene feedstock certification schemes as brand owners embed Scope 3 emissions targets into polymer procurement specifications.
Market Dynamics
Solar panel encapsulation film demand from photovoltaic manufacturers is concentrating procurement power among a handful of module producers, reshaping contract structures and purity specifications across the value chain. The EU Green Deal and China's dual carbon goals are simultaneously tightening material specifications while expanding addressable volume.
Growth Catalysts
- REACH compliance mandates:European footwear producers are certifying EVA compounds through ECHA-registered testing protocols, eliminating phthalate plasticizers and creating specification premiums for compliant suppliers.
- Photovoltaic-grade purity requirements:Solar encapsulant films now carry 25-year performance warranties, locking in multi-year supply agreements and technical collaboration between resin producers and module manufacturers.
- Hot-melt adhesive displacement:Formulators targeting solvent-based system replacement are driving R&D investment toward high vinyl acetate grades with enhanced thermal stability.
Market Restraints
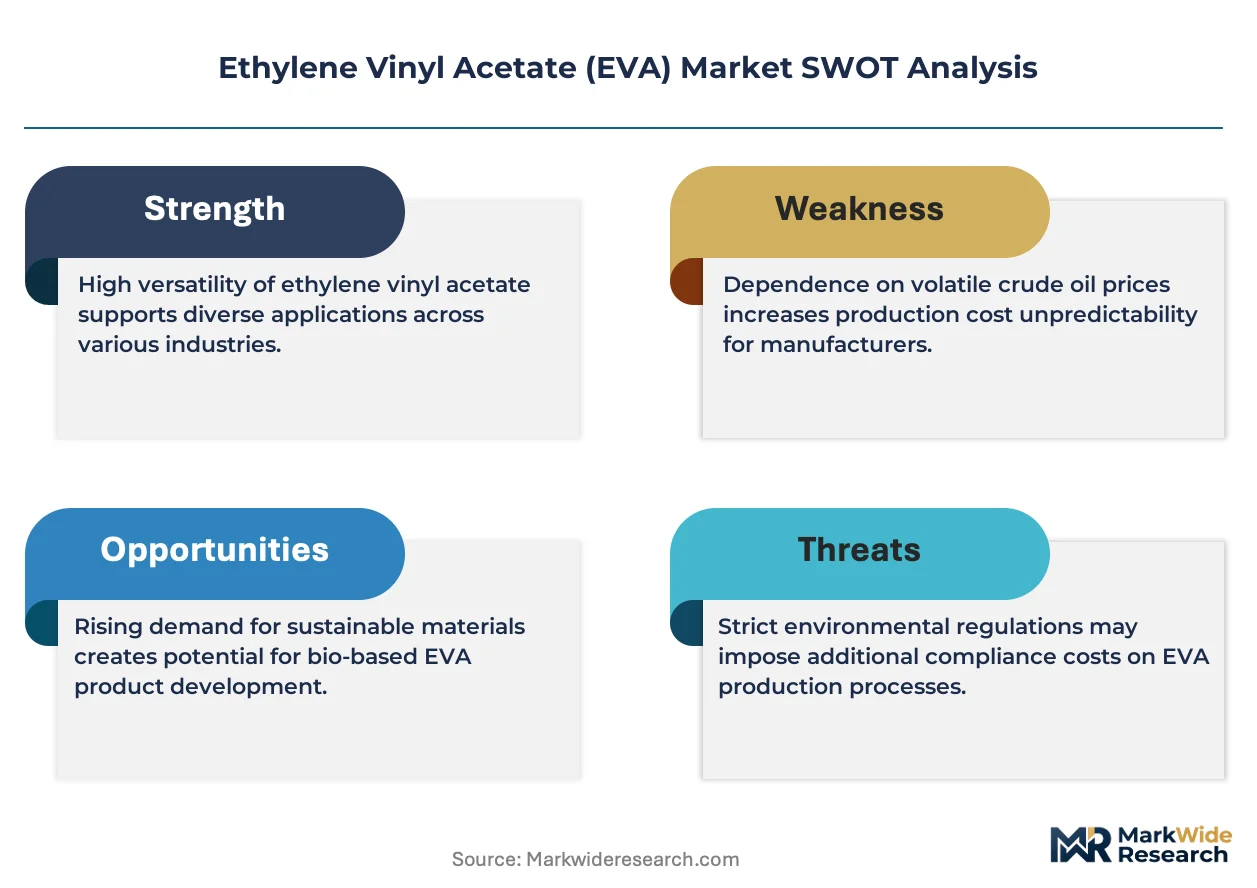
- Ethylene feedstock volatility:Crude oil price swings transmit directly to EVA production economics, compressing margins for non-integrated compounders lacking captive ethylene supply.
- Polyolefin elastomer substitution:Select footwear midsole applications are migrating to lower-density alternatives offering comparable resilience, capping volume growth in traditional EVA strongholds.
- Vinyl acetate monomer residual limits:OSHA workplace exposure thresholds shape plant ventilation investments and quality control sampling frequency, elevating fixed costs for smaller producers.
Strategic Opportunities
- Biobased ethylene certification schemes:Brand owners embedding Scope 3 emissions targets into polymer procurement specifications are creating preferential sourcing lanes for certified renewable feedstock suppliers.
- Agricultural greenhouse cladding replacement cycles:UV stabilization technology advances are shortening film replacement intervals in protected cultivation, expanding recurring revenue streams for film-grade producers.
- Metallocene catalyst convergence:Proprietary molecular weight distribution control is enabling premium positioning in optical clarity applications previously dominated by conventional Ziegler-Natta systems.
Industry Challenges
- Photovoltaic-grade contamination control:Achieving 25-year performance warranties requires sub-ppm metallic impurity management, demanding capital-intensive cleanroom compounding infrastructure.
- Legacy adhesive formulation requalification:EPA Clean Air Act Title I compliance is forcing manufacturers toward higher-solids or reactive hot-melt systems, triggering extended customer approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Vinyl Acetate (EVA) Market |
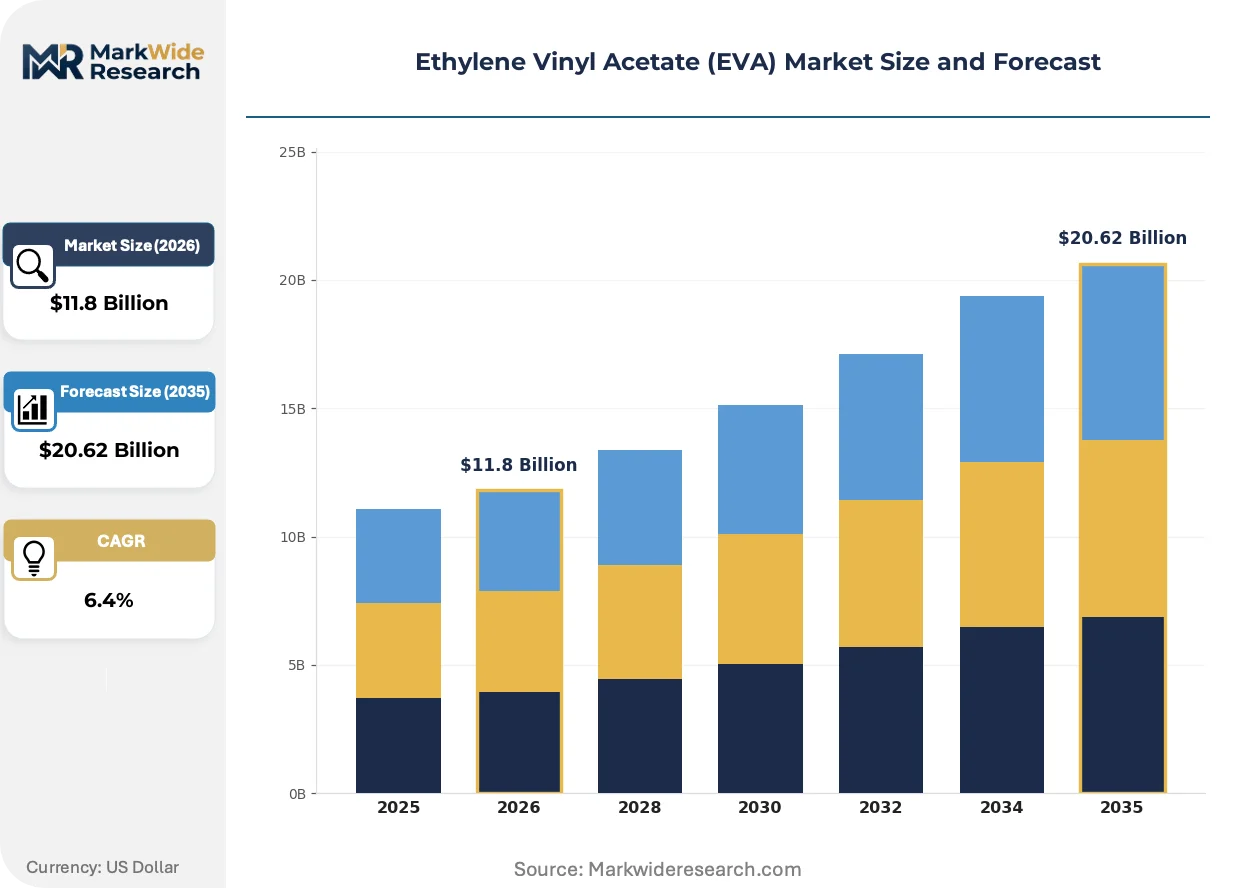
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
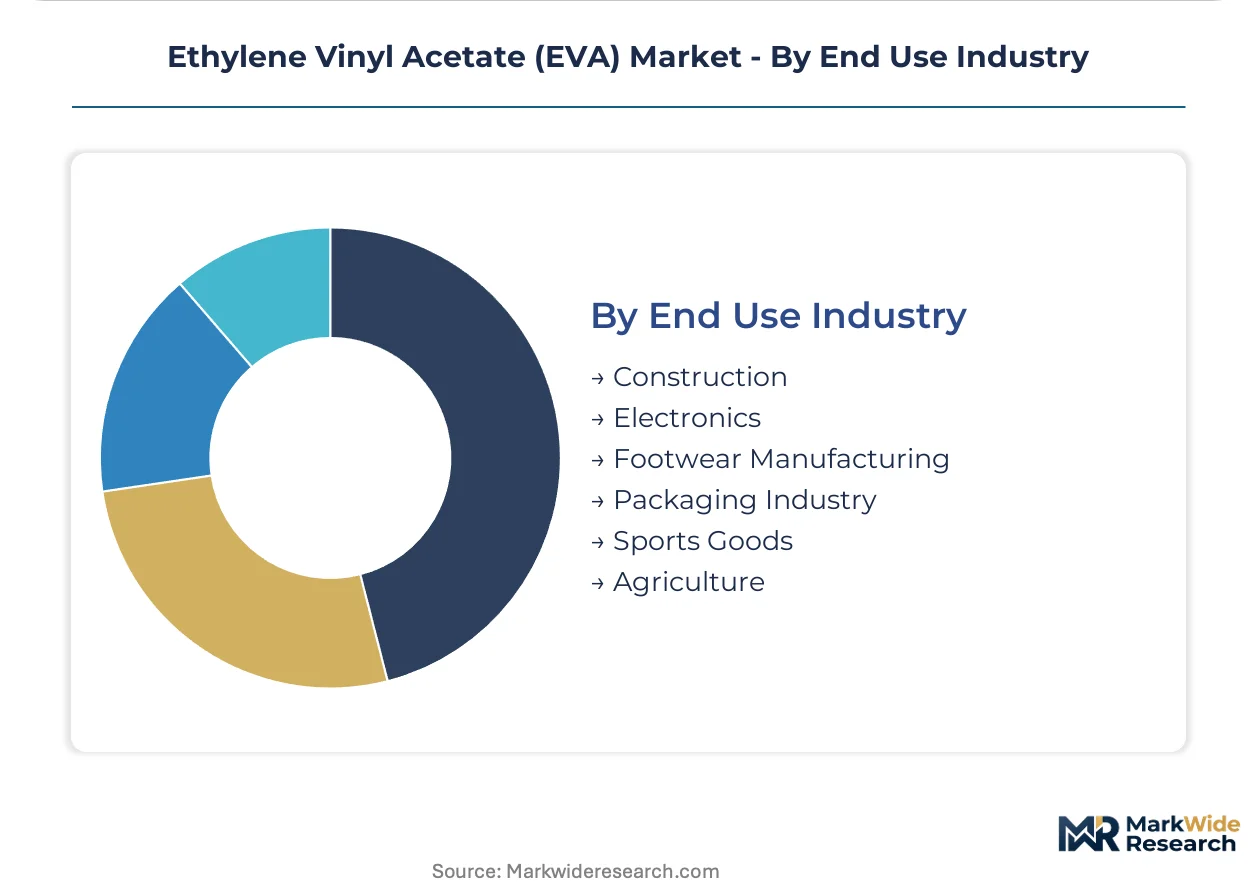
| Segmentation | Product Type: Granules, Films, Sheets, Foams, Powders Grade: Standard, High Vinyl Acetate, Low Density, High Melt Index, Cross-linked Application: Footwear Components, Solar Panel Encapsulation, Wire & Cable Insulation, Adhesives, Packaging, Sports Equipment End Use Industry: Construction, Electronics, Footwear Manufacturing, Packaging Industry, Sports Goods, Agriculture |
| Companies Covered | Exxon Mobil Corporation, Dow Inc., LyondellBasell Industries N.V., Celanese Corporation, Formosa Plastics Corporation, Hanwha Chemical Corporation, LG Chem Ltd., Borealis AG, Braskem S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Vinyl Acetate (EVA) Market Shifts & Advancements
Metallocene catalyst technology is tightening molecular weight distribution control, enabling precision-grade EVA variants that command specification premiums in optical and encapsulant applications. Three convergent developments are reshaping competitive positioning.
Peroxide-crosslinked EVA formulations for solar encapsulation are absorbing disproportionate R&D investment from compounders seeking to extend module service life. Photovoltaic manufacturers in China and South Korea are qualifying these grades at accelerated pace. This technology is absorbing technical risk that previously constrained supplier selection to a narrow qualified base.
REACH restrictions on phthalate plasticizer migration are compelling footwear producers to reformulate EVA compounds around bio-based or polymeric alternatives. The industrial consequence is a bifurcation between legacy compounders facing reformulation costs and early movers capturing certification premiums. Consumer-contact applications across the EU are responding by embedding ECHA-registered testing into supplier qualification workflows.
Module manufacturers are consolidating procurement around vertically integrated resin suppliers capable of certifying carbon footprint through Scope 3 accounting. Direct long-term agreements are displacing distributor-mediated spot purchasing in solar encapsulant film supply. This pattern is most visible in China, where domestic solar module production expansion is concentrating demand among state-linked energy conglomerates with stringent sustainability reporting requirements.
Ethylene Vinyl Acetate (EVA) Market Segmentation
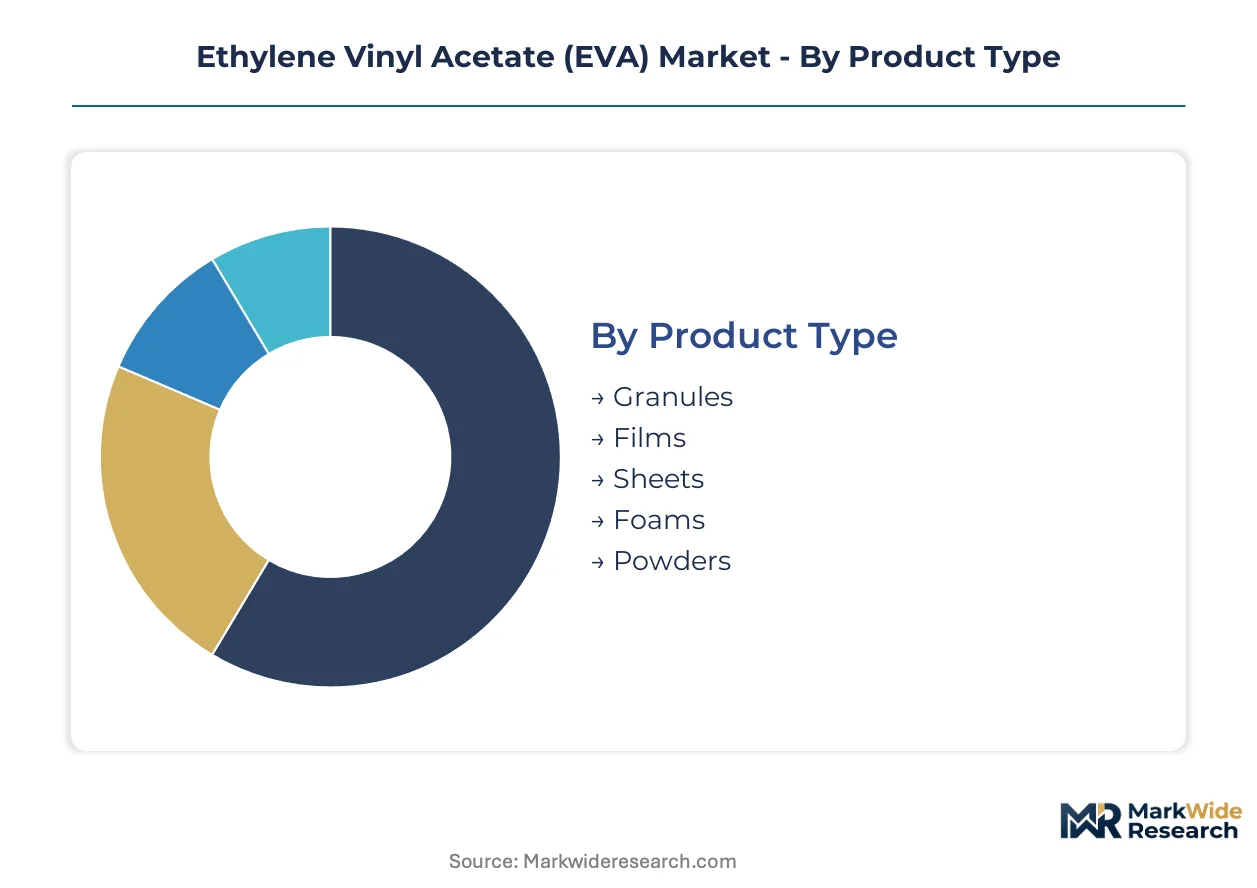
EVA's performance spectrum spans from rigid packaging films to soft foams, making granular segmentation essential for matching material specifications to end-use durability requirements. Each dimension reveals distinct capital intensity patterns and margin structures that determine supplier profitability.
Product Type:
Capital intensity varies sharply across physical forms, with films demanding the most sophisticated extrusion and biaxial orientation infrastructure.
- Films:Biaxially oriented or cast variants serve agricultural greenhouse cladding and photovoltaic encapsulation, where sub-ppm metallic impurity control commands premium pricing. Chinese solar module manufacturers are concentrating procurement among Korean and domestic suppliers capable of certifying 25-year performance warranties.
- Foams:Expanded cellular structures provide cushioning in athletic footwear midsoles and sports equipment padding, with density gradients dictating energy return characteristics. REACH phthalate restrictions are forcing compounders toward bio-based plasticizer systems that elevate formulation costs.
- Granules:Pelletized feedstock for injection molding and extrusion compounding.
- Sheets:Calendered or pressed flat stock for thermoforming and lamination substrates.
- Powders:Fine particulate grades for rotational molding and specialty coating applications.
Most installed capacity flows through Films. Expansion is steepest in Foams.
Grade:
Margin profiles diverge most dramatically by vinyl acetate content and crosslink density, with specialty grades capturing disproportionate value.
- High Vinyl Acetate:Grades exceeding 28% VA content deliver enhanced adhesion and optical clarity for hot-melt adhesive and solar encapsulant applications. EPA Clean Air Act Title I compliance is accelerating displacement of solvent-based systems in US manufacturing.
- Cross-linked:Peroxide or silane-grafted variants achieve thermoset characteristics that extend module service life beyond conventional thermal limits. Photovoltaic manufacturers in South Korea are qualifying these grades at accelerated pace to meet dual carbon goals.
- Standard:General-purpose grades with 12-18% VA for conventional packaging and molding.
- Low Density:Reduced crystallinity variants for flexible film and sheet applications.
- High Melt Index:Low molecular weight grades optimized for injection molding cycle times.
Standard grades dominate volume throughput. Cross-linked variants are climbing the fastest.
Application:
Customer concentration patterns vary by application, with solar encapsulation exhibiting the most extreme procurement consolidation.
- Solar Panel Encapsulation:Photovoltaic-grade films require cleanroom compounding infrastructure and carbon footprint certification through Scope 3 accounting. State-linked Chinese energy conglomerates are consolidating procurement around vertically integrated resin suppliers.
- Adhesives:Hot-melt formulations target solvent-based system replacement in packaging and woodworking, with higher-solids systems triggering extended customer requalification timelines under OSHA workplace exposure limits.
- Footwear Components:Midsole cushioning and outsole compounds face polyolefin elastomer substitution pressure in select density-critical applications.
- Wire & Cable Insulation:Low-smoke halogen-free jacketing for building and automotive harnesses.
- Packaging:Heat-seal layers and shrink films for food and consumer goods.
- Sports Equipment:Protective padding and grip surfaces for athletic gear.
Packaging absorbs the largest volume share. Solar encapsulation is gaining share fastest.
End Use Industry:
Regulatory exposure differs markedly by sector, with consumer-contact applications facing the most stringent migration testing protocols.
- Electronics:Solar module manufacturing and wire harness production demand photovoltaic-grade purity and RoHS compliance for EU market access. ECHA-registered testing protocols now embed into supplier qualification workflows.
- Footwear Manufacturing:Midsole and component producers must certify EVA compounds against REACH phthalate restrictions, creating specification premiums for early movers.
- Construction:Flooring underlayment and waterproofing membranes.
- Packaging Industry:Flexible food packaging and industrial shrink applications.
- Sports Goods:Protective equipment and athletic accessory manufacturing.
- Agriculture:Greenhouse cladding and silage wrap films with UV stabilization requirements.
Construction represents the most mature demand base. Electronics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta solar module clusters concentrate photovoltaic-grade EVA demand as Chinese manufacturers expand encapsulant film procurement. State-linked energy conglomerates anchor supply agreements with resin producers certifying carbon footprint through Scope 3 accounting. This procurement consolidation pattern is reshaping contract structures across Asian supply chains.
China
Domestic solar module production expansion drives photovoltaic-grade EVA consumption as manufacturers qualify peroxide-crosslinked formulations. MIIT dual carbon goals tighten material specifications while expanding addressable volume for certified suppliers. Yangtze River Delta and Pearl River Delta clusters concentrate cleanroom compounding infrastructure investments.
United States
EPA Clean Air Act Title I compliance accelerates hot-melt adhesive displacement of solvent-based systems in packaging and woodworking applications. OSHA workplace exposure limits for vinyl acetate monomer residual concentrations shape plant ventilation investments. Gulf Coast petrochemical corridors leverage integrated ethylene supply to sustain cost leadership across high vinyl acetate grades.
South Korea
Photovoltaic manufacturers qualify cross-linked EVA grades at accelerated pace to meet dual carbon goals and extend module service life. MFDS regulations on industrial chemical exposure inform workplace safety protocols at compounding facilities. Korean production lines anchor Asian supply for solar encapsulant films through dedicated photovoltaic-grade capacity.
Germany
REACH restrictions on phthalate plasticizer migration compel footwear producers to certify EVA compounds through ECHA-registered testing protocols. EU Green Deal material specifications tighten across European supply chains, creating specification premiums for compliant suppliers. Ruhr industrial region and Bavarian chemical clusters concentrate reformulation R&D investment.
India
BIS certification requirements for polymer imports create qualification barriers for non-domestic suppliers entering footwear and packaging applications. PLI scheme incentives for solar module manufacturing are stimulating photovoltaic-grade EVA demand growth. Gujarat and Maharashtra industrial corridors attract compounding capacity investments serving domestic solar and adhesive markets.
Ethylene Vinyl Acetate (EVA) Market Competitive Landscape
Global majors compete with regional champions across vinyl acetate grade specialization and photovoltaic certification capabilities. Market structure tiers between integrated petrochemical conglomerates with captive ethylene supply and independent compounders purchasing monomer on spot markets. Three archetypes dominate: upstream-integrated resin producers, specialty film compounders with cleanroom infrastructure, and regional distributors serving footwear and packaging formulators. Capacity expansion and backward integration into ethylene cracking represent the primary competitive moves as margin pressure transmits from feedstock volatility.
Within the integrated-resin tier, Exxon Mobil Corporation and Dow Inc. exemplify scale-driven positioning through proprietary catalyst technology and Gulf Coast production assets. Hanwha Chemical Corporation anchors Korean supply capabilities for Asian photovoltaic markets. These three entities represent distinct geographic anchors for regional procurement consolidation as module manufacturers consolidate supply agreements around vertically integrated partners capable of certifying carbon footprint through Scope 3 accounting.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Dow Inc. |
| LyondellBasell Industries N.V. |
| Celanese Corporation |
| Formosa Plastics Corporation |
| Hanwha Chemical Corporation |
| LG Chem Ltd. |
| Borealis AG |
| Braskem S.A. |
| Others |
Supply & Pricing Matrix
Peroxide-crosslinked EVA formulation adoption simultaneously elevates cleanroom compounding capital requirements and concentrates procurement leverage among photovoltaic module manufacturers capable of certifying 25-year performance warranties. This technology transition compresses margins for non-integrated compounders while rewarding resin producers with captive ethylene supply and carbon footprint accounting infrastructure.
Pricing Analysis
Ethylene feedstock volatility transmits directly to EVA production economics through spot-market naphtha and ethane pricing, compressing margins for compounders lacking integrated cracking capacity. Three-tier pricing structure across photovoltaic-grade, industrial-grade, and commodity-grade levels separates certified solar encapsulant films commanding specification premiums from standard packaging grades facing cost compression. Price differentiation hinges on metallic impurity control thresholds and Scope 3 carbon certification status. Smaller footwear compounders exhibit highest price sensitivity due to REACH reformulation cost absorption, while solar module manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Specialized chemical engineering talent shortages in the Yangtze River Delta and Korean industrial corridors constrain cleanroom compounding capacity expansion timelines. Supply concentrates in China, South Korea, and the United States, with Chinese state-linked energy conglomerates consolidating procurement around vertically integrated domestic suppliers. The chain draws from ethylene monomer, vinyl acetate monomer, and peroxide crosslinking agents, with vinyl acetate residual management shaping plant ventilation investments. Single-source vulnerability runs through Korean photovoltaic-grade film capacity. Distribution runs through direct long-term agreements displacing spot-market distributor channels in solar encapsulant segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU REACH phthalate restrictions and China's dual carbon goals simultaneously constrain formulation flexibility and expand certified-supplier premiums.
For Market Incumbents: Acquire cleanroom compounding infrastructure in the Yangtze River Delta to anchor photovoltaic-grade supply agreements with state-linked Chinese module manufacturers. Defend margin position by securing biobased ethylene feedstock certification ahead of brand-owner Scope 3 procurement mandates, while accelerating peroxide-crosslinked grade qualification timelines to match Korean competitor pace.
For New Entrants and Emerging Players: Enter via agricultural greenhouse cladding film segments where UV stabilization technology gaps create white-space opportunities for regional compounders lacking solar-grade certification infrastructure. Target India's PLI-stimulated solar module manufacturing corridor before domestic Korean and Chinese suppliers establish localized compounding presence. Lead with reactive hot-melt adhesive formulations displacing solvent-based systems under EPA Clean Air Act compliance timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among independent compounders purchasing ethylene on spot markets without photovoltaic-grade certification capabilities. Long-term viability favors upstream-integrated resin producers with metallocene catalyst technology and carbon accounting infrastructure. Monitor BIS certification requirement enforcement in India as inflection signal for regional supply consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Cracking | Gulf Coast and Korean producers secure cost leadership against naphtha-dependent compounders. |
| Photovoltaic-Grade Cleanroom Certification | MIIT dual carbon goals in China lock in multi-year supply agreements with module manufacturers. |
| Biobased Feedstock Certification Program | REACH and EU Green Deal procurement specifications create preferential sourcing lanes. |
| Peroxide Crosslinking Technology Licensing | South Korean manufacturers extend module service life beyond conventional thermal limits. |
| Long-Term Supply Agreement with State-Linked Conglomerates | Yangtze River Delta solar clusters consolidate procurement around vertically integrated partners. |
Research Methodology
Multiple input streams — plant managers at compounding facilities, procurement leads at photovoltaic module manufacturers, distribution channel partners in Asian supply chains, and technical R&D directors at catalyst technology developers — were reconciled against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up volume modeling across vinyl acetate grade tiers and top-down demand validation from end-use industry consumption patterns were cross-referenced to establish market sizing.
Historical capacity utilization trends were cross-referenced against panel input from solar module procurement officers and footwear compounder reformulation timelines to construct demand elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product type, vinyl acetate content grade, application, and end-use industry, with CAGRs derived from weighted average of historical trajectory and technology adoption curve analysis. Forecast inputs incorporated EPA Clean Air Act compliance timelines and MIIT dual carbon policy implementation pace.
Inputs from ECHA-registered testing protocol disclosures and BIS certification requirement announcements were available through the study window; gaps in real-time vinyl acetate monomer spot pricing transparency introduce uncertainty bands around margin compression scenarios for non-integrated compounders. Practitioners should monitor OSHA workplace exposure limit revision proposals and biobased ethylene feedstock certification scheme adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
Europe Engineering Plastics Market