
 Polysulfide Resin Market | 2026-2036
Polysulfide Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Polysulfide Resin Market Analytics
High-performance aerospace-grade specifications are redrawing competitive boundaries in the polysulfide resin space. AkzoNobel leverages its coatings heritage to dominate marine and protective segments with tailored sulfur-polymer formulations. BASF sustains R&D intensity across European manufacturing centers, developing low-temperature-cure variants for automotive assembly. Huntsman Corporation anchors North American supply through specialized adhesives and sealants for commercial aviation MRO channels.
Polysulfide resins comprise liquid polymers with reactive thiol-terminated backbones, typically cured through manganese dioxide or epoxy systems to form elastomeric seals with exceptional fuel resistance and flexibility across temperature extremes from minus fifty-five to plus one hundred thirty degrees Celsius. Liquid formulations lead volume shipments due to their ease of application in aerospace fuel tank sealing and construction joint filling, while paste grades capture premium margins in electronics encapsulation where precise dispensing and gap-filling geometry matter. Solid polysulfide compounds occupy a mature niche in molded gasket production, with powder formats gaining traction in additive manufacturing feedstock development for custom seal geometries.
EPA regulations constrain solvent content in architectural sealants, pushing formulators toward higher-solids polysulfide systems. REACH authorization requirements under ECHA oversight restrict certain curing agent chemistries, redirecting R&D spending toward compliant manganese dioxide and peroxide alternatives. ISO 8339 and ASTM C920 standards govern elastomeric joint sealant performance, creating certification barriers for new entrants. Stakeholders must track evolving building energy codes and aviation sustainability mandates to anticipate specification shifts before they crystallize in procurement contracts.
Market Dynamics
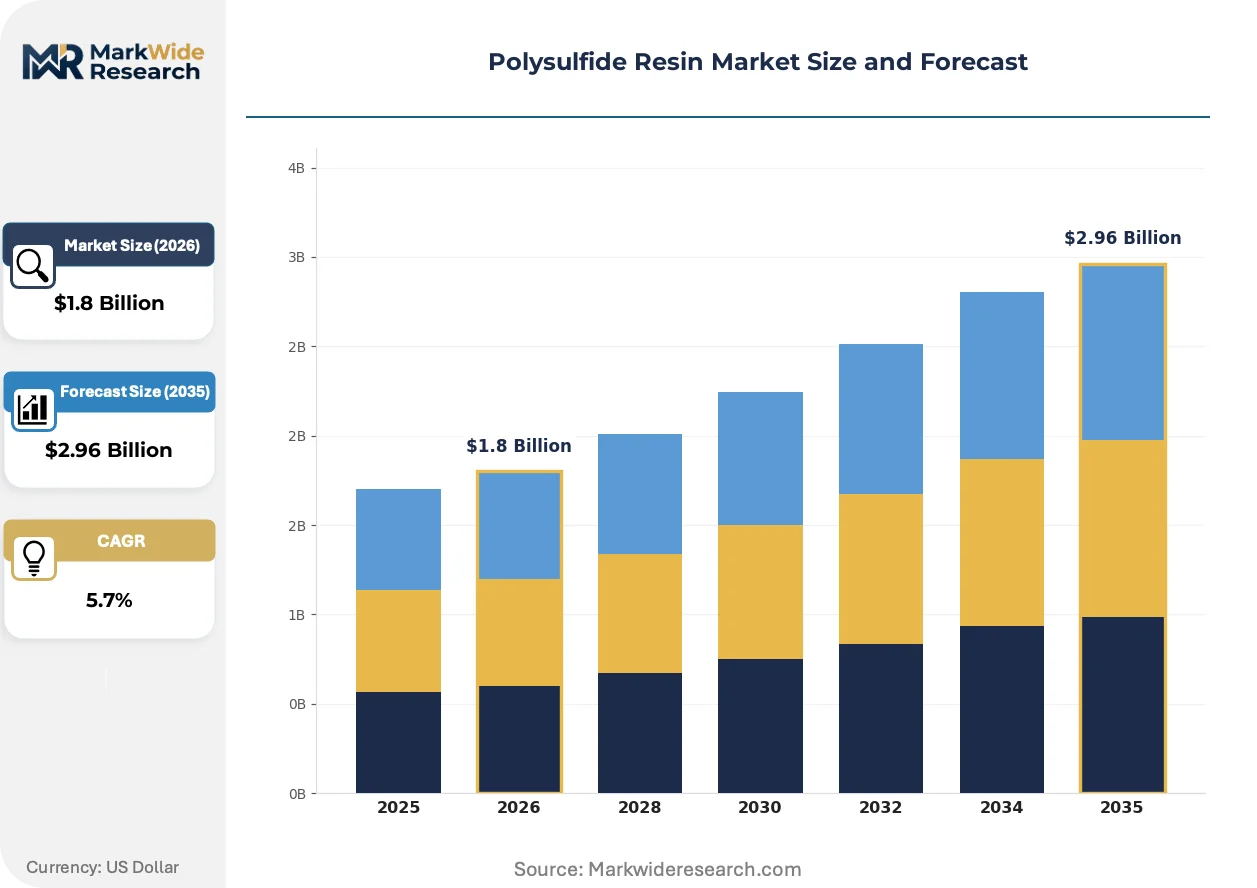
Aerospace OEM procurement specifications for fuel-efficiency gains are compressing qualification cycles and forcing reformulation investments across polysulfide resin suppliers. REACH authorization requirements under ECHA oversight and EPA solvent-content thresholds are simultaneously tightening, creating dual-compliance pressure that favors integrated formulators with regulatory affairs capabilities.
Growth Catalysts
- Aerospace Fuel-Tank Sealing Mandates:Commercial aviation OEMs specify polysulfide compounds for integral wing tank sealing to meet FAA fuel-efficiency and safety standards, pulling volume through MRO channels and new airframe programs.
- Construction Joint Standards:ISO 8339 and ASTM C920 certification requirements for elastomeric sealants in high-movement building joints are displacing silicone alternatives in cold-climate infrastructure projects.
- Automotive Structural Bonding:German automotive OEMs and tier-one suppliers specify manganese dioxide-cured polysulfide systems for crash-resistant structural adhesives in electric vehicle battery enclosures.
Market Restraints
- Thiol Raw Material Concentration:Liquid polysulfide polymer production concentrates among specialty chemical manufacturers in Western Europe, exposing formulators to single-source risk and freight cost volatility.
- REACH Authorization Friction:ECHA oversight of certain epoxy curing agents restricts formulation flexibility, forcing R&D redirection toward compliant peroxide and manganese dioxide systems with longer development timelines.
- Polyurethane Substitution Threat:Two-component polyurethane sealants with comparable fuel resistance and faster cure profiles are capturing share in non-aviation transportation applications where specification flexibility exists.
Strategic Opportunities
- India Infrastructure Build-Out:National highway expansion and metro rail construction under the Ministry of Road Transport and Highways specifications create demand for ASTM C920-compliant joint sealants in high-vibration civil engineering.
- Electronics Encapsulation:Paste-grade polysulfide formulations with precise dispensing characteristics are penetrating semiconductor packaging and sensor module protection against thermal cycling and chemical exposure.
- Additive Manufacturing Feedstock:Powder-format polysulfide compounds are emerging as printable materials for custom gasket geometries in aerospace aftermarket and industrial maintenance applications.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in thiol-terminated polymer chemistry and manganese dioxide cure kinetics is concentrating among retiring technical staff at established European suppliers.
- Dual Certification Timelines:Simultaneous FAA airworthiness qualification and EPA VOC compliance verification for new aerospace sealant products extends time-to-revenue by eighteen to thirty-six months.
- Legacy Equipment Integration:Paste-grade dispensing systems in automotive assembly plants require retrofitting for thiol-based material handling, complicating specification switches from incumbent polyurethane platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polysulfide Resin Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Paste, Powder Application: Aerospace, Automotive, Construction, Electronics End User: Manufacturers, Contractors, OEMs, Distributors Distribution Channel: Online, Direct Sales, Retail, Wholesale |
| Companies Covered | AkzoNobel, BASF, Nouryon, Master Bond, Huntsman Corporation, PPG Industries, Wacker Chemie, Arkema, Toray Fine Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polysulfide Resin Market Evolving Landscape
Low-temperature-cure chemistry and digital formulation tools are compressing product development cycles while regulatory data management systems reshape how compliance documentation travels through supply chains. These shifts are redrawing competitive boundaries between integrated chemical producers and specialized compounders.
Two-part polysulfide systems with sub-ambient cure activation are fragmenting the traditional aerospace sealant market. Airframe manufacturers adopting these formulations reduce tank sealing cycle times by eliminating elevated-temperature post-cure requirements. The technology is fragmenting procurement patterns as MRO operators gain in-situ repair capabilities previously restricted to OEM facilities.
EPA architectural sealant VOC thresholds are forcing higher-solids formulation migration. Formulators are eliminating aromatic solvents and reducing exempt compound reliance, which increases raw material costs but opens specification access to federal and state green building procurement. Construction sealant distributors in California and New York are prioritizing compliant inventory ahead of enforcement phase-ins.
Specification-driven procurement consolidation is compressing supplier bases in commercial aviation. Airlines and lessors now require centralized sealant qualification databases with full formulation disclosure, displacing fragmented spot-buying through regional distributors. This behavioral shift is most visible in North American and European MRO networks where fleet commonality programs dominate sourcing decisions.
Polysulfide Resin Market Segmentation
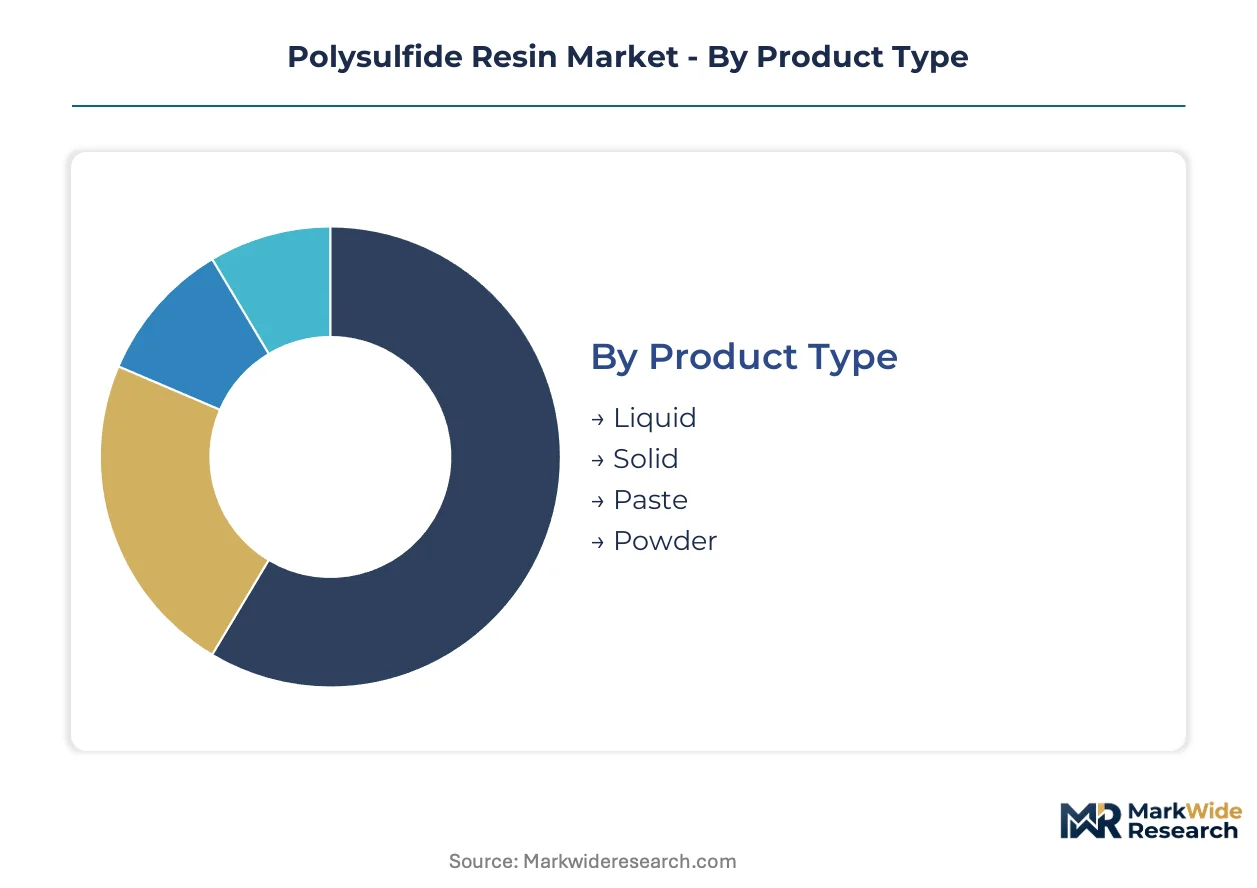
Polysulfide resin segmentation reveals distinct supply chain configurations across physical forms and customer touchpoints. Product type determines manufacturing location and export intensity, while end-user structure shapes pricing power and technical service requirements.
Product Type:
Liquid and paste grades dominate export flows from Western European manufacturing hubs, while solid and powder formats serve more localized construction and industrial maintenance demand.
- Liquid:Thiol-terminated polymers in pourable consistency cure through manganese dioxide or epoxy systems to form fuel-resistant elastomeric seals. German and French specialty chemical manufacturers ship liquid formulations globally for aerospace fuel tank sealing and construction joint filling, with airframe OEM procurement specifications driving qualification investments. Liquid holds the largest share; momentum sits with paste.
- Paste:Thixotropic formulations with precise viscosity control enable automated dispensing in electronics encapsulation and aerospace seam sealing. Paste-grade specifications command premium positioning in semiconductor packaging and sensor module protection, where gap-filling geometry and thermal cycling resistance justify higher unit economics. German automotive tier-one suppliers increasingly specify paste systems for electric vehicle battery enclosure bonding.
- Solid:Pre-formed compounds serve molded gasket production with established cure profiles and dimensional stability. Solid formats concentrate in regional supply chains serving industrial maintenance and plumbing applications.
- Powder:Granular polysulfide compounds are emerging as additive manufacturing feedstock for custom seal geometries in aerospace aftermarket applications.
Liquid formulations anchor revenue concentration; paste grades capture expanding specification scope in precision applications.
Application:
Application segmentation tracks regulatory intensity and qualification timeline variation across end-use sectors.
- Aerospace:Integral wing tank sealing and fuel system encapsulation demand FAA-qualified formulations with minus fifty-five to plus one hundred thirty degrees Celsius performance envelopes. Airframe manufacturers in the United States and France specify polysulfide compounds for fuel-efficiency compliance, pulling volume through MRO channels and new production programs. Aerospace commands the highest margin tier; construction shows steepest volume expansion.
- Automotive:Structural bonding applications in electric vehicle battery enclosures utilize manganese dioxide-cured systems for crash resistance and thermal management. German OEMs and tier-one suppliers drive specification adoption, with assembly plants requiring paste-grade dispensing system retrofits.
- Construction:Elastomeric joint sealants for high-movement infrastructure must satisfy ISO 8339 and ASTM C920 certification. Cold-climate bridge and highway projects in Canada and Scandinavia favor polysulfide over silicone alternatives for low-temperature flexibility retention.
- Electronics:Semiconductor packaging and sensor module protection leverage paste-grade dispensing precision against chemical exposure and thermal cycling stress.
Aerospace generates premium returns; construction joint standards are expanding addressable volume fastest.
End User:
End-user structure concentrates technical service requirements and formulation disclosure obligations among integrated OEMs.
- Manufacturers:Compounders and formulators purchasing raw liquid polymer for captive sealant production.
- Contractors:Construction and MRO installation crews procuring certified sealants through distributor networks.
- OEMs:Airframe and automotive original equipment manufacturers with centralized qualification databases and full formulation disclosure requirements. OEM procurement consolidation in North American and European aviation networks is displacing fragmented spot-buying.
- Distributors:Regional inventory holders managing California and New York green building compliance ahead of EPA enforcement phase-ins.
OEMs concentrate specification authority; distributors mediate regulatory compliance access for smaller contractors.
Distribution Channel:
Channel selection reflects order size, technical support needs, and geographic proximity to manufacturing.
- Online:Digital procurement platforms serve small-volume maintenance and repair customers with standardized product grades.
- Direct Sales:Technical sales engineers manage aerospace OEM and automotive tier-one relationships with formulation customization and qualification support.
- Retail:Hardware and industrial supply outlets stock construction sealants for contractor walk-up demand.
- Wholesale:Regional distributors aggregate inventory for multi-site contractors and MRO operators across fleet commonality programs.
Direct sales capture strategic accounts; wholesale channels scale geographic coverage for specification-driven demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France demonstrate low price elasticity where aerospace qualification requirements dominate procurement, while construction contractors in India and Brazil exhibit high sensitivity to unit costs in bulk sealant purchasing.
United States
FAA fuel-efficiency mandates and commercial aviation MRO expansion drive polysulfide specification in integral wing tank sealing. EPA solvent-content thresholds for architectural sealants push formulators toward higher-solids systems. The Pacific Northwest and Southern California aerospace clusters concentrate airframe manufacturing procurement with centralized qualification databases.
Germany
Automotive OEMs and tier-one suppliers specify manganese dioxide-cured polysulfide systems for electric vehicle battery enclosure bonding. REACH authorization requirements under ECHA oversight restrict certain epoxy curing agents, redirecting R&D toward compliant alternatives. The Stuttgart and Munich automotive engineering corridors anchor specification authority for structural adhesives.
France
Airframe manufacturers specify polysulfide compounds for fuel system encapsulation in new production programs. ECHA oversight of curing agent chemistries creates compliance friction for formulators serving both aerospace and construction sectors. The Toulouse aerospace cluster drives qualification investments for minus fifty-five to plus one hundred thirty degrees Celsius performance envelopes.
India
National highway expansion and metro rail construction under Ministry of Road Transport and Highways specifications create demand for ASTM C920-compliant joint sealants. BIS certification requirements for construction chemicals shape import and local formulation strategies. The Delhi-Mumbai Industrial Corridor and Bangalore infrastructure projects concentrate civil engineering procurement.
China
Domestic aviation programs and commercial aircraft manufacturing pull volume for fuel-resistant sealant specifications. GB standards for construction sealants and evolving environmental regulations on VOC emissions influence formulation migration. The Yangtze River Delta aerospace and chemical manufacturing base concentrates supply chain integration.
Polysulfide Resin Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical majors commanding premium aerospace qualifications and regional compounders capturing construction volume through price-competitive formulations. The market structure tiered around three strategic archetypes: diversified coatings and adhesives multinationals with regulatory affairs capabilities, European specialty chemical producers with thiol polymer heritage, and regional formulators serving localized construction demand. Dominant competitive moves include portfolio diversification into low-temperature-cure variants and strategic partnerships with automotive tier-one suppliers for electric vehicle battery bonding specifications.
Among integrated chemical producers, AkzoNobel, BASF, and Huntsman Corporation exemplify the technology-architecture archetype. AkzoNobel occupies a position reflecting coatings heritage applied to sulfur-polymer formulation. BASF sits within the European R&D-intensive tier developing compliant cure systems. Huntsman Corporation anchors North American supply chain presence through specialized adhesives positioning. These three represent differentiated approaches to regulatory compliance and qualification-intensive end-use penetration.
| Leading Market Players |
|---|
| AkzoNobel |
| BASF |
| Nouryon |
| Master Bond |
| Huntsman Corporation |
| PPG Industries |
| Wacker Chemie |
| Arkema |
| Toray Fine Chemicals |
| Others |
Value Network & Pricing Analysis
FAA airworthiness qualification requirements gate both supplier entry and price differentiation simultaneously, compressing procurement cycles for aerospace-grade formulations while elevating premium tiers for compliant manganese dioxide-cured systems. Construction contractors face divergent economics where ASTM C920 certification creates specification premiums in cold-climate infrastructure, while uncertified bulk sealants compete on unit cost in price-sensitive emerging markets.
Pricing Analysis
Aftermarket MRO service contracts and extended qualification support drive lifetime value for established suppliers. Three-tier pricing structure across aerospace-qualified, automotive-specified, and construction-grade levels separates manganese dioxide-cured systems from peroxide alternatives from uncertified commodity formulations. Cost compression in construction-grade liquid formulations is intensifying because REACH-compliant curing agent substitution elevates raw material expenses. Distributors in California and New York exhibit lowest price sensitivity where green building procurement mandates guarantee volume; Indian highway contractors demonstrate highest sensitivity where ASTM C920 compliance remains optional.
Supply Chain Analysis
Strategic stockpiling of liquid polysulfide polymer dominates aerospace procurement, while just-in-time delivery prevails in automotive assembly integration. Manufacturing concentrates in Germany, France, and the United States, with German specialty chemical producers anchoring European export flows. Formulation draws from thiol-terminated polymer feedstock, manganese dioxide curing agents, and epoxy hardener systems. Single-source vulnerability in Western European liquid polymer production exposes formulators to freight cost volatility and qualification disruption. Distribution runs through direct technical sales for OEM accounts and wholesale regional networks for construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-temperature-cure chemistry disruption is fragmenting established aerospace procurement patterns, creating acceleration windows for compliant formulators and retrofit service providers.
For Market Incumbents: Secure manganese dioxide curing agent supply through backward integration or long-term offtake agreements with European specialty chemical producers. Deepen qualification databases with full formulation disclosure to defend against centralized airline procurement consolidation. Prioritize R&D investment in peroxide cure systems to preempt REACH authorization restrictions on epoxy hardeners. For New Entrants and Emerging Players: Anchor in India's national highway expansion and metro rail construction, where Ministry of Road Transport and Highways specifications create ASTM C920-compliant demand without entrenched supplier relationships. Target electronics encapsulation paste grades for semiconductor packaging applications, where precision dispensing requirements justify premium positioning. Pursue technical partnership routes with German automotive tier-one suppliers seeking electric vehicle battery enclosure bonding alternatives. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified coatings parents with underutilized sulfur-polymer R&D capabilities and dormant aerospace qualification pathways. Long-term viability hinges on regulatory compliance infrastructure and OEM certification relationships rather than commodity volume scale. Monitor ECHA authorization list updates for epoxy curing agents as the critical inflection signal for formulation migration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thiol Polymer Feedstock | Captive supply of liquid polysulfide polymer reduces single-source exposure from Western European producers. |
| Low-Temperature-Cure Chemistry Development | Elimination of elevated-temperature post-cure requirements compresses airframe tank sealing cycle times. |
| REACH-Compliant Peroxide Cure System Investment | ECHA authorization restrictions on epoxy hardeners redirect R&D toward compliant alternatives with longer timelines. |
| Centralized Qualification Database Expansion | Full formulation disclosure meets airline and lessor procurement consolidation requirements in North American MRO networks. |
| Additive Manufacturing Feedstock Positioning | Powder-format polysulfide compounds enable custom gasket geometries for aerospace aftermarket applications. |
Research Methodology
Cross-validation between primary interviews with aerospace procurement directors, automotive tier-one supplier technical leads, construction chemical distributors, and ECHA regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from FAA airworthiness directives, ECHA authorization lists, ASTM C920 certification databases, and customs trade flow records. Bottom-up segmentation modeling triangulates against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis tests volume and value outputs against alternative regulatory enforcement timelines and raw material cost scenarios. The analytical framework segments by physical form, application sector, end-user archetype, and geographic production hub across the projection horizon. CAGRs derive from segment-level elasticity modeling and input-output coefficient analysis. Forecast inputs incorporate aerospace OEM production schedules, electric vehicle battery enclosure specification adoption curves, and infrastructure investment commitments.
Decision-makers should treat outputs as directional under sustained FAA fuel-efficiency mandate enforcement and REACH authorization friction assumptions; material deviation would warrant model refresh. Specific risk factors include polyurethane substitution acceleration in non-aviation transportation, thiol raw material supply disruption, and dual certification timeline extension beyond standard qualification windows. Revision becomes warranted when ECHA epoxy hardener restriction thresholds trigger formulation migration at scale.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market