
 Styrene Acrylonitrile (SAN) Resins Market | 2026-2036
Styrene Acrylonitrile (SAN) Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Styrene Acrylonitrile (SAN) Resins Market Analytics
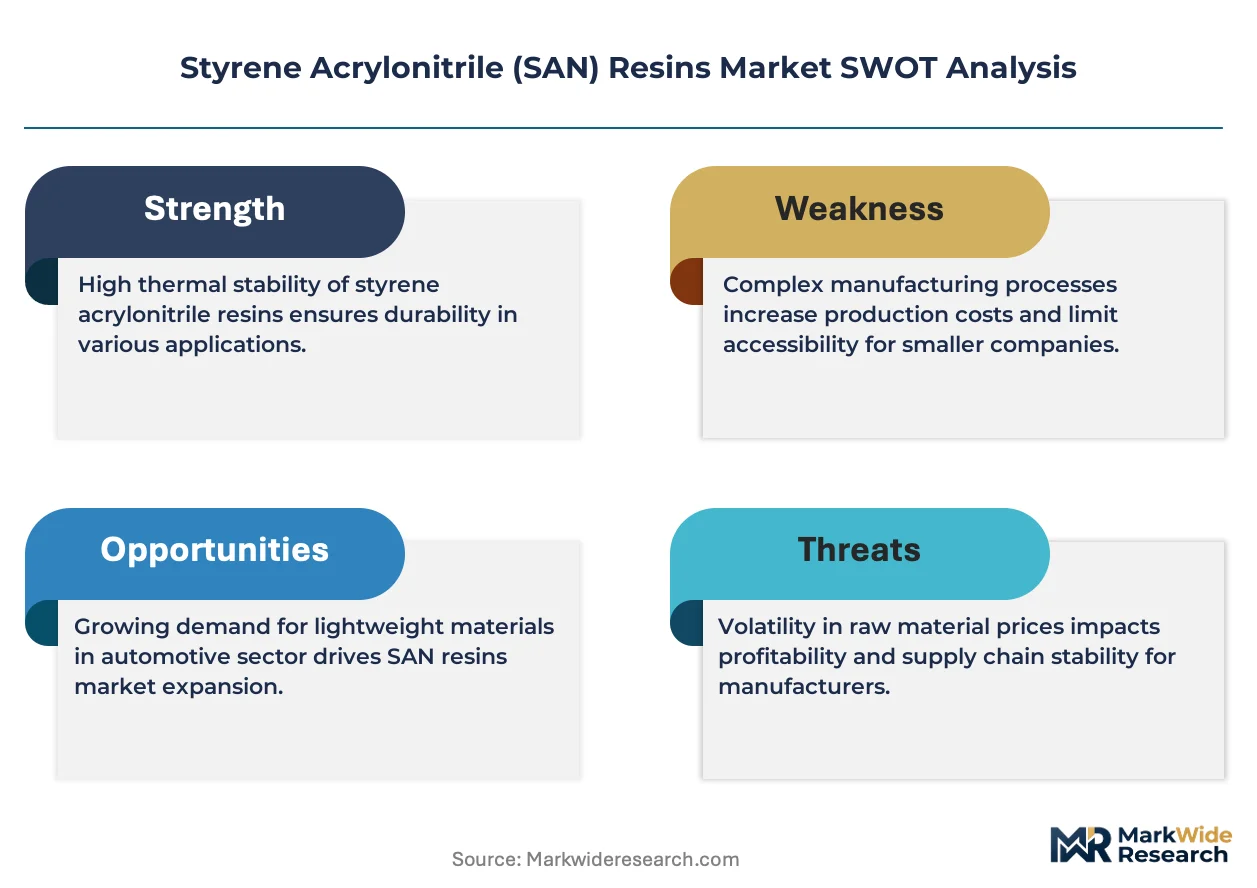
REACH compliance is consolidating the cost-of-entry calculus for European SAN resin compounders, forcing smaller blenders toward certified feedstock sourcing or exit. INEOS Styrolution leverages its backward integration into styrene monomer to sustain margin stability across European appliance supply chains. LG Chem anchors its position through dedicated SAN lines serving Korean electronics OEMs with color-matched, high-gloss grades.
Styrene acrylonitrile resin is a transparent thermoplastic copolymer containing 20-30% acrylonitrile by weight, manufactured via continuous mass polymerization or suspension processes to achieve rigidity, chemical resistance, and optical clarity for injection-molded and extruded components. Injection molded grades dominate volume flows into automotive instrument clusters and medical device housings where dimensional tolerance is critical. Extruded sheet commands premium positioning in refrigerator door liners and lighting diffusers, while blow molded applications remain a niche serving specialty packaging with limited supplier participation.
FDA food-contact regulations and EU REACH restrictions on residual acrylonitrile monomer jointly shape formulation standards and testing protocols for SAN resins entering consumer-facing applications. China's GB standards on plastic materials for household appliances create parallel compliance obligations for exporters serving Chinese OEM assembly operations. Stakeholders must monitor divergence between regional chemical registration regimes and assess whether localized compounding investments outweigh centralized export-model economics.
Market Dynamics
REACH compliance on acrylonitrile monomer emissions is consolidating European compounder economics while China's integrated production clusters reshape procurement geography for appliance and electronics molders.
Growth Catalysts
- Appliance demand in China's eastern coastal provinces:Integrated styrene-acrylonitrile production clusters serve downstream refrigerator liner and control panel manufacturing with localized feedstock supply.
- FDA food-contact regulations:Formulation standards for residual acrylonitrile monomer testing create certified supply premiums for medical device housing and consumer-facing applications.
- Mass polymerization process improvements:Continuous production methods enhance optical clarity and dimensional tolerance for injection-molded automotive instrument clusters.
Market Restraints
- Styrene monomer price volatility:Crude-linked feedstock costs compress margin stability for non-integrated compounders without captive aromatic supply.
- Acrylonitrile supply concentration:Petrochemical corridor dependencies in specific coastal manufacturing zones create geographic exposure to logistics disruptions.
- Polycarbonate substitution in lighting diffusers:Higher-heat polymers displace SAN extruded sheet in premium LED applications requiring extended thermal aging resistance.
Strategic Opportunities
- Medical device housing certification:FDA and EU MDR parallel compliance pathways reward compounders with validated residual monomer testing protocols.
- Color-matched high-gloss grades for Korean electronics OEMs:Dedicated production lines serving display bezel and control panel applications command formulation premiums.
- EU Green Deal chemical sustainability requirements:Mass balance-certified feedstock sourcing creates differentiated positioning for REACH-registered compounders.
Industry Challenges
- Residual monomer analytical capability gaps:Gas chromatography testing infrastructure requirements strain mid-scale blending operations seeking medical-grade certification.
- Legacy suspension process retrofit costs:Continuous mass polymerization technology migration demands capital deployment that smaller European compounders cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrene Acrylonitrile (SAN) Resins Market |
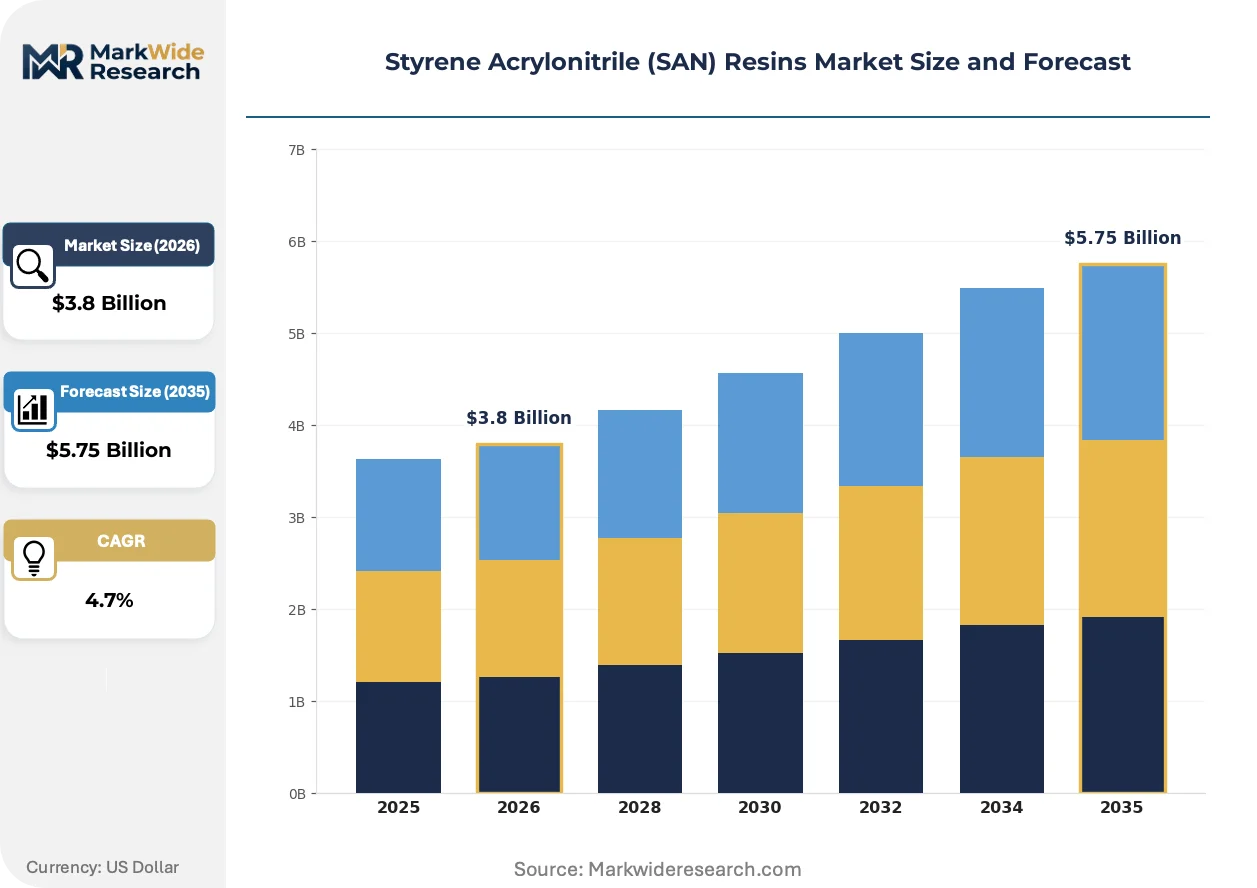
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded, Injection Molded, Blow Molded, Filament Wound Application: Automotive Components, Appliances, Electronic Housings, Medical Devices End User: Manufacturers, Distributors, Suppliers, OEMs Distribution Channel: Online, Direct Sales, Wholesale, Retail |
| Companies Covered | LG Chem, Trinseo, INEOS Styrolution, Formosa Chemicals & Fibre Corporation, Asahi Kasei Corporation, SABIC, BASF SE, Samsung Cheil Industries, Chi Mei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrene Acrylonitrile (SAN) Resins Market Evolving Landscape
Formulation science and regulatory chemistry are reshaping competitive positioning in SAN resins, with sustainability certification and process technology convergence defining supplier differentiation.
Mass polymerization technology is consolidating market structure around continuous production systems that deliver superior optical clarity and batch consistency. Korean electronics OEMs and German automotive tier-1 molders are specifying these grades for high-visibility instrument clusters and display housings. The technology is consolidating supplier tiers by rewarding capital-intensive operations with validated process control while marginalizing smaller suspension-based compounders.
EU REACH restrictions on acrylonitrile monomer emissions are tightening testing protocols and documentation requirements for compounders serving consumer-facing applications. Industrial consequence includes mandatory gas chromatography residual testing and supply chain audit trails for medical device and food-contact grades. European appliance manufacturers are responding by consolidating qualified supplier lists toward backward-integrated producers with in-house analytical capabilities.
Specification-driven procurement is compressing qualified vendor lists as OEMs consolidate resin sourcing around certified compounders with validated regulatory dossiers. Long-tail distributors and independent trading houses are losing share to direct mill relationships with documented REACH and FDA compliance. This consolidation is most visible in German automotive supply chains and Korean electronics molding operations where traceability requirements exceed generic commercial resin capabilities.
Styrene Acrylonitrile (SAN) Resins Market Segmentation
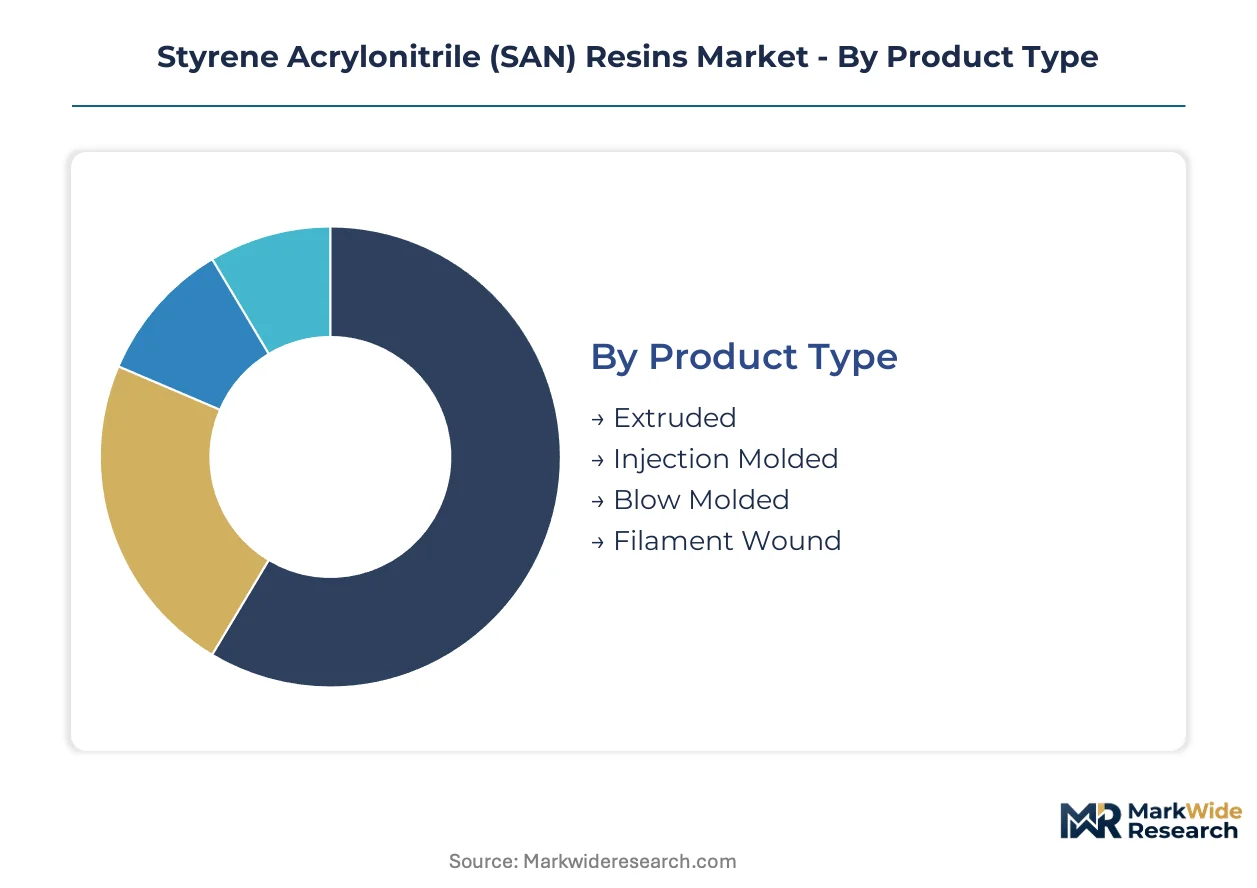
Segmentation in SAN resins reveals how production technology, regulatory compliance, and supply chain configuration concentrate value capture among specialized compounders. Distinct performance requirements across molding processes and end-use certifications fragment procurement patterns.
Product Type:
Supply concentration in continuous mass polymerization capacity favors producers of optical-grade resins with validated batch consistency for premium applications.
- Injection Molded:These grades deliver superior dimensional tolerance and surface finish for automotive instrument clusters and medical device housings. Demand concentrates with German automotive tier-1 molders and Korean electronics OEMs specifying color-matched, high-gloss formulations for display bezels.
- Extruded:Sheet and profile grades serve refrigerator door liners and lighting diffusers where chemical resistance and optical clarity are critical. Chinese appliance manufacturers in eastern coastal provinces anchor procurement volumes through integrated styrene-acrylonitrile production clusters.
- Blow Molded:Specialty packaging applications with limited supplier participation due to narrow specification windows and small batch requirements.
- Filament Wound:Niche structural composites requiring customized acrylonitrile content for enhanced chemical resistance.
Injection molded grades absorb the bulk of installed capacity; extruded grades are expanding most quickly.
Application:
Regulatory chemistry divides the market between FDA food-contact certified supply and industrial grades with lower compliance burdens.
- Appliances:Refrigerator liners and control panels dominate volume flows, with Chinese OEMs driving procurement through localized feedstock supply chains in Jiangsu and Zhejiang provinces.
- Automotive Components:Instrument clusters and interior trim require heat-resistant formulations with low residual monomer content. ECHA REACH compliance documentation and gas chromatography testing protocols filter qualified suppliers.
- Electronic Housings:Display bezels and control panels demand color stability and high-gloss surfaces. Korean electronics OEMs specify dedicated production lines with validated process control.
- Medical Devices:FDA and EU MDR parallel compliance pathways reward compounders with residual acrylonitrile testing infrastructure. Premium pricing reflects analytical capability investment and audit trail documentation.
Appliances absorb the bulk of installed capacity; medical devices are climbing the fastest.
End User:
Procurement authority is consolidating toward OEMs with direct mill relationships, marginalizing independent distributors lacking certified regulatory dossiers.
- OEMs:Appliance and automotive manufacturers specify certified grades with documented REACH and FDA compliance, consolidating qualified supplier lists toward backward-integrated producers.
- Manufacturers:Compounders with captive styrene supply and in-house analytical capabilities capture margin stability across European appliance supply chains.
- Distributors:Long-tail trading houses lose share as traceability requirements exceed generic commercial resin capabilities.
- Suppliers:Feedstock and additive providers serving formulation customization for niche applications.
OEMs absorb the bulk of procurement volume; manufacturers are gaining share fastest.
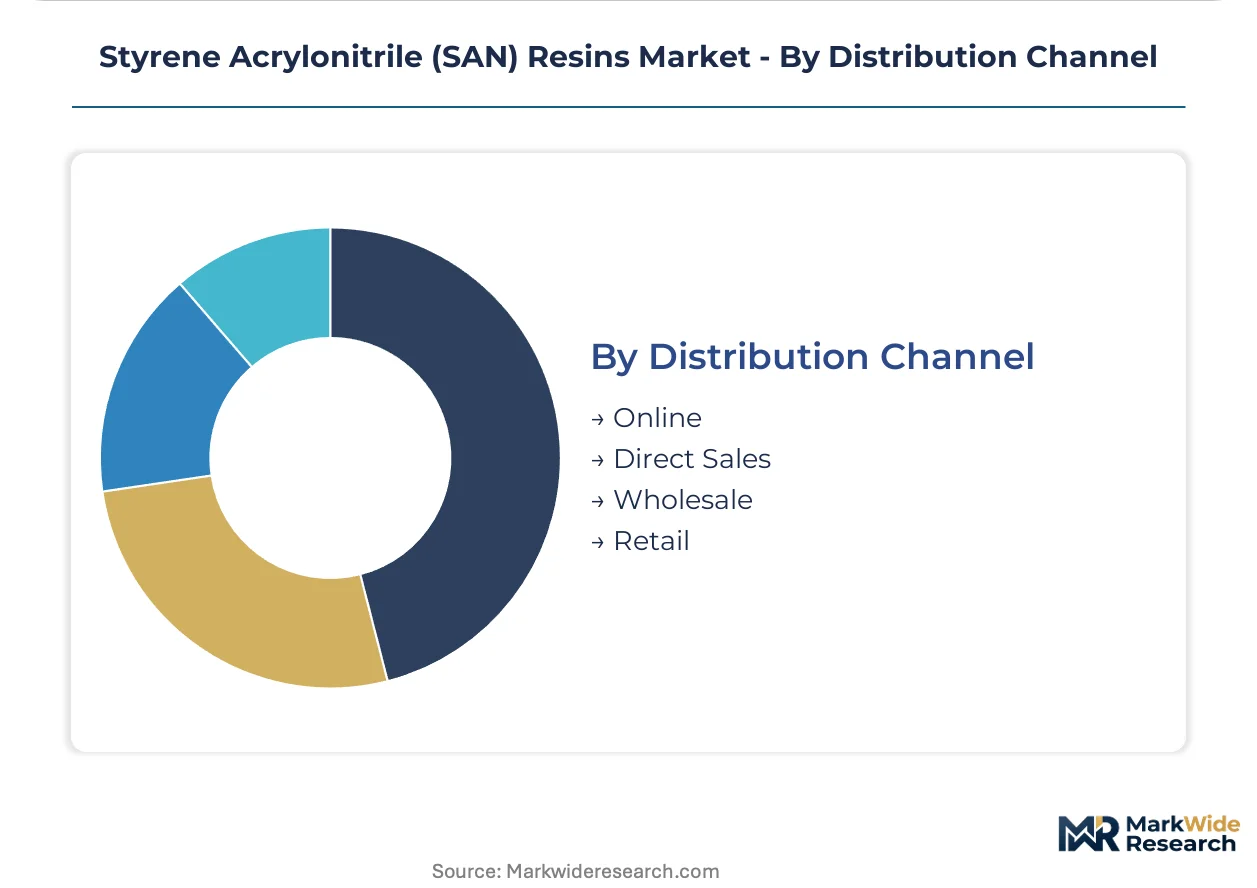
Distribution Channel:
Channel economics reflect the divergence between specification-driven direct procurement and residual spot-market activity for generic grades.
- Direct Sales:Mill-direct relationships dominate certified grade procurement for automotive and medical applications requiring batch documentation and supply chain audit trails.
- Wholesale:Regional distributors serve mid-scale injection molders with standardized grades for appliance components and consumer goods.
- Online:Digital platforms facilitate spot purchasing for small-batch specialty formulations and technical service access.
- Retail:Minimal presence limited to hobbyist and prototyping markets with negligible commercial volume.
Direct sales absorb the bulk of certified-grade volume; wholesale channels are stabilizing as distributor tiers consolidate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate integrated styrene-acrylonitrile production clusters serving appliance and electronics molders with localized feedstock supply chains. German automotive tier-1 suppliers anchor European demand through REACH-compliant certified grades. Korean electronics OEMs drive premium-grade procurement through dedicated production lines.
China
Jiangsu and Zhejiang provinces host integrated styrene-acrylonitrile production clusters supplying refrigerator liner and control panel manufacturers. GB standards on plastic materials for household appliances create compliance obligations for domestic OEM assembly operations. Ningbo and Shanghai chemical parks concentrate mass polymerization capacity serving downstream electronics molding in the Yangtze River Delta.
Germany
Automotive instrument cluster manufacturers specify low-residual-monomer grades requiring ECHA REACH documentation and gas chromatography testing protocols. The EU Green Deal chemical sustainability requirements push compounders toward mass balance-certified feedstock sourcing. North Rhine-Westphalia's petrochemical corridor anchors backward-integrated production serving European appliance supply chains.
South Korea
Electronics OEMs demand color-matched, high-gloss SAN grades for display bezels and control panels with validated process control. MFDS medical device regulations parallel FDA pathways for compounders seeking healthcare certification. The Ulsan petrochemical complex concentrates dedicated SAN production lines serving Samsung and LG supply chains.
United States
FDA food-contact regulations shape formulation standards for residual acrylonitrile monomer in medical device housings and consumer applications. EPA oversight of styrene monomer emissions affects compounder operations in Gulf Coast petrochemical corridors. Texas and Louisiana chemical manufacturing zones supply injection-molded grades to automotive tier-1 molders in the Midwest.
Japan
METI industrial standards drive specification requirements for optical-grade resins in automotive and electronics applications. JIS certification protocols filter qualified suppliers for high-visibility instrument cluster components. The Chubu region around Nagoya concentrates precision molding operations serving Toyota and Honda supply chains.
Styrene Acrylonitrile (SAN) Resins Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions in SAN resins. The market structure concentrates around backward-integrated petrochemical majors with captive styrene supply and in-house analytical capabilities. Three archetypes dominate: integrated petrochemical giants with monomer production, specialized compounders with certified regulatory dossiers, and regional blenders serving spot-market generic grades. Competitive moves center on capacity expansion in Asian production clusters and technology licensing for continuous mass polymerization systems.
Among Asian chemical conglomerates, LG Chem and Chi Mei Corporation exemplify the integrated archetype with dedicated production lines serving electronics OEMs. INEOS Styrolution anchors the European tier through its backward integration into styrene monomer. These three companies occupy positions that reflect the geographic divergence between Asian volume production and European regulatory compliance specialization.
| Leading Market Players |
|---|
| LG Chem |
| Trinseo |
| INEOS Styrolution |
| Formosa Chemicals & Fibre Corporation |
| Asahi Kasei Corporation |
| SABIC |
| BASF SE |
| Samsung Cheil Industries |
| Chi Mei Corporation |
| Others |
Value Network & Pricing Analysis
EU REACH restrictions on acrylonitrile monomer emissions gate qualified supply access and premium-tier pricing power for SAN resin compounders serving medical device and food-contact applications. REACH compliance documentation and gas chromatography testing infrastructure create tiered entry barriers that concentrate margin capture among backward-integrated producers with in-house analytical capabilities.
Pricing Analysis
Short lead-time premiums for certified medical-grade SAN resins command substantial markups over spot-market generic grades held by distributors. Contract-based long-term offtake agreements dominate procurement between appliance OEMs and integrated compounders, while price differentiation hinges on FDA certification tier and volume scale. Pricing pressure stems from styrene monomer cost volatility linked to crude oil fluctuations, compressing margins for non-integrated blenders. Mid-scale injection molders serving consumer goods exhibit highest price sensitivity; Korean electronics OEMs and German automotive tier-1 suppliers demonstrate lowest sensitivity due to specification-locked supply relationships.
Supply Chain Analysis
Styrene monomer supply rests on petrochemical corridor concentration in China, South Korea, and Germany, with integrated production clusters in each country feeding downstream SAN compounding operations. Acrylonitrile, styrene, and specialty additives constitute the critical input trio, with acrylonitrile sourcing particularly concentrated in coastal manufacturing zones. Single-source vulnerability around mass polymerization technology licensing creates supply chain risk for European compounders seeking process upgrades. Distribution runs through direct mill relationships for certified grades, while wholesale channels handle standardized appliance-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAN resin production is transitioning from legacy suspension processes to continuous mass polymerization systems that deliver superior optical clarity and batch consistency. This technology migration is consolidating supplier tiers and marginalizing smaller compounders unable to absorb capital deployment requirements.
For Market Incumbents: Extend analytical capability investments to capture medical device housing certification premiums under FDA and EU MDR parallel pathways. Polycarbonate substitution in LED lighting diffusers threatens extruded sheet demand; defend against this by deepening backward integration into styrene monomer to sustain margin stability across European appliance supply chains. Capacity expansion in China's eastern coastal provinces anchors volume growth.
For New Entrants and Emerging Players: Digital platform channels offer lower-friction access to small-batch specialty formulations for prototyping and niche packaging applications. Target blow molded specialty packaging as the most penetrable segment given limited incumbent participation and narrow specification windows. Technical service bundling with online spot purchasing creates differentiated positioning against legacy distributor relationships.
For Investors and Strategic Acquirers: REACH registration completion for acrylonitrile monomer handling is the leading indicator that European compounders have crossed the compliance threshold for sustained premium-tier access. The five-to-ten-year viability window favors acquisition of mid-scale compounders with validated gas chromatography infrastructure and documented supply chain audit trails. Watch for suspension-to-mass polymerization retrofit announcements as inflection signals for technology-transition completion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | Captive aromatic supply insulates margin stability from crude-linked feedstock volatility for European compounders. |
| Mass Polymerization Technology Licensing | Continuous production systems from Korean and German equipment suppliers consolidate optical-grade resin capability. |
| FDA and EU MDR Certification Investment | Residual acrylonitrile testing protocols unlock premium pricing in medical device housing applications. |
| Long-term Supply Agreement with Appliance OEMs | Direct mill relationships with Chinese refrigerator manufacturers secure volume commitments in Jiangsu and Zhejiang provinces. |
| Joint Venture in Yangtze River Delta Chemical Parks | Localized production clusters reduce logistics exposure and serve downstream electronics molding operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this SAN resin market assessment. Primary interviews with plant managers at compounding facilities, procurement leads at Korean electronics OEMs, distribution channel partners serving European appliance manufacturers, and technical R&D directors validated demand patterns and process technology trends. SEC 10-K filings from petrochemical majors, Cefic chemical industry reports, and customs import-export databases provided supply-side calibration. Bottom-up capacity modeling and top-down demand segmentation were triangulated against trade flow data.
Data-stream reconciliation across production capacity databases, end-use consumption surveys, and price benchmarking sources shaped the analytical framework. Segmentation dimensions modeled include product type grade tier, end-use application, regional production hub, and regulatory certification level. CAGRs were derived from trend extrapolation of historical trade flows and capacity utilization rates. Styrene monomer price trajectories and appliance production forecasts from Chinese manufacturing clusters served as industry-specific demand inputs across the projection horizon.
The model holds under stable REACH enforcement intensity and continued mass polymerization technology diffusion; deviation in acrylonitrile supply disruptions or polycarbonate substitution acceleration would shift volume and value outputs. Forecasts reflect documented assumptions about regulatory compliance timelines and process technology migration rates. A small set of named triggers—ECHA enforcement actions, suspension plant closure announcements, and LED thermal management specification changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Polyglycerates Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Vinyl Acetate Homopolymer Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Global Fluoropolymer Market