
 Middle East LLDPE Market | 2026-2036
Middle East LLDPE Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East LLDPE Market Foresight
Project finance tied to integrated refinery-petrochemical complexes is rewriting competitive entry requirements across the Middle East LLDPE landscape. SABIC leverages its feedstock advantage at Jubail Industrial City to sustain cost leadership in blown film grades. Dow anchors its regional position through technology licensing and catalyst supply agreements with local producers.
Linear low-density polyethylene is an ethylene-alpha-olefin copolymer produced via gas-phase or solution polymerization, with density ranging from 0.915 to 0.925 g/cm³ and characterized by short-chain branching that imparts superior puncture resistance and tensile strength for stretch films and heavy-duty sacks. Blown film dominates volume consumption across the Middle East due to regional packaging sector expansion and import substitution in flexible food wraps. Agricultural films represents the fastest-growing application segment as Saudi Arabia and the UAE expand protected cultivation under water-scarcity adaptation programs.
Saudi Arabia's SFDA mandates food-contact compliance testing for LLDPE packaging resins, while the UAE's MOHAP enforces parallel safety standards that shape import specifications and local formulation requirements. Borealis and EQUATE navigate these dual regulatory frameworks by maintaining separate certification streams for Gulf and non-Gulf product lines. Stakeholders must monitor catalyst technology licensing costs and feedstock slate flexibility as naphtha-ethane arbitrage shifts regional production economics.
Market Dynamics
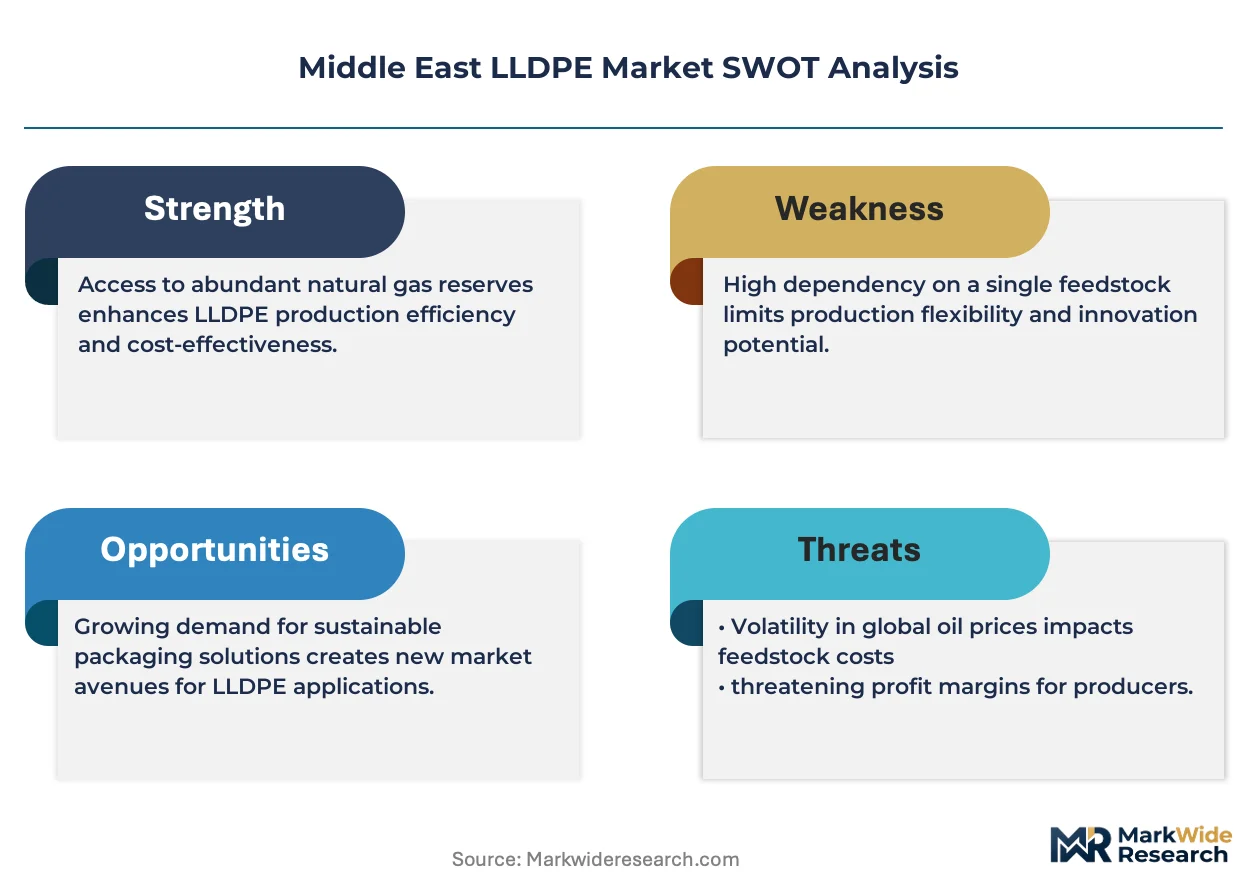
Metallocene catalyst technology is compressing resin specification cycles across Middle East LLDPE production, forcing converters to retool extrusion lines for higher clarity grades demanded by Saudi Arabia's food-contact packaging sector.
Growth Catalysts
- SFDA food-contact mandates:Saudi Arabia's food safety authority mandates compliance testing for packaging resins, redirecting formulation requirements toward certified grades and expanding domestic testing laboratory capacity.
- Protected cultivation expansion:Agricultural films consumption is accelerating across Saudi Arabia and the UAE as water-scarcity adaptation programs drive greenhouse infrastructure buildout.
- Jubail Industrial City integration:Feedstock-advantaged crackers at this Eastern Province cluster supply captive LLDPE extrusion lines, compressing delivered resin costs for regional converters.
Market Restraints
- Ethane-naphtha feedstock volatility:Regional production economics hinge on ethane availability from associated gas, exposing margins to crude-linked naphtha arbitrage shifts when ethane supply tightens.
- Dual certification burden:Borealis and EQUATE maintain separate Gulf and non-Gulf product streams to satisfy divergent SFDA and MOHAP standards, fragmenting batch runs and elevating inventory carrying costs.
- Conventional Ziegler-Natta displacement:Metallocene-catalyzed resins with superior puncture resistance are eroding demand for legacy blown film grades in premium food-wrap applications.
Strategic Opportunities
- UAE flexible packaging import substitution:Local extrusion capacity expansion in Dubai Industrial City targets food-service and retail wrap segments currently served by European resin imports.
- Metallocene-mLLDPE technology licensing:Dow's catalyst supply agreements with regional producers create pathways for technology transfer and localized specialty grade production.
- Reverse logistics film recovery:Stretch film collection and mechanical recycling infrastructure is emerging around Jeddah's logistics corridor, opening circular feedstock channels for post-consumer resin formulations.
Industry Challenges
- Metallocene process engineering expertise:Regional converters face skill gaps in gas-phase reactor optimization and comonomer distribution control for narrow molecular weight distribution resins.
- SFDA certification timeline compression:Migration testing and food-contact safety documentation cycles average 14-18 months, delaying new grade commercialization for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East LLDPE Market |
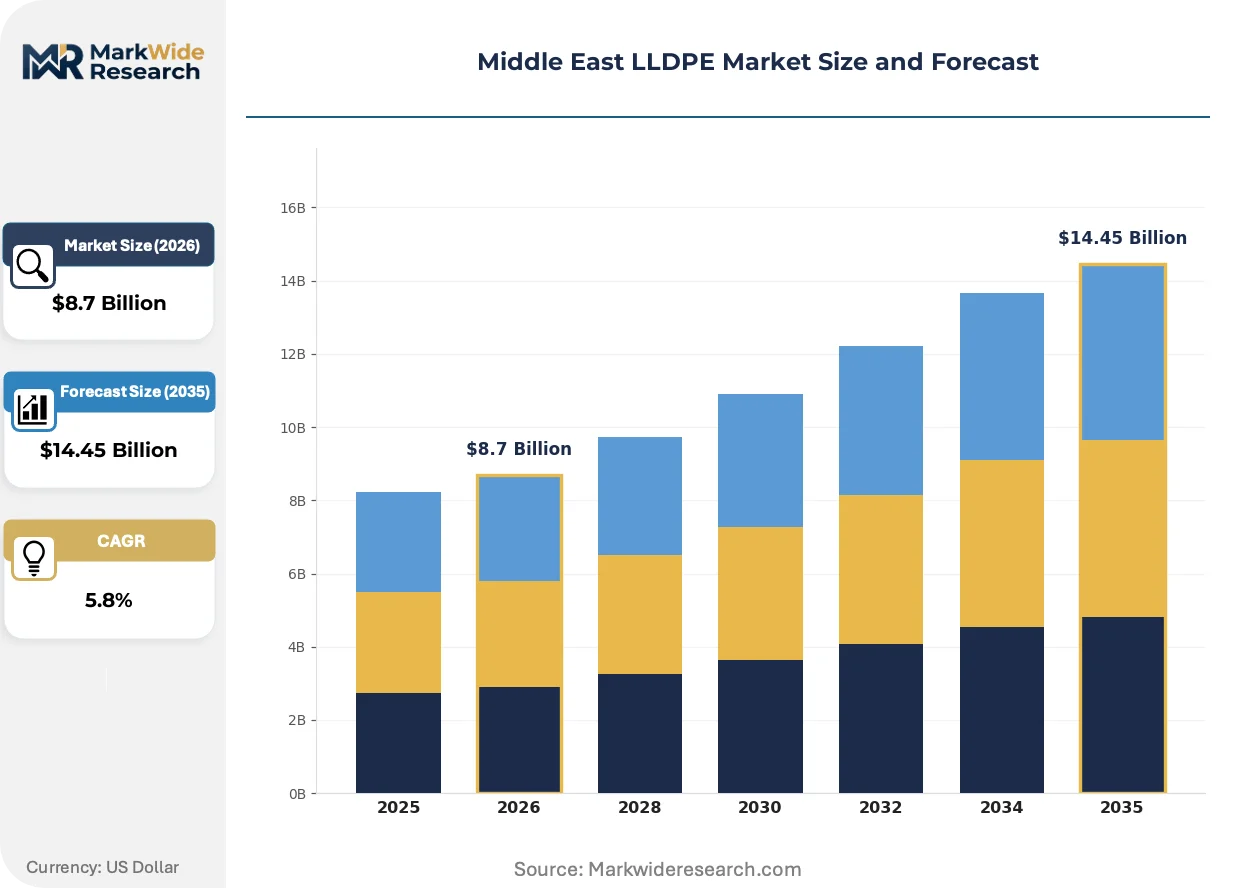
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Blown Film, Extrusion Coating, Compression Molding End User: Packaging, Automotive, Consumer Goods, Agriculture Application: Flexible Packaging, Rigid Containers, Agricultural Films, Coatings Form: Granules, Pellets, Films, Sheets |
| Companies Covered | Dow, Petro Rabigh, SABIC, National Iranian Oil Company, EQUATE, Saudi Polymers LLC, Saudi Aramco, Borealis, ExxonMobil, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East LLDPE Market Shifts & Advancements
Polymerization technology advances and regulatory harmonization pressures are restructuring how Middle East LLDPE producers specify, certify, and deliver resin grades to converters serving food-contact and agricultural end-uses.
Single-site metallocene catalyst systems enable precise control over short-chain branching distribution, producing LLDPE with enhanced optical clarity and heat-seal performance. Food and beverage distributors across Gulf Cooperation Council states are adopting these grades for high-definition printed flexible packaging. Conventional Ziegler-Natta catalyzed resins with inferior clarity and broader molecular weight distribution are rendering obsolete for premium blown film applications.
MOHAP's alignment with Gulf Standardization Organization food-contact safety protocols is compressing regulatory fragmentation across UAE and Saudi Arabia. Producers now face streamlined but stricter migration testing requirements for heavy metals and residual catalyst residues. Flexible packaging converters in Dubai and Sharjah free zones are consolidating supplier bases to reduce dual-certification overhead.
Direct resin procurement from integrated petrochemical complexes is displacing distributor-mediated purchasing among large-scale film extruders. Major converters in Saudi Arabia's Eastern Province now contract directly with Jubail-based producers for scheduled offtake agreements. This channel consolidation is most visible in the heavy-duty sack segment, where volume buyers negotiate formula pricing tied to ethane feedstock indices rather than spot resin quotations.
Middle East LLDPE Market Segmentation
LLDPE specification cycles in the Middle East compress around catalyst technology advances and regulatory compliance tiers. Segmentation reveals how resin grades diverge across food-contact mandates, agricultural adaptation programs, and converter capability thresholds.
Product Type:
Application requirements and processing economics determine which polymerization output commands converter preference and margin capture.
- Blown Film:Gas-phase resins with density 0.915–0.925 g/cm³ dominate stretch wrap and heavy-duty sack production across Saudi Arabia's Eastern Province. Food-contact certification under SFDA mandates is redirecting volume toward metallocene-catalyzed clarity grades for retail packaging.
- Injection Molding:Narrow molecular weight distribution resins enable thin-wall container production with cycle time advantages. Demand concentrates in the UAE's Dubai Industrial City for food-service disposables requiring MOHAP compliance documentation.
- Extrusion Coating:LDPE/LLDPE coextrusion structures serve liquid packaging board lamination for regional dairy and juice processors.
- Compression Molding:Specialty grades for large-part industrial applications remain limited by regional converter equipment bases.
Blown Film holds installed capacity. Injection Molding is rotating up the share rankings.
End User:
Customer industry exposure shapes resin specification cycles and certification burden intensity across the value chain.
- Packaging:Flexible food wraps, stretch films, and heavy-duty sacks absorb the majority of regional LLDPE offtake. SFDA migration testing requirements for food-contact resins are extending commercialization timelines for new grade introductions.
- Agriculture:Greenhouse and mulch film demand is climbing fastest as Saudi Arabia and the UAE expand protected cultivation under water-scarcity programs. UV-stabilized metallocene grades command premium positioning over conventional Ziegler-Natta alternatives.
- Automotive:Interior trim and underhood applications require heat-resistant compounded formulations with limited regional compounding infrastructure.
- Consumer Goods:Housewares and toy applications face fragmented demand across Gulf Cooperation Council import substitution initiatives.
Packaging anchors volume commitments. Agriculture is gaining share fastest on policy tailwinds.
Application:
Functional performance requirements segment the market between commodity blown film and specialty barrier structures.
- Flexible Packaging:Multilayer coextrusion films for snack, frozen food, and retail meat packaging require puncture resistance and heat-seal strength. Metallocene catalyst technology is displacing conventional grades in high-clarity premium segments.
- Agricultural Films:Greenhouse covers, mulch films, and silage wraps demand UV stabilization and mechanical durability for extended field exposure. Saudi Arabia's National Transformation Program is accelerating infrastructure buildout.
- Rigid Containers:Injection-molded pails and crates serve industrial and logistics applications with lower specification intensity than food-contact films.
- Coatings:Extrusion-coated paper and board laminations target liquid packaging for regional dairy processors.
Flexible Packaging maintains capacity dominance. Agricultural Films is climbing the fastest on climate adaptation spending.
Form:
Physical delivery format determines logistics economics and converter processing flexibility.
- Pellets:Standard extrusion-grade cylindrical pellets feed blown film and injection molding lines across Jubail-based converter clusters. Direct procurement from integrated producers is displacing distributor channels for volume buyers.
- Granules:Irregular particle forms serve compounding and masterbatch operations with lower homogeneity requirements.
- Films:Pre-extruded roll stock targets small-scale converters lacking blown film capability in Sharjah and Jeddah free zones.
- Sheets:Thermoforming feedstock for rigid packaging applications remains import-dependent with limited regional extrusion capacity.
Pellets command logistics infrastructure. Films is rotating up on converter fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export capacity from integrated petrochemical complexes across the Middle East exceeds regional consumption, positioning the Gulf as a net resin supplier to Asian and African markets while domestic demand concentrates in packaging and agricultural film applications.
Saudi Arabia
Blown film extruders in the Eastern Province absorb the majority of domestic LLDPE offtake for food-contact packaging applications. SFDA mandates on migration testing and heavy metal limits redirect formulation requirements toward certified clarity grades. Jubail Industrial City hosts captive resin production feeding downstream converter clusters with ethane-advantaged feedstock economics.
United Arab Emirates
Flexible packaging converters in Dubai and Sharjah free zones drive demand for high-clarity metallocene grades serving retail food wrap segments. MOHAP alignment with Gulf Standardization Organization protocols streamlines compliance documentation across emirates. Dubai Industrial City extrusion capacity expansion targets import substitution in food-service disposables currently sourced from European resin suppliers.
Iran
Domestic polymer consumption focuses on agricultural films and irrigation piping for water-scarcity adaptation programs. Sanctions-related logistics constraints redirect export volumes toward neighboring markets through informal trade channels. Petrochemical complexes in the Assaluyeh special economic zone maintain olefin production capacity despite infrastructure maintenance challenges.
Kuwait
Polyethylene production from Shuaiba and Ahmadi refining complexes serves regional flexible packaging demand with limited domestic conversion infrastructure. EQUATE operations link Kuwaiti olefin supply to downstream extrusion partners across the Gulf. Local consumption concentrates in heavy-duty sacks and construction films with lower certification intensity than food-contact grades.
Qatar
Ras Laffan Industrial City crackers supply ethane-based polyethylene feedstock to regional converter networks through long-term offtake arrangements. Domestic demand remains constrained by limited downstream film extrusion capacity. Qatari resin volumes predominantly export to Indian and Pakistani packaging markets via dedicated shipping terminals.
Middle East LLDPE Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with catalyst and process technology supply. Market structure consolidates around state-affiliated petrochemical holdings with integrated refinery-olefin-polymer assets. Three archetypes dominate: feedstock-integrated national champions, technology licensors with catalyst supply agreements, and regional joint ventures bridging capital and know-how. Competitive moves center on metallocene grade commercialization and direct procurement channel development with volume converters.
Among technology licensors, Dow anchors catalyst supply relationships across regional gas-phase reactor operations. SABIC exemplifies the feedstock-integrated archetype through its Jubail-based ethane crackers and downstream extrusion feed. Borealis occupies a position bridging European technical standards with Gulf production economics through its partnership structures. These three entities represent distinct competitive vectors: proprietary catalysis, captive feedstock advantage, and regulatory harmonization expertise.
| Leading Market Players |
|---|
| Dow |
| Petro Rabigh |
| SABIC |
| National Iranian Oil Company |
| EQUATE |
| Saudi Polymers LLC |
| Saudi Aramco |
| Borealis |
| ExxonMobil |
| Others |
Supply & Pricing Matrix
Jubail Industrial City's ethane-advantaged crackers compress delivered resin costs for Eastern Province converters, translating feedstock dominance into pricing power over spot-indexed imports. Direct procurement channels from integrated producers now displace distributor-mediated purchasing for volume buyers negotiating formula pricing tied to ethane indices.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the Middle East LLDPE landscape. Price differentiation separates SFDA-certified food-contact grades from uncertified commodity resins, with clarity premiums widening as metallocene adoption accelerates. Cost compression in conventional Ziegler-Natta tiers is intensifying because converters retool for higher-specification film grades. Small-scale free-zone extruders in Sharjah and Jeddah exhibit highest price sensitivity, while integrated packaging groups in Saudi Arabia's Eastern Province leverage volume scale for formula-indexed supply security.
Supply Chain Analysis
Ethane feedstock from associated gas production in Saudi Arabia, Qatar, and Kuwait anchors regional LLDPE economics against naphtha-linked import competition. Raw material dependencies center on alpha-olefin comonomer supply, metallocene catalyst licensing, and UV stabilizer masterbatches for agricultural film grades. Single-source vulnerability concentrates in catalyst technology licensing from Dow and specialized additive suppliers. Distribution runs through direct mill-to-converter arrangements for volume buyers, with distributor channels serving fragmented free-zone processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East LLDPE market sits in early-cycle expansion as protected cultivation programs across Saudi Arabia and the UAE drive agricultural film penetration ahead of regional packaging saturation.
For Market Incumbents: Insulate feedstock-advantaged positions at Jubail and Ras Laffan through captive supply agreements with downstream extrusion clusters. Deepen backward integration into metallocene catalyst formulation to reduce licensing exposure. Prioritize SFDA certification investment ahead of MOHAP harmonization to capture first-mover clarity premiums. For New Entrants and Emerging Players: Iran's domestic agricultural film demand under sanctions-constrained supply offers white-space access through informal trade corridor development. Target UAE food-service disposables in Dubai Industrial City where import substitution lags European resin dependency. Lead with toll-manufacturing partnerships at underutilized Kuwaiti compounding assets to bypass greenfield cracker economics. For Investors and Strategic Acquirers: Long-term, this sits as a feedstock-capture play because ethane availability from associated gas production underwrites cost structures unavailable to naphtha-dependent Asian competitors. Acquisition targets should emphasize converters with established SFDA certification pipelines and direct procurement relationships with Jubail-based producers. Monitor metallocene grade commercialization timelines as inflection signals for premium tier margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Production | Captive comonomer supply reduces catalyst formulation cost exposure for metallocene grade expansion. |
| Metallocene Technology Licensing Agreement | Dow catalyst partnerships enable regional producers to displace conventional Ziegler-Natta capacity. |
| SFDA Certification Pipeline Investment | Food-contact compliance infrastructure accelerates commercialization timelines for clarity grade launches. |
| Direct Procurement Channel Development | Mill-to-converter agreements at Jubail displace distributor markups for heavy-duty sack volume buyers. |
| Agricultural Film UV Stabilization Partnership | Additive supplier alliances secure extended field performance specifications for Saudi greenhouse programs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SABIC and EQUATE operational disclosures, and Gulf petrochemical industry association reports. Conversations spanned plant managers at Eastern Province extrusion facilities, procurement leads at Dubai flexible packaging converters, distribution channel partners in Jeddah logistics corridors, and technical R&D directors overseeing metallocene catalyst trials. Bottom-up resin consumption estimates triangulate against top-down cracker output projections across the analysis window.
Forecast inputs incorporate ethane-naphtha arbitrage modeling, SFDA regulatory timeline assumptions, and protected cultivation acreage expansion trajectories. Segmentation dimensions span catalyst technology tier, end-use industry exposure, food-contact certification status, and regional production hub. CAGRs derive from installed capacity utilization trends and converter capability upgrade cycles throughout the forecast period. Agricultural film demand elasticity to water-scarcity policy intensity represents a key sensitivity input.
Practitioners should monitor ethane supply allocation shifts and metallocene catalyst licensing cost trajectories for early signals of margin compression or expansion. Forecasts reflect assumptions on regulatory harmonization pace and cracker maintenance scheduling that could revise with feedstock disruption or SFDA protocol amendments. Cross-checking against IEA Middle East energy balances and Gulf Standardization Organization migration testing disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Bio-Sourced Nylon Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Hydrocarbon Resins Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Polybutene-1 Market