
 Asia-Pacific Polyethylene Terephthalate (PET) Resin Market | 2026-2036
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market Outlook
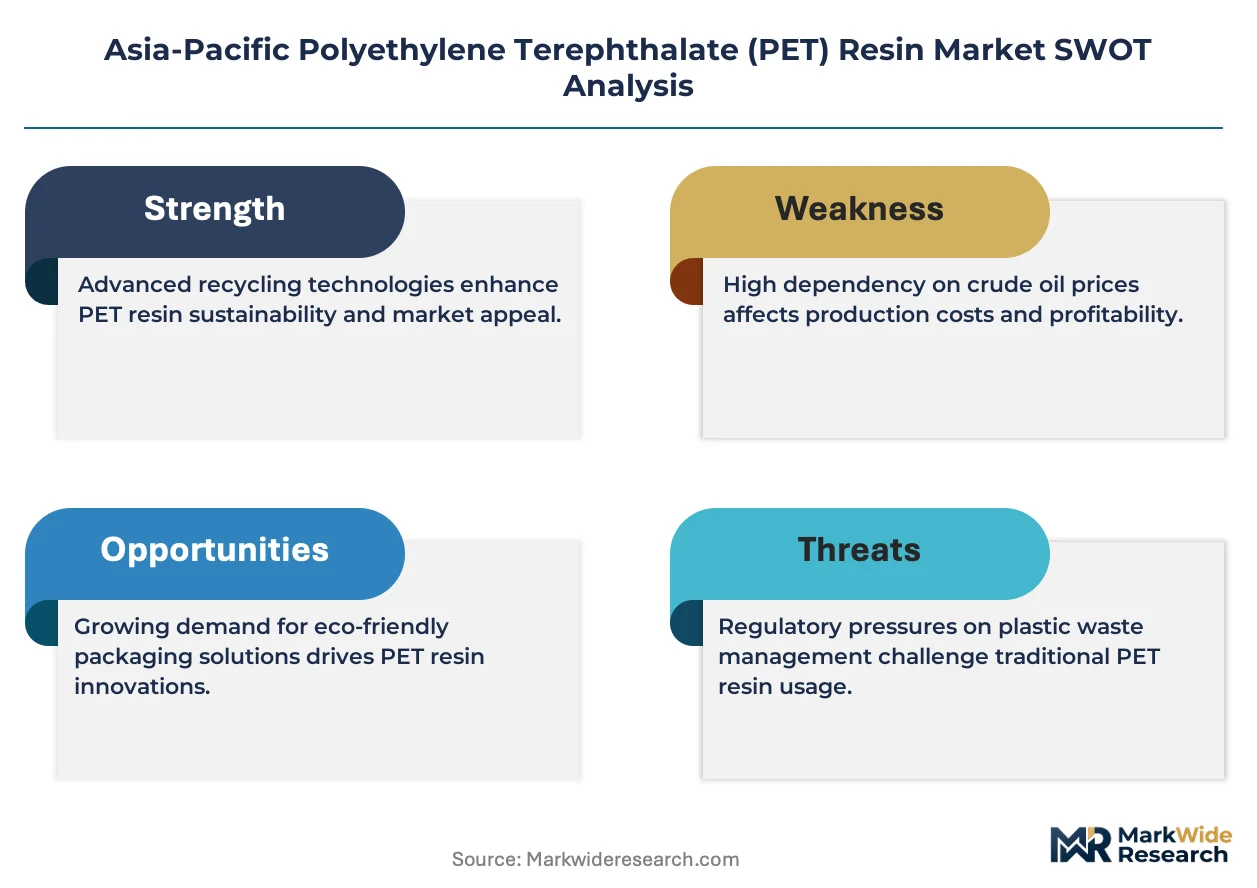
Recycled polyethylene terephthalate (rPET) is recalibrating virgin resin economics across Asia-Pacific as brand owners commit to post-consumer content targets. Indorama Ventures Public Company Limited leverages its integrated recycling footprint in Thailand to secure long-term supply contracts. Yisheng Petrochemical anchors its position through massive purified terephthalic acid (PTA) self-sufficiency at its Zhejiang complex. Lotte Chemical Corporation differentiates via specialized film-grade resin production for premium electronics applications.
Polyethylene terephthalate resin is a thermoplastic polymer synthesized through esterification of terephthalic acid with ethylene glycol, yielding a material with intrinsic viscosity typically ranging from 0.70 to 0.84 dL/g depending on end-use requirements. It serves primarily as a moldable, barrier-resistant substrate for rigid packaging and synthetic fiber systems. Bottle-grade PET commands the largest value pool given its dominance in carbonated soft drink and bottled water container manufacturing. Fiber-grade resin represents the fastest-expanding category as polyester textile demand surges in Bangladesh and Vietnam garment sectors. Sheet-grade PET occupies a narrower but higher-margin niche serving thermoformed food trays and pharmaceutical blister packs.
China's MEE enforces wastewater and emissions intensity limits that elevate compliance costs for PTA-PET integrated producers. India's BIS certification mandates and the country's phased plastic waste management rules shape product specifications and recycling infrastructure investments. Japan's METI circular economy guidelines and container deposit systems in South Korea and Australia create differentiated demand profiles for virgin versus recycled-content resin. Stakeholders must track how recycled-content mandates evolve across Southeast Asian import markets and whether rPET flake supply bottlenecks constrain brand commitments.
Market Dynamics
China's dual carbon goals and stricter MEE emissions standards are compressing virgin resin margins while forcing integrated PTA-PET producers to absorb carbon accounting costs. This regulatory pressure is accelerating capital redeployment toward recycled-content infrastructure across the Asia-Pacific region.
Growth Catalysts
- Beverage container procurement:Bottling capacity expansion in India and Vietnam is pulling resin demand upward. Brand owners are locking in multi-year supply contracts with integrated producers.
- MEE wastewater standards:China's intensified enforcement is filtering out marginal producers. Compliance investments by survivors are tightening effective supply.
- Polyester textile demand:Bangladesh and Vietnam garment sectors are consuming fiber-grade resin at accelerating rates. Regional spinning capacity is expanding to match.
Market Restraints
- PTA feedstock volatility:Paraxylene price swings transmit directly into PET resin cost structures. Integrated producers absorb margin compression during crude oil spikes.
- rPET flake supply concentration:Collection infrastructure bottlenecks in Southeast Asia constrain brand owner recycled-content commitments. Thailand and Indonesia dominate regional flake output.
- Technical viscosity limitations:Mechanical recycling degrades polymer chain length. Bottle-to-bottle applications require supplemental virgin resin blending.
Strategic Opportunities
- India's BIS certification pathways:Standardized recycled-content grades would unlock institutional procurement. Early movers in certification infrastructure capture specification-setting authority.
- Pharmaceutical blister pack migration:Sheet-grade PET is displacing PVC in healthcare packaging. Japan and South Korea medical device manufacturers are specifying higher-barrier formulations.
- Chemical recycling scale-up:Pyrolysis and glycolysis technologies promise food-contact purity without viscosity loss. Pilot investments in Singapore and Taiwan are testing commercial viability.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for recycled-content resin blending is concentrated among legacy producers. New entrants face 18-24 month capability build timelines.
- Depolymerization reactor capex:Chemical recycling facilities require $200-400 million per unit. Financing availability constrains deployment velocity.
- Multi-jurisdictional compliance:India's phased plastic waste rules, South Korea's container deposit system, and Australia's recycled-content mandates create fragmented certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polyethylene Terephthalate (PET) Resin Market |
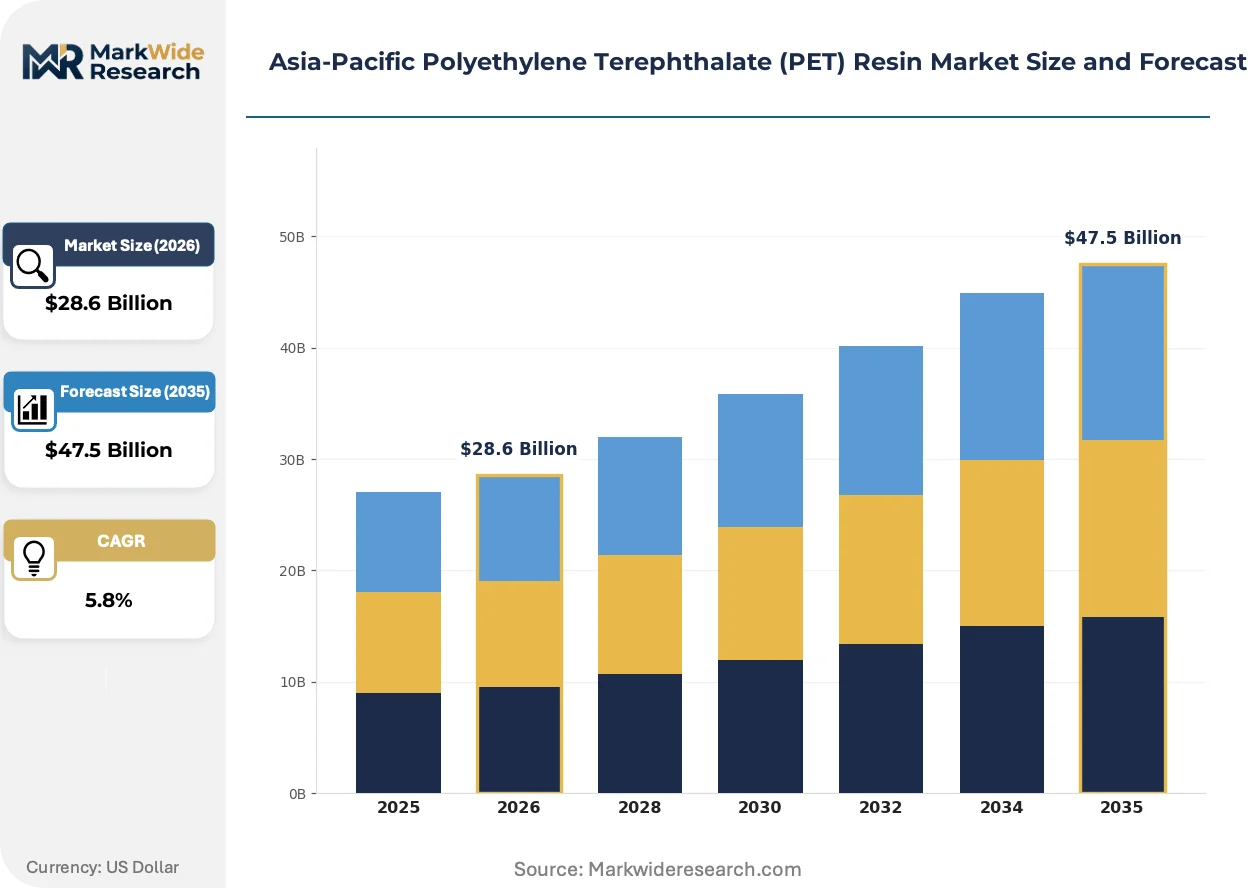
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottle Grade, Fiber Grade, Sheet Grade, Film Grade End Use Industry: Packaging, Textiles, Automotive, Electronics Distribution Channel: Direct Sales, Retail, Online, Wholesale Application: Food Packaging, Beverage Containers, Textile Production, Electrical Components |
| Companies Covered | Yisheng Petrochemical, Lotte Chemical Corporation, Indorama Ventures Public Company Limited, Jiangsu Sanfangxiang Industrial Group, Reliance Industries, China Petroleum & Chemical Corporation, Zhejiang Wankai New Materials, SK Global Chemical, Far Eastern New Century Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market Strategic Shifts
Recycled-content technologies and regulatory carbon accounting are restructuring competitive advantage in Asia-Pacific PET resin. Producers are racing to secure flake supply and de-risk compliance exposure.
Advanced mechanical recycling with solid-state polymerization is overtaking conventional reprocessing for bottle-grade applications. Japanese beverage bottlers are specifying 50% rPET content by 2025. This technology compression is eroding the quality premium historically commanded by virgin resin.
China's MEE emissions intensity limits are forcing integrated producers to install carbon capture or switch to bio-based feedstock blends. Compliance costs are elevating minimum efficient scale thresholds. Smaller Zhejiang and Jiangsu producers are exiting rather than retrofitting.
Brand owner direct contracting with recyclers is bypassing traditional resin distributor channels. Nestlé and Coca-Cola procurement teams in Bangkok and Singapore are negotiating flake supply agreements independent of resin producers. This disintermediation is most advanced in Thailand where Indorama's integrated recycling footprint enables transparent chain-of-custody documentation.
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market Segmentation
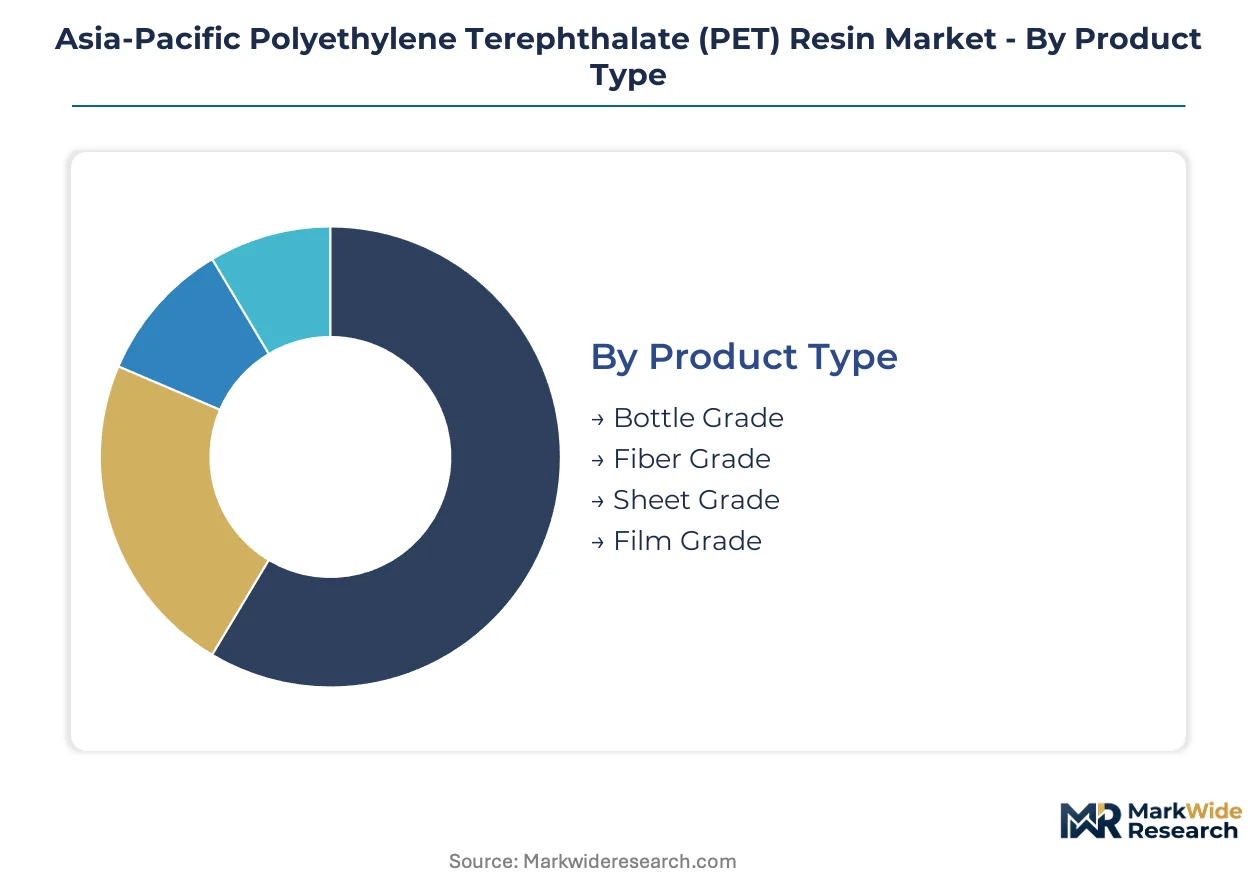
PET resin segmentation in Asia-Pacific reveals distinct margin structures across product grades and end-use applications. Procurement patterns diverge sharply between integrated beverage bottlers and dispersed textile spinners, reshaping channel economics across the region.
Product Type:
Bottle-grade resin operates as a standalone specification system with direct brand owner contracting, while fiber and film grades embed into longer manufacturing chains with less visibility to resin producers.
- Bottle Grade:Intrinsic viscosity specifications range from 0.72 to 0.82 dL/g with acetaldehyde content below 1 ppm for taste-sensitive applications. Carbonated soft drink bottlers in Thailand and Vietnam are locking in five-year supply agreements with integrated PTA-PET producers. China's MEE emissions standards are compressing margins for non-integrated resin suppliers.
- Fiber Grade:Lower viscosity ranges of 0.58 to 0.68 dL/g suit melt-spinning processes for polyester textile production. Bangladesh and Vietnam garment sectors are pulling fiber-grade volumes upward as regional spinning capacity expands to serve export demand.
- Sheet Grade:Amorphous formulations with clarified nucleating agents serve thermoformed food trays and pharmaceutical blister packs. Japanese medical device manufacturers specify higher-barrier formulations displacing PVC.
- Film Grade:Biaxially oriented variants with controlled crystallinity anchor premium electronics applications. South Korean display component suppliers source specialized film-grade resin through direct technical partnerships.
Bottle grade leads volumes today; fiber grade is gaining share fastest.
End Use Industry:
Cost tier differentiation separates high-specification packaging procurement from price-sensitive textile applications, with automotive and electronics representing emerging premium niches.
- Packaging:Rigid container manufacturing dominates value capture across carbonated beverages, bottled water, and edible oil segments. India's BIS certification mandates are reshaping procurement specifications for food-contact applications.
- Textiles:Polyester staple fiber and filament yarn production consumes the largest tonnage volumes regionally. Vietnam's garment export growth is accelerating fiber-grade resin absorption faster than domestic supply expansion.
- Automotive:Underhood electrical connectors and interior trim components utilize glass-reinforced PET compounds. Japanese automakers specify heat-stabilized grades for engine compartment applications.
- Electronics:Connector housings and LED reflectors demand flame-retardant formulations with precise dimensional stability. Taiwan semiconductor packaging suppliers are qualifying specialized resin grades.
Packaging commands the highest value per ton; textiles absorb the greatest absolute volumes.
Distribution Channel:
Channel selection correlates with customer scale and technical service requirements, fragmenting across direct mill relationships and distributor networks.
- Direct Sales:Integrated producers like Indorama Ventures and Yisheng Petrochemical contract directly with multinational beverage bottlers and textile conglomerates. Long-term offtake agreements with price adjustment clauses dominate this channel.
- Wholesale:Regional distributors aggregate smaller textile spinner orders across India's Surat and Tiruppur clusters. Working capital constraints limit distributor inventory depth during paraxylene price spikes.
- Retail:Specialty compounders and small-batch processors source through plastics trading houses in Shanghai and Singapore. This channel serves experimental formulations and short-run applications.
- Online:Digital platforms facilitate spot market transactions for standard-grade resin among small processors. Price transparency is improving but logistics coordination remains challenging for bulk deliveries.
Direct sales generates the highest margin per transaction; wholesale moves the largest aggregate tonnage.
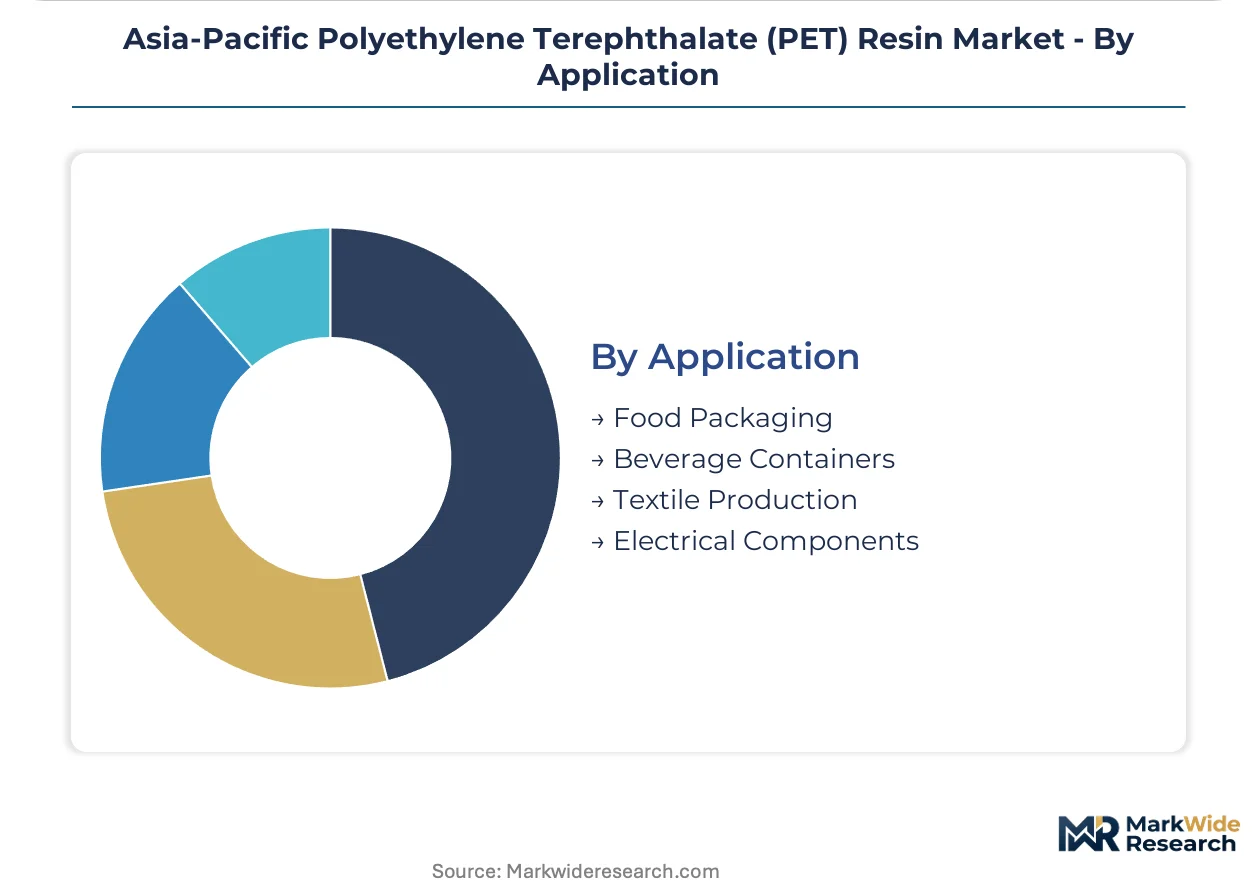
Application:
Application segmentation tracks the migration from commodity packaging toward specialized barrier and electrical performance requirements.
- Beverage Containers:Carbonated soft drink and bottled water bottles represent the most technically demanding rigid packaging application. Thailand's integrated recycling infrastructure supports brand owner rPET content commitments.
- Food Packaging:Thermoformed trays and clamshells for fresh produce and ready meals utilize amorphous PET with oxygen scavenger additives. Japan's METI circular economy guidelines shape recycled-content specifications.
- Textile Production:Polyester staple fiber for apparel and industrial yarns for tire cord represent divergent viscosity requirements. Bangladesh's garment sector expansion is outpacing regional fiber-grade supply growth.
- Electrical Components:Connector bodies and coil bobbins demand flame-retardant grades with UL94 V-0 ratings. South Korean electronics manufacturers are qualifying domestic resin sources to reduce import dependency.
Beverage containers anchor current profitability; electrical components show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors Asia-Pacific PET resin production capacity through integrated PTA-PET complexes serving both domestic bottle-grade demand and export-oriented fiber-grade consumption. Regional procurement patterns diverge sharply between China's emissions-regulated integrated producers and Southeast Asia's recycling-dependent supply chains. India's bottling infrastructure expansion and Bangladesh's textile sector absorption are redrawing sub-regional trade flows.
China
Zhejiang province hosts the densest concentration of PTA-PET integrated capacity, with producers absorbing MEE emissions intensity compliance costs through carbon capture retrofits. The dual carbon goals framework is filtering out marginal operators in Jiangsu province while survivors consolidate around minimum efficient scale thresholds. Yisheng Petrochemical's captive PTA supply at its Ningbo complex exemplifies the backward integration strategy dominating surviving producers.
India
Maharashtra and Gujarat clusters are expanding bottling capacity to serve carbonated soft drink and bottled water brand owners committing to multi-year resin offtake agreements. BIS certification mandates for food-contact applications are reshaping procurement specifications and forcing importers to document compliance pathways. Reliance Industries' integrated refining-petrochemicals position at Jamnagar anchors western India's supply security.
Thailand
Rayong province's Eastern Economic Corridor concentration supports Southeast Asia's most advanced mechanical recycling infrastructure, with flake supply agreements increasingly bypassing traditional resin distribution channels. Brand owner procurement teams in Bangkok negotiate direct chain-of-custody contracts with integrated recyclers. Indorama Ventures' recycling footprint enables transparent documentation for beverage bottler rPET commitments.
Vietnam
Binh Duong and Dong Nai provinces are absorbing fiber-grade resin volumes faster than domestic supply expansion, creating import dependency for textile spinning serving garment export contracts. Bottling capacity additions for bottled water and edible oil segments are pulling bottle-grade procurement upward. The country's phased plastic waste management rules are beginning to shape recycler investment location decisions.
South Korea
Yeosu and Ulsan petrochemical complexes anchor specialized film-grade resin production for display component and electronics packaging applications. The national container deposit system creates differentiated demand profiles separating virgin and recycled-content resin procurement pools. Lotte Chemical Corporation's position exemplifies the premium electronics specialization strategy competing with generalized commodity grades.
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market Competitive Environment
Global majors compete with regional champions across integrated feedstock control and recycling infrastructure access. The vendor base clusters around three archetypes: PTA-backward-integrated petrochemical conglomerates, mechanical recycling specialists with flake supply dominance, and diversified chemical groups pivoting toward film-grade specialties. Capacity consolidation and direct brand owner contracting represent the dominant competitive moves reshaping channel economics.
Within the integrated petrochemical tier, Yisheng Petrochemical and China Petroleum & Chemical Corporation exemplify the captive PTA supply model compressing non-integrated competitors' margins. Among recycling-anchored specialists, Indorama Ventures occupies a position linking Southeast Asian flake collection to brand owner chain-of-custody requirements. Lotte Chemical Corporation represents the premium specialization archetype serving electronics and medical device specifications that command higher-barrier formulation premiums.
| Leading Market Players |
|---|
| Yisheng Petrochemical |
| Lotte Chemical Corporation |
| Indorama Ventures Public Company Limited |
| Jiangsu Sanfangxiang Industrial Group |
| Reliance Industries |
| China Petroleum & Chemical Corporation |
| Zhejiang Wankai New Materials |
| SK Global Chemical |
| Far Eastern New Century Corporation |
| Others |
Value Chain & Pricing Dynamics
Paraxylene feedstock volatility transmits directly through PTA-PET integrated complexes into bottle-grade resin quotations across China and India. Contract structures with multinational beverage bottlers absorb crude oil spikes through quarterly price adjustment clauses, while spot-market fiber-grade transactions in Vietnam and Bangladesh expose smaller spinners to immediate cost pass-through.
Pricing Analysis
Input-cost pass-through dominates Asia-Pacific PET resin pricing, with paraxylene movements transmitting within 30-45 days into bottle-grade contract rates. Three-tier pricing structure across premium certified, standard food-grade, and economy textile-grade levels differentiates procurement pools. Pricing pressure stems from China's MEE emissions compliance costs compressing margins at non-integrated Zhejiang producers. Brand owners in Thailand and Vietnam demonstrate lowest price sensitivity through long-term offtake agreements, while Surat textile clusters exhibit highest sensitivity to paraxylene volatility.
Supply Chain Analysis
Certification gating through India's BIS food-contact mandates and Japan's METI circular economy guidelines fragments procurement pathways across the Asia-Pacific region. Production concentrates in China, India, and Thailand, with Zhejiang province hosting the densest PTA-PET integrated capacity. Raw material flows draw from paraxylene refineries in South Korea and Singapore, ethylene glycol from Middle Eastern crackers, and recycled flake from Thai and Indonesian collection networks. Single-source vulnerability concentrates in purified terephthalic acid supply where Yisheng Petrochemical's Ningbo complex anchors regional availability. Distribution runs through direct mill relationships for multinational bottlers and wholesale distributor networks for dispersed Indian textile spinners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific PET resin functions as a stable compounder anchored by non-discretionary beverage packaging demand and polyester textile consumption in garment export economies. Regulatory recycled-content mandates provide predictable demand floor expansion rather than cyclical volatility.
For Market Incumbents: To counter brand owner disintermediation into direct flake contracting, deepen backward integration into mechanical recycling infrastructure in Thailand and Indonesia. Secure BIS certification pathways in India ahead of institutional procurement standardization. Channel control through transparent chain-of-custody documentation preserves pricing power against distributor bypass. For New Entrants and Emerging Players: Specialty pharmaceutical blister pack manufacturers in Japan and South Korea represent underserved buyers seeking higher-barrier sheet-grade formulations with UL94 V-0 equivalency. Chemical recycling pilot scale-up in Singapore and Taiwan offers white-space entry without mechanical recycling's viscosity degradation constraints. Technical partnership qualification with South Korean display component suppliers enables premium film-grade positioning above commodity competition. For Investors and Strategic Acquirers: Consolidation pressure builds where MEE compliance costs exceed retrofit economics for sub-scale Jiangsu producers. Long-term viability favors integrated PTA-PET recyclers with captive flake supply and brand owner direct contracting relationships. Acquisition targets cluster around mechanical recycling specialists with Southeast Asian collection network density. The signal to watch is rPET flake price divergence from virgin resin indicating supply constraint inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Infrastructure | Captive flake supply secures chain-of-custody documentation for Coca-Cola and Nestlé procurement teams. |
| MEE Emissions Compliance Retrofit | Carbon capture installation at Zhejiang complexes filters marginal competitors and tightens effective supply. |
| Long-term Supply Agreement with Beverage Bottlers | Five-year offtake contracts with Thai and Vietnamese bottlers lock in volume visibility through crude volatility. |
| Joint Venture for Chemical Recycling Scale-up | Pyrolysis partnerships in Singapore and Taiwan test food-contact purity without viscosity loss limitations. |
| BIS Certification Infrastructure Investment | Early standardized grade qualification in India captures specification-setting authority for institutional procurement. |
Study Parameters
Multiple input streams — primary interviews with plant managers at integrated PTA-PET complexes, procurement leads at multinational beverage bottlers, and distribution channel partners across Indian textile clusters — were reconciled against secondary validation from customs trade data, SEC filings of listed petrochemical groups, and MEE emissions disclosure records. Bottom-up capacity utilization estimates and top-down demand absorption models were triangulated to constrain volume outputs.
Historical capacity expansion patterns were cross-referenced against panel input from resin procurement directors to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry concentration, and regional regulatory framework cluster. CAGRs were derived from supply-demand balance trajectories incorporating India's BIS certification rollout pace and China's dual carbon goal implementation stringency.
Inputs from MEE disclosure filings and brand owner sustainability reports were available through the study window; gaps in real-time flake inventory positioning introduce uncertainty bands around recycled-content penetration assumptions. Forecasts reflect documented assumptions regarding chemical recycling commercialization timelines and Southeast Asian collection infrastructure buildout velocity. A model refresh is warranted upon material change in China's emissions enforcement intensity or India's plastic waste rule implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Europe Engineering Plastics Market