
 Styrene Acrylonitrile (SAN) Market | 2026-2036
Styrene Acrylonitrile (SAN) Market Size, Share, and Industry Trends Forecast 2026-2036
Styrene Acrylonitrile (SAN) Market Intelligence
The unbundling of general-purpose grades from specialty high-heat or chemical-resistant compounds is shifting buyer procurement strategies toward more targeted material selection. INEOS Styrolution leverages its extensive production network to serve high-volume applications across multiple continents. BASF SE differentiates through its portfolio of advanced polymer additives and specialized SAN blends for technical parts. Chi Mei Corporation competes on manufacturing scale and cost efficiency, particularly for customers within Asia.
Styrene Acrylonitrile (SAN) is a copolymer thermoplastic produced from styrene and acrylonitrile monomers, typically with an acrylonitrile content between 20% and 30%. It is valued for its high transparency, rigidity, and superior chemical resistance compared to standard polystyrene. Its primary industrial purpose is in manufacturing items that require both visual clarity and structural integrity, such as appliance components and cosmetic packaging. Consumer goods, including housewares and appliance housings, constitute the largest application segment, while demand for specialized SAN blends is rising in automotive parts.
Compliance with chemical safety regulations like the EU's REACH framework is mandatory for market access in Europe. In the United States, the FDA specifies requirements for SAN used in food-contact applications under 21 CFR. China's GB standards govern material safety and performance for a wide range of consumer and industrial products, impacting formulation choices for producers. SAN manufacturers must navigate these divergent regional standards while innovating to meet demands for more sustainable polymer solutions.
Market Dynamics
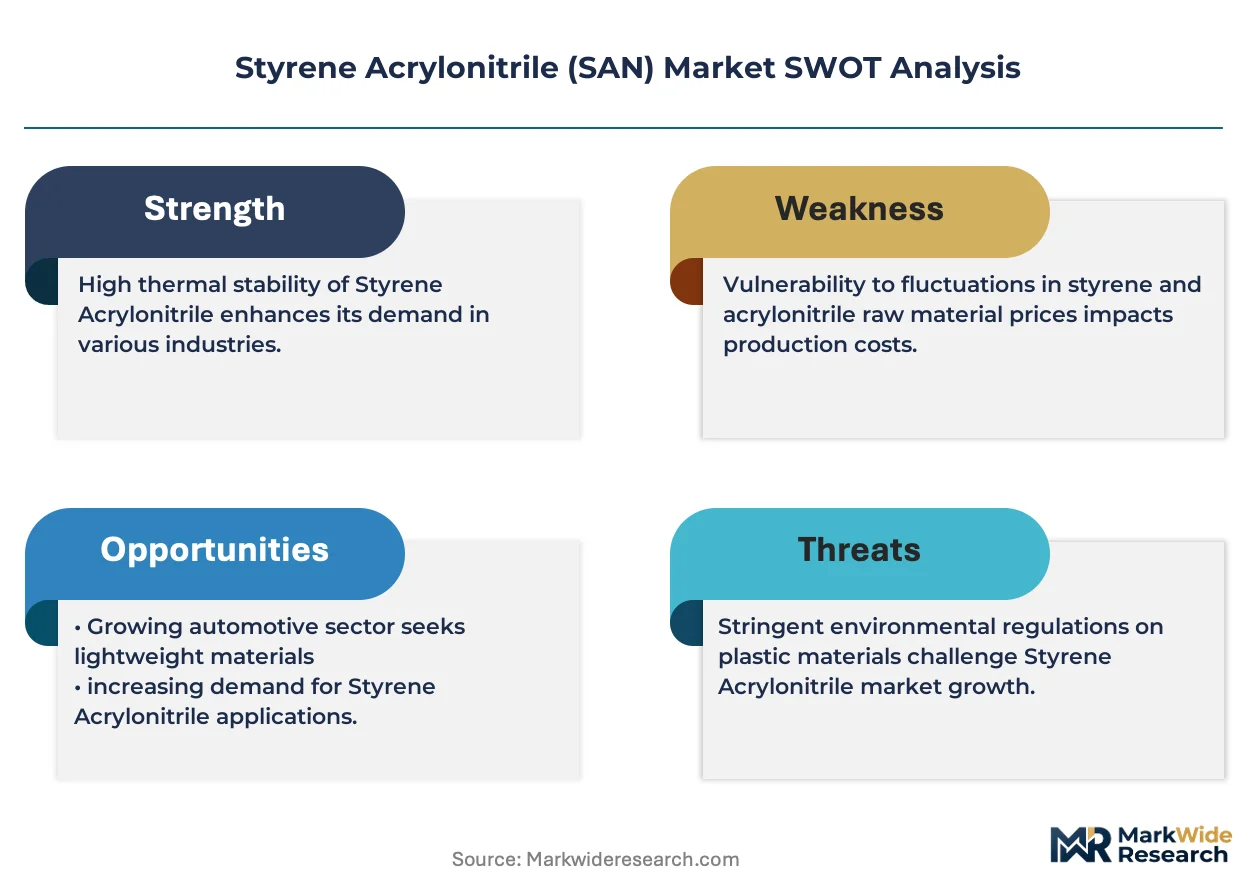
The market's central dynamic is the bifurcation between high-volume, general-purpose grades and specialized compounds. This divergence is driven by application-specific performance demands from industries like automotive and electronics, clashing with cost-down pressures from commodity procurement.
Growth Catalysts
- Consumer Goods Expansion:Demand from the home appliance and kitchenware sectors for materials with high clarity, like refrigerator drawers and blender jars, continues to expand.
- Stricter Food-Contact Standards:Regulations such as the EU's specific migration limits are pushing manufacturers toward higher-quality, compliant SAN grades, creating a premium performance segment.
- Automotive Sector Demand:The use of SAN in automotive interiors and lighting components is increasing as carmakers in Germany and Japan seek to reduce vehicle weight.
Market Restraints
- Styrene Monomer Volatility:Price fluctuations in styrene, a primary feedstock derived from crude oil, directly impact SAN production costs and create margin pressure for manufacturers.
- Competition from Alternative Polymers:Materials like polycarbonate (PC) and acrylic (PMMA) offer similar properties for certain applications, posing a substitution threat in transparent housings and covers.
- Geographic Production Concentration:The heavy concentration of SAN manufacturing in China creates supply chain vulnerabilities for buyers in other regions, exposing them to geopolitical risks and shipping disruptions.
Strategic Opportunities
- Medical Device Components:Developing medical-grade SAN for applications like diagnostic cassettes and fluid-handling devices represents a high-value growth avenue, leveraging its chemical resistance and clarity.
- Bio-based Feedstocks:Innovating with bio-attributed or recycled styrene monomers to produce more sustainable SAN grades can meet corporate sustainability goals and appeal to environmentally conscious customers.
- Expansion in Southeast Asia:Manufacturing growth in countries like Vietnam and Indonesia presents underpenetrated markets for SAN, especially for appliance and electronics production.
Industry Challenges
- Navigating Divergent Regulations:Managing compliance across multiple regional standards, such as the EU's REACH, US FDA rules, and China's GB standards, requires significant technical and administrative resources.
- Improving Heat Resistance:Enhancing the heat deflection temperature of SAN without compromising its clarity or processability is a persistent technical challenge for R&D teams targeting demanding applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Styrene Acrylonitrile (SAN) Market |
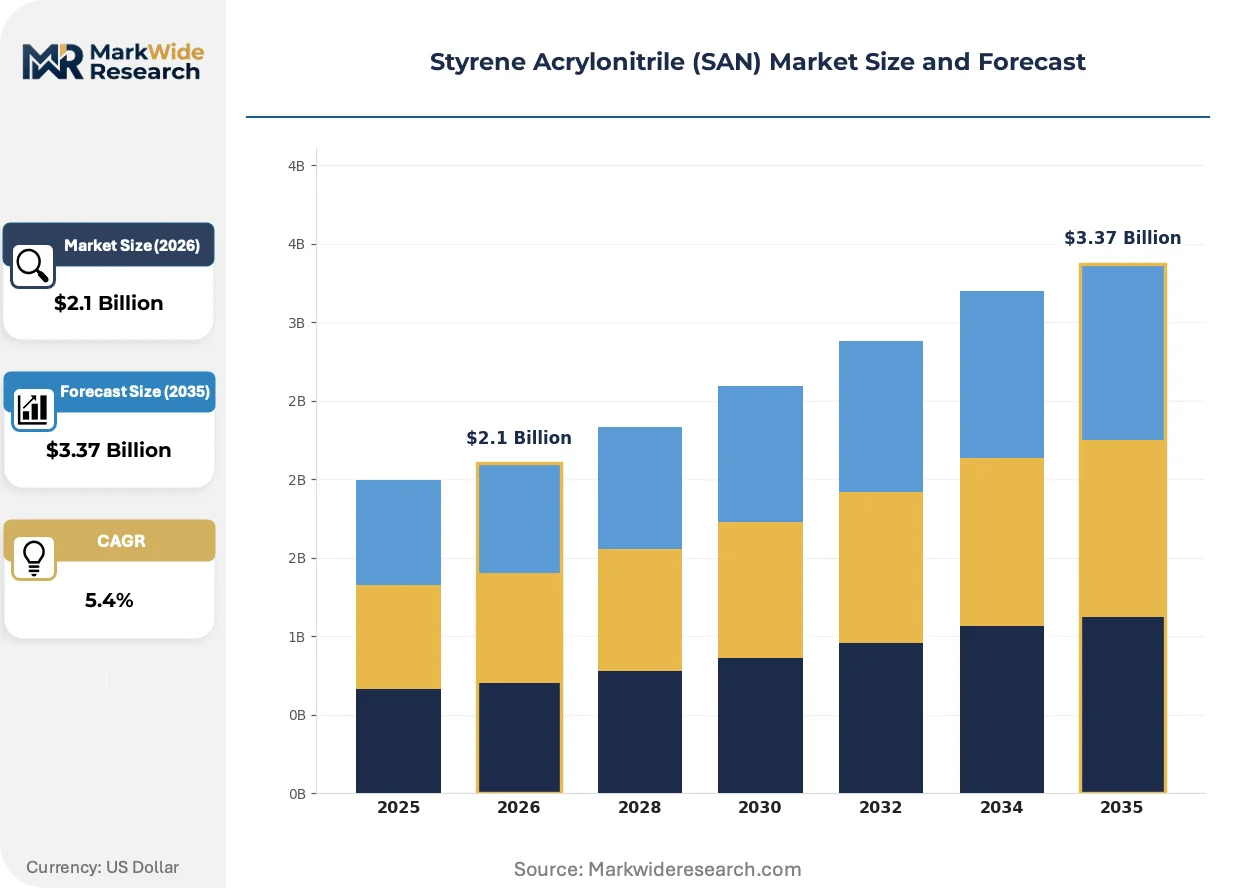
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copolymer, Blends, Compounds, Granules Application: Consumer Goods, Automotive Parts, Electrical Components, Packaging Films End User: Manufacturers, Retailers, Automotive OEMs, Electronics Firms Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Specialty Stores |
| Companies Covered | BASF SE, Chi Mei Corporation, SABIC, Styron LLC, Asahi Kasei Corporation, INEOS Styrolution, Trinseo, Versalis S.p.A., LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Styrene Acrylonitrile (SAN) Market Strategic Shifts & Innovations
Material science innovation is actively focused on enhancing sustainability credentials without sacrificing performance. This dual objective drives new polymer formulations and influences downstream product design, particularly in consumer-facing sectors like appliances and packaging.
Specialized polymer additives, such as advanced UV stabilizers and antistatic agents, enhance SAN’s durability for outdoor or electronic applications. Automotive and consumer electronics manufacturers are increasingly specifying these enhanced grades for exterior parts and sensitive component housings. This development of tailored compounds is absorbing market share from materials requiring secondary processing steps.
European Union regulations like the Corporate Sustainability Reporting Directive (CSRD) are creating new compliance demands. The directive compels producers to disclose detailed environmental data, including the carbon footprint of polymers like SAN throughout their lifecycle. This affects all manufacturers selling into the EU, forcing investments in life-cycle assessment capabilities and traceable supply chains.
Buyers are shifting toward more targeted material selection based on specific performance needs, moving away from reliance on general-purpose grades. This unbundling of specialty compounds disrupts traditional high-volume distribution channels, fostering direct collaboration between end-users and polymer manufacturers for technical solutions. This pattern is most pronounced in the medical device and automotive sectors in North America and Europe.
Styrene Acrylonitrile (SAN) Market Segmentation
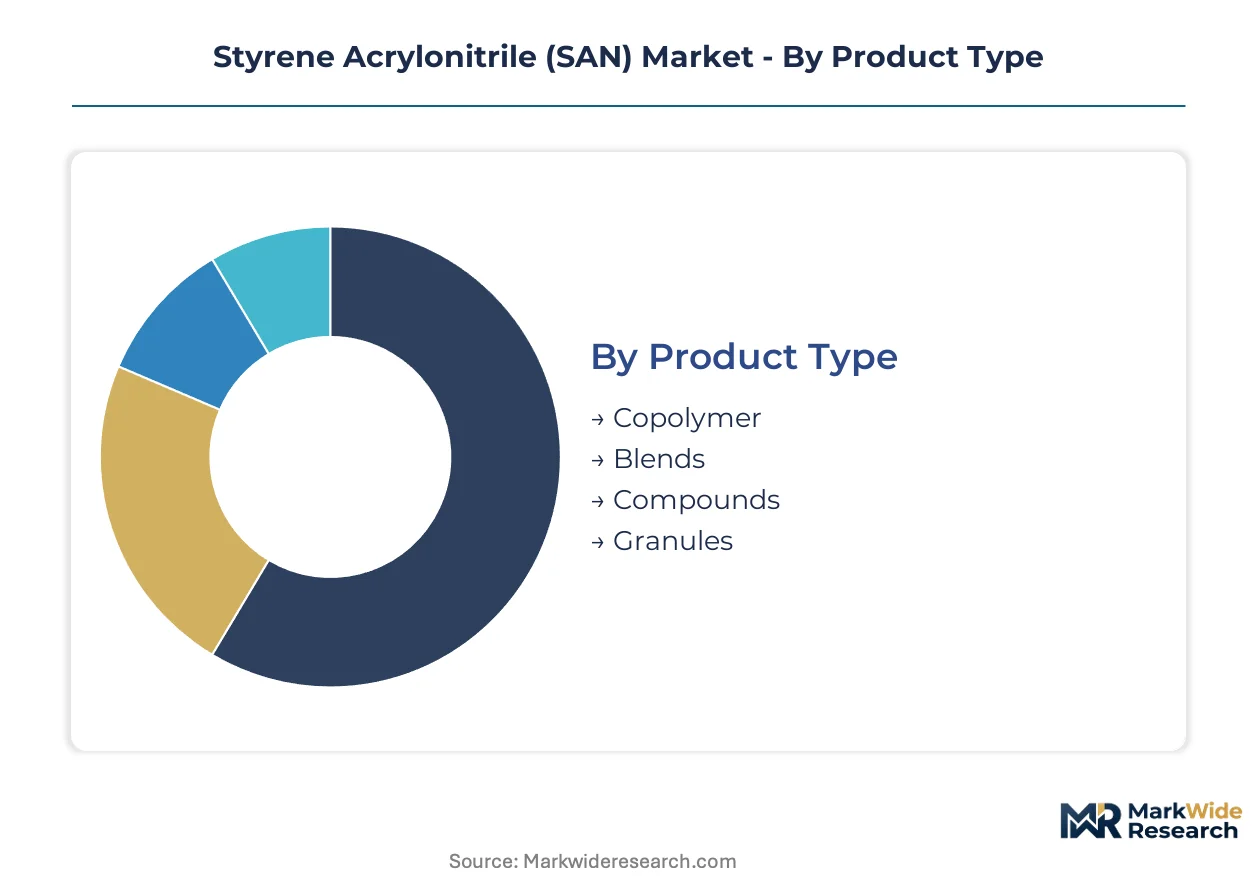
Understanding the segmentation of the Styrene Acrylonitrile (SAN) market is critical for stakeholders to identify specific growth avenues and tailor product development. This detailed breakdown illuminates how various product forms, applications, end-users, and distribution channels shape demand dynamics and competitive strategies across the industry.
Product Type:
Buyers often select Styrene Acrylonitrile based on the specific performance characteristics required for their manufacturing processes and final product specifications.
- Copolymer:This is the base SAN material, offering high transparency, rigidity, and chemical resistance, making it suitable for clear components. Demand concentrates in high-clarity consumer goods like kitchenware and refrigerator drawers, driven by aesthetic and durability requirements in Europe.
- Blends:These combine SAN with other polymers to enhance specific properties such as impact strength or heat resistance for more demanding applications. Automotive parts manufacturers in Germany utilize these blends for interior components to meet stringent performance and safety standards.
- Compounds:These are specialized SAN formulations incorporating additives for UV stability or antistatic properties, tailored for specific environmental or functional needs. Electronics firms specify these for sensitive component housings requiring enhanced protection.
- Granules:This form represents the primary raw material state for molding and extrusion processes, offering ease of handling and processing. Manufacturers procure granules for high-volume production of appliance components in China.
Copolymer leads on scale; Blends lead on momentum.
Application:
The functionality required for a specific product dictates the choice of SAN, influencing material selection across diverse industrial sectors.
- Consumer Goods:This segment includes housewares, personal care items, and appliance housings, valuing SAN for its clarity, rigidity, and chemical inertness. Demand from the home appliance sector in China is particularly strong for refrigerator drawers and blender jars.
- Automotive Parts:SAN finds use in interior trim, lighting components, and instrument panels, where its scratch resistance and aesthetic appeal are critical. Japanese carmakers increasingly integrate SAN to achieve vehicle weight reduction targets for new models.
- Electrical Components:SAN is used in switch covers and transparent housings for its insulating properties and dimensional stability under various conditions. Electronics manufacturers in Southeast Asia utilize SAN for sensitive enclosures.
- Packaging Films:This application leverages SAN's barrier properties and clarity for food and cosmetic packaging, providing enhanced product visibility and protection. Pharmaceutical packaging producers utilize SAN for rigid containers.
Consumer Goods represent the largest volume segment, while Automotive Parts exhibit the steepest expansion trajectory.
End User:
Different end-user types prioritize material attributes differently, shaping their procurement strategies for Styrene Acrylonitrile.
- Manufacturers:These include producers of various consumer goods and industrial products, who procure SAN as a raw material for injection molding and extrusion. Appliance manufacturers in Vietnam require consistent SAN grades for high-volume production lines.
- Automotive OEMs:Original Equipment Manufacturers directly specify SAN for vehicle interior components, demanding high-performance grades that meet strict automotive standards. German automotive brands frequently collaborate with SAN suppliers for customized blends.
- Retailers:This segment primarily involves companies selling finished goods containing SAN, influencing material choice through consumer preferences and regulatory compliance. Large retail chains affect packaging material specifications.
- Electronics Firms:These companies use SAN for housings, displays, and internal components, valuing its clarity, rigidity, and electrical insulation. South Korean electronics giants utilize SAN for transparent device covers.
Manufacturers drive the bulk of SAN consumption, with Automotive OEMs gaining share fastest due to specialized requirements.
Distribution Channel:
The structure of the supply chain significantly influences how Styrene Acrylonitrile reaches its diverse end-users, affecting logistics and pricing.
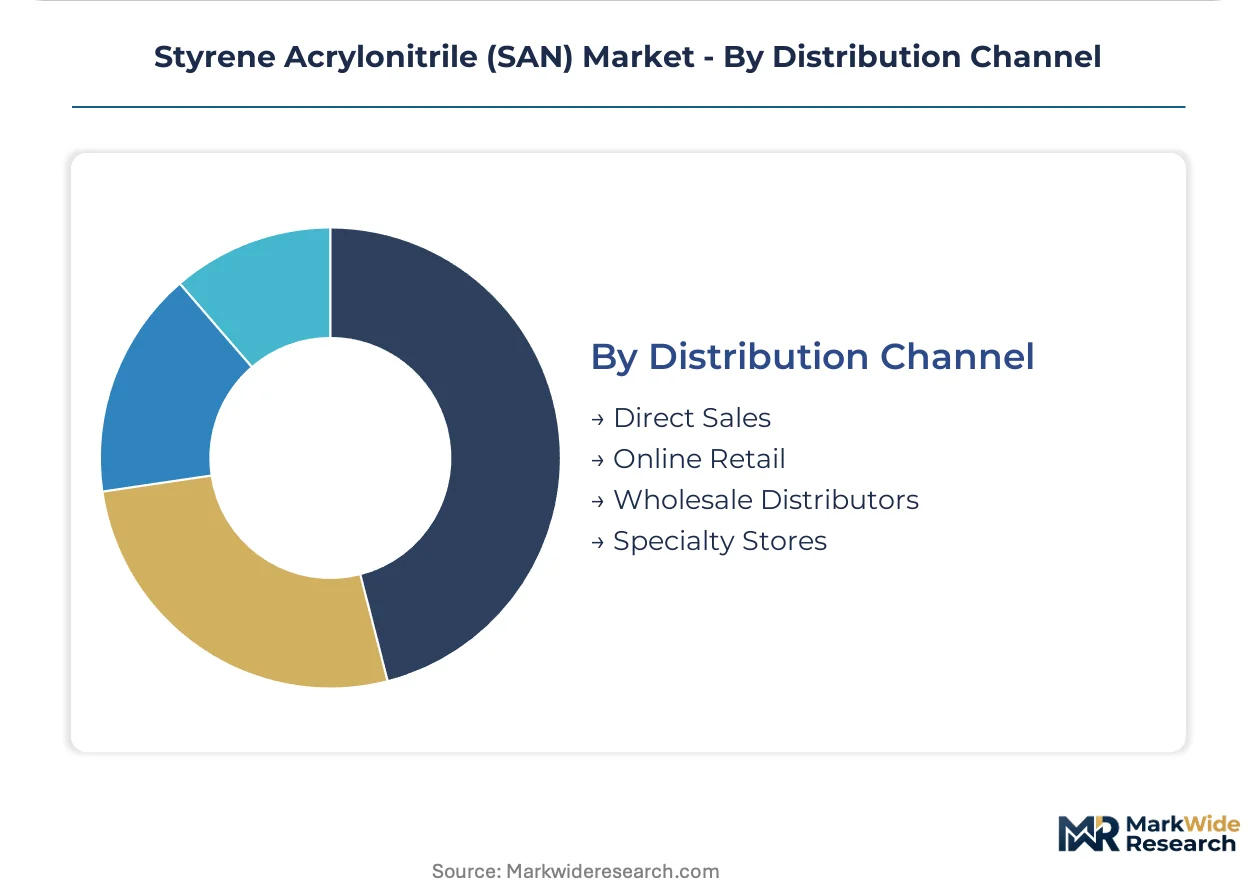
- Direct Sales:This channel involves direct transactions between SAN producers and large industrial buyers, often for high-volume, customized orders. Major chemical companies manage direct sales to global automotive suppliers for specialized grades.
- Wholesale Distributors:These intermediaries handle bulk quantities of SAN, providing inventory management and logistics services to smaller manufacturers and diverse industrial clients. Regional distributors in India serve local appliance and packaging producers.
- Online Retail:This emerging channel facilitates procurement of standard SAN grades, particularly for smaller businesses or specialized projects. E-commerce platforms offer a convenient purchasing option for specific SAN compounds.
- Specialty Stores:These outlets cater to niche markets requiring specific SAN formulations, often in smaller volumes, such as for prototyping or specialized technical applications. Technical plastics suppliers stock specific SAN grades for R&D purposes.
Direct Sales manage the largest volumes of SAN, while Wholesale Distributors show consistent expansion in regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Styrene Acrylonitrile market originated and scaled significantly with the rise of plastics manufacturing in the mid-20th century. Early applications in consumer goods and appliances drove initial demand across developed economies. Today, global production and consumption patterns reflect evolving industrial landscapes and regulatory frameworks.
China
Demand from its expansive electronics and automotive industries fuels significant SAN consumption. China's GB standards strictly govern material safety and performance for diverse product applications. The Yangtze River Delta region, including major manufacturing hubs like Shanghai and Nanjing, drives high-volume appliance and electronics production using SAN.
Germany
Automotive parts manufacturers in Germany increasingly specify SAN for interior components and lighting applications. The EU's REACH framework ensures stringent chemical safety and market access for all SAN producers. Bavaria and North Rhine-Westphalia house major automotive component suppliers and advanced plastics processors, fostering material innovation.
United States
Consumer goods and medical device components are expanding as key application areas for SAN in the United States. The FDA specifies requirements for SAN used in food-contact applications under 21 CFR, influencing formulation choices. The Ohio Valley region supports a robust chemical and plastics manufacturing base, serving diverse industrial and consumer end-users.
Japan
Carmakers in Japan increasingly integrate SAN to achieve vehicle weight reduction targets for new models and aesthetic appeal. JIS standards guide material quality and performance for SAN across diverse industrial and consumer applications. The Kanto region, including Tokyo, concentrates automotive and electronics manufacturing, driving specialized SAN demand and R&D.
Styrene Acrylonitrile (SAN) Market Key Industry Players
Premium-margin players sit above commodity-margin players across product specialization, technical support, and regulatory compliance. The market structure exhibits a tiered consolidation, with large integrated chemical companies at the top and regional specialists below. Strategic archetypes include global material suppliers, specialized compounders focused on high-performance grades, and cost-efficient regional producers serving high-volume markets. Portfolio diversification into advanced blends and geographic expansion into emerging industrial hubs represent dominant competitive moves among the larger entities.
Within the global material supplier archetype, BASF SE, a German-based chemical giant, exemplifies a focus on advanced polymer additives and specialized SAN blends for technical parts, particularly in demanding automotive and electronics applications. INEOS Styrolution, operating from its extensive production network across multiple continents, represents a high-volume supplier for general-purpose and specialty SAN applications. Chi Mei Corporation, a Taiwan-based manufacturer, anchors the cost-efficiency segment, particularly serving customers within Asia with large-scale production capabilities for consumer goods and appliance components.
| Leading Market Players |
|---|
| BASF SE |
| Chi Mei Corporation |
| SABIC |
| Styron LLC |
| Asahi Kasei Corporation |
| INEOS Styrolution |
| Trinseo |
| Versalis S.p.A. |
| LG Chem |
| Others |
Cost & Logistics Intelligence
European Union regulations like the Corporate Sustainability Reporting Directive (CSRD) gate both qualified SAN supply and premium-tier pricing access. This mandate compels producers to disclose detailed environmental data, influencing market dynamics.
Pricing Analysis
Contract-based long-term offtake agreements define pricing for specialized SAN grades, while general-purpose materials often trade on commodity spot markets. Price differentiation stems from specific performance characteristics required by applications like automotive interiors and regulatory compliance for food-contact materials. Pricing softness reflects volatility in styrene monomer feedstock costs, impacting manufacturer margins. General-purpose buyers in consumer goods exhibit high price sensitivity, whereas Automotive OEMs prioritize performance and regulatory adherence.
Supply Chain Analysis
Regional distribution centers facilitate the flow of SAN from major production hubs to diverse end-users, supporting a hub-and-spoke model for local markets. Supply concentration is prominent in China, Germany, and Japan, which anchor significant manufacturing capabilities. The SAN supply chain relies on styrene and acrylonitrile monomers, making it vulnerable to feedstock price volatility. Geopolitical risks and shipping disruptions pose a structural risk for buyers outside primary production regions. Direct sales manage large volumes, while wholesale distributors serve smaller, regional manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Styrene Acrylonitrile market operates as a regulatory compounder, with the EU's specific migration limits for food-contact materials driving demand for higher-quality, compliant SAN grades. This regulatory push elevates performance requirements across the industry.
For Market Incumbents: Anticipate continued pressure from alternative polymers like polycarbonate by investing heavily in R&D for enhanced SAN properties. Deepen vertical integration into bio-based feedstocks to mitigate styrene monomer volatility and meet sustainability goals. Expand production capacity in Southeast Asia to serve appliance and electronics manufacturing growth there. Strengthen technical support for specialized blends to maintain premium positioning against commodity players.
For New Entrants and Emerging Players: Medical device manufacturers represent an underserved buyer archetype, seeking high-value SAN for diagnostic cassettes and fluid-handling devices. Target this segment with specialized medical-grade SAN formulations leveraging clarity and chemical resistance. Southeast Asia's appliance production offers a penetrable market for cost-effective, compliant SAN grades. Go-to-market strategies should focus on bio-attributed or recycled content certifications to appeal to environmentally conscious customers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional producers focused on high-volume, general-purpose SAN grades. The long-term viability of the SAN market depends on continuous innovation in sustainable solutions over the next decade. Target specialized compounders with proprietary blends for automotive and medical applications as acquisition archetypes. A key signal to watch is the widespread adoption of bio-based styrene monomers, indicating a shift towards circular economy principles.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces the carbon footprint of SAN production, aligning with EU CSRD requirements for manufacturers. |
| Long-term Supply Agreement | Secures stable feedstock supply, mitigating styrene monomer price volatility for producers. |
| Capacity Expansion | Addresses growing demand from the consumer goods sector in Southeast Asia, particularly for appliance components. |
| Joint Venture | Facilitates shared R&D for advanced SAN blends, targeting demanding applications in the automotive sector. |
| Certification Investment | Gains market access in regulated sectors, meeting FDA and EU food-contact material standards. |
Research Approach
Multiple input streams — primary interviews, industry association reports, and trade statistics — were reconciled to build the market's data foundation. Primary research engaged plant managers, procurement leads at OEMS, R&D directors, and distribution channel partners across key regions. Secondary validation utilized customs data, chemical industry reports, and company 10-K filings. This approach ensured bottom-up granularity and top-down consistency through triangulation.
Data-stream reconciliation informed the analytical framework across the analysis window, integrating historical trends with future projections. The model segmented demand by product type, application, end-user, and regional production hubs like the Yangtze River Delta. Compound Annual Growth Rates were derived from an assessment of application-specific demand and technological advancements. Key inputs included styrene monomer price forecasts and regional automotive production volumes.
Underlying measurement precision varies by segment; consumer goods and automotive parts carry tighter precision than emerging medical device applications. All forecasts reflect assumptions regarding feedstock stability and regulatory evolution. Geopolitical shifts or unforeseen feedstock price volatility represent risk factors that could revise these projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Water-Borne Epoxy Resins Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Global Polypropylene Random Copolymer Market