
 Soy Polysaccharides Market | 2026-2036
Soy Polysaccharides Market Size, Share, and Industry Trends Forecast 2026-2036
Soy Polysaccharides Market Analytics
China is reshaping soy polysaccharide supply dynamics through expanded domestic crushing and refining infrastructure. Archer Daniels Midland Company leverages its origination network across the U.S. Midwest to secure consistent soybean supply for polysaccharide extraction. Cargill, Incorporated sustains vertical integration from seed development to food ingredient formulation, reducing input cost volatility. Fuji Oil Holdings anchors Asian market access through specialized soy protein and fiber production capabilities in Japan.
Soy polysaccharides comprise complex carbohydrate fractions extracted from soybean cell walls and cotyledon matrices, typically containing pectic substances, hemicelluloses, and cellulose with molecular weights ranging from 10,000 to 2,000,000 Daltons; these hydrocolloid structures function primarily as water-binding agents, stabilizers, and fat replacers in processed foods. The food industry end user segment dominates current volume consumption, driven by reformulation demands in bakery products and dairy alternatives where soy fiber replaces modified starches. Nutraceutical applications represent the fastest-expanding demand pool, as soy gums gain traction in encapsulation matrices for bioactive delivery systems.
FDA oversight of Generally Recognized As Safe notifications shapes ingredient approval timelines for novel soy polysaccharide fractions entering U.S. food channels. REACH registration requirements in Europe enforce comprehensive toxicological dossiers for imported soy-derived additives, elevating compliance costs for non-European suppliers. ISO 22000 certification has become a baseline qualifier for ingredient vendors serving multinational food manufacturers. Stakeholders must monitor evolving EFSA opinions on dietary fiber definitions, as reclassification would directly alter permissible health claims and reformulation incentives across member states.
Market Dynamics
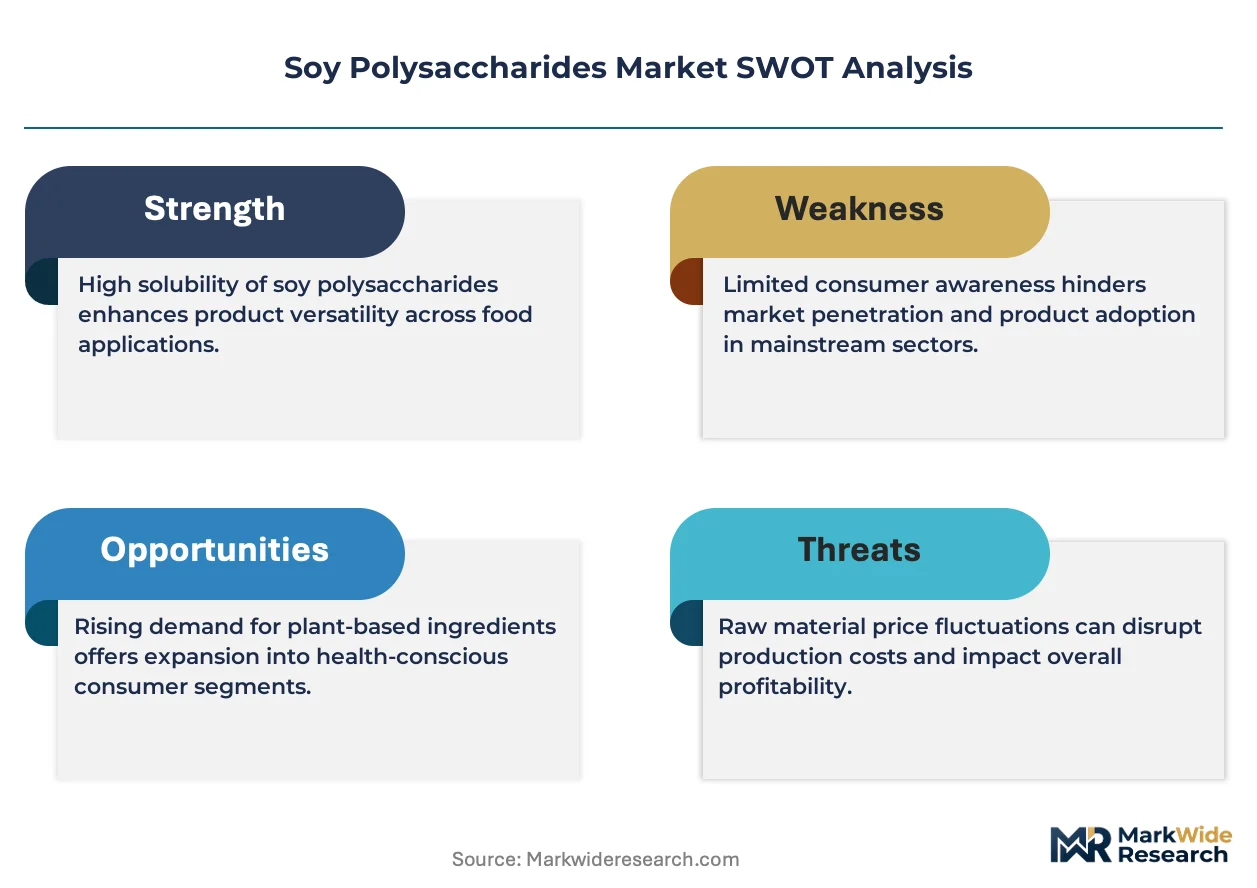
Clean-label reformulation mandates across North American beverage and dairy alternative sectors are compressing approval timelines for novel soy polysaccharide fractions, forcing ingredient suppliers to pre-validate glycation protocols and fiber purity benchmarks before commercial scale-up.
Growth Catalysts
- REACH compliance deadlines:ECHA registration requirements for imported hydrocolloids are compelling European food manufacturers to qualify domestic soy fiber sources, accelerating contract migrations to EU-based refiners.
- Encapsulation matrix demand:Nutraceutical formulators in Japan are adopting soy gum complexes for bioactive delivery systems, displacing gelatin and synthetic alternatives in probiotic and omega-3 applications.
- Germany dairy alternatives:Food technologists in Berlin and Hamburg prioritize glycated soy protein isolates for oat-soy hybrid beverages, creating pull-through demand for companion polysaccharide stabilizers.
Market Restraints
- Soybean input volatility:Crush margin compression at U.S. Midwest processing facilities transmits directly to polysaccharide extraction economics, squeezing tolling contract profitability.
- EFSA fiber definition uncertainty:Pending opinions on dietary fiber reclassification threaten to invalidate existing health claims across member states, freezing reformulation investment cycles.
- Modified starch substitution:Clean-label positioning of tapioca and potato-derived texturizers in bakery applications limits soy fiber penetration in premium European bread segments.
Strategic Opportunities
- Indian FSSAI fiber fortification:Draft guidelines on mandatory dietary fiber enrichment in processed wheat products create a regulatory tailwind for soy hull polysaccharide imports.
- Cell-cultured meat scaffolding:Hybrid soy fiber-collagen matrices are emerging as cost-effective structural supports for cultivated poultry and seafood prototypes in Singapore and Israel.
- Direct-to-manufacturer platforms:Digital ingredient marketplaces are disintermediating traditional distributor networks, enabling mid-size U.S. bakery chains to source customized soy gum blends with shorter lead times.
Industry Challenges
- ISO 22000 audit backlog:Certification body capacity constraints in Asia-Pacific are extending supplier qualification timelines by four to six months, delaying multinational food manufacturer onboarding.
- Glycation IP fragmentation:Overlapping patent estates covering controlled Maillard reaction protocols for soy protein-carbohydrate conjugates are complicating freedom-to-operate assessments for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soy Polysaccharides Market |
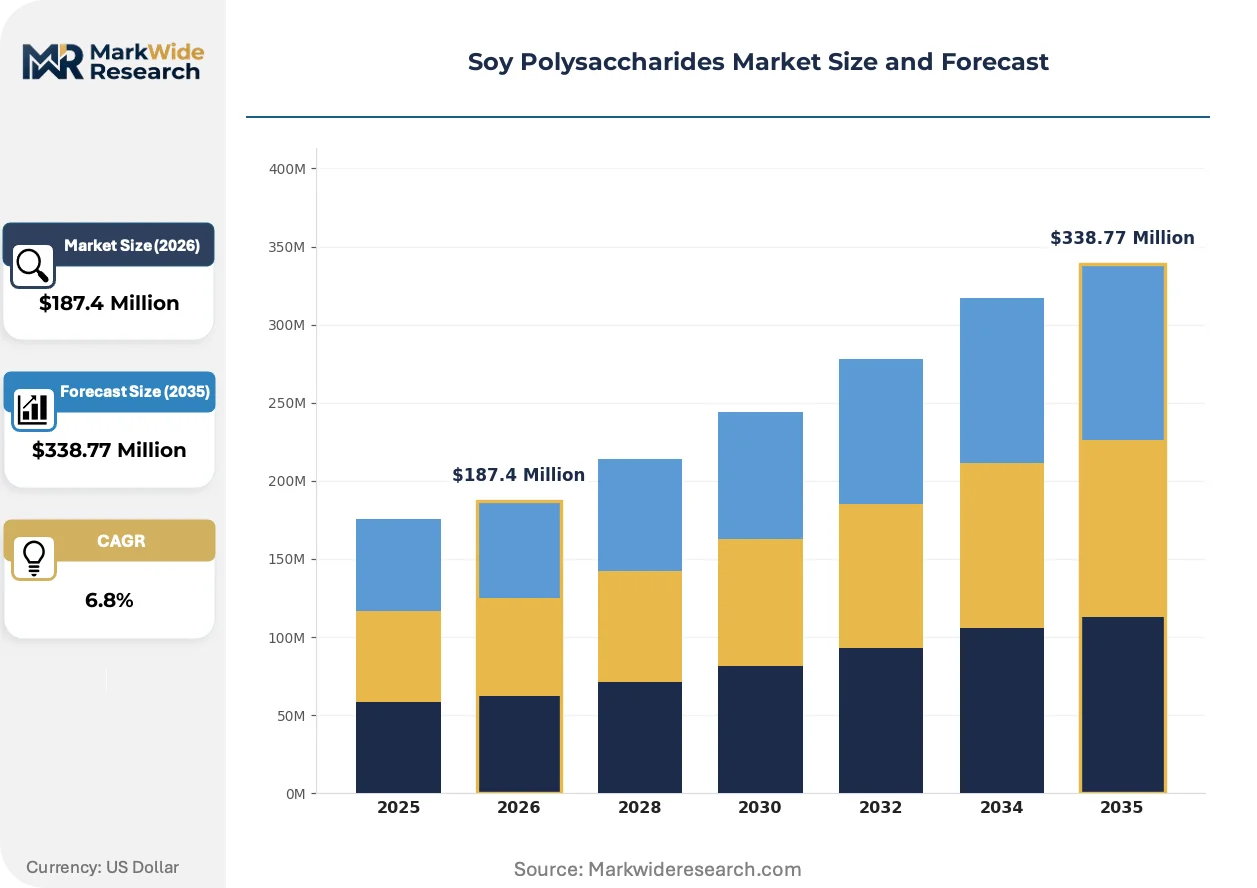
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glycated Soy Protein, Soy Fiber, Soy Gums, Soy Lecithin Application: Beverages, Bakery Products, Sauces, Dairy Alternatives End User: Food Industry, Nutraceuticals, Animal Feed, Cosmetic Industry Packaging Type: Bags, Containers, Bulk, Drums |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, Fuji Oil Holdings, DuPont de Nemours, BASF, Ingredion Incorporated, Kerry Group, Roquette Frères, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soy Polysaccharides Market Evolving Landscape
Enzymatic extraction protocols and precision glycation technologies are compressing the functional performance gap between soy polysaccharides and synthetic hydrocolloids, reshaping competitive dynamics in clean-label formulation.
Enzyme-assisted cell wall disruption using cellulase-pectinase cocktails is migrating from pilot-scale academic partnerships to commercial installations at U.S. and Japanese soy processing facilities. Bakery manufacturers in California and Texas are adopting these fractions at accelerated procurement cycles. This technology is enabling fat-replacement parity with modified starches at 15-20% lower inclusion rates, compressing formulation cost structures for mass-market bread and cake applications.
EFSA's evolving guidance on dietary fiber analytical methods is forcing reformulators to resubmit dossiers for soy hull-derived fractions previously approved under AOAC 985.29. European dairy alternative producers are responding by diversifying supplier bases across German, Dutch, and Spanish extraction facilities to mitigate batch-specific compliance risk. The uncertainty is accelerating investment in in-house analytical capabilities at major food manufacturers.
Specification-driven procurement contracts are displacing traditional commodity purchasing for soy gums in North American beverage applications. Mid-size clean-label brands are bypassing broadline distributors to negotiate directly with Japanese and U.S. refiners for customized viscosity profiles and microbial specifications. This pattern is most visible in the Pacific Northwest and Northeast corridor, where regional kombucha and plant-based milk startups consolidate purchasing through cooperative buying groups.
Soy Polysaccharides Market Segmentation
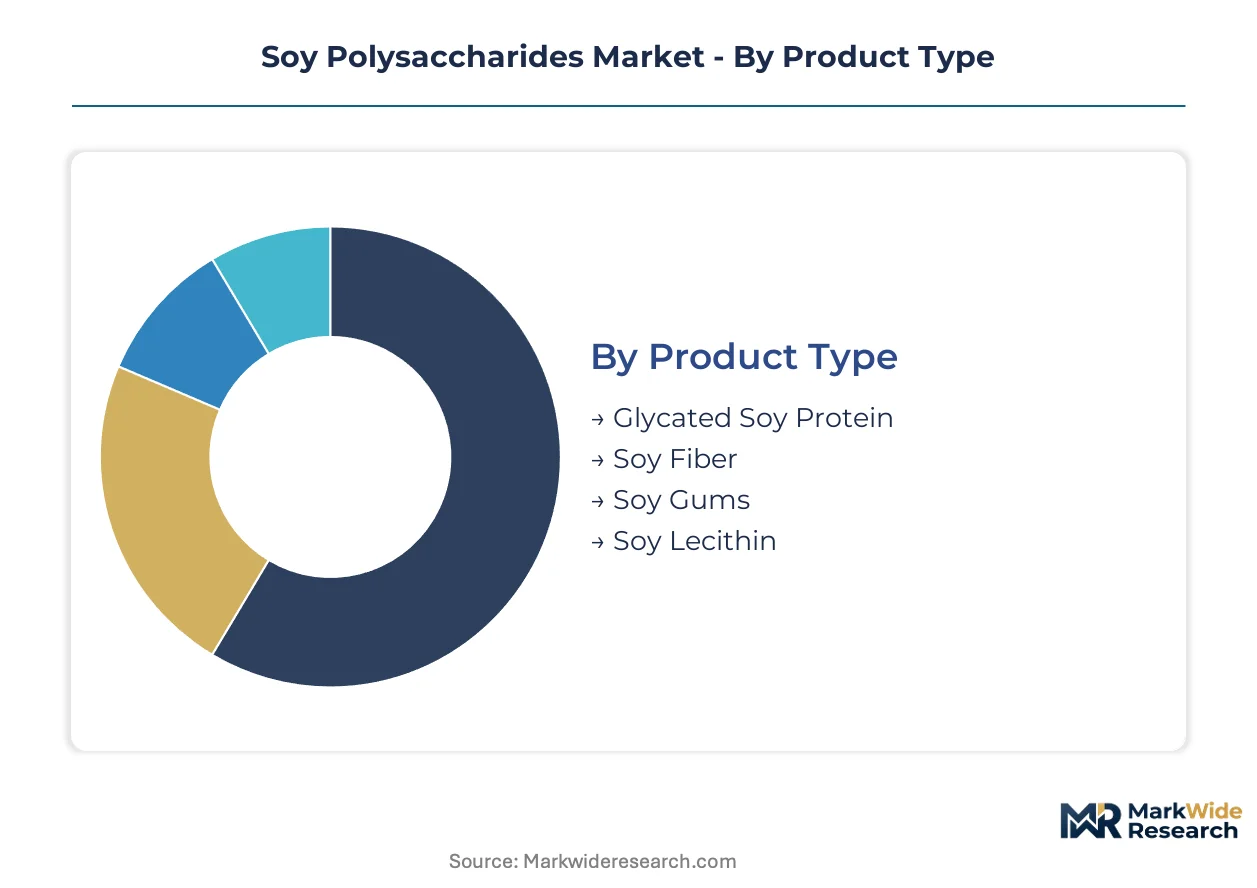
Segmentation in soy polysaccharides reflects divergent technical specifications and procurement cycles across food, nutraceutical, and industrial channels. Product-grade differentiation drives pricing spreads, while application-specific functionality determines supplier qualification timelines and contract structures.
Product Type:
Soy fiber commands the longest production cycles due to multi-stage purification, while soy gums turn over fastest through standardized toll processing agreements.
- Soy Fiber:Cell wall-derived fractions containing hemicellulose and cellulose matrices, typically processed through alkaline extraction and bleaching sequences. Bakery manufacturers in Germany and the Netherlands specify this grade for clean-label bread applications where water-binding capacity must exceed 8g water per gram dry matter. FDA fiber labeling guidance and EFSA dietary fiber definition uncertainty create reformulation risk for existing product lines.
- Soy Gums:Soluble polysaccharide complexes extracted from soybean cotyledons, functioning as hydrocolloid stabilizers with viscosity profiles tunable through enzyme treatment. Japanese nutraceutical formulators in Osaka and Tokyo are adopting these fractions for probiotic encapsulation matrices, displacing gelatin in omega-3 delivery systems. REACH registration requirements for imported hydrocolloids are compressing European procurement timelines.
- Glycated Soy Protein:Maillard-reaction conjugates combining protein and carbohydrate fractions for enhanced emulsification stability. Food technologists in Berlin prioritize these isolates for oat-soy hybrid beverages.
- Soy Lecithin:Phospholipid-rich extracts functioning as emulsifiers distinct from true polysaccharide fractions, though often co-processed in integrated extraction facilities.
Soy fiber dominates installed base across European and North American food manufacturing. Soy gums are where expansion concentrates, climbing the fastest in Asian nutraceutical applications.
Application:
Cost tier stratification separates commodity beverage applications from premium dairy alternative formulations requiring customized viscosity profiles and extended stability guarantees.
- Dairy Alternatives:High-specification stabilizer systems demanding thermal stability across UHT processing and extended shelf-life distribution. California and Pacific Northwest plant-based milk startups are consolidating purchasing through cooperative buying groups to access Japanese refiner capabilities. Specification-driven procurement contracts are displacing traditional commodity purchasing in this channel.
- Bakery Products:Fat replacement and moisture retention applications where enzyme-extracted fractions achieve parity with modified starches at reduced inclusion rates. Texas and California manufacturers are accelerating procurement cycles for cellulase-pectinase processed materials.
- Beverages:Clean-label texturizing applications in kombucha and functional drinks where mid-size brands bypass distributors for direct refiner relationships.
- Sauces:Viscosity modification and emulsion stability in processed condiments, typically sourcing through broadline ingredient distributors with lower technical service requirements.
Bakery products dominate installed base in mass-market applications. Dairy alternatives are where expansion concentrates, gaining share fastest in premium positioning segments.
End User:
Customer type determines margin structure, with multinational food manufacturers demanding ISO 22000 certification and dedicated technical service versus price-sensitive animal feed compounders.
- Food Industry:Dominant volume channel encompassing reformulation mandates across bakery, beverage, and processed food categories. EFSA fiber definition uncertainty is freezing investment cycles at major European manufacturers pending analytical method clarification.
- Nutraceuticals:Encapsulation matrix and bioactive delivery applications with steepest expansion trajectory. Japanese formulators are driving specification innovation for probiotic and omega-3 stabilization.
- Animal Feed:Soy hull polysaccharide applications in pet food and livestock nutrition, sourcing primarily through commodity trading channels with minimal technical service requirements.
- Cosmetic Industry:Emerging demand for soy-derived rheology modifiers in natural positioning personal care products, currently limited by supply chain qualification timelines.
Food industry dominates installed base across all geographies. Nutraceuticals are where expansion concentrates, representing the most rapid demand acceleration.
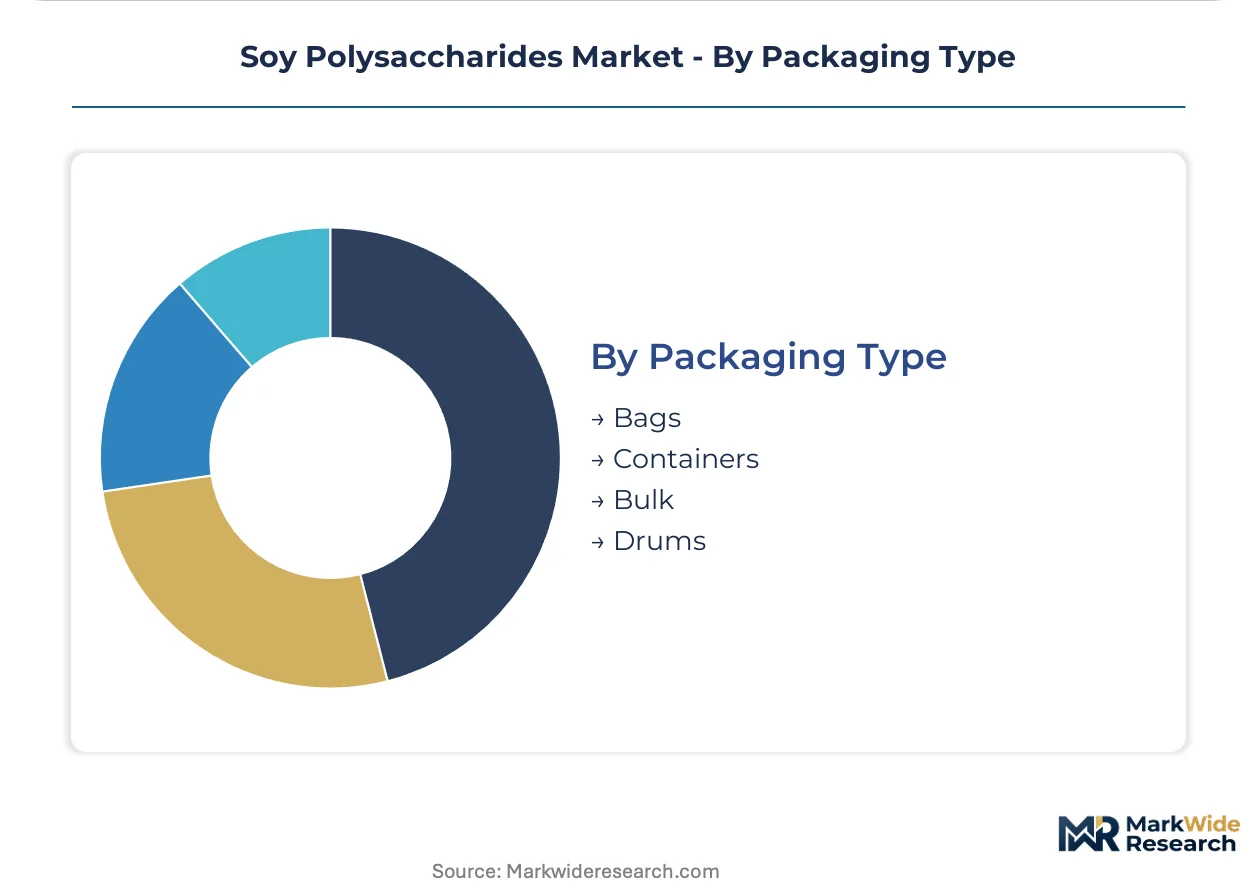
Packaging Type:
Supply concentration in bulk formats reflects downstream processing economics, while specialized containers serve qualified pharmaceutical and cosmetic applications with contamination control requirements.
- Bulk:Tanker and railcar deliveries serving high-volume food manufacturers with integrated handling infrastructure. U.S. Midwest crushing facilities transmit margin compression directly to tolling contract economics.
- Drums:Standardized intermediate packaging for regional distributors and mid-size manufacturers without bulk handling capabilities.
- Bags:Flexible packaging for bakery and small-batch nutraceutical processors with lower throughput requirements.
- Containers:Specialized sanitary packaging for cosmetic and pharmaceutical applications demanding lot traceability and contamination prevention protocols.
Bulk dominates installed base in high-volume food manufacturing. Containers are where expansion concentrates in premium cosmetic and pharmaceutical qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of New Orleans anchors North American soy polysaccharide flows, handling soybean exports from Midwest crushing facilities while European demand routes through Rotterdam's specialized food ingredient terminals.
United States
Midwest crushing complexes in Iowa and Illinois supply raw material to extraction facilities. FDA guidance on plant-based ingredient labeling tightens disclosure standards for soy fiber applications. California beverage startups in the Pacific Northwest consolidate purchasing through cooperative buying groups to access customized soy gum specifications.
Germany
Berlin and Hamburg food technologists prioritize glycated soy protein isolates for oat-soy hybrid beverages. EFSA dietary fiber definition uncertainty freezes reformulation investment cycles pending analytical method clarification. Dutch and Spanish extraction facilities diversify supplier bases to mitigate batch-specific compliance risk.
Japan
Osaka and Tokyo nutraceutical formulators adopt soy gum complexes for probiotic encapsulation matrices. METI standards govern food additive purity specifications for domestic and export markets. Specialized soy protein and fiber production capabilities anchor Asian market access through integrated refining infrastructure.
China
Expanded domestic crushing and refining infrastructure reshapes supply dynamics for soy-derived ingredients. SAMR oversight of food additive registrations shapes approval timelines for novel polysaccharide fractions. Yangtze River Delta processing clusters concentrate enzyme-assisted extraction technology deployment.
India
Draft FSSAI guidelines on mandatory dietary fiber enrichment in processed wheat products create import demand for soy hull polysaccharides. BIS certification requirements elevate qualification timelines for foreign suppliers. Maharashtra and Gujarat food manufacturers evaluate clean-label reformulation options for mass-market bakery applications.
Soy Polysaccharides Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with extraction and purification capabilities. The supplier base stratifies between multinational agribusiness conglomerates with origination networks and specialized refiners with proprietary glycation protocols. Three archetypes dominate: seed-to-ingredient integrators, toll processing specialists, and regional purification facilities. Competitive moves concentrate on backward integration into crushing assets and technology licensing for enzymatic extraction protocols.
Among North American agribusiness operators, Archer Daniels Midland Company and Cargill, Incorporated exemplify the integrated archetype with origination networks across the U.S. Midwest. Fuji Oil Holdings occupies a position within the Asian specialist tier, anchoring regional market access through Japan-based production capabilities. These three entities represent distinct geographic and structural positions without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Fuji Oil Holdings |
| DuPont de Nemours |
| BASF |
| Ingredion Incorporated |
| Kerry Group |
| Roquette Frères |
| International Flavors & Fragrances Inc. |
| Others |
Value Network & Pricing Analysis
REACH registration chokepoints for imported hydrocolloids determine both three-tier pricing spreads across premium, standard, and economy certification levels and the geographic restructuring of supplier networks toward EU-based refiners. Crush margin volatility at U.S. Midwest processing facilities transmits directly into tolling contract economics, compressing profitability for non-integrated extraction operations and accelerating backward integration strategies among major ingredient suppliers.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade soy gums certified under ISO 22000 and REACH dossier completeness from standard food-grade fiber and economy-tier animal feed fractions. Price differentiation rests on glycation protocol IP access and EFSA fiber definition compliance status, with premium tiers commanding substantial spreads due to pending analytical method uncertainty. Pricing pressure stems from modified starch substitution in European bakery applications, eroding soy fiber penetration in premium bread segments. Mid-size clean-label beverage brands exhibit highest price sensitivity through cooperative buying groups, while multinational food manufacturers prioritize specification stability over unit cost.
Supply Chain Analysis
Upstream soybean origination draws from U.S. Midwest crushing complexes, Brazilian export terminals, and expanding Yangtze River Delta processing clusters. Raw material dependencies include soybean hull feedstock, cellulase-pectinase enzyme inputs, and caustic soda for alkaline extraction sequences. Tariff exposure on imported hydrocolloids into Europe is compelling contract migrations to German, Dutch, and Spanish refining facilities. Distribution runs through Rotterdam's specialized food ingredient terminals for European dairy alternative manufacturers and direct-to-manufacturer digital platforms disintermediating traditional distributor networks in North American beverage channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through cooperative purchasing consolidation among Pacific Northwest and Northeast corridor clean-label beverage startups, fragmenting traditional distributor relationships and forcing suppliers toward specification-driven direct contracts.
For Market Incumbents: Insulate tolling contract profitability through captive crushing assets in Iowa and Illinois to offset margin compression from soybean input volatility. Prioritize ISO 22000 certification body capacity investments in Asia-Pacific to reduce supplier qualification delays that extend multinational food manufacturer onboarding timelines by four to six months.
For New Entrants and Emerging Players: Pursue white-space positioning in Indian FSSAI fiber fortification compliance, where draft mandatory enrichment guidelines for processed wheat products create import demand for soy hull polysaccharides. Target cosmetic industry rheology modifier applications with specialized sanitary packaging and lot traceability protocols, leveraging supply chain qualification gaps that currently limit incumbent penetration.
For Investors and Strategic Acquirers: The market sits at a regulatory-uncertainty phase that favors toll processing specialists with proprietary enzymatic extraction capabilities over commodity-grade fiber producers. Long-term viability hinges on glycation IP consolidation and freedom-to-operate clarity in controlled Maillard reaction protocols. Watch EFSA dietary fiber definition resolution as the inflection signal that would unfreeze European reformulation investment cycles and revalue compliant supplier assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crushing Assets | Captive soybean supply secures margin stability against Midwest processing volatility. |
| Enzymatic Extraction Technology Licensing | Cellulase-pectinase protocol partnerships enable fat-replacement parity at reduced inclusion rates. |
| REACH Dossier Completion and Registration | Full ECHA compliance unlocks European dairy alternative procurement contracts. |
| Direct-to-Manufacturer Platform Development | Digital disintermediation captures mid-size bakery chain demand with customized viscosity specifications. |
| Glycation IP Portfolio Acquisition | Controlled Maillard reaction patents resolve freedom-to-operate barriers for protein-carbohydrate conjugates. |
Research Methodology
The analysis maps soy fiber, soy gums, glycated soy protein, and soy lecithin sub-sectors, each validated through food technologists, nutraceutical formulators, procurement leads at multinational food manufacturers, and toll processing operators. Primary interviews combined with secondary validation from FDA GRAS notifications, EFSA dietary fiber opinion trackers, REACH registration databases, and FSSAI draft guideline repositories. Bottom-up volume modeling across extraction facility capacities triangulated with top-down demand aggregation from bakery, dairy alternative, and encapsulation matrix applications.
Assumptions held fixed include current EFSA analytical method uncertainty and REACH compliance timelines, while soybean crush margin volatility and FSSAI fiber fortification finalization were modeled as scenario variables. Segmentation dimensions span product grade, application functionality, end-user certification requirements, and packaging format. CAGRs were derived from installation base expansion rates and specification-driven contract conversion patterns. Industry-specific inputs incorporated enzyme-assisted extraction technology deployment timelines and glycation protocol patent estate fragmentation.
Sensitivities concentrate around EFSA fiber definition reclassification and FSSAI guideline finalization as primary revision triggers. Forecasts reflect documented assumptions on regulatory approval trajectories and buyer consolidation patterns. Material shifts in European dietary fiber analytical standards or Indian mandatory fortification enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Thermoplastic Polyamide Elastomer (TPE) Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market