
 Acrylonitrile Market | 2026-2036
Acrylonitrile Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylonitrile Market Intelligence
Asset-light leasing arrangements for propylene feedstock access is reshaping competitive entry in acrylonitrile production. INEOS Group Limited leverages its European petrochemical integration to sustain cost-advantaged ammonia sourcing. SABIC anchors Middle Eastern supply through captive propylene from cracking operations. Asahi Kasei Corporation specializes in high-purity grades for carbon fiber precursors, differentiating beyond commodity acrylic fiber markets.
Acrylonitrile is a volatile, colorless liquid organic compound manufactured primarily through the Sohio process, where propylene and ammonia react in the presence of a bismuth-molybdenum oxide catalyst at temperatures near 450°C; its primary commercial purpose is serving as a monomer for synthetic polymers including plastics, elastomers, and carbon fiber precursors. ABS resin commands the dominant value pool given its penetration in automotive and electronics housings where impact resistance and moldability prove critical. Polyacrylonitrile represents the fastest-growing product type as precursor demand for aerospace and wind turbine carbon fiber accelerates. Acrylic fiber maintains volume scale in textiles but faces margin compression from polyester substitution in apparel applications.
EPA emissions standards in the United States and EU REACH chemical registration requirements constrain propylene-ammonia process configurations and waste handling protocols. China's MEE enforces dual carbon targets that elevate energy efficiency mandates for coal-based acrylonitrile plants. Stakeholders must monitor feedstock volatility, regulatory compliance costs, and carbon fiber precursor qualification timelines to align capacity decisions with shifting polymer demand profiles.
Market Dynamics
Propylene-ammonia process economics are compressing margins for merchant acrylonitrile producers as integrated petrochemical complexes capture feedstock cost advantages. China's dual carbon mandates and EU REACH chemical restrictions are forcing capital-intensive emissions retrofits that favor scale players with balance sheet capacity.
Growth Catalysts
- Automotive lightweighting mandates:NHTSA fuel economy standards and EU CO2 fleet targets are accelerating ABS resin penetration in vehicle interior and exterior components. German and Japanese OEMs specify high-impact grades for battery housings.
- REACH chemical registration:The EU's substance authorization protocols are consolidating supply among pre-registered producers, creating qualified-supplier premiums for compliant acrylonitrile.
- Carbon fiber precursor qualification:Aerospace OEMs and wind turbine blade manufacturers are qualifying textile-grade PAN from acrylonitrile, opening specification-tight supply relationships with polymer specialists.
Market Restraints
- Propylene price volatility:Steam cracker feedstock shifts between naphtha and ethane are transmitting cost instability to ammonia-oxidation economics, compressing spot margins.
- Supply concentration in China:Coastal petrochemical clusters around Ningbo and Shanghai control exportable surplus, exposing buyers to single-geography disruption risk.
- Polyester substitution in textiles:Acrylic fiber faces displacement in apparel applications where recycled PET achieves comparable hand-feel at lower unit cost.
Strategic Opportunities
- India chemical specialization:PLI scheme incentives for advanced materials are attracting acrylonitrile derivative investments in Gujarat and Maharashtra industrial corridors.
- Hydrogen cyanide co-product valorization:Sodium cyanide and acetone cyanohydrin outlets from acrylonitrile production are improving integrated site economics for complex operators.
- MEE emissions trading:China's national carbon market is creating credit-generation opportunities for coal-to-acrylonitrile plants that achieve efficiency benchmarks ahead of compliance deadlines.
Industry Challenges
- Specialized catalyst procurement:Bismuth-molybdenum oxide formulation expertise concentrates with two technology licensors, constraining process optimization flexibility.
- Carbon fiber qualification timelines:Aerospace-grade PAN precursor certification requires multi-year testing protocols with Boeing, Airbus, and tier-one composite suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylonitrile Market |
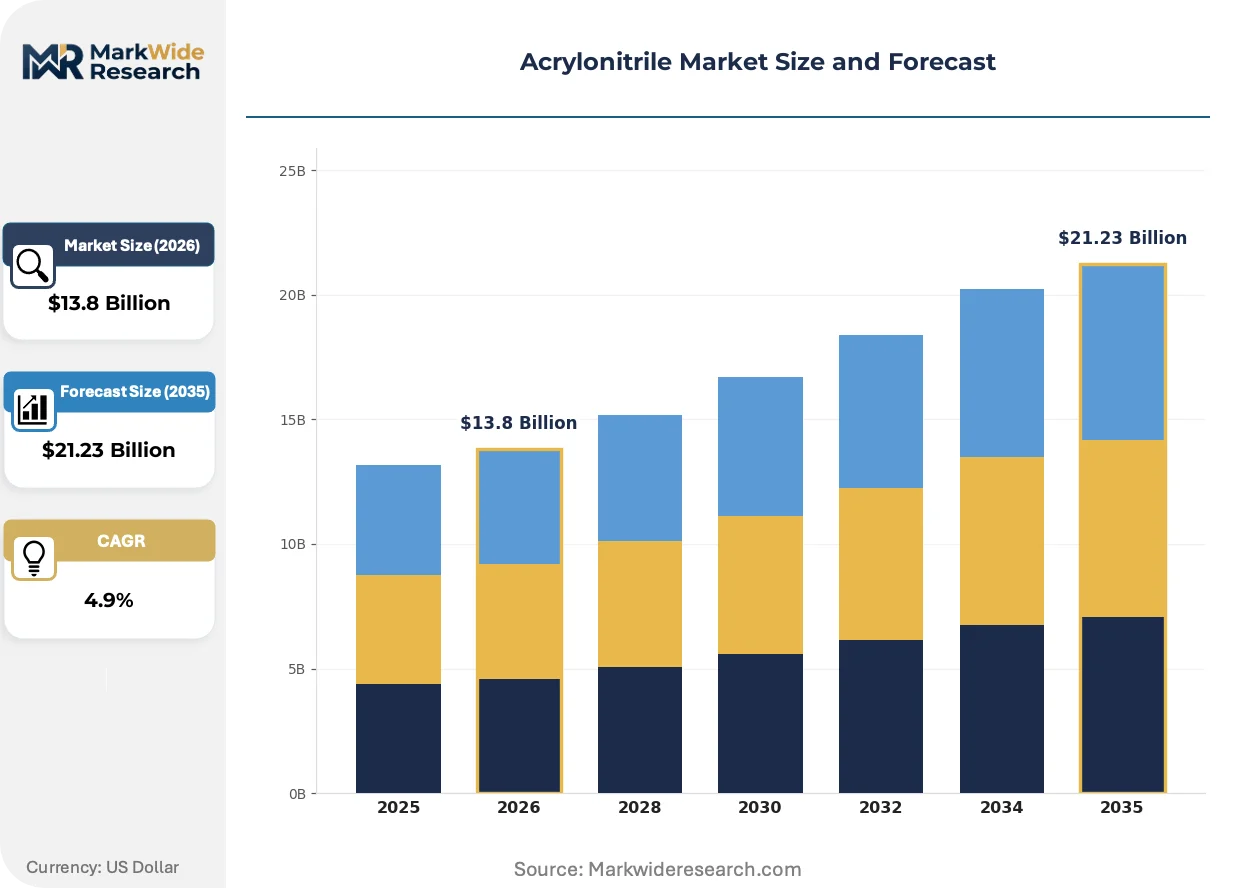
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $21.23 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyacrylonitrile, Acrylic Fiber, ABS Resin, Nitrile Rubber End Use Industry: Textiles, Automotive, Construction, Consumer Goods Application: Filtration, Coating, Adhesives, Packaging Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | PetroChina Company Limited, Formosa Plastics Corporation, INEOS Group Limited, Sumitomo Chemical Co., Ltd., AnQore BV, Asahi Kasei Corporation, China Petrochemical Corporation, SABIC, Ascend Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylonitrile Market Strategic Shifts & Innovations
Process intensification and digital control systems are reshaping acrylonitrile manufacturing economics, while regulatory chemistry restrictions and downstream specification tightening are redefining competitive qualification requirements.
Advanced process control using real-time reactor analytics is digitizing yield optimization in propylene-ammonia oxidation units. SABIC and INEOS have deployed machine-learning models that adjust catalyst bed temperatures within seconds of deviation detection. This capability is digitizing margin capture that previously required manual laboratory intervention and hours of response lag.
EU REACH substance restriction proposals are tightening acrylonitrile handling protocols for worker exposure and environmental release. The ECHA authorization list expansion is forcing derivative manufacturers to document safer-use alternatives or secure time-limited exemptions. Specialty carbon fiber precursor producers face the steepest compliance burden given aerospace customer ESG audit requirements.
Direct mill-to-polymer-plant contracting is displacing merchant spot trading for acrylonitrile offtake. ABS compounders in Germany and Japan are negotiating five-year supply agreements with propylene-integrated producers, locking volume and quality specifications. This pattern concentrates procurement leverage with automotive tier-one suppliers while marginalizing independent distributors.
Acrylonitrile Market Segmentation
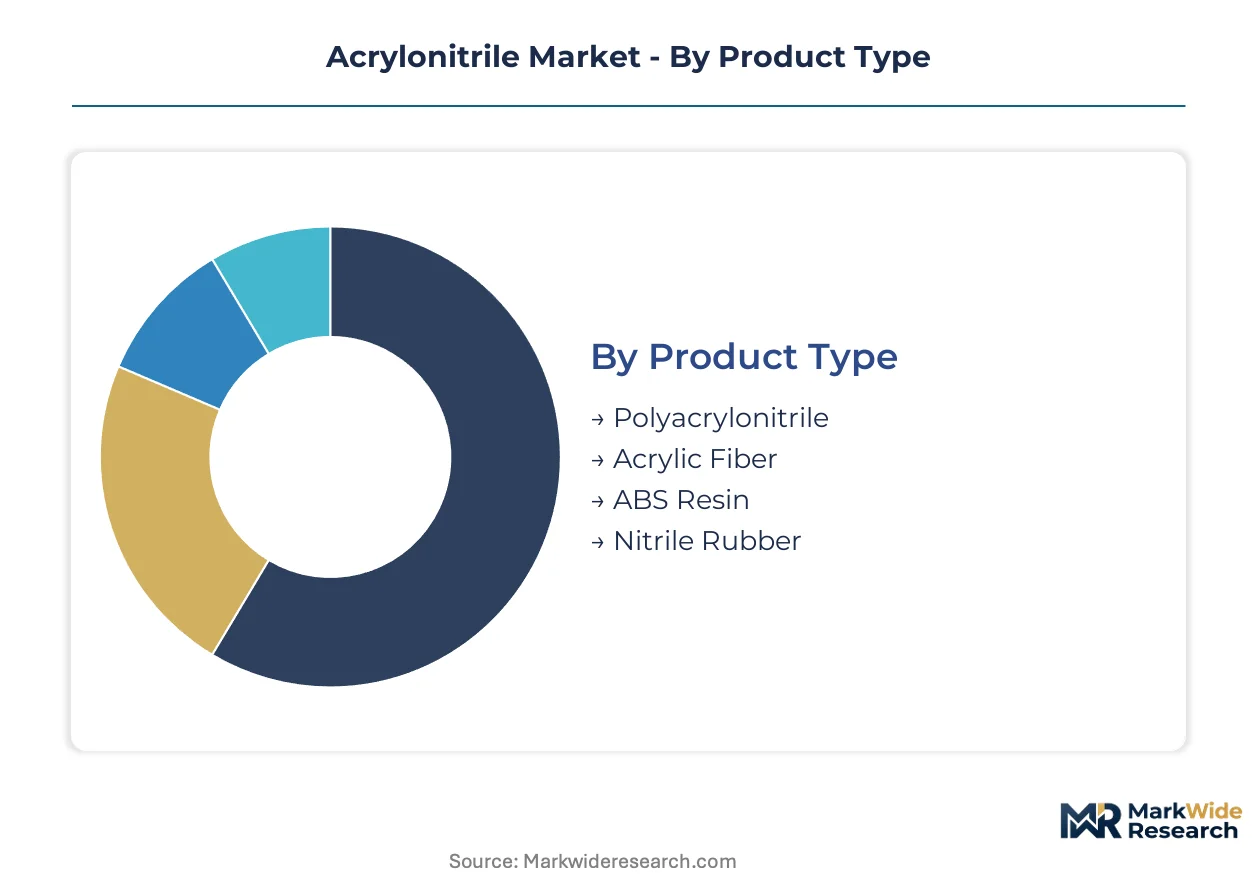
Acrylonitrile derivatives demand radically different technical support intensity across value chains. Carbon fiber precursor qualification requires multi-year aerospace certification support, while textile acrylic fiber operates on spot-market logistics with minimal service overlay.
Product Type:
After-sales service intensity varies dramatically by product chemistry, with aerospace-grade precursors demanding continuous technical partnership and commodity fibers requiring minimal post-sale engagement.
- Polyacrylonitrile:High-purity precursor polymer for carbon fiber manufacturing with stringent molecular weight distribution controls. Demand concentrates in Germany and Japan where aerospace OEMs and wind turbine blade fabricators qualify suppliers through multi-year certification protocols. Aerospace OEMs enforce ESG audit requirements that elevate compliance burdens for specialty producers.
- ABS Resin:Terpolymer of acrylonitrile, butadiene, and styrene delivering impact resistance and moldability for engineered plastics. Automotive lightweighting programs in Germany and Japan specify high-impact grades for battery housings under NHTSA fuel economy standards and EU CO2 fleet targets.
- Acrylic Fiber:Synthetic textile staple and filament facing polyester substitution pressure in apparel applications.
- Nitrile Rubber:Oil-resistant elastomer for seals, gaskets, and industrial hose applications.
ABS Resin holds the largest share; momentum sits with Polyacrylonitrile.
End Use Industry:
Application maturity determines margin architecture, with established sectors trading volume against price and emerging segments offering specification premiums.
- Automotive:Primary demand driver for ABS resin in interior trim, exterior panels, and battery enclosures. German and Japanese OEMs anchor consumption through tier-one compounder relationships.
- Textiles:Acrylic fiber penetration in outdoor fabrics and industrial applications where weather resistance justifies cost premiums over polyester alternatives.
- Construction:Adhesives, sealants, and modified concrete additives utilizing nitrile rubber and specialty acrylonitrile derivatives.
- Consumer Goods:Electronics housings, appliance components, and packaging films leveraging ABS impact properties and processability.
Automotive commands the dominant volume position; construction applications are climbing the fastest.
Application:
Functional performance requirements stratify procurement relationships, with specification-tight applications securing dedicated supply agreements.
- Filtration:Electrospun nanofiber membranes and industrial filter media requiring controlled fiber diameter distributions.
- Coating:Protective and decorative finishes for automotive, marine, and industrial substrates demanding weatherability and chemical resistance.
- Adhesives:Structural and pressure-sensitive formulations utilizing nitrile rubber tack and solvent resistance properties.
- Packaging:Barrier films and thermoformed containers leveraging ABS clarity and processability for consumer goods protection.
Coating applications hold the largest share; filtration represents the steepest expansion trajectory.
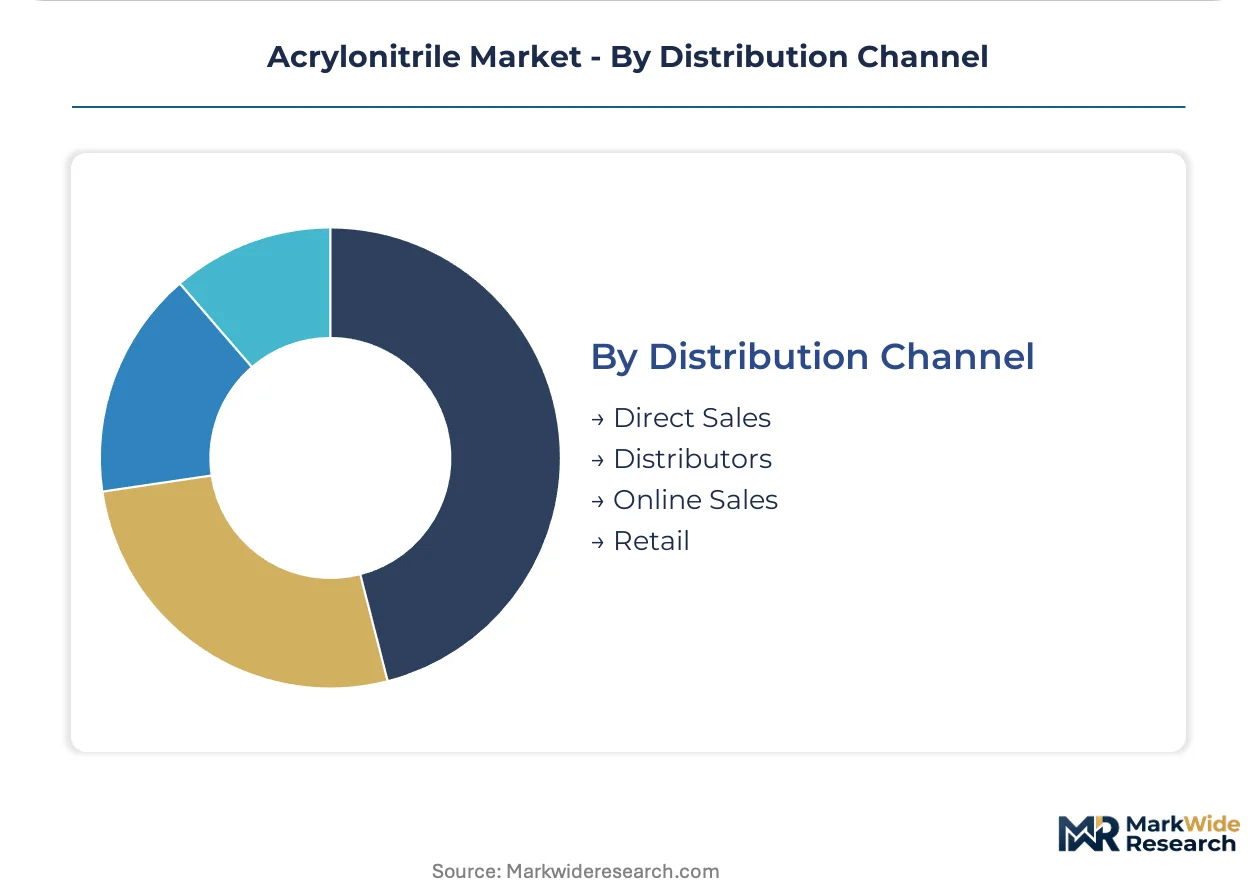
Distribution Channel:
Channel economics reflect buyer scale and specification complexity, with integrated producers capturing direct relationships from large compounders.
- Direct Sales:Mill-to-polymer-plant contracting dominates ABS offtake as German and Japanese compounders negotiate five-year supply agreements locking volume and quality specifications with propylene-integrated producers.
- Distributors:Merchant spot trading persists for small-batch textile acrylic fiber and specialty nitrile rubber grades where buyers lack storage infrastructure.
- Online Sales:Emerging channel for standard-grade raw materials among mid-scale processors seeking price transparency.
- Retail:Minimal penetration limited to laboratory reagents and small-volume specialty chemicals.
Direct Sales holds the largest share; momentum is concentrating with Distributors serving fragmented downstream processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene-integrated producers in China extract feedstock cost advantages that compress margins for merchant operators in Europe and North America. This pricing-power asymmetry is reshaping trade flows as Asian coastal clusters capture exportable surplus. Regional regulatory divergence around carbon intensity and chemical handling protocols is layering compliance premiums onto delivered costs.
China
ABS resin demand from electric vehicle battery housing programs and wind turbine blade manufacturing is concentrating derivative consumption. MEE enforces dual carbon targets that elevate energy efficiency mandates for coal-based acrylonitrile plants. Ningbo and Shanghai petrochemical clusters control exportable surplus, exposing international buyers to single-geography disruption risk.
Germany
Automotive OEMs specify high-impact ABS grades for interior trim and exterior panels under EU CO2 fleet targets. ECHA REACH substance authorization protocols consolidate supply among pre-registered producers, creating qualified-supplier premiums. The Rhine-Ruhr industrial corridor hosts propylene-integrated complexes that leverage pipeline networks for cost-advantaged ammonia sourcing.
United States
Gulf Coast steam crackers supply captive propylene to acrylonitrile units serving ABS compounders for appliance and electronics housing. EPA emissions standards constrain propylene-ammonia process configurations and waste handling protocols. Texas and Louisiana chemical clusters benefit from ethane feedstock flexibility that stabilizes oxidation economics against naphtha volatility.
Japan
Carbon fiber precursor qualification for aerospace OEMs and wind turbine manufacturers is driving polyacrylonitrile specification tightening. METI industrial policy supports advanced materials supply chain security through domestic production mandates. The Chubu region around Nagoya anchors carbon fiber composite manufacturing that pulls high-purity acrylonitrile through qualified supply relationships.
India
PLI scheme incentives for advanced materials are attracting acrylonitrile derivative investments in Gujarat and Maharashtra industrial corridors. BIS standards for automotive plastics are elevating quality specifications for imported ABS resin. The Dahej and Mundra port zones concentrate petrochemical infrastructure that enables import substitution for textile and engineering polymer applications.
Acrylonitrile Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream capturing specification premiums in carbon fiber precursor and high-purity grades. The producer base concentrates around propylene-integrated petrochemical complexes with three to four scale players anchoring regional supply. Strategic archetypes include feedstock-backward integrators, specialty-grade purists, and merchant-market survivors. Dominant competitive moves involve multi-year direct contracting with automotive tier-one compounders and catalyst technology licensing arrangements.
Among Asian state-affiliated energy majors, PetroChina Company Limited and China Petrochemical Corporation occupy positions that exemplify feedstock-integrated scale advantage. INEOS Group Limited represents the European petrochemical integration archetype sustaining cost-advantaged ammonia sourcing through pipeline networks. Asahi Kasei Corporation sits within the specialty-grade purist tier, differentiating beyond commodity acrylic fiber markets through carbon fiber precursor qualification protocols.
| Leading Market Players |
|---|
| PetroChina Company Limited |
| Formosa Plastics Corporation |
| INEOS Group Limited |
| Sumitomo Chemical Co., Ltd. |
| AnQore BV |
| Asahi Kasei Corporation |
| China Petrochemical Corporation |
| SABIC |
| Ascend Performance Materials |
| Others |
Cost & Logistics Intelligence
Single-geography concentration around Ningbo and Shanghai petrochemical clusters exposes international buyers to disruption risk that widens contract-versus-spot pricing spreads and forces inventory-holding strategies across multiple supply nodes. Propylene feedstock volatility transmits directly into acrylonitrile margin compression, compelling merchant producers to absorb cost swings while integrated operators capture tier premiums through captive supply security.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock volume and quality specifications with propylene-integrated producers in Germany and Japan. Price differentiation hinges on carbon fiber precursor certification grade and volume scale, with aerospace-qualified PAN commanding substantial premiums over textile-grade material. Cost compression in commodity acrylic fiber is intensifying because polyester substitution erodes apparel demand, squeezing margins for non-integrated producers. Small-batch textile processors exhibit highest price sensitivity, while automotive tier-one compounders prioritize supply security over unit cost.
Supply Chain Analysis
Export-control regimes on bismuth-molybdenum oxide catalyst technology limit process optimization flexibility and concentrate licensing leverage with two technology providers. Manufacturing gravity centers on China, Germany, and the United States, with coastal petrochemical clusters controlling exportable surplus. Production draws from propylene, ammonia, and specialized catalyst formulations, with feedstock shifts between naphtha and ethane destabilizing oxidation economics. Single-source vulnerability from China's coastal concentration exposes buyers to MEE emissions enforcement disruptions. Distribution runs through direct mill-to-polymer-plant contracting for ABS offtake, marginalizing merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acrylonitrile markets are cycling through a recovery phase as automotive lightweighting programs and carbon fiber precursor qualification timelines restock downstream inventory positions. Propylene-ammonia process margin compression has forced capacity discipline that sets conditions for pricing power restoration as demand firms.
For Market Incumbents: Pre-empt polyester substitution threats in textile applications by accelerating high-purity PAN capacity for aerospace and wind turbine qualification pipelines. Deepen backward integration into propylene feedstock through pipeline network access in the Rhine-Ruhr and Gulf Coast corridors. Secure catalyst technology licensing arrangements to defend process optimization flexibility against technology licensor concentration.
For New Entrants and Emerging Players: India's chemical specialization corridors in Gujarat and Maharashtra offer underpenetrated entry points where PLI scheme incentives offset capital intensity barriers. Target carbon fiber precursor qualification support services as the most penetrable segment, where multi-year aerospace certification protocols create sticky supplier relationships. Pursue joint venture structures with state-affiliated energy majors to secure propylene feedstock access without balance sheet-heavy cracking investments.
For Investors and Strategic Acquirers: EU REACH substance authorization expansion reshapes the acquisition landscape by consolidating supply among pre-registered producers and creating qualified-supplier premiums. Long-term viability favors specialty-grade purists with carbon fiber precursor qualification protocols over commodity acrylic fiber exposure. Watch MEE emissions trading credit generation rates as the signal for coal-based plant competitiveness inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Captive feedstock access from Gulf Coast steam crackers stabilizes oxidation economics against naphtha volatility. |
| Carbon Fiber Precursor Qualification | Multi-year aerospace certification with Boeing and Airbus creates specification-tight supply relationships. |
| Long-term Supply Agreement | Five-year direct contracting with German and Japanese automotive tier-one compounders locks volume commitments. |
| Green Manufacturing Transition | MEE emissions trading credit generation ahead of compliance deadlines improves coal-based plant economics. |
| Joint Venture | Partnerships with Indian state-affiliated energy majors leverage PLI scheme incentives for derivative investments. |
Research Approach
A spread of perspectives from plant operations managers, procurement leads at ABS compounders, carbon fiber precursor technical directors, and distribution channel partners converged on the working assumptions underpinning demand forecasts. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from petrochemical majors. Bottom-up capacity and utilization estimates triangulated against top-down end-use consumption models across automotive, aerospace, and textile value chains.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by product grade tier, end-use industry concentration, and regional production hub configuration. CAGRs were derived from fitted growth curves against historical propylene-ammonia process economics and carbon fiber precursor qualification timelines. Forecast inputs incorporated automotive lightweighting program specifications, wind turbine blade manufacturing pull-through rates, and MEE dual carbon enforcement intensity assumptions.
Macroeconomic conditions sit as an overlay; deviation in propylene feedstock pricing, EU REACH authorization timelines, or aerospace OEM build rates would shift the trajectory. Forecasts reflect documented assumptions about catalyst technology licensing availability and emissions credit market liquidity. Material shifts in China's petrochemical export policy or carbon fiber precursor qualification protocol changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Organic Rheological Modifiers Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Triethylene Glycol Market
Organic Chemicals
Global Metal-Organic Framework Market
Organic Chemicals
Global Carboxylic Acid Market
Organic Chemicals
Organic Binders Market
Organic Chemicals
North America Phenol Market
Organic Chemicals
Phenol Market
Organic Chemicals
Acrylic Acid Market
Organic Chemicals
Terephthalic Aldehyde Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Organic Matting Agent Market
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Dioctyl Maleate (DOM) Market
Organic Chemicals
Oxo Chemicals Market