
 Vinyl Acetate Homopolymer Market | 2026-2036
Vinyl Acetate Homopolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Vinyl Acetate Homopolymer Market Intelligence
New capacity additions in China's specialty chemical sector are recalibrating supply dynamics for vinyl acetate homopolymer producers. Celanese Corporation leverages its extensive manufacturing scale to maintain cost leadership in commodity grades for the construction industry. Wacker Chemie AG specializes in high-performance dispersions for demanding automotive and industrial coating applications. Kuraray Co. Ltd. differentiates its offerings through a portfolio of advanced polymers tailored for the food-contact packaging industry.
Vinyl acetate homopolymer is a thermoplastic polymer created through the polymerization of the vinyl acetate monomer in an emulsion or solution process. It is characterized by strong adhesive properties and excellent film-forming capabilities when dispersed in water. The material serves as a foundational component for a wide range of water-based adhesives, paints, and coatings. Emulsion product types dominate the market, while the adhesives application, particularly for paper and board, remains the primary volume driver.
Regulations from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) steer the market toward low-VOC formulations. These standards, often mirrored by China's Ministry of Ecology and Environment (MEE), restrict solvent-based alternatives in consumer and industrial products like paints and textiles. Consequently, material selection decisions for manufacturers increasingly balance performance attributes with evolving environmental compliance mandates across key global export destinations.
Market Dynamics
Regulatory mandates for lower volatile organic compound (VOC) content are the central force shaping the vinyl acetate homopolymer market. This pressure, originating from agencies like the EPA and ECHA, dictates formulation strategies and material selection across end-use industries.
Growth Catalysts
- Regulatory Push for Water-Based Systems:Regulations like the EU's REACH framework actively discourage solvent-based products, accelerating the switch to water-based vinyl acetate homopolymer emulsions in paints and adhesives.
- Packaging Industry Expansion:Demand for paper and board packaging, especially for food-contact applications, drives volume growth for adhesives that offer strong, reliable, and compliant bonding solutions.
- Construction in Emerging Economies:Infrastructure and housing projects in countries like India require large volumes of adhesives for applications such as woodworking, flooring, and tiling, creating sustained demand.
Market Restraints
- Feedstock Price Volatility:The market is sensitive to price fluctuations of the primary raw material, vinyl acetate monomer (VAM), which is derived from petrochemical feedstocks and impacts production costs.
- Substitution from Copolymers:In applications requiring greater flexibility or water resistance, ethylene-vinyl acetate (EVA) and other copolymers present a significant substitution threat to standard homopolymers.
- Supply Chain Concentration:Heavy reliance on new capacity additions in China creates potential risks related to geopolitical tensions, trade policy shifts, and regional supply-demand imbalances for global buyers.
Strategic Opportunities
- Bio-Based Formulations:Developing homopolymers from bio-renewable feedstocks presents a significant opportunity to capture demand from brands seeking to improve the sustainability profile of their products.
- Textile and Non-Woven Binders:There is an opportunity to expand the use of specialized vinyl acetate homopolymer emulsions as formaldehyde-free binders in textile finishing and non-woven fabric production.
- Penetration in Latin America:The growing construction and packaging sectors in countries such as Brazil represent an underpenetrated market for high-performance, water-based adhesives and coatings.
Industry Challenges
- Navigating Global Food-Contact Laws:Ensuring a single product formulation complies with the divergent food-contact material regulations of the US FDA, Europe's EFSA, and other national bodies is a complex and costly challenge.
- High Capital Investment:Modernizing or building new emulsion polymerization plants requires significant capital expenditure to meet stringent environmental controls and achieve necessary economies of scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vinyl Acetate Homopolymer Market |
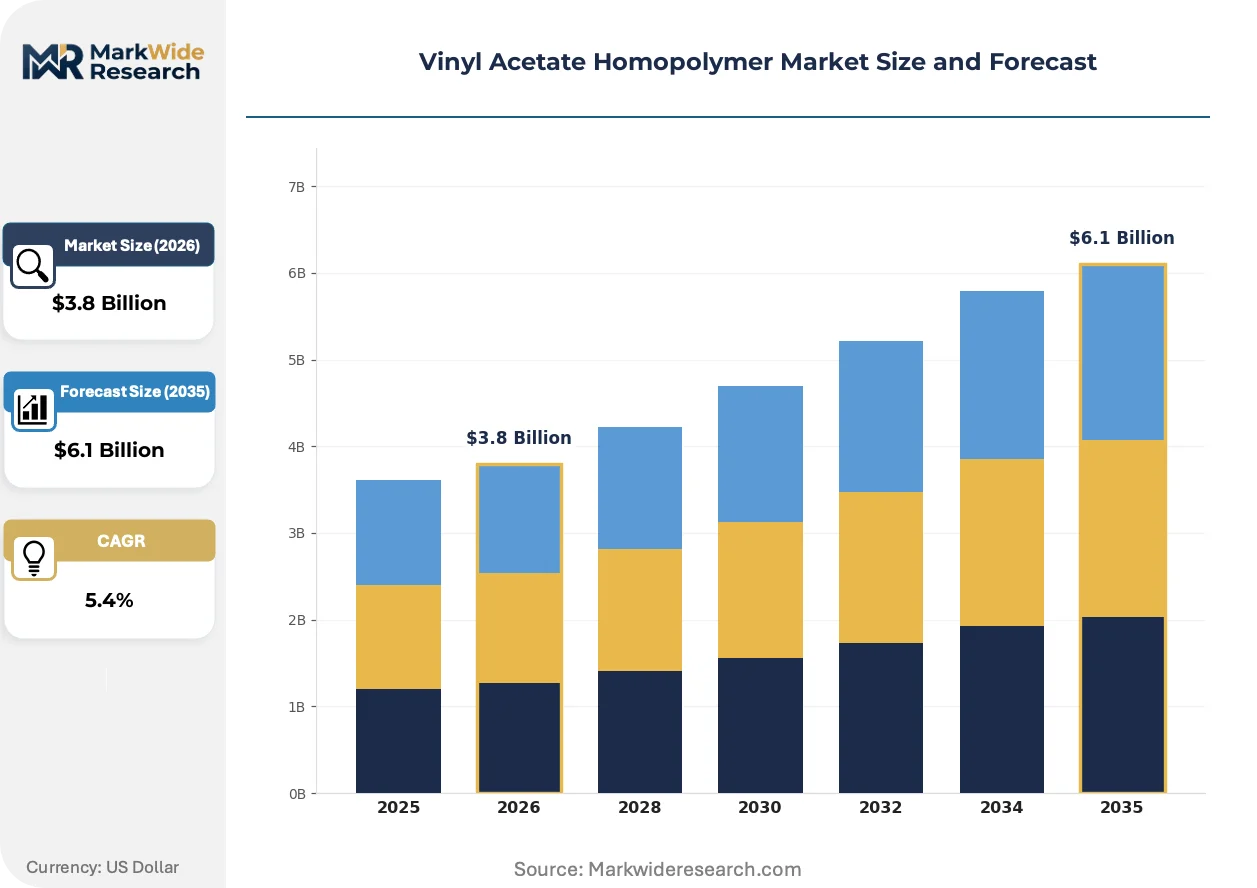
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Dispersion, Powder, Solution Application: Adhesives, Paints, Coatings, Textiles End User: Construction, Automotive, Packaging, Consumer Goods Delivery Mode: Bulk, Bags, Drums, IBCs |
| Companies Covered | LyondellBasell Industries, Arkema, Celanese Corporation, Shin-Etsu Chemical Co. Ltd, Kuraray Co. Ltd, The Dow Chemical Company, Mitsubishi Chemical Corporation, Pexi Chem Private Limited, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vinyl Acetate Homopolymer Market Strategic Shifts & Innovations
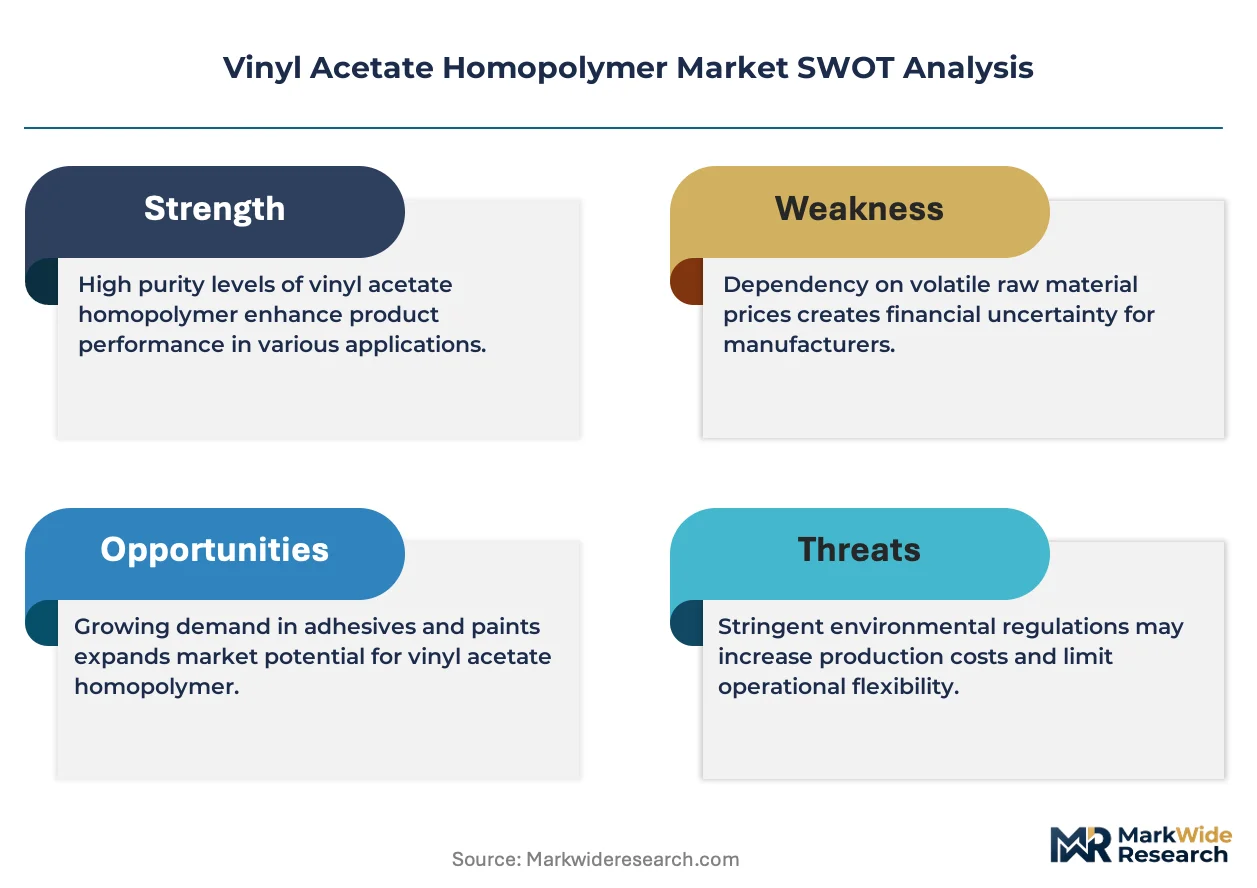
The market's evolution pivots on a dual axis of performance specialization and environmental stewardship. This dynamic compels producers to innovate beyond commodity grades, developing formulations that meet both stringent regulatory standards and sophisticated application-specific requirements.
High-solids, low-VOC emulsion technology provides superior film-forming properties with reduced environmental impact. Paint and coatings formulators are rapidly adopting these advanced systems to comply with stricter air quality standards from regulators like the EPA. This technology is overtaking traditional solvent-based systems in demanding architectural and industrial coating applications.
China's national standards and MEE policies mandating lower VOC content in consumer and industrial goods are reconfiguring Asia's supply chain. This forces a rapid reformulation of adhesives and coatings sold within the world's largest manufacturing hub. The shift particularly affects producers in the furniture and textile sectors, who must transition to compliant water-based systems.
A behavioral shift among consumer-packaged goods companies prioritizes adhesives certified for recyclability and compostability. This disrupts purchasing models based purely on cost and bond strength, creating a preference for suppliers with documented sustainable formulations. The trend is most visible within the food and beverage packaging supply chains across Europe.
Vinyl Acetate Homopolymer Market Segmentation
Understanding the distinct segments within the vinyl acetate homopolymer market reveals specific pockets of demand and strategic opportunities. This granular view helps producers align product development with evolving end-user requirements, from specialized industrial applications to high-volume consumer goods.
Product Type:
The market for vinyl acetate homopolymer product types reflects a continuous upgrade cycle, as formulators seek superior performance and environmental compliance in their adhesive and coating systems.
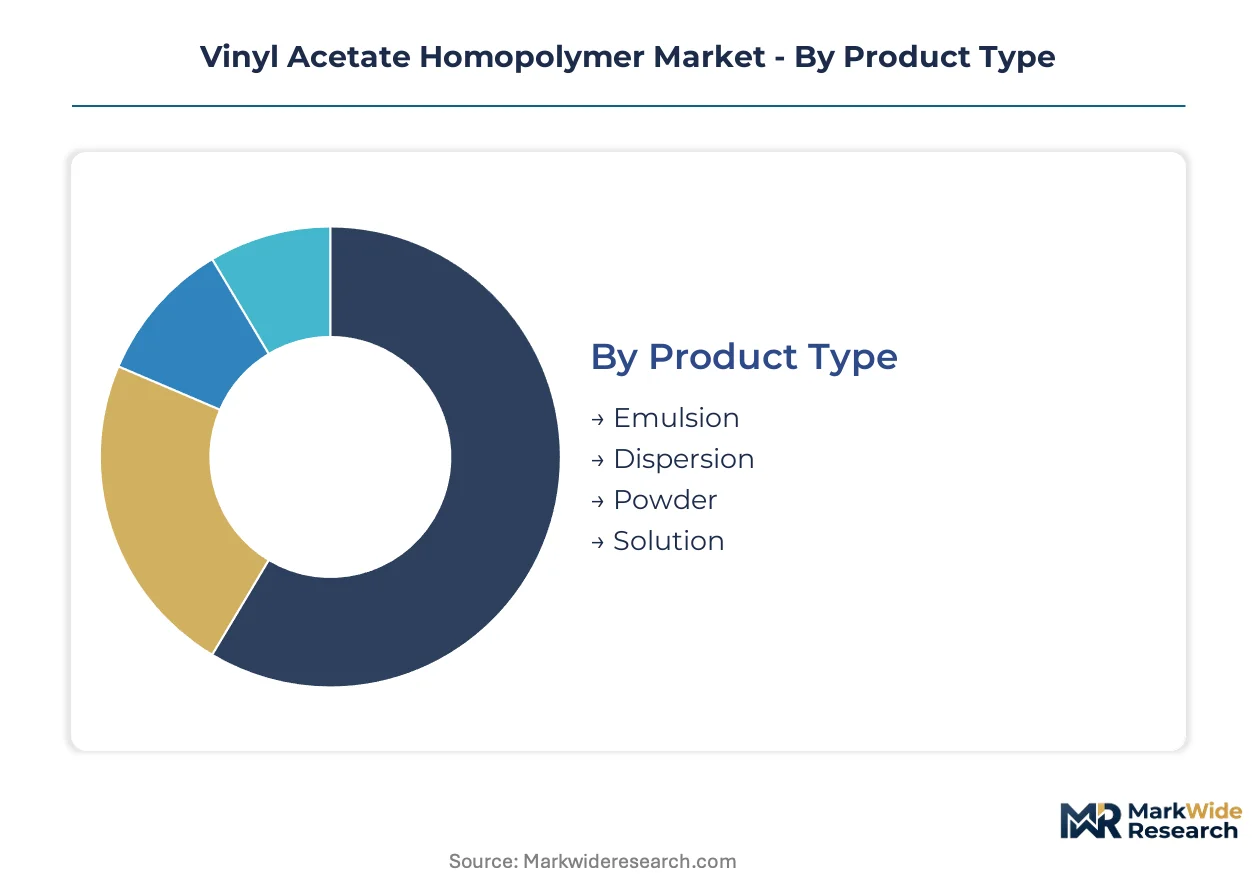
- Emulsion:This product type consists of vinyl acetate homopolymer particles uniformly dispersed in water, forming a stable, milky liquid. Emulsions are foundational for water-based paints, adhesives, and coatings due to their excellent film-forming properties and low VOC content. Demand concentrates in the construction sector across India and China for architectural coatings and wood adhesives.
- Dispersion:Vinyl acetate homopolymer dispersions are characterized by fine polymer particles suspended in a liquid medium, offering enhanced stability and rheological control. These high-performance systems are critical for demanding applications requiring superior adhesion, flexibility, and water resistance, such as automotive and industrial coatings.
- Powder:Vinyl acetate homopolymer powders are redispersible polymers, designed for dry-mix formulations like tile adhesives and cementitious renders.
- Solution:This product type involves vinyl acetate homopolymer dissolved in organic solvents, typically used in niche industrial applications where fast drying or specific solubility is required.
Emulsion sits at the top of the volume ranking, with Dispersion climbing the fastest.
Application:
Volume concentration dictates strategic focus within the vinyl acetate homopolymer application landscape, with certain end-uses driving significant material consumption and innovation.
- Adhesives:Vinyl acetate homopolymers form the backbone of numerous water-based adhesive formulations, providing strong bond strength and film flexibility. This application dominates volume, particularly in packaging (paper and board) and woodworking, driven by e-commerce growth in the US and Europe.
- Paints:In paint formulations, vinyl acetate homopolymers serve as primary binders, contributing to scrub resistance, adhesion, and overall durability of architectural and decorative coatings. Regulatory shifts toward lower VOC content in Germany and France drive adoption.
- Coatings:Industrial and specialty coatings leverage vinyl acetate homopolymer for protective and decorative finishes on various substrates, including textiles and metal.
- Textiles:In the textile industry, these polymers function as binders for non-woven fabrics, sizing agents, and finishes, improving fabric hand and durability.
Adhesives remain the largest application segment, while Paints show substantial expansion.
End User:
Specific end-user industries drive demand for vinyl acetate homopolymer, with their unique requirements shaping product specifications and market growth trajectories.
- Packaging:The packaging industry utilizes vinyl acetate homopolymers extensively in adhesives for paper, board, and flexible packaging, particularly for food-contact applications requiring compliance with FDA and EFSA standards. This sector experiences sustained demand from the consumer goods market in Brazil.
- Construction:The construction sector relies on vinyl acetate homopolymers for various applications, including wood adhesives, tile adhesives, cement modifiers, and architectural coatings. Infrastructure projects in India and China underpin strong demand.
- Automotive:Automotive applications include interior trim adhesives, carpet backing, and specialized coatings, where high performance and durability are paramount.
- Consumer Goods:This broad category encompasses a range of uses, such as binders in disposable hygiene products, craft adhesives, and general-purpose glues.
Packaging represents a significant demand driver, with Construction exhibiting consistent growth.
Delivery Mode:
Efficiency and scale of logistics define the delivery mode segment, influencing procurement strategies and supply chain optimization for vinyl acetate homopolymer products.
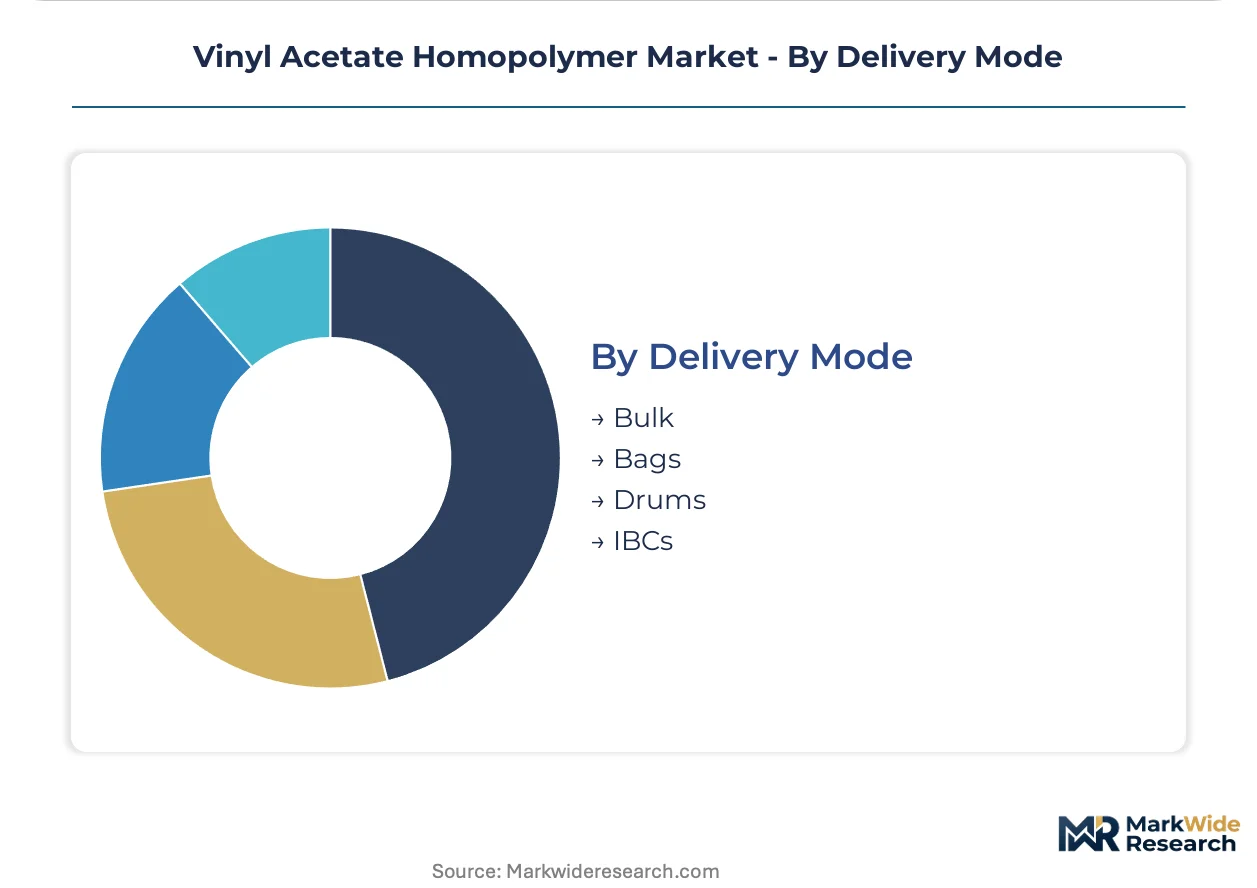
- Bulk:Large-volume customers, typically major manufacturers, prefer bulk delivery via tanker trucks or rail cars for cost efficiency and continuous production processes. This mode is prevalent for commodity grades supplied to large industrial sites in the US Gulf Coast and European chemical hubs.
- IBCs:Intermediate Bulk Containers (IBCs) offer a balance between bulk and smaller packaging, suitable for medium-sized customers requiring significant quantities but without full bulk infrastructure. IBCs are common for specialty grades in the automotive supply chain across Germany.
- Bags:Powdered vinyl acetate homopolymers are commonly supplied in multi-ply bags, allowing for easier handling and storage in dry-mix formulation facilities.
- Drums:Drums are used for smaller volumes of liquid products, offering flexibility for customers with lower consumption or for specialized product variants.
Bulk delivery accounts for the largest share, while IBCs demonstrate expanding utility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's robust manufacturing sector drives significant vinyl acetate homopolymer demand, contrasting with Europe's focus on specialized, low-VOC formulations. Global regulatory pressures for sustainable materials influence market dynamics across all major economies. This material serves critical functions in diverse industries worldwide.
China
China's extensive construction and packaging industries create substantial demand for vinyl acetate homopolymer. The Ministry of Ecology and Environment (MEE) policies mandate lower VOC content, accelerating the shift to water-based systems. Manufacturing hubs in the Yangtze River Delta actively reformulate adhesives and coatings for domestic and export markets.
India
Infrastructure development in India fuels adhesive consumption for woodworking and flooring applications. The Bureau of Indian Standards (BIS) promotes quality and environmental compliance in construction materials. Urban centers like Mumbai and Delhi experience strong demand from ongoing housing and commercial projects.
United States
E-commerce expansion in the United States increases the need for paper and board packaging adhesives. The US Environmental Protection Agency (EPA) drives demand for low-VOC formulations in paints and coatings. Chemical manufacturing clusters along the US Gulf Coast supply large volumes of commodity grades to industrial users.
Germany
Germany's automotive and industrial sectors require high-performance vinyl acetate homopolymer dispersions. European Chemicals Agency (ECHA) regulations steer product development towards greener chemistries and safer applications. The Rhine-Main region, with its strong chemical industry, leads innovation in specialized coating solutions.
Brazil
Growing construction activity in Brazil presents an expanding market for water-based adhesives and paints. Brazilian national environmental regulations encourage the adoption of more sustainable building materials. São Paulo's industrial base and consumer goods market drive consistent demand for packaging and construction applications.
Vinyl Acetate Homopolymer Market Key Industry Players
Chinese producers anchor one tier, focusing on commodity grades and large-scale output; European and North American specialists hold another, emphasizing high-performance and sustainable formulations. The market exhibits a tiered structure, with global chemical giants competing on cost and smaller players differentiating through innovation. Strategic archetypes include integrated commodity suppliers, specialty dispersion manufacturers, and niche polymer developers. Dominant competitive moves involve capacity expansion in high-growth regions and portfolio diversification into bio-based materials.
Within the specialty dispersion manufacturing tier, Wacker Chemie AG exemplifies a focus on high-performance formulations for automotive and industrial coatings. Celanese Corporation represents the integrated commodity supplier archetype, leveraging extensive manufacturing scale for cost leadership in construction-grade materials. Kuraray Co. Ltd. differentiates its offerings through advanced polymers tailored for the food-contact packaging industry, showcasing a niche polymer developer approach. These firms illustrate the diverse strategies employed to capture market share across various application segments.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| Arkema |
| Celanese Corporation |
| Shin-Etsu Chemical Co. Ltd |
| Kuraray Co. Ltd |
| The Dow Chemical Company |
| Mitsubishi Chemical Corporation |
| Pexi Chem Private Limited |
| Wacker Chemie AG |
| Others |
Cost & Logistics Intelligence
A clear performance tier divergence, separating commodity grades for construction from high-performance specialty formulations, manifests in distinct pricing models and supply chain configurations. This bifurcation influences how producers manage costs and distribute products to diverse end-user industries.
Pricing Analysis
Distributor margin structures influence the final cost of vinyl acetate homopolymer, particularly for smaller volume buyers. Contract-based long-term offtake agreements typically govern commodity grades, while value-based pricing applies to specialized dispersions. Price differentiation stems from volume scale and critical performance specifications like food-contact compliance. Pricing softness reflects feedstock vinyl acetate monomer (VAM) price volatility, impacting producer margins. The construction sector exhibits the highest price sensitivity, contrasting with the lower sensitivity seen in automotive and food-contact packaging applications.
Supply Chain Analysis
Vinyl acetate homopolymer production relies heavily on vinyl acetate monomer (VAM), which itself draws from petrochemical feedstocks like acetic acid and ethylene. Geographic supply concentration exists in China, the US Gulf Coast, and European chemical hubs like Germany. Geopolitical tensions affecting China's new capacity additions present a structural risk for global buyers. Bulk delivery via tanker trucks or rail cars dominates for large-volume commodity grades, while IBCs and drums serve the specialized dispersion market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU's REACH framework driving significant shifts towards water-based systems and sustainable formulations.
For Market Incumbents: Extend cost leadership in commodity grades by optimizing existing large-scale manufacturing sites. Deepen R&D into bio-based formulations to counter substitution threats from copolymers. Invest in specialized certification processes for high-growth segments like food-contact packaging, leveraging existing channel control. Pursue strategic capacity additions in emerging economies like India to capture sustained infrastructure demand.
For New Entrants and Emerging Players: Digital-first sales channels present an opportunity to target underpenetrated markets for specialized binders. Focus on developing formaldehyde-free binders for the textile and non-woven fabric sectors. Brazil's expanding construction and packaging sectors represent a penetrable segment for high-performance, water-based adhesives. Leverage sustainability certifications and low-VOC compliance as a core go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance demands significant R&D investment and specialized manufacturing capabilities. The long-term viability of vinyl acetate homopolymer remains strong, driven by sustained demand from packaging and construction, amplified by environmental regulations. Target archetype companies include specialty dispersion manufacturers with strong intellectual property in green chemistry. Increased M&A activity in the bio-based materials sector serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Secures supply for India's infrastructure growth and regional market penetration. |
| Green Manufacturing Transition | Aligns production with global environmental mandates and enhances brand reputation. |
| Long-term Supply Agreement for VAM | Mitigates feedstock price volatility and ensures production stability for manufacturers. |
| Portfolio Diversification into Bio-based Materials | Captures demand from brands prioritizing sustainable product formulations. |
| Certification Investment for Food-Contact | Unlocks premium segments and ensures compliance with stringent global regulations. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative modeling — were reconciled to construct a comprehensive market view. This involved engaging R&D directors, procurement managers at packaging firms, construction project leads, and regulatory compliance officers. Secondary data sources included customs/trade data, EPA/ECHA regulatory documents, company financial filings, and industry association reports, triangulated through both bottom-up and top-down approaches.
The analytical framework integrated various data streams into a robust quantitative model across the analysis window. Segmentation dimensions modeled included product type, application, end-user, delivery mode, and regional regulatory compliance. Compound annual growth rates (CAGRs) were derived from historical data analysis and projected market drivers, with raw material price forecasts and construction spending projections serving as key inputs.
The model assumes a particular technology adoption path; alternative pathways for advanced polymer development would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement and technological advancements. Geopolitical shifts or unforeseen feedstock disruptions could alter the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Middle-East and Africa Fluoropolymers Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
Hydrocarbon Resins Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market