
 China Geopolymer Market | 2026-2036
China Geopolymer Market Size, Share, and Industry Trends Forecast 2026-2036
China Geopolymer Market Intelligence
Ordinary Portland cement is restructuring product economics across China's construction supply chain as geopolymer binders gain cost-competitiveness at scale. SLB anchors its position through deep R&D intensity in oilwell cementing applications where thermal stability requirements favor aluminosilicate chemistry. Milliken & Company differentiates via specialized additive systems that control rheology in fly ash-based formulations. Imerys leverages captive metakaolin reserves to secure upstream control over high-purity feedstock for premium building material grades.
Geopolymers are inorganic aluminosilicate materials formed through alkali-activation of industrial byproducts or natural pozzolans, typically achieving compressive strengths of 20-80 MPa within 24 hours depending on precursor selection and curing regime. Their primary commercial purpose centers on carbon-intensive cement replacement in structural concrete, precast elements, and hazardous waste immobilization matrices. Fly ash-based formulations dominate volume flows due to abundant thermal power plant residue availability, while metakaolin-based grades command premium positioning in fireproof coating applications where superior thermal resistance justifies higher input costs. Slag-based variants are capturing share in road construction as steel mill waste streams align with circular economy mandates.
China's MIIT enforces GB standards governing geopolymer concrete performance benchmarks, while MEE oversight of industrial waste classification directly shapes precursor availability and qualification pathways. The dual carbon goals embed geopolymer adoption within provincial emissions reduction accountability frameworks, creating compliance-driven demand in state-backed infrastructure tenders. Stakeholders must monitor evolving precursor quality consistency, alkali activator price volatility, and the pace of GB standard harmonization with international IEC frameworks to calibrate capacity commitments and formulation investments.
Market Dynamics
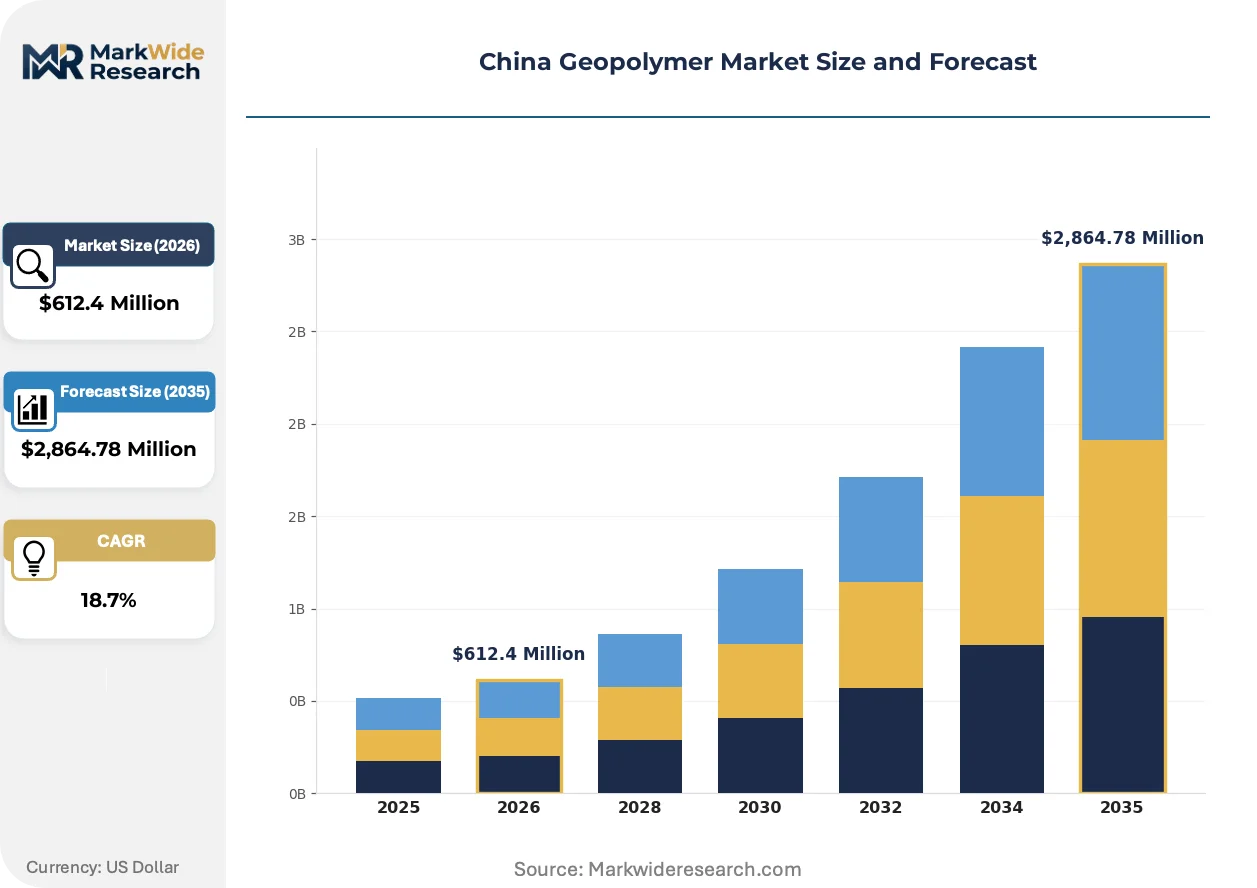
China's dual carbon goals are compressing the cement substitution timeline, forcing municipal infrastructure tenders to specify geopolymer concrete for Yangtze River Delta rehabilitation projects ahead of cost parity with ordinary Portland cement.
Growth Catalysts
- MEE industrial waste classification reforms:Steel mill slag and coal fly ash reclassification as qualified precursors expands feedstock pools for Jiangsu-based producers.
- Municipal road reconstruction mandates:Provincial emissions accountability frameworks in Zhejiang embed geopolymer specifications in state-backed tenders.
- Alkali-activation chemistry advances:Low-calcium fly ash formulations achieve 28-day compressive strengths matching GB standard benchmarks for structural concrete.
Market Restraints
- Sodium hydroxide price volatility:Chlor-alkali plant output fluctuations in Shandong province destabilize activator cost structures for inland formulators.
- Precursor quality inconsistency:Thermal power plant desulfurization retrofits alter fly ash chemistry, requiring batch-specific formulation adjustments.
- GB standard harmonization gaps:Divergent provincial interpretations of MIIT performance benchmarks create compliance friction for multi-province contractors.
Strategic Opportunities
- Fireproof coating applications:Metakaolin-based grades command premium positioning in high-rise building codes across Shanghai and Shenzhen.
- Hazardous waste immobilization:MEE soil remediation tenders in the Pearl River Delta specify geopolymer matrices for heavy metal encapsulation.
- Industrial symbiosis clusters:Steel-construction-material vertical integration in Hebei province enables captive slag-to-binder pipelines.
Industry Challenges
- Alkali-activation expertise scarcity:Formulation chemists with aluminosilicate reaction kinetics training remain concentrated in university research institutes rather than production facilities.
- Curing regime infrastructure gaps:Ambient-temperature strength development requires humidified curing chambers that extend project timelines versus conventional concrete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Geopolymer Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,864.78 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fly Ash-Based, Slag-Based, Metakaolin-Based, Others End User: Construction, Agriculture, Waste Management, Aerospace Application: Building Materials, Soil Stabilization, Road Construction, Fireproof Coatings Technology: 3D Printing, Casting, Injection Molding, Precast Systems |
| Companies Covered | SLB (Schlumberger Limited), Milliken & Company, Betolar Plc, Kiran Global Chems Limited, JSW Cement Limited, Imerys, URETEK, Vortex Companies LLC, MITSUI & CO., LTD., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Geopolymer Market Strategic Shifts & Innovations
Digital twin modeling of geopolymer gel microstructure is compressing formulation development cycles, while alkali-activator blending systems and precursor pre-treatment methods reshape production economics across Chinese manufacturing bases.
Hybrid alkali-activation systems combining sodium silicate and sodium hydroxide is unifying strength development timelines across variable fly ash chemistries. Municipal infrastructure contractors in Jiangsu province are adopting these blended activators for road reconstruction tenders. The technology is unifying procurement specifications that previously required project-specific binder qualifications.
MIIT's evolving GB standards for green building materials are mandating carbon intensity disclosures in state procurement frameworks. Industrial waste-derived binders gain preferential scoring in dual carbon compliance audits. Precast concrete manufacturers in Zhejiang province are restructuring product lines to capture these certification-driven preference shifts.
Specification-led buying patterns now dominate municipal infrastructure procurement, displacing price-first sourcing for structural concrete. Engineering consultants in the Yangtze River Delta are embedding geopolymer clauses in tender documents before contractor engagement. This behavioral shift concentrates demand validation risk with provincial design institutes rather than construction firms.
China Geopolymer Market Segmentation
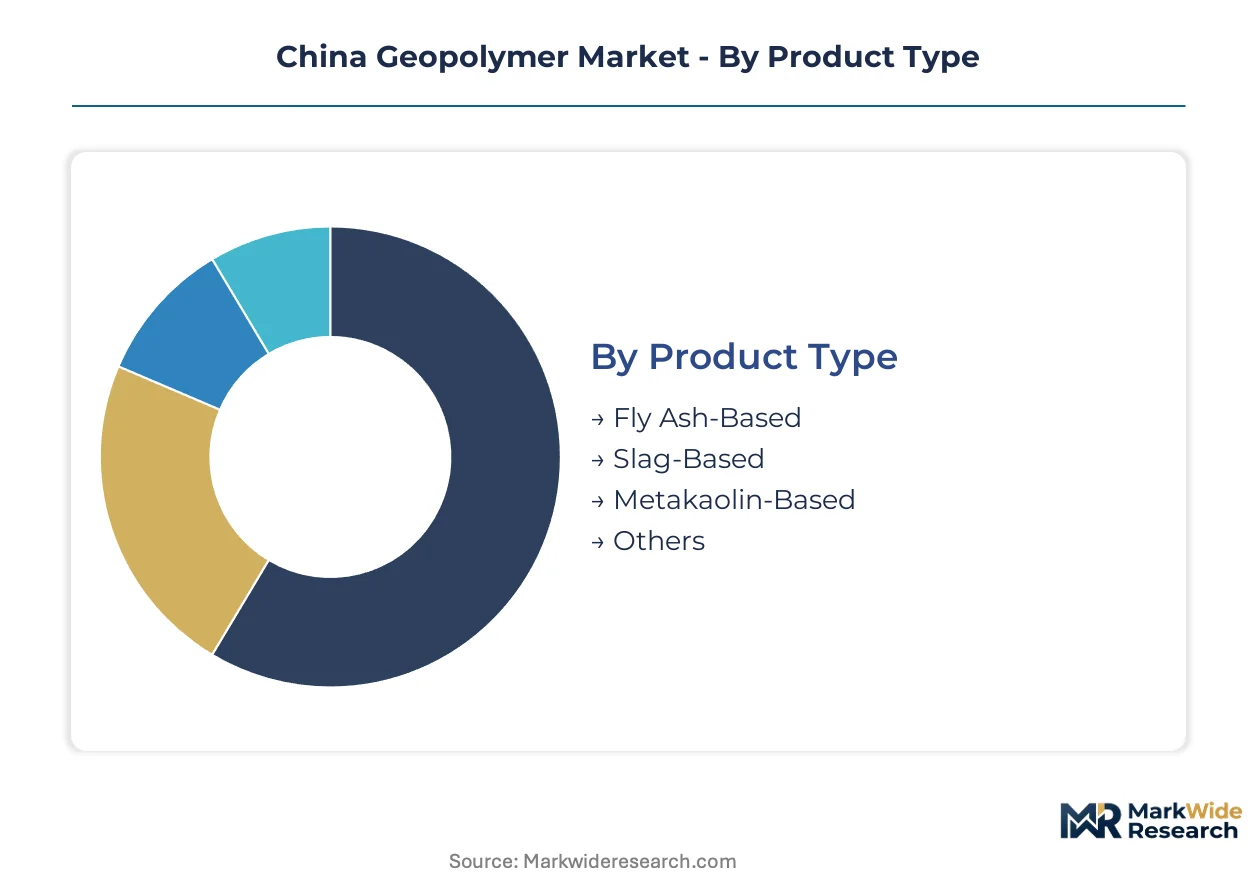
Geopolymer procurement in China stratifies sharply across precursor chemistry, end-use certification requirements, and forming technology. MIIT's evolving GB standards create divergent compliance burdens that reshape segment economics and vendor positioning across the Yangtze River Delta and Pearl River Delta industrial clusters.
Product Type:
GB standard certification intensity varies substantially by precursor source, with fly ash and metakaolin formulations facing distinct MEE qualification pathways for hazardous waste encapsulation versus structural concrete applications.
- Fly Ash-Based:Coal combustion residue activated by sodium silicate-sodium hydroxide blends dominates volume flows across Jiangsu province road reconstruction tenders. Thermal power plant desulfurization retrofits introduce batch chemistry variability that forces formulation recalibration at provincial concrete batching plants.
- Metakaolin-Based:Calcined kaolin clay delivers superior thermal stability exceeding 1000°C, commanding premium positioning in Shanghai high-rise fireproof coating specifications where GB standard fire resistance ratings justify elevated input costs.
- Slag-Based:Steel mill granulated blast furnace slag aligns with Hebei province circular economy mandates for captive industrial symbiosis.
- Others:Rice husk ash and natural pozzolan variants serve niche agricultural and remote construction applications in southwestern China.
Leading the category by volume: Fly Ash-Based. Growing fastest: Metakaolin-Based.
End User:
Customer procurement authority concentrates in state-backed infrastructure tenders versus private industrial contracts, with divergent specification rigor shaping segment margins.
- Construction:Municipal road reconstruction and precast concrete manufacturing absorb the majority of geopolymer volume across Zhejiang province dual carbon compliance frameworks. Provincial emissions accountability mechanisms embed geopolymer clauses in state tender documents before contractor engagement.
- Waste Management:MEE soil remediation tenders in the Pearl River Delta specify geopolymer matrices for heavy metal encapsulation, requiring specialized leaching resistance certification under evolving GB standards for hazardous waste immobilization.
- Agriculture:Low-strength formulations stabilize irrigation canal linings and livestock waste containment in rural Sichuan.
- Aerospace:Thermal protection system prototyping for launch infrastructure remains experimental at CASC facilities.
Construction commands absolute volume dominance. Waste Management climbs fastest on MEE remediation tender expansion.
Application:
Performance specifications diverge sharply between structural load-bearing requirements and protective coating applications, with distinct GB standard test protocols governing each.
- Road Construction:Municipal infrastructure rehabilitation across the Yangtze River Delta specifies geopolymer concrete for pavement overlays and base course stabilization. Zhejiang provincial tenders now mandate carbon intensity disclosures that favor industrial waste-derived binders in compliance scoring.
- Fireproof Coatings:Metakaolin-based spray-applied systems achieve GB standard fire resistance ratings for Shanghai and Shenzhen high-rise building codes, with specification-led buying patterns displacing price-first sourcing.
- Building Materials:Precast wall panels and structural elements gain share in green building certification frameworks.
- Soil Stabilization:Brownfield remediation and soft ground improvement applications concentrate in coastal industrial zones.
Road Construction leads by installed volume. Fireproof Coatings expands most quickly on urban high-rise code tightening.
Technology:
Forming method selection ties directly to project scale economics and curing infrastructure availability, with precast systems benefiting from factory-controlled conditions.
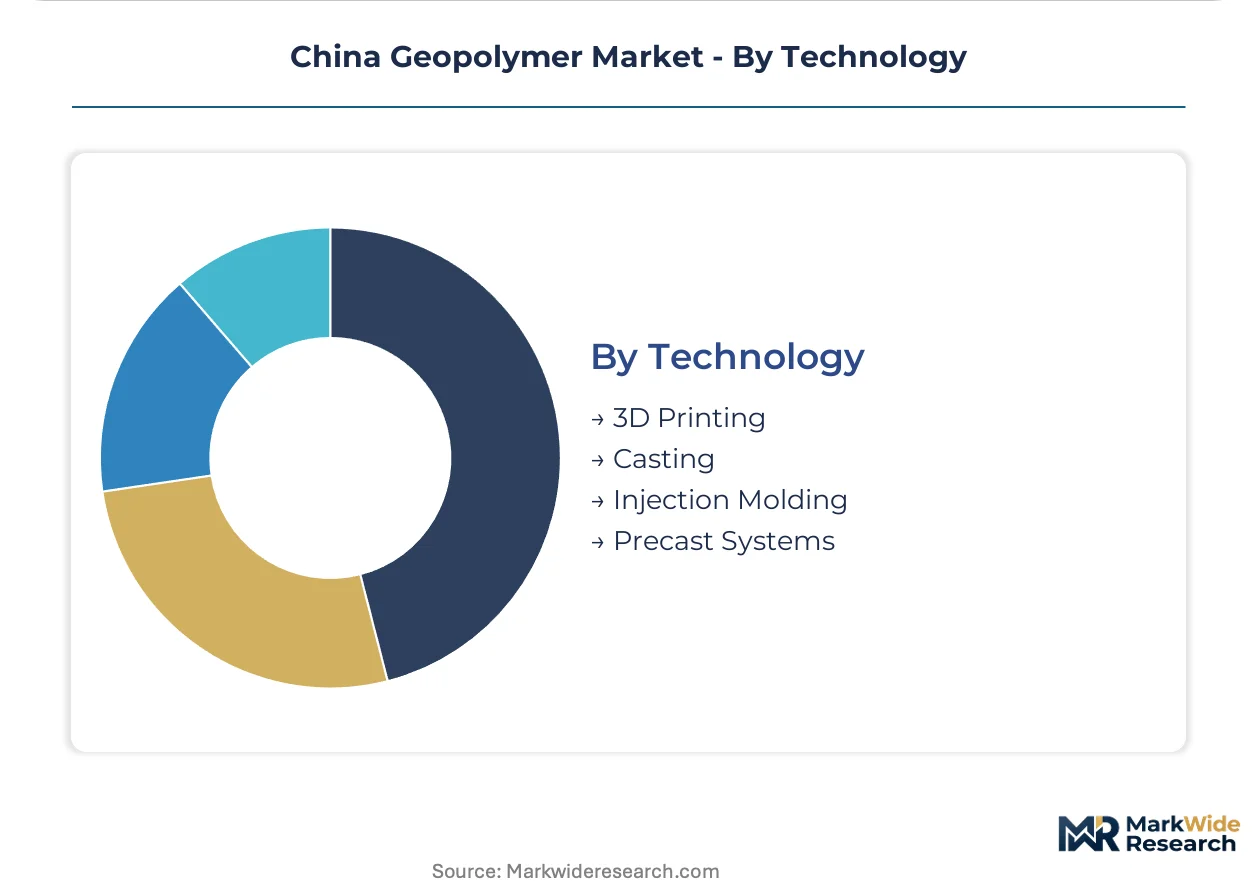
- Precast Systems:Factory-cured beams, panels, and structural elements dominate Zhejiang province manufacturing, where humidified curing chambers overcome ambient-temperature strength development limitations. Digital twin modeling of gel microstructure compresses formulation development cycles for standardized product lines.
- Casting:In-situ pouring for municipal road reconstruction requires mobile batching equipment and on-site alkali-activator storage protocols.
- 3D Printing:Robotic extrusion of geopolymer paste remains pilot-scale for architectural elements in Shenzhen demonstration projects.
- Injection Molding:Limited to small precision components for specialized industrial applications.
Precast Systems dominates current production volume. 3D Printing shows steepest expansion trajectory on construction automation pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's geopolymer demand concentrates in coastal industrial clusters where dual carbon compliance frameworks intersect with abundant precursor waste streams. Provincial emissions accountability mechanisms are reshaping procurement specifications across municipal infrastructure tenders. The analysis examines five sub-regional markets driving volume absorption.
Yangtze River Delta
Jiangsu and Zhejiang provinces anchor geopolymer consumption through municipal road reconstruction and precast concrete manufacturing. MIIT's evolving GB standards for green building materials embed carbon intensity disclosures in state tender documents. Nanjing and Hangzhou batching plants are restructuring supply chains to capture dual carbon compliance scoring advantages.
Pearl River Delta
MEE soil remediation tenders in Guangdong province specify geopolymer matrices for heavy metal encapsulation in brownfield rehabilitation projects. Shenzhen high-rise building codes are tightening fire resistance requirements that favor metakaolin-based coating applications. Guangzhou municipal authorities are piloting geopolymer pavement overlays in port infrastructure zones.
Beijing-Tianjin-Hebei
Hebei province's steel-construction-material vertical integration enables captive slag-to-binder pipelines aligned with circular economy mandates. Tianjin industrial symbiosis clusters are consolidating steel mill waste streams for road base stabilization applications. Beijing municipal procurement frameworks are beginning to specify industrial waste-derived binders in green building certification pathways.
Shandong Peninsula
Chlor-alkali plant output fluctuations in Shandong province create sodium hydroxide price volatility that destabilizes activator cost structures for inland formulators. Qingdao precast manufacturers are experimenting with hybrid alkali-activation systems to buffer raw material volatility. Provincial regulators are monitoring GB standard harmonization gaps that create compliance friction for multi-province contractors.
Sichuan-Chongqing
Western China infrastructure rehabilitation projects are absorbing low-strength geopolymer formulations for irrigation canal linings and rural road stabilization. Chongqing municipal authorities are exploring rice husk ash variants for agricultural waste containment applications. Chengdu research institutes are training formulation chemists to address alkali-activation expertise scarcity in production facilities.
China Geopolymer Market Key Industry Players
Capacity expansion dominates the current landscape as producers scale alkali-activation infrastructure to meet compressed cement substitution timelines. The vendor base stratifies across multinational chemical conglomerates, specialized additive suppliers, and captive industrial waste processors. Three archetypes occupy distinct positions: upstream feedstock controllers, formulation technology licensors, and integrated construction material suppliers. M&A activity and strategic partnerships are consolidating precursor supply chains while technology licensing agreements accelerate process standardization.
Among multinational chemical conglomerates, SLB and Imerys exemplify upstream control strategies through captive mineral reserves and specialized aluminosilicate chemistry expertise. Milliken & Company occupies a position within the formulation technology tier, representing additive system specialization that governs rheology in industrial waste-based binders. These three entities anchor the competitive structure while regional Chinese producers and industrial waste processors fill volume-driven segments.
| Leading Market Players |
|---|
| SLB (Schlumberger Limited) |
| Milliken & Company |
| Betolar Plc |
| Kiran Global Chems Limited |
| JSW Cement Limited |
| Imerys |
| URETEK |
| Vortex Companies LLC |
| MITSUI & CO., LTD. |
| Others |
Cost & Logistics Intelligence
Metakaolin-grade premium positioning versus fly ash commodity volumes splits China's geopolymer market into divergent economic strata. MIIT's GB standard certification ladders enforce this bifurcation: high-purity calcined kaolin commands elevated pricing in Shanghai fireproof coating specifications, while thermal power plant residue flows through municipal road tenders at compressed margins. This tier divergence reshapes supply chain investments, with producers either pursuing captive metakaolin reserves or clustering near coal-fired generation assets.
Pricing Analysis
Volume-margins split sharply across precursor chemistry tiers. Fly ash-based formulations dominate transactional flows through Jiangsu provincial batching plants at commodity price points, while metakaolin grades capture certification-driven premiums in high-rise building codes. Price differentiation hinges on GB standard fire resistance ratings and dual carbon compliance scoring. Cost compression in the fly ash tier intensifies as thermal power plant desulfurization retrofits force batch-specific formulation recalibration. Municipal contractors exhibit highest price sensitivity, whereas specification-led buyers in Shanghai and Shenzhen absorb premium positioning for thermal stability.
Supply Chain Analysis
Regional distribution centers in Jiangsu and Zhejiang provinces anchor hub-and-spoke patterns for alkali-activator chemicals and precursor materials. Supply concentrates in coastal industrial clusters where steel mill slag and coal fly ash streams intersect with chlor-alkali plant output. Raw material dependencies include sodium hydroxide from Shandong province, metakaolin from Imerys captive reserves, and granulated blast furnace slag from Hebei steel complexes. Single-source vulnerability runs through Shandong's chlor-alkali corridor, where output fluctuations destabilize activator cost structures. Distribution runs through provincial concrete batching networks and precast manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's geopolymer sector is consolidating around upstream feedstock control and downstream specification authority. Players securing captive precursor pipelines or MIIT certification advantages are compressing margins for asset-light competitors.
For Market Incumbents: Lock in precursor supply security through long-term offtake agreements with Jiangsu and Zhejiang thermal power plants, or backward integration into metakaolin calcination capacity. Defend against emerging slag-based entrants from Hebei steel-construction verticals by accelerating GB standard harmonization investments that raise compliance barriers for multi-province contractors. For New Entrants and Emerging Players: Capture white-space in MEE soil remediation tenders across the Pearl River Delta, where hazardous waste immobilization specifications outpace qualified supplier capacity. Target Chongqing and Chengdu training institute partnerships to address alkali-activation expertise scarcity before establishing production footprints. Lead with hybrid alkali-activation system licensing to bypass formulation development cycles. For Investors and Strategic Acquirers: Re-rating potential sits with captive industrial waste processors given MEE classification reforms expanding qualified precursor pools. Long-term viability favors assets with demonstrated GB standard certification pathways and provincial tender relationships. Monitor MIIT harmonization announcements with international IEC frameworks as inflection signals for multi-province scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive fly ash or metakaolin reserves insulate margins from Shandong chlor-alkali volatility. |
| GB Standard Certification Investment | MIIT compliance scoring unlocks preferential positioning in Zhejiang state-backed tenders. |
| Hybrid Alkali-Activation Licensing | Technology transfer agreements accelerate market entry without proprietary R&D cycles. |
| Industrial Symbiosis Cluster Formation | Hebei steel-to-binder pipelines align with circular economy mandates and reduce logistics costs. |
| Digital Twin Formulation Development | Gel microstructure modeling compresses product development timelines for precast standardization. |
Research Approach
Document review covered MIIT GB standard filings, MEE industrial waste classification protocols, and provincial tender documentation, complemented by interviews with Jiangsu concrete batching plant managers, Zhejiang precast manufacturing technical directors, Hebei steel mill slag processing leads, and Shanghai high-rise engineering consultants. Secondary validation drew from customs trade data, chlor-alkali industry association reports, and construction sector procurement databases. Bottom-up volume estimates from provincial tender awards were triangulated against top-down market sizing from precursor waste stream availability.
Cross-referencing historical procurement patterns against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include precursor chemistry tier, end-use certification requirement, forming technology, and regional emissions accountability framework. CAGRs were derived from trend extrapolation of dual carbon compliance penetration rates and alkali-activation chemistry advancement curves. Industry-specific forecast inputs incorporated thermal power plant desulfurization retrofit schedules and MEE soil remediation tender pipeline visibility.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GB standard harmonization pace, sodium hydroxide price volatility, and precursor quality consistency from coal fleet environmental retrofits. Outputs reflect documented assumptions around MIIT enforcement intensity and provincial dual carbon accountability mechanisms. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Orthophthalic Resins Market