
 Polyetherketoneketone (PEKK) Market | 2026-2036
Polyetherketoneketone (PEKK) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyetherketoneketone (PEKK) Market Analytics
A shift from single-source to multi-source resin procurement is pivoting how aerospace tier suppliers manage PEKK feedstock risk. Arkema S.A. leverages its fluoropolymer heritage to sustain fluorinated PEKK copolymer development. Solvay S.A. anchors European supply through its specialty polymers division in Tavaux, France. Evonik Industries AG differentiates via high-purity medical grades certified for spinal implant applications.
Polyetherketoneketone is a semi-crystalline thermoplastic in the polyaryletherketone family with a melting point near 305°C and a glass transition temperature of approximately 162°C, engineered for load-bearing components requiring chemical resistance and flame retardancy without additives. PEKK powder dominates current volume through laser sintering workflows in aerospace prototyping, while PEKK filament is the fastest-expanding category as fused deposition modeling spreads from tooling to end-use medical implants. Injection molding retains the deepest margin pool in automotive underhood applications where cycle time efficiency offsets higher tooling investment.
FDA 21 CFR 177.2415 governs food-contact PEKK formulations, while EU MDR and REACH constrain monomer residuals and biocompatibility documentation for European medical device markets. The EPA oversees emissions from fluorinated ketone monomer production in the United States. Stakeholders must monitor evolving recyclability mandates under EU Green Deal implementation and assess whether chemical recycling infrastructure for polyaryletherketone waste streams matures ahead of landfill diversion deadlines.
Market Dynamics
Aerospace manufacturers are consolidating their supplier base around resin producers capable of certifying PEKK batches to AS9100 traceability standards, compressing the qualification timeline from 18 months to under 12 months for structural flight hardware.
Growth Catalysts
- Aerospace lightweighting mandates:FAA fuel efficiency targets are accelerating PEKK substitution for metal brackets and ducting in narrow-body aircraft programs. Tier 1 suppliers now specify PEKK for cabin interior components previously molded from PPS.
- EU MDR implant-grade certification:The European Medical Device Regulation is creating a two-tier polymer market where ISO 10993-5 certified PEKK commands premium placement for spinal cages and cranial implants.
- Fluorinated copolymer R&D pipelines:Arkema's fluoropolymer heritage is yielding PEKK variants with enhanced chemical resistance for semiconductor wet process equipment.
Market Restraints
- Fluorinated ketone monomer supply concentration:Over 70 percent of difluorobenzophenone feedstock originates from Chinese specialty chemical producers, exposing European compounders to export license volatility.
- REACH monomer residual limits:ECHA enforcement of 10 ppm residual ketone thresholds in implant-grade PEKK is disqualifying legacy production batches from EU medical device markets.
- PPS price compression:Polyphenylene sulfide producers in South Korea are narrowing the performance-price gap for underhood automotive applications below the threshold that justifies PEKK tooling investment.
Strategic Opportunities
- India medical device manufacturing:CDSCO's phased implementation of Medical Device Rules 2017 is attracting PEKK compounders to Ahmedabad and Hyderabad clusters for export-oriented spinal implant production.
- Chemical recycling infrastructure:EU Green Deal landfill diversion deadlines for thermoplastic waste are incentivizing pyrolysis partnerships that could recover ketone monomers from aerospace scrap.
- PEKK-CF tape placement automation:Convergence of automated fiber placement robotics with in-situ consolidation is opening continuous fiber-reinforced PEKK for wing spar applications beyond current compression molding limits.
Industry Challenges
- Polymer processing specialist scarcity:Aerospace tier suppliers report 14-month lead times for hiring technicians proficient in laser sintering parameter optimization for PEKK powder bed fusion.
- AS9100D certification backlog:Resin producers face 8-month queue times for aerospace quality management audits, delaying customer qualification programs.
- Implant-grade batch consistency:Medical device OEMs are rejecting PEKK lots with crystallinity variation exceeding 3 percent, forcing compounders to install inline DSC monitoring at €2.4 million per extrusion line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyetherketoneketone (PEKK) Market |
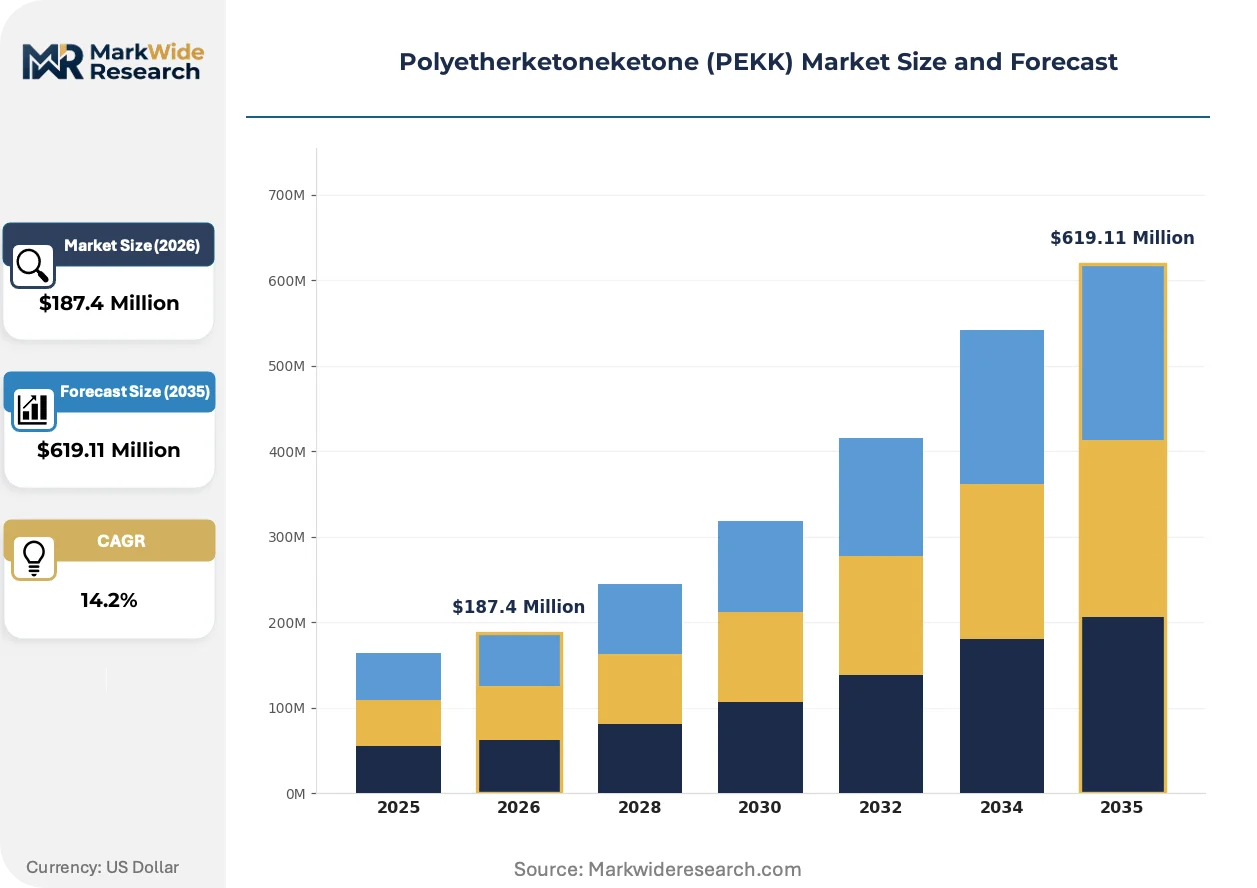
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEKK Powder, PEKK Filament, PEKK Granules, PEKK Film Application: Aerospace, Automotive, Medical Devices, Industrial Components Technology: 3D Printing, Injection Molding, Compression Molding, Extrusion End User: Aerospace Manufacturers, Medical Institutions, Automotive OEMs, Electronics |
| Companies Covered | SABIC, Oxford Performance Materials Inc., Arkema S.A., Ensinger GmbH, RTP Company, Solvay S.A., Evonik Industries AG, Shandong Kaisheng New Materials Co., Ltd., Victrex plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyetherketoneketone (PEKK) Market Evolving Landscape
PEKK manufacturing is bifurcating into high-throughput powder production for additive manufacturing and ultra-purity filament extrusion for load-bearing implants, with process control technologies becoming the primary competitive differentiator.
Non-fluorinated PEKK copolymers are rewriting material selection criteria for semiconductor fab equipment. These formulations eliminate perfluorinated substance content while maintaining etch chamber plasma resistance. Lam Research and Applied Materials are qualifying non-fluorinated grades for 3nm node wafer processing tools. The shift is compressing the addressable market for legacy fluorinated PEEK formulations in high-purity fluid handling.
REACH Annex XIV authorization requirements for diphenyl ether derivatives are forcing reformulation of standard PEKK grades sold into European markets. Compounders must submit substitution plans for process aids previously exempt under intermediate use derogations. Medical device producers in Germany and Switzerland are accelerating inventory builds ahead of 2026 sunset dates for legacy additive packages.
Hospital procurement consortia are consolidating polymer sourcing for spinal implant programs around single-resin platforms. Three US group purchasing organizations now mandate PEKK for all new cage submissions, displacing PEEK-OPTIMA in volume tenders. The concentration is visible in Midwest orthopedic clusters where Zimmer Biomet and Stryker coordinate resin qualification timelines.
Polyetherketoneketone (PEKK) Market Segmentation
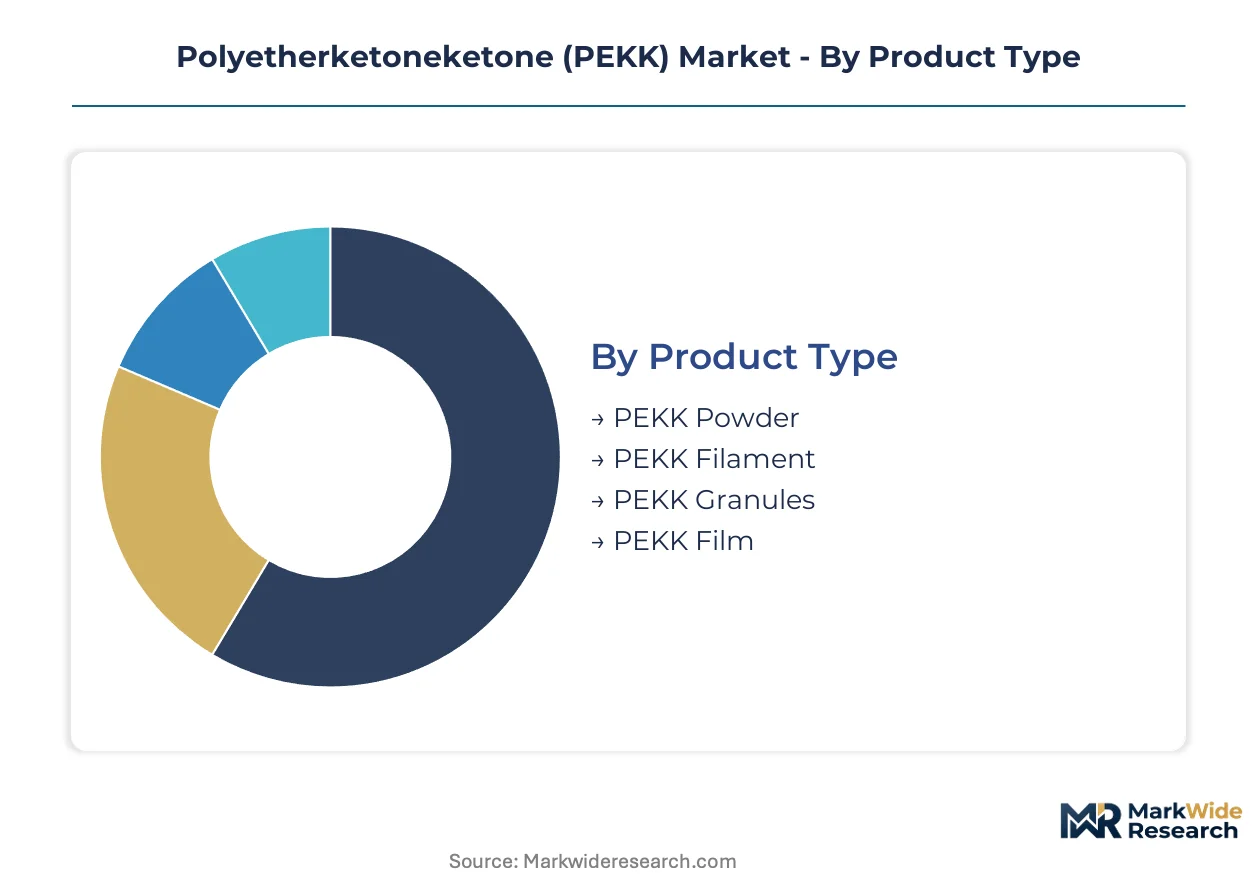
PEKK's semi-crystalline morphology and 305°C melting point create divergent processing requirements across product formats. Each segment demands distinct thermal management protocols, driving equipment specialization and certification fragmentation among compounders.
Product Type:
Particle geometry and thermal history dictate which conversion technology each format serves, with aerospace and medical end-uses imposing incompatible purity specifications.
- PEKK Powder:Spherical morphology optimized for laser sintering bed fusion achieves layer thickness below 100 microns. Demand concentrates in aerospace prototyping workflows around Toulouse and Wichita, where AS9100 traceability requirements favor qualified powder suppliers over filament alternatives.
- PEKK Filament:Diameter-controlled extrusion for fused deposition modeling enables patient-specific medical implants without tooling investment. Spinal cage manufacturers in Warsaw and Minneapolis are shifting volume toward filament-based production to compress surgical kit lead times.
- PEKK Granules:Standard pellet feedstock for conventional thermoplastic processing.
- PEKK Film:Thin-gauge calendered sheet for electrical insulation and membrane applications.
Mature deployment sits with PEKK Powder. Newer deployment is concentrated in PEKK Filament.
Application:
Performance thresholds and regulatory exposure split the market into flight-certified, implant-grade, and industrial durability tiers with minimal overlap in resin specifications.
- Aerospace:FAA fuel efficiency mandates are accelerating substitution of metal brackets and ducting in narrow-body programs. Tier 1 suppliers now specify PEKK for cabin interiors previously molded from PPS, compressing qualification timelines from 18 months to under 12 months.
- Medical Devices:EU MDR and FDA 21 CFR 177.2415 impose divergent biocompatibility documentation requirements. ISO 10993-5 certified grades command premium placement for spinal cages and cranial implants, with crystallinity variation exceeding 3 percent triggering automatic lot rejection.
- Automotive:Underhood thermal management components compete with polyphenylene sulfide on price-performance positioning.
- Industrial Components:Chemical processing equipment and semiconductor fab hardware drive fluorinated copolymer formulations.
Revenue concentration favors Aerospace. Steepest expansion trajectory appears in Medical Devices.
Technology:
Processing method determines achievable part complexity, surface finish, and economic batch size, with aerospace and medical sectors driving divergent equipment investment cycles.
- 3D Printing:Laser sintering and fused deposition modeling enable topology-optimized geometries without hard tooling. Parameter optimization expertise for PEKK powder bed fusion commands 14-month hiring lead times at aerospace tier suppliers.
- Injection Molding:High-pressure processing retains the deepest margin pool in automotive underhood applications, where cycle time efficiency offsets tooling investment despite PPS price compression from South Korean producers.
- Compression Molding:Continuous fiber-reinforced formats for structural aerospace components.
- Extrusion:Profile and film production for electrical insulation and membrane substrates.
Capital intensity peaks with Injection Molding. Process innovation concentrates in 3D Printing.
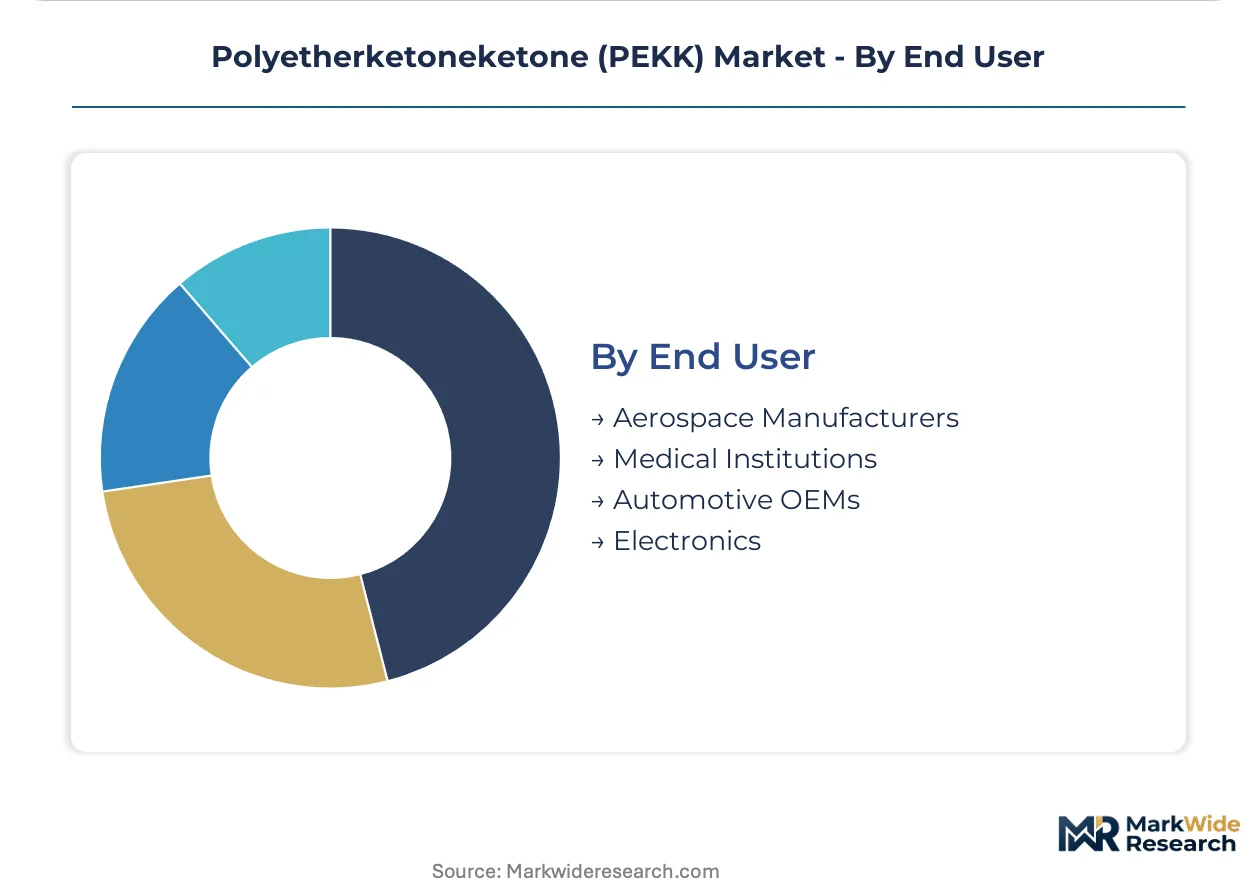
End User:
Procurement authority and technical specification control vary sharply across customer types, with consolidated purchasing in medical devices contrasting fragmented aerospace tier supply chains.
- Aerospace Manufacturers:AS9100D certification requirements and batch traceability standards are consolidating supplier bases around resin producers capable of sub-12-month qualification timelines. Frankfurt and Mannheim industrial corridors host co-located OEM clusters driving regional demand concentration.
- Medical Institutions:US group purchasing organizations now mandate PEKK for all new spinal cage submissions, displacing PEEK-OPTIMA in volume tenders. Three Midwest orthopedic consortia coordinate resin qualification timelines between Zimmer Biomet and Stryker.
- Automotive OEMs:Underhood thermal and chemical resistance specifications compete with metal and PPS alternatives.
- Electronics:Semiconductor wet process equipment manufacturers qualify non-fluorinated PEKK grades for 3nm node tools.
Specification control rests with Aerospace Manufacturers. Procurement consolidation advances fastest among Medical Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Difluorobenzophenone feedstock concentration in Chinese specialty chemical producers shapes procurement risk calculus across downstream PEKK markets. Aerospace OEMs in France and Germany, medical device manufacturers in the United States, and emerging compounders in India each navigate distinct regulatory and supply chain configurations.
United States
FAA fuel efficiency mandates accelerate PEKK substitution for metal brackets in narrow-body aircraft programs at Boeing and its tier suppliers. FDA 21 CFR 177.2415 governs food-contact formulations while EPA oversees emissions from fluorinated ketone monomer production. Wichita hosts concentrated aerospace prototyping workflows where AS9100 traceability requirements favor qualified powder suppliers.
Germany
EU MDR implant-grade certification creates premium placement for ISO 10993-5 certified PEKK in spinal cages and cranial implants. ECHA enforcement of residual ketone thresholds disqualifies legacy production batches from medical device markets. The Frankfurt-Mannheim industrial corridor hosts co-located medical device and automotive OEM clusters driving regional demand concentration.
France
REACH Annex XIV authorization requirements for diphenyl ether derivatives force reformulation of standard PEKK grades ahead of 2026 sunset dates. Arkema S.A. leverages its fluoropolymer heritage from its specialty polymers operations. Toulouse anchors aerospace prototyping demand where laser sintering workflows concentrate around Airbus supply chain nodes.
China
Over 70 percent of difluorobenzophenone feedstock originates from domestic specialty chemical producers, exposing European compounders to export license volatility. GB standards and MIIT oversight shape local production compliance for semiconductor wet process equipment applications. Shandong province hosts emerging PEKK compounders targeting domestic aerospace and medical device qualification programs.
India
CDSCO's phased implementation of Medical Device Rules 2017 attracts PEKK compounders to Ahmedabad and Hyderabad clusters for export-oriented spinal implant production. BIS certification requirements and PLI scheme incentives support domestic manufacturing scale-up. Mumbai-Pune pharmaceutical corridors drive early adoption of implant-grade polymer sourcing for orthopedic OEMs.
Polyetherketoneketone (PEKK) Market Competitive Landscape
Global majors compete with regional champions across resin purity tiers and certification depth. The supplier base consolidates around compounders capable of AS9100 aerospace traceability and ISO 10993-5 medical biocompatibility documentation. Three archetypes dominate: diversified chemical conglomerates with fluoropolymer heritage, specialty polymer pure-plays focused on implant-grade consistency, and emerging Asian compounders exploiting feedstock proximity. Competitive moves center on backward integration into ketone monomer production and strategic partnerships with automated fiber placement equipment vendors.
Within the diversified chemical conglomerate tier, Arkema S.A. and Solvay S.A. occupy positions anchored by European fluoropolymer and specialty polymer operations. Evonik Industries AG exemplifies the medical-grade pure-play archetype through its high-purity certification focus. Among emerging Asian producers, Shandong Kaisheng New Materials Co., Ltd. represents feedstock-proximate compounders targeting qualification in aerospace and medical segments. These three entities collectively illustrate the geographic and strategic segmentation shaping procurement decisions across end-use markets.
| Leading Market Players |
|---|
| SABIC |
| Oxford Performance Materials Inc. |
| Arkema S.A. |
| Ensinger GmbH |
| RTP Company |
| Solvay S.A. |
| Evonik Industries AG |
| Shandong Kaisheng New Materials Co., Ltd. |
| Victrex plc |
| Others |
Value Network & Pricing Analysis
AS9100D certification requirements from aerospace OEMs are compressing supplier qualification timelines below 12 months, forcing compounders to absorb inline DSC monitoring costs of €2.4 million per extrusion line while medical device OEMs reject lots with crystallinity variation exceeding 3 percent. This specification tightening concentrates procurement among qualified resin producers capable of dual-grade aerospace-medical output, elevating pricing power for compliant batches while legacy production faces disqualification from EU medical device markets under ECHA residual ketone thresholds.
Pricing Analysis
Warranty and technical service bundling separates qualified aerospace powder suppliers from unbundled filament distributors serving prototyping workshops. Three-tier pricing structure across implant-grade certified, aerospace-qualified, and industrial-standard levels reflects ISO 10993-5 certification investment and AS9100 traceability depth. Cost compression in automotive underhood applications intensifies as South Korean PPS producers narrow the performance-price gap below PEKK tooling justification thresholds. Medical institutions through group purchasing organizations demonstrate lowest price sensitivity, while automotive Tier 2 molders face acute margin pressure from metal substitution economics.
Supply Chain Analysis
Dual-sourcing mandates from Boeing and Airbus tier suppliers require qualified backup resin producers for each PEKK grade specification, extending qualification timelines but reducing single-source vulnerability. Difluorobenzophenone feedstock concentrates in Chinese specialty chemical producers alongside domestic compounding capacity in Shandong province, while European supply anchors through Arkema's fluoropolymer operations and Solvay's Tavaux facility. Export license volatility from Chinese monomer producers represents the dominant structural risk. Distribution runs through qualified distributor networks for aerospace powder and direct mill relationships for medical filament volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR implant-grade certification creates a cost-of-compliance moat where ISO 10993-5 documentation investment disqualifies speculative entrants, reserving premium placement for compounders with validated biocompatibility dossiers and inline crystallinity monitoring infrastructure.
For Market Incumbents: Lock in aerospace supply agreements ahead of AS9100D audit queue times extending to 8 months, while accelerating backward integration into difluorobenzophenone production to neutralize Chinese export license volatility threatening European compounder feedstock security. Prioritize dual-grade extrusion capacity serving both spinal implant and structural flight hardware specifications to maximize asset utilization across demand cycles. For New Entrants and Emerging Players: Export-oriented spinal implant manufacturers in Ahmedabad and Hyderabad clusters represent the most penetrable buyer archetype, as CDSCO's phased Medical Device Rules 2017 implementation attracts compounders seeking qualification ahead of domestic market maturation. Target semiconductor wet process equipment manufacturers qualifying non-fluorinated PEKK grades for 3nm node tools, leveraging fluoropolymer formulation expertise absent among feedstock-proximate Asian producers. Lead with application engineering partnerships rather than price competition against established medical-grade pure-plays. For Investors and Strategic Acquirers: The window for entry favors specialty polymer pure-plays with validated ISO 10993-5 dossiers and existing AS9100 traceability infrastructure, as diversified chemical conglomerates face capital allocation competition from core fluoropolymer segments. Long-term viability hinges on chemical recycling partnership maturity ahead of EU Green Deal landfill diversion deadlines for thermoplastic waste streams. Monitor pyrolysis technology deployment for ketone monomer recovery from aerospace scrap as the inflection signal for circular economy positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ketone Monomer Production | Captive supply of difluorobenzophenone neutralizes Chinese export license exposure for European compounders. |
| Dual-Grade Extrusion Capacity Expansion | Shared production lines for aerospace powder and medical filament maximize equipment utilization across demand cycles. |
| Chemical Recycling Infrastructure Partnership | Pyrolysis recovery of ketone monomers from aerospace scrap aligns with EU Green Deal landfill diversion mandates. |
| Non-Fluorinated Copolymer R&D Pipeline | Elimination of perfluorinated substances qualifies PEKK for Lam Research and Applied Materials 3nm node tool specifications. |
| Inline Crystallinity Monitoring Installation | Automated DSC systems at €2.4 million per line reduce medical device OEM lot rejection rates below 3 percent variation thresholds. |
Research Methodology
Multi-period observation of AS9100 certification queue times, ECHA enforcement patterns for residual ketone thresholds, and CDSCO Medical Device Rules implementation phases anchored the trend analysis, supplemented by interviews with aerospace tier supplier procurement directors, medical device OEM polymer specification engineers, compounder plant managers, and GPO contracts managers. Secondary validation drew from ECHA authorization databases, FDA 510(k) PEKK device filings, EU customs trade data for difluorobenzophenone imports, and SEC specialty polymer segment disclosures. Bottom-up resin volume estimates triangulated against top-down aerospace and medical device demand modeling.
Segment-weighting across product type, application, technology, and end-user dimensions informed volume and value outputs across the analysis window. Aerospace prototyping powder, spinal implant filament, and automotive underhood granule segments each carried distinct thermal management protocol assumptions and certification depth premiums. CAGRs derived from regression of historical qualification timeline compression against fuel efficiency mandate acceleration and EU MDR implementation phasing. Forecast inputs incorporated automated fiber placement equipment deployment rates for continuous fiber-reinforced PEKK-CF tape and hospital procurement consortium consolidation around single-resin spinal cage platforms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pyrolysis technology maturation for chemical recycling, REACH Annex XIV sunset date enforcement for diphenyl ether derivatives, and Chinese export license policy volatility for fluorinated ketone monomers. Deviation in AS9100D audit queue times or ECHA residual ketone threshold enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
Propylene Terpolymer Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market