
 United Kingdom Engineering Plastics Market | 2026-2036
United Kingdom Engineering Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Engineering Plastics Market Insights
Buyer concentration across UK automotive tier-one suppliers is rebalancing as electric vehicle platforms fragment sourcing pools among new battery housing specialists and legacy powertrain moulders. Victrex leverages its Thornton-Cleveleys manufacturing base to sustain high-performance PEEK supply for aerospace landing gear programmes. BASF SE anchors its European compounding network through Ludwigshafen-linked distribution to UK automotive OEMs. Covestro AG competes on polycarbonate optical grades for EV headlamp lenses, differentiating through direct technical service to Midlands tooling houses.
Engineering plastics encompass thermoplastic polymers engineered to withstand mechanical load, thermal stress, and chemical exposure beyond commodity resin capabilities, typically exhibiting flexural modulus above 1,000 MPa and continuous service temperatures exceeding 100°C, produced via melt polymerisation, interfacial condensation, or ring-opening polymerisation for structural, electrical, and barrier applications. Nylon retains dominant volume share in under-the-hood automotive connectors where heat ageing resistance commands premium pricing, while polycarbonate optical clarity drives fastest growth in EV lighting and display housings. Polyethylene variants occupy commoditised industrial sheet markets where pellet-to-part converters compete on throughput scale rather than formulation IP.
The Health and Safety Executive enforces REACH substance restrictions on phthalate plasticisers and brominated flame retardants, redirecting formulation R&D toward halogen-free alternatives. British Standards Institution certification for rail and medical device grades creates tiered market access thresholds that filter sub-scale compounders. The Environment Agency's Extended Producer Responsibility implementation tightens post-consumer recycling content mandates for packaging applications. Stakeholders must monitor polymer-specific carbon border adjustment readiness and align capital allocation with UK net-zero industrial cluster timelines.
Market Dynamics
Automotive electrification is fragmenting established resin procurement channels across the West Midlands manufacturing belt, as battery housing specialists displace legacy powertrain moulders in tier-one supplier hierarchies. This structural reconfiguration is redrawing material specification authority and compounding network access.
Growth Catalysts
- REACH substance restrictions:The Health and Safety Executive's enforcement of phthalate and brominated flame retardant bans is redirecting formulation R&D toward halogen-free alternatives, creating pull-through demand for certified engineering grades.
- EV platform proliferation:Electric vehicle headlamp lens specifications are accelerating polycarbonate optical grade consumption across Midlands tooling houses serving JLR and Nissan Sunderland.
- Thornton-Cleveleys aerospace cluster:Landing gear programme continuity at this Lancashire manufacturing base sustains high-performance PEEK demand independent of automotive cyclicality.
Market Restraints
- Crude oil derivative volatility:Benzene and caprolactam feedstock cost swings compress compounder margins on nylon 6 and nylon 66 grades, forcing quarterly price renegotiations with automotive buyers.
- Ludwigshafen supply concentration:BASF SE's European compounding network dominance creates single-source vulnerability for UK automotive OEMs seeking PA6-GF30 and PBT specifications.
- Continuous service temperature ceilings:Polycarbonate thermal limitations below 130°C restrict under-the-hood penetration, ceding volume to polyamide and PPS in charge air cooler applications.
Strategic Opportunities
- Greater Manchester advanced manufacturing corridor:Underutilised compounding capacity in this northern hub offers geographic diversification from Midlands supply concentration for medical device moulders.
- Extended Producer Responsibility mandates:The Environment Agency's tightening post-consumer recycling content rules for packaging applications creates certified recycled-content engineering resin premiums.
- Carbon fibre hybridisation:Long-fibre thermoplastic overmoulding with PEEK and PPS matrices is integrating into aerospace bracket production, opening hybrid material specification pathways.
Industry Challenges
- Polymer chemist recruitment:Formulation laboratories across the West Midlands report acute shortages of specialists capable of halogen-free flame retardant compounding under REACH transition timelines.
- British Standards Institution certification lag:Rail and medical device grade approval cycles extending eighteen to twenty-four months delay new compound market entry against incumbent qualified suppliers.
- Legacy injection moulding asset retrofit:Tooling houses serving mixed ICE-EV automotive programmes face capital allocation conflicts between PPA high-heat tooling and existing polycarbonate-dedicated presses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Engineering Plastics Market |
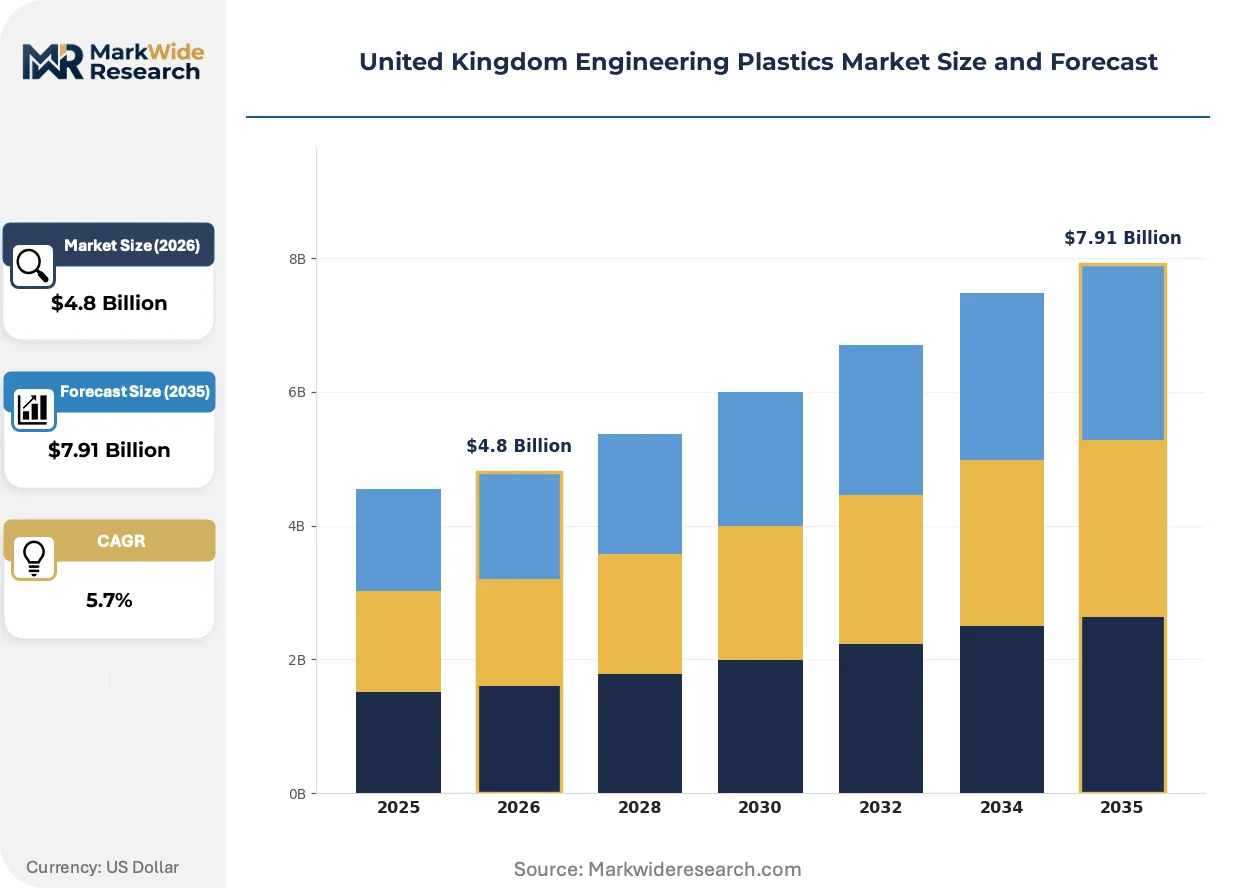
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Nylon, Polyethylene, Acetal End User: Aerospace, Automotive, Consumer Goods, Electronics Form: Sheet, Rod, Film, Pellets Application: Packaging, Structural Components, Electrical Insulation, Medical Devices |
| Companies Covered | Victrex, BASF SE, Covestro AG, Sumitomo Chemical Co Ltd, Teijin Limited, Celanese Corporation, INEOS, Asahi Kasei Corporation, Mitsubishi Chemical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Engineering Plastics Market Trends and Innovations
Material science convergence with regulatory compliance requirements is redefining competitive differentiation in UK engineering plastics, shifting value capture from commodity throughput toward certified formulation IP and technical service proximity.
Glass-reinforced polyphthalamide compounds are integrating into power electronics housings for 800-volt EV architectures, where dielectric strength and comparative tracking index ratings exceed standard PA66 capabilities. Tier-one suppliers at the MIRA Technology Park are validating these grades for inverter enclosures. This substitution is integrating high-heat polymer specifications deeper into electrified powertrain supply chains, compressing the addressable market for metal die-cast alternatives.
The Environment Agency's Extended Producer Responsibility implementation timeline is tightening traceability mandates for polymer flows into packaging-adjacent industrial applications. Compounders must now document post-consumer recycled content percentages through mass balance certification. Medical device and rail sectors are responding fastest, with BSI-certified grades commanding specification premiums over uncertified alternatives in procurement evaluations.
Automotive buyers are consolidating resin specifications across fewer qualified suppliers to reduce homologation costs for multi-platform EV programmes. Direct technical service relationships with Midlands tooling houses are displacing traditional distributor channels for optical polycarbonate and laser-weldable PBT grades. This concentration is most visible at JLR's Halewood and Solihull facilities, where material approval authority has shifted from purchasing to engineering functions.
United Kingdom Engineering Plastics Market Segmentation
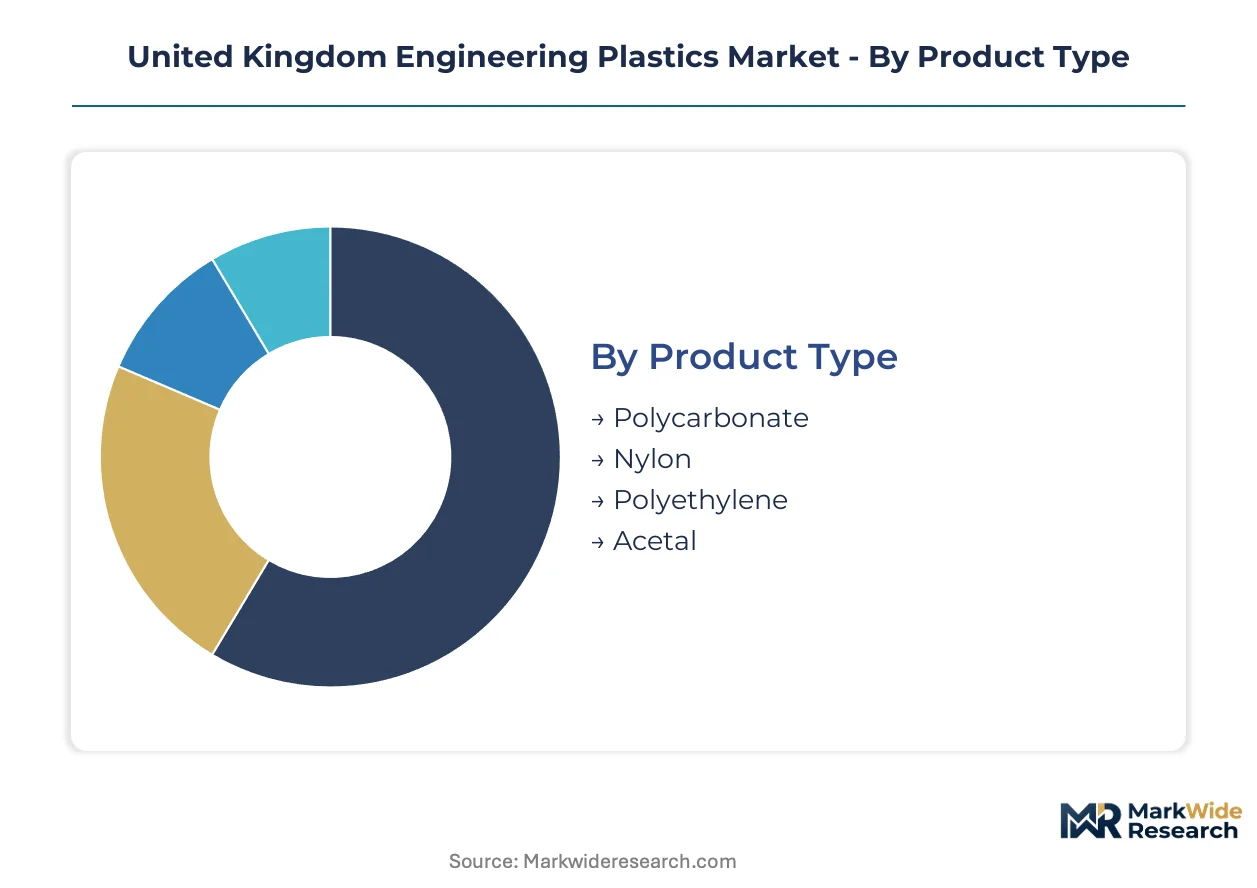
Engineering plastics procurement in the United Kingdom fragments across performance tiers, regulatory exposure, and conversion technology requirements. Buyers select grades based on continuous service temperature thresholds, flame retardant certification needs, and proximity to qualified compounding capacity.
Product Type:
Cost tier separates commodity converters from specification-critical compounders serving aerospace and medical device programmes.
- Nylon:Polyamide grades dominate under-the-hood automotive connectors where heat ageing resistance commands premium formulation pricing. Demand concentrates across West Midlands tier-one suppliers serving JLR and Nissan Sunderland powertrain programmes, with glass-reinforced PA6-GF30 and PA66-GF30 specifications displacing metal in charge air cooler housings.
- Polycarbonate:Optical clarity grades exhibit bisphenol-A backbone chemistry enabling light transmission above 90% in 2mm sections. EV headlamp lens specifications at Midlands tooling houses are accelerating consumption fastest, though thermal ceiling limitations below 130°C restrict under-the-hood penetration against polyamide alternatives.
- Acetal:Polyoxymethylene homopolymer and copolymer grades deliver low friction coefficients for precision gear applications.
- Polyethylene:Ultra-high molecular weight variants occupy commoditised industrial sheet markets where pellet-to-part converters compete on throughput scale.
Volume sits with Nylon; growth tilts toward Polycarbonate.
End User:
Application maturity determines qualification timeline intensity and supplier switching costs.
- Automotive:Electrification is fragmenting established resin procurement channels across the West Midlands manufacturing belt. Battery housing specialists displace legacy powertrain moulders in tier-one supplier hierarchies, redrawing material specification authority toward 800-volt power electronics housings.
- Aerospace:Landing gear programmes at the Thornton-Cleveleys cluster sustain high-performance PEEK demand independent of automotive cyclicality. Lancashire manufacturing bases serve Boeing and Airbus qualification requirements with carbon fibre hybridised brackets.
- Electronics:Connector and enclosure specifications drive laser-weldable PBT and halogen-free flame retardant polycarbonate grades.
- Consumer Goods:Durables manufacturers source standard grades through distributor channels with limited technical service attachment.
Procurement scale concentrates in Automotive; specification complexity peaks in Aerospace.
Form:
Conversion technology requirements separate extrusion-based processors from injection moulding houses.
- Pellets:Standardised melt polymerisation output feeds injection moulding and extrusion compounding operations across UK converter networks. Greater Manchester advanced manufacturing corridor houses underutilised capacity serving medical device moulders seeking geographic diversification from Midlands concentration.
- Sheet:Flat extrusion products supply thermoforming operations for equipment housings and industrial liners.
- Rod:Stock shapes enable CNC machining of precision bearings and gears without tooling investment.
- Film:Thin-gauge extrusion serves electrical insulation and membrane applications.
Throughput volume concentrates in Pellets; margin capture is strongest in Sheet.
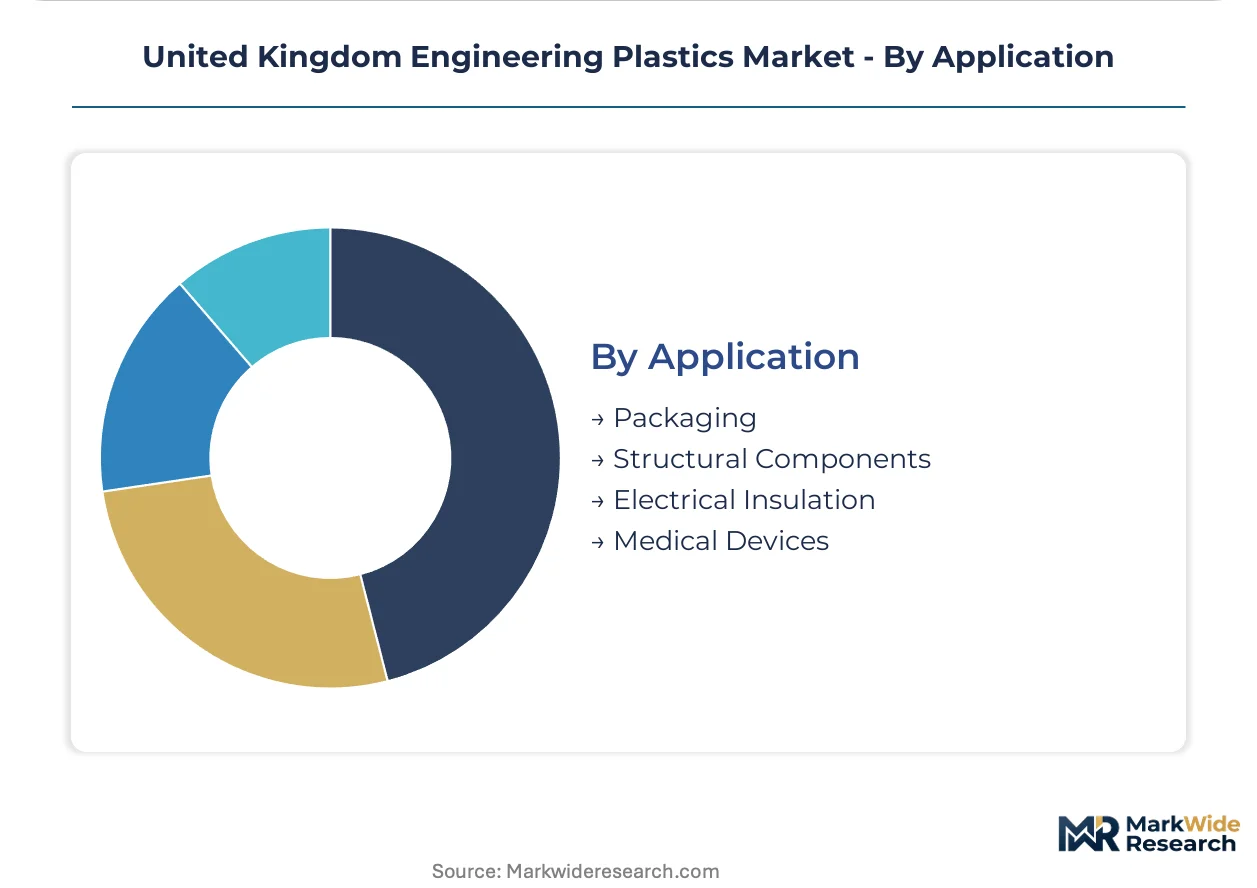
Application:
Regulatory exposure tier separates REACH-sensitive specifications from industrial commodity flows.
- Medical Devices:British Standards Institution certification creates eighteen to twenty-four month approval cycles that filter sub-scale compounders. BSI-certified grades command specification premiums over uncertified alternatives in procurement evaluations for surgical instruments and diagnostic equipment housings.
- Electrical Insulation:Dielectric strength and comparative tracking index requirements exceed standard PA66 capabilities in 800-volt EV architectures. Tier-one suppliers at MIRA Technology Park validate glass-reinforced polyphthalamide compounds for inverter enclosures.
- Structural Components:Load-bearing brackets and housings integrate long-fibre thermoplastic overmoulding with PEEK and PPS matrices.
- Packaging:Environment Agency Extended Producer Responsibility mandates tighten traceability requirements for post-consumer recycled content percentages.
Certification intensity peaks in Medical Devices; volume scale sits with Structural Components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for engineering plastics concentrates in the West Midlands automotive belt and Greater Manchester advanced manufacturing corridor, with regulatory enforcement through REACH and Extended Producer Responsibility rules tightening material traceability requirements nationwide.
West Midlands
Battery housing specialists at MIRA Technology Park validate glass-reinforced polyphthalamide compounds for 800-volt inverter enclosures. The Health and Safety Executive enforces phthalate plasticiser bans across this automotive cluster. Tier-one suppliers serving JLR Halewood and Solihull facilities consolidate resin specifications to reduce homologation costs.
Greater Manchester
Medical device moulders seek geographic diversification from Midlands supply concentration at underutilised compounding capacity in this northern hub. British Standards Institution certification creates eighteen to twenty-four month approval cycles for rail and surgical instrument grades. The Environment Agency's Extended Producer Responsibility implementation tightens post-consumer recycling content mandates.
Lancashire
Thornton-Cleveleys sustains high-performance PEEK demand for aerospace landing gear programmes independent of automotive cyclicality. REACH substance restrictions on brominated flame retardants redirect formulation R&D toward halogen-free alternatives at this manufacturing base. Carbon fibre hybridised brackets serve Boeing and Airbus qualification requirements.
South East England
Electronics connector specifications drive laser-weldable PBT consumption across distributor channels serving London-based procurement offices. The Health and Safety Executive's enforcement of flame retardant bans creates pull-through demand for certified engineering grades. Technical service relationships concentrate around optical polycarbonate grades for display housings.
Scotland
Precision gear applications source acetal grades through distributor networks with limited technical service attachment. The Environment Agency's traceability mandates for polymer flows affect packaging-adjacent industrial applications in this region. Underpenetration in high-heat power electronics specifications offers expansion potential for compounders.
United Kingdom Engineering Plastics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue certified formulation IP and technical service proximity as differentiation vectors. The vendor base separates into three maturity tiers: global resin suppliers with European compounding networks, regional compounders serving qualified automotive programmes, and specialised distributors handling commodity polyethylene flows. Strategic moves concentrate on direct technical service relationships displacing traditional channels, and portfolio diversification toward halogen-free flame retardant grades under REACH transition timelines.
Among UK-based and European-anchored suppliers, Victrex exemplifies the high-performance polymer archetype through its Thornton-Cleveleys manufacturing presence, while BASF SE and Covestro AG represent the continental European network model serving UK automotive OEMs through Ludwigshafen-linked distribution and direct Midlands technical service respectively. These three occupy positions spanning aerospace qualification continuity, nylon and PBT specification authority, and polycarbonate optical grade differentiation.
| Leading Market Players |
|---|
| Victrex |
| BASF SE |
| Covestro AG |
| Sumitomo Chemical Co Ltd |
| Teijin Limited |
| Celanese Corporation |
| INEOS |
| Asahi Kasei Corporation |
| Mitsubishi Chemical Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive compounding capacity at Ludwigshafen-linked facilities anchors both supply security and pricing power for UK automotive OEMs sourcing PA6-GF30 and PBT specifications. This upstream integration insulates BASF SE from feedstock volatility while compressing margin room for distributor-dependent competitors serving smaller moulding houses.
Pricing Analysis
Volume concentrates in commoditised polyethylene sheet markets where pellet-to-part converters compete on throughput scale, while margin capture peaks in BSI-certified medical device grades commanding specification premiums over uncertified alternatives. Price differentiation hinges on REACH compliance tier and British Standards Institution certification level, with halogen-free flame retardant compounds attracting premium positioning. Cost compression in nylon 6 and nylon 66 grades is intensifying because benzene and caprolactam feedstock swings force quarterly renegotiations. Automotive tier-one suppliers exhibit lowest price sensitivity due to homologation lock-in, whereas industrial packaging converters demonstrate highest sensitivity to resin index movements.
Supply Chain Analysis
Regional distribution centres at Midlands tooling houses operate hub-and-spoke patterns feeding JLR Halewood and Solihull facilities with optical polycarbonate and laser-weldable PBT grades. Supply concentrates in Germany, Belgium, and the Netherlands for European compounding networks, with UK resin flows drawing from Ludwigshafen, Antwerp, and Rotterdam chemical clusters. Raw material dependencies centre on benzene derivatives, caprolactam monomer, and bisphenol-A feedstocks. Single-source vulnerability from BASF SE's European network dominance creates procurement risk for UK automotive OEMs. Distribution runs through direct technical service relationships displacing traditional distributor channels for specification-critical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating as REACH substance restrictions and Extended Producer Responsibility mandates force sub-scale compounders out of specification-critical segments. Regulatory compliance costs filter participants faster than demand growth absorbs them.
For Market Incumbents: Extend halogen-free flame retardant formulation portfolios ahead of Health and Safety Enforcement phasing deadlines. Backward integration into caprolactam supply or captive recycling streams defends margin position against feedstock volatility. Lock in direct technical service relationships with Midlands tooling houses to displace distributor channels for optical polycarbonate specifications.
For New Entrants and Emerging Players: Extended Producer Responsibility in the United Kingdom opens a window for certified recycled-content engineering resin premiums. Target medical device moulders in Greater Manchester seeking geographic diversification from Midlands supply concentration. Pursue British Standards Institution certification pathways for rail and surgical instrument grades as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap compounders with qualified automotive programmes and BSI-certified grade portfolios. Long-term viability hinges on regulatory compliance capability rather than commodity scale. Watch for carbon border adjustment mechanism implementation signals as the inflection indicator for UK net-zero industrial cluster capital allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Captive benzene or caprolactam sourcing insulates BASF SE and Victrex from derivative volatility. |
| Halogen-Free Flame Retardant Certification | REACH-compliant grades redirect procurement toward qualified compounders with Health and Safety Executive alignment. |
| Direct Technical Service Deployment | Covestro AG's Midlands tooling house relationships displace distributor channels for optical polycarbonate. |
| Post-Consumer Recycled Content Certification | Environment Agency mass balance mandates create premium positioning for compounders with traceable polymer flows. |
| Carbon Fibre Hybridisation Capacity | Long-fibre thermoplastic overmoulding at Thornton-Cleveleys opens aerospace bracket specifications for PEEK and PPS matrices. |
Research Methodology
Independent corroboration across primary interviews with polymer chemists, tier-one supplier procurement leads, and Midlands tooling house engineers underwrites the qualitative findings. Secondary validation draws from British Standards Institution certification records, Health and Safety Executive REACH enforcement disclosures, and Environment Agency Extended Producer Responsibility implementation documents. Customs and trade data from HMRC, Cefic industry reports, and SEC filings of listed resin suppliers provide quantitative anchoring. Bottom-up demand modelling from end-use consumption patterns triangulates against top-down supply capacity assessments across European compounding networks.
Comparable historical periods spanning pre-pandemic baseline, supply disruption intervals, and regulatory transition phases anchor the forecast window to observable demand elasticity patterns. Segmentation dimensions modelled include performance tier, regulatory exposure grade, conversion technology requirement, and regional production cluster proximity. CAGRs derive from elasticity-adjusted demand projections and capacity expansion timelines across the analysis window. Industry-specific inputs incorporate automotive electrification content shifts and aerospace programme qualification cycles.
The model assumes a particular technology adoption path for 800-volt EV architectures; alternative pathways for solid-state battery thermal management would alter the outlook for high-heat polymer specifications. Forecasts reflect documented assumptions on regulatory enforcement intensity and feedstock cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Hydrocarbon Resins Market