
 Storage Class Memory Market | 2026-2036
Storage Class Memory Market Size, Share, and Industry Trends Forecast 2026-2036
Storage Class Memory Market Outlook
Market Context
East Asian foundry capacity is restructuring around advanced logic and memory co-production. Samsung Electronics dominates high-volume 3D XPoint and MRAM wafer output. SK Hynix anchors supply through backward integration into EUV lithography and materials refining. Micron Technology leverages Idaho-based R&D to sustain technology leadership in persistent memory architectures.
Technical Definition and Segment Structure
Storage class memory bridges the latency gap between DRAM and NAND flash, offering sub-microsecond access times with non-volatile retention for mission-critical databases and real-time analytics. The product type dimension shows NAND Flash occupying the largest revenue pool while MRAM captures the fastest expansion in automotive and edge deployments. End user concentration tilts toward Data Centers, where persistent memory tiers reduce total infrastructure cost for hyperscale caching and analytics workloads.
Regulatory Environment and Outlook
REACH and RoHS frameworks in Europe restrict hazardous substances in semiconductor manufacturing, while the EU F-Gas Regulation phases down fluorinated greenhouse gases used in etching processes. South Korea's Ministry of Environment enforces parallel emissions controls under its national carbon neutrality roadmap. Stakeholders must monitor how evolving chemical compliance timelines reshape foundry location decisions and capital allocation across the memory supply chain.
Market Dynamics
Data center operators are consolidating memory tiers to collapse latency hierarchies, forcing foundries to retool for persistent memory co-production alongside advanced logic rather than discrete NAND fabrication.
Growth Catalysts
- EU F-Gas Regulation phase-down:Semiconductor etching chemistry constraints accelerate transition to atomic layer deposition processes compatible with next-generation MRAM stacks.
- Hyperscale caching workloads:Persistent memory modules reduce total infrastructure cost for real-time analytics platforms operating at sub-microsecond access thresholds.
- South Korean cluster concentration:Hwasung and Pyeongtaek foundry ecosystems achieve backward integration into EUV lithography and materials refining, compressing development cycles.
Market Restraints
- Fluorinated gas supply chokepoints:REACH and RoHS chemical compliance timelines in Europe constrain etching process availability, extending qualification periods for new wafer starts.
- East Asian foundry concentration:Samsung Electronics and SK Hynix control high-volume 3D XPoint and MRAM output, creating single-source vulnerability for non-captive buyers.
- DRAM-NAND price compression:Persistent memory architectures face substitution pressure when volatile memory pricing cycles collapse the latency-cost gap.
Strategic Opportunities
- Automotive edge deployments:MRAM captures fastest expansion in powertrain control and ADAS sensor fusion applications requiring radiation-hardened non-volatile retention.
- Idaho-based R&D anchoring:Micron Technology's captive materials science capabilities create technology leadership pathways in persistent memory architectures outside East Asian supply clusters.
- South Korean carbon neutrality roadmap:Ministry of Environment emissions controls incentivize greenfield foundry construction with integrated renewable power and closed-loop chemical recovery.
Industry Challenges
- EUV lithography talent scarcity:Specialized photoresist engineering and mask defectivity expertise concentrates at ASML and incumbent foundries, constraining new entrant process development.
- Legacy memory controller integration:Persistent memory modules require firmware rearchitecture to expose byte-addressable interfaces through existing PCIe and CXL topologies.
- Cross-border chemical logistics:Fluorinated compound shipping restrictions under national carbon neutrality frameworks disrupt just-in-time etching gas replenishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage Class Memory Market |
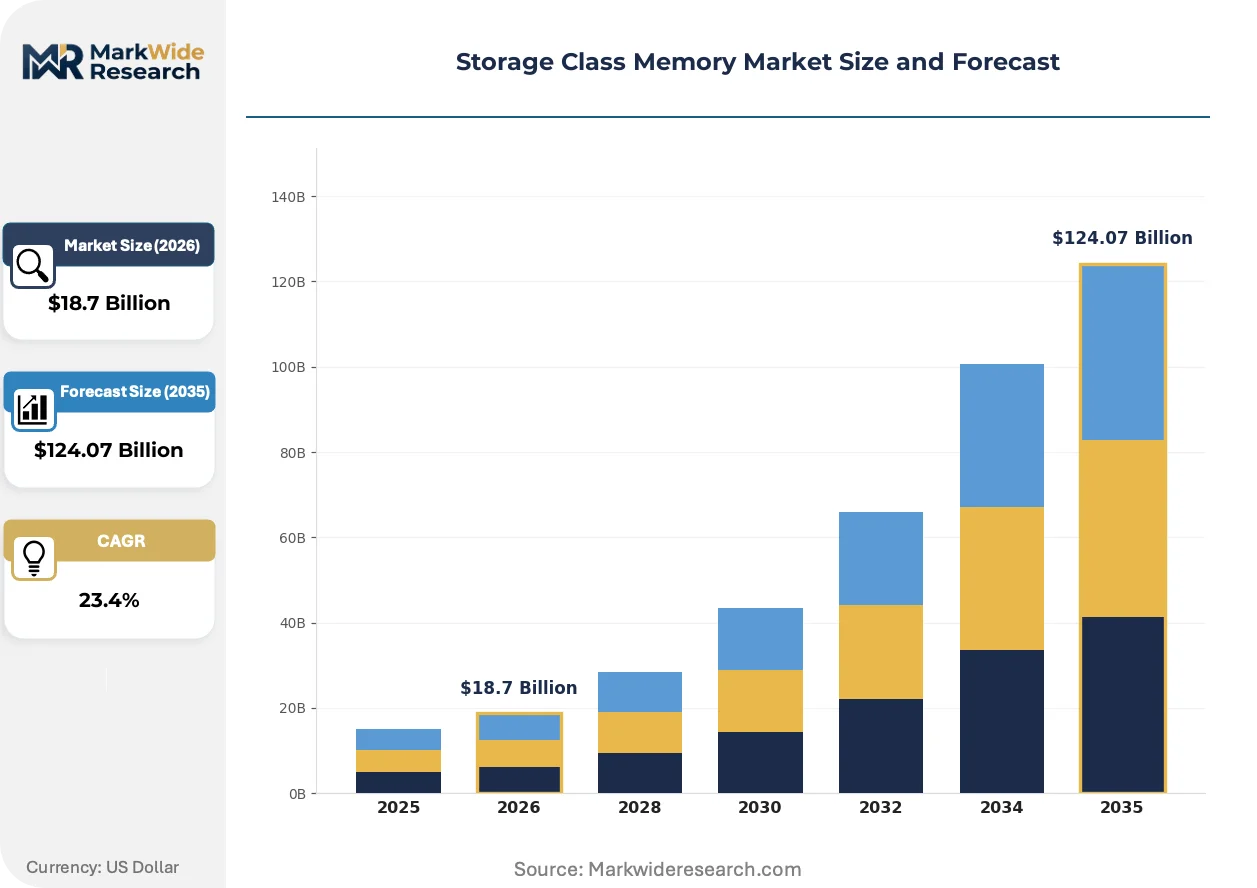
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $124.07 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NAND Flash, 3D XPoint, MRAM, PCM End User: Data Centers, Enterprise, Automotive, IoT Devices Technology: Byte-addressable, Block-access, Persistent, Non-volatile Application: Databases, Caching, Storage Systems, Analytics |
| Companies Covered | Intel, GSI Technology, Samsung Electronics, eMemory Technology, NVE Corporation, SK Hynix, Everspin Technologies, Infineon Technologies, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage Class Memory Market Strategic Shifts
Memory-class storage architectures are collapsing traditional tier boundaries, enabling new system designs that treat persistence as a native compute property rather than an I/O bottleneck.
MRAM is consolidating position as the embedded non-volatile layer for automotive microcontrollers and edge AI accelerators. Tier-1 automotive suppliers specify magnetoresistive stacks for powertrain controllers requiring 10-year data retention across temperature extremes. This consolidation compresses the addressable market for competing embedded flash technologies in safety-critical applications.
REACH substance restrictions and the EU F-Gas Regulation are forcing etching chemistry substitution in European-located semiconductor fabrication. Industrial consequence includes extended qualification timelines for new persistent memory process nodes as atomic layer deposition replaces fluorinated plasma etching. Memory foundries with European packaging and test operations face highest compliance cost exposure, accelerating nearshoring to South Korean and US-based backend facilities.
Hyperscale buyers are unbundling memory procurement from server OEM contracts, establishing direct foundry relationships for persistent memory die supply. Cloud infrastructure operators now qualify bare die for in-house module assembly, displacing traditional memory distributor channels. This pattern concentrates in North American data center deployments where Meta, Google, and Microsoft operate captive integration facilities.
Storage Class Memory Market Segmentation
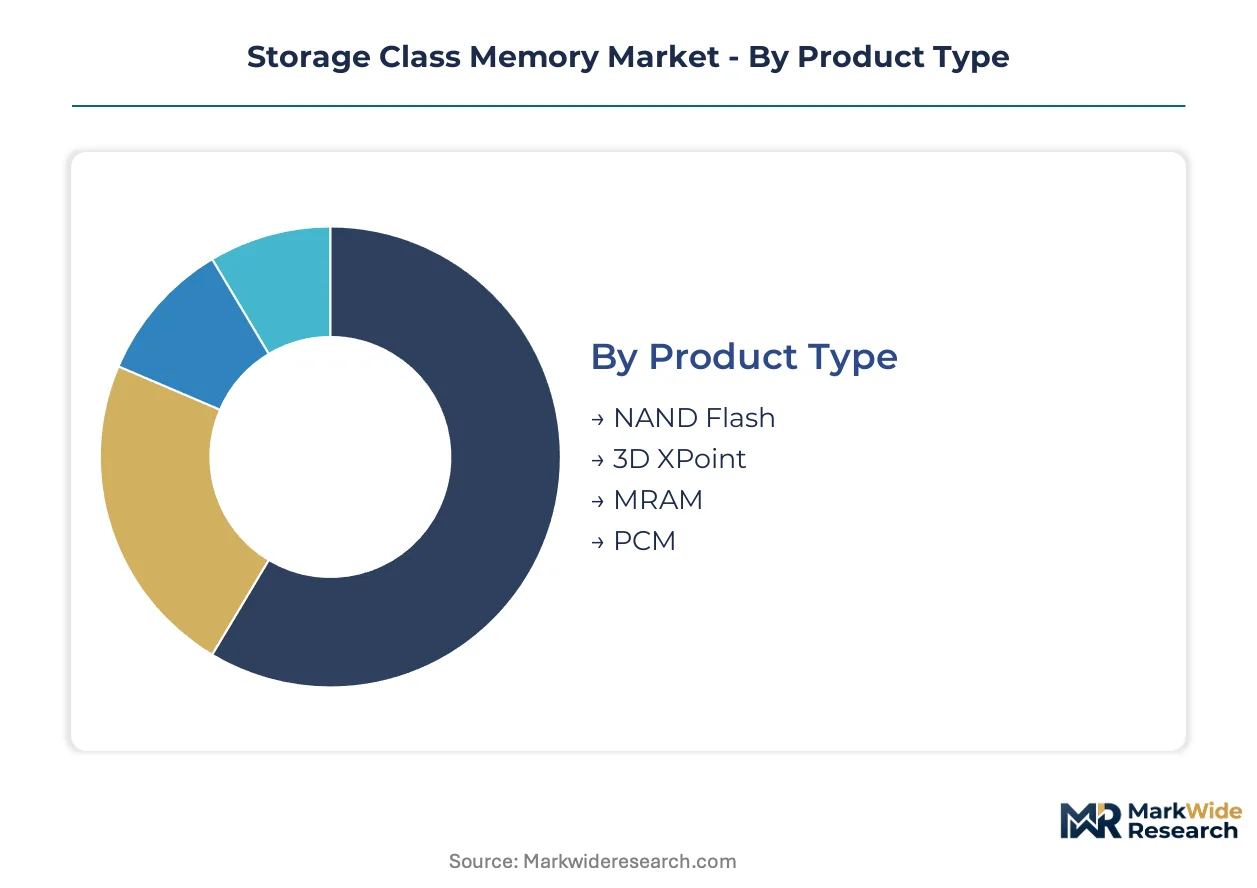
Storage class memory procurement decisions hinge on matching persistence requirements to workload latency thresholds. Foundries and module assemblers configure production lines around these segment boundaries to capture premium pricing in mission-critical deployments.
Product Type:
Cost tier determines module qualification cycles and foundry allocation priority.
- NAND Flash:Charge-trap cell architectures dominate high-density storage tiers with established supply chains from Samsung and SK Hynix fabs in South Korea. Data center operators in Hwasung and Pyeongtaek clusters absorb the majority of wafer output for hyperscale caching layers.
- MRAM:Magnetic tunnel junction stacks deliver sub-50ns write endurance for automotive powertrain controllers. Tier-1 suppliers specify MRAM for ADAS sensor fusion requiring radiation-hardened retention across temperature extremes.
- 3D XPoint:Phase-change material crosspoint arrays target persistent memory DIMM form factors.
- PCM:Chalcogenide-based phase change cells bridge DRAM-NAND latency gaps in enterprise storage arrays.
Volume sits with NAND Flash; growth tilts toward MRAM.
End User:
Application criticality shapes certification requirements and supplier relationship depth.
- Data Centers:Hyperscale operators unbundle memory procurement from server OEM contracts, establishing direct foundry relationships for bare die supply. Meta, Google, and Microsoft operate captive integration facilities in North America to collapse latency hierarchies for real-time analytics.
- Automotive:Functional safety ISO 26262 compliance mandates traceable supply chains for powertrain and chassis control modules. MRAM penetration climbs fastest here as embedded flash faces endurance limitations.
- Enterprise:Financial services and telecom operators prioritize persistent memory tiers for database acceleration.
- IoT Devices:Edge sensor nodes favor low-leakage non-volatile retention for intermittent power environments.
Data Centers command the largest procurement volumes; Automotive shows the steepest expansion trajectory.
Technology:
Interface architecture determines firmware reengineering burden for memory controller vendors.
- Byte-addressable:Load-store semantics expose persistent memory through existing CPU memory controllers, eliminating block translation overhead. CXL 2.0 protocol adoption accelerates in Hwasung cluster deployments.
- Persistent:Retention without power enables new system designs treating storage as native compute property. REACH and RoHS compliance timelines in Europe constrain etching chemistry for persistent layer fabrication.
- Block-access:Traditional NAND page structures persist in cost-optimized storage tiers.
- Non-volatile:Retention specifications vary from 10-year automotive requirements to data center refresh cycles.
Block-access retains the installed base; byte-addressable gains share fastest.
Application:
Workload characteristics dictate endurance, latency, and capacity tradeoffs in module specification.
- Caching:Sub-microsecond access thresholds reduce total infrastructure cost for hyperscale analytics platforms. South Korean foundries prioritize wafer allocation to caching-optimized die configurations.
- Databases:ACID transaction logging benefits from persistent memory commit buffers eliminating double-write penalties. EU F-Gas Regulation phase-down extends qualification timelines for database-optimized process nodes.
- Analytics:In-memory column store acceleration drives high-capacity module demand.
- Storage Systems:Tiered persistence architectures collapse traditional SAN/NAS boundaries.
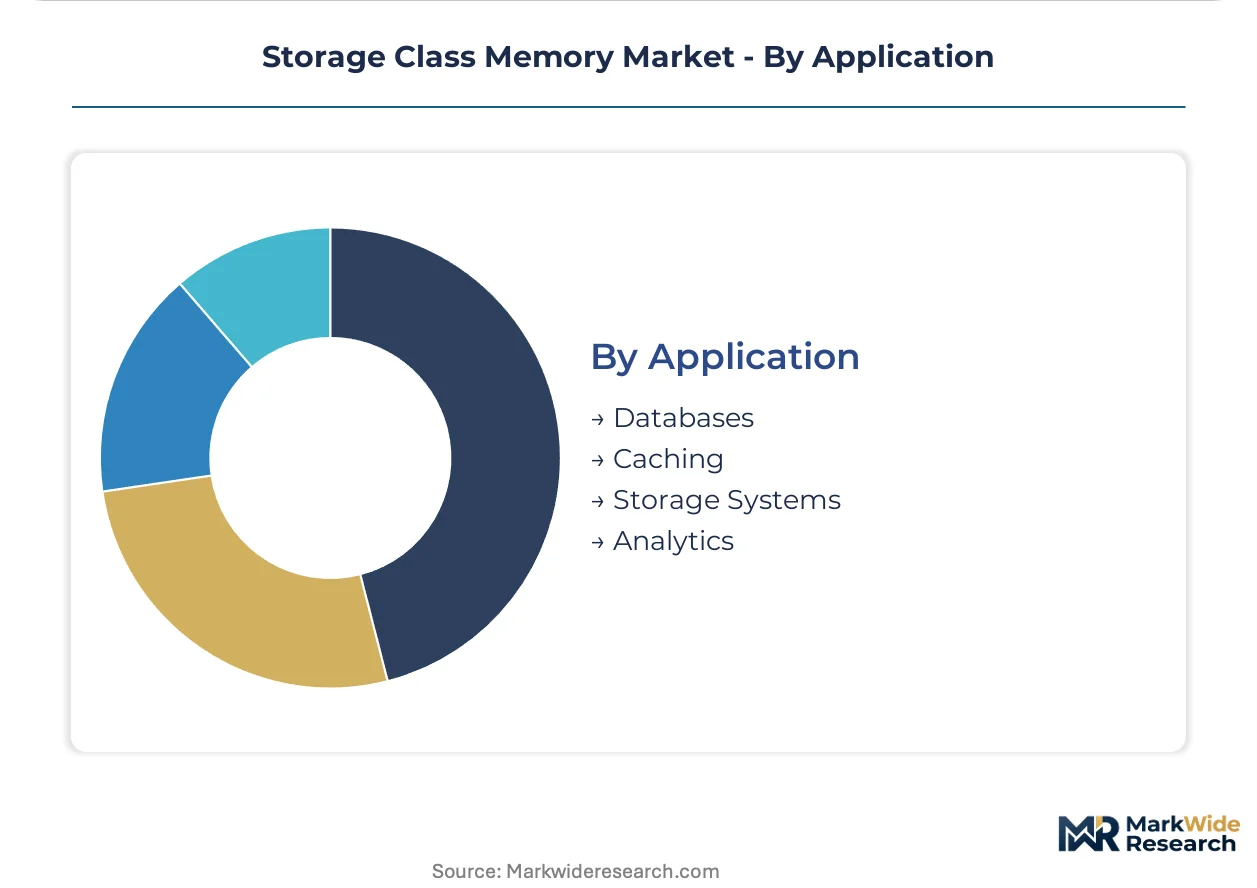
Caching captures current volume leadership; databases are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silicon metal from Norway's Elkem and Germany's Wacker Chemie anchors European wafer substrate supply for persistent memory foundries. South Korean tungsten concentrate from Sangdong feeds EUV mask blank production. Chinese rare earth processing at Baotou controls magnetoresistive material precursors for MRAM tunnel junctions.
United States
Hyperscale data center operators in Northern Virginia and Phoenix drive bare die procurement for captive module assembly. EPA emissions standards under the Clean Air Act constrain fluorinated gas use in domestic etching operations. Idaho's Micron Technology facilities anchor persistent memory R&D outside East Asian supply clusters.
South Korea
Hwasung and Pyeongtaek semiconductor clusters absorb the majority of 3D XPoint and MRAM wafer output for hyperscale caching layers. The Ministry of Environment enforces carbon neutrality roadmap emissions controls parallel to EU F-Gas phase-down timelines. Samsung Electronics and SK Hynix achieve backward integration into EUV lithography and materials refining.
China
Yangtze Memory Technologies and domestic cloud operators expand procurement of locally sourced NAND flash for state-backed data center buildouts. MIIT industrial policy directs capital toward memory self-sufficiency targets under dual carbon goals. Shanghai and Hefei foundry ecosystems concentrate advanced packaging capacity for persistent memory module assembly.
Germany
Automotive Tier-1 suppliers in Baden-Württemberg specify MRAM for powertrain controllers requiring ISO 26262 functional safety compliance. ECHA REACH restrictions and RoHS substance limits extend qualification timelines for new persistent memory process nodes. Dresden's silicon Saxony cluster hosts Infineon Technologies fabrication for automotive-qualified non-volatile memory.
Japan
Tokyo Electron and Shin-Etsu Chemical supply EUV photoresist and silicon wafer substrates to global foundry customers. METI industrial competitiveness framework subsidizes next-generation memory technology development. Kyushu's Kumamoto region concentrates specialty chemical production for etching gas alternatives under national carbon neutrality targets.
Storage Class Memory Market Competitive Environment
Global majors compete with regional champions across foundry capacity and materials integration. The vendor base organizes around three tiers: captive integrated device manufacturers with in-house wafer fabrication, fabless specialists licensing core cell technology, and memory module assemblers sourcing bare die for system integration. Strategic moves concentrate on EUV lithography talent acquisition and atomic layer deposition process licensing to circumvent fluorinated gas constraints.
Among integrated device manufacturers, Samsung Electronics, SK Hynix, and Micron Technology exemplify the captive fabrication archetype with control over wafer starts from substrate through module test. Everspin Technologies and NVE Corporation occupy positions within the specialty non-volatile memory tier focused on magnetoresistive architectures. Intel represents the systems-level entrant leveraging processor-memory co-design for persistent memory DIMM deployment.
| Leading Market Players |
|---|
| Intel |
| GSI Technology |
| Samsung Electronics |
| eMemory Technology |
| NVE Corporation |
| SK Hynix |
| Everspin Technologies |
| Infineon Technologies |
| Micron Technology |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between automotive-qualified MRAM and commodity NAND flash manifests in both module pricing and foundry allocation priority. Tier-1 automotive suppliers absorb 40-60% price premiums for ISO 26262-traceable die, while hyperscale data center operators negotiate bare-die offtake contracts that strip out traditional module-level service bundling entirely.
Pricing Analysis
Warranty and service bundling splits sharply between captive integration and third-party module supply. Three-tier pricing structure across premium, standard, and economy levels reflects endurance specification and temperature-grade certification, with automotive powertrain controllers commanding the highest tier. Price differentiation hinges on foundry location and REACH compliance documentation, with EU-sourced die carrying documentation premiums. Pricing pressure stems from DRAM spot-price volatility collapsing the latency-cost gap for caching workloads. Enterprise storage buyers exhibit highest price sensitivity, while automotive functional safety mandates render Tier-1 suppliers relatively inelastic.
Supply Chain Analysis
Dual-sourcing requirements from hyperscale buyers mandate multi-supplier qualification for bare die across South Korea, the United States, and Japan. Raw material dependencies center on high-purity silicon metal from Norway and Germany, EUV-grade photoresist from Japan, and tungsten concentrate from South Korea for mask blank production. Supply chain risk concentrates in single-source vulnerability for EUV lithography equipment and specialized etching gases constrained by the EU F-Gas Regulation. Distribution runs through direct foundry relationships for captive integration, bypassing traditional memory distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where the EU F-Gas Regulation phase-down erects a barrier-to-entry moat for foundries with capitalized atomic layer deposition capabilities.
For Market Incumbents: Deepen backward integration into EUV photoresist and mask blank supply to defend against etching chemistry substitution delays. Secure captive tungsten and rare earth precursor streams from Sangdong and Baotou to insulate MRAM tunnel junction production from export restriction risk. Prioritize greenfield foundry construction with integrated renewable power to satisfy South Korean Ministry of Environment emissions controls ahead of competitor qualification timelines. For New Entrants and Emerging Players: Direct-to-hyperscale digital channels bypass entrenched memory distributor relationships and unlock bare-die procurement contracts with Meta, Google, and Microsoft captive integration facilities. Target Idaho-based R&D anchoring for persistent memory architectures outside East Asian supply clusters, exploiting Micron Technology's materials science ecosystem for talent acquisition. Lead with CXL 2.0 byte-addressable interface specialization to capture firmware rearchitecture demand from legacy memory controller vendors. For Investors and Strategic Acquirers: Re-rating potential sits with atomic layer deposition process licensors given EU F-Gas Regulation phase-down timelines accelerating technology substitution. Long-term viability favors foundries with demonstrated REACH and RoHS compliance documentation and established relationships with automotive Tier-1 suppliers. Watch EUV lithography talent migration from ASML and incumbent foundries as the inflection signal for process development capability scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Atomic Layer Deposition Licensing | EU F-Gas Regulation compliance enables continued European foundry operation without etching gas substitution delays. |
| Automotive Functional Safety Certification | ISO 26262 traceability unlocks powertrain controller supply contracts with Volkswagen and Toyota Tier-1 networks. |
| Hyperscale Bare-Die Direct Supply | Meta and Microsoft captive integration facilities displace traditional memory module distributor margins. |
| EUV Photoresist Backward Integration | Shin-Etsu Chemical supply anchoring insulates against Japan export restriction scenarios. |
| CXL 2.0 Protocol Acceleration | Hwasung cluster deployments validate byte-addressable persistent memory for real-time analytics workloads. |
Study Parameters
Independent corroboration across foundry operations executives, hyperscale data center procurement officers, automotive Tier-1 supplier quality directors, and EUV lithography equipment specialists underwrites the qualitative findings. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade data, EPA emissions disclosures, and ECHA REACH registration databases. Bottom-up wafer start projections and top-down memory module shipment triangulation anchored the market sizing framework.
Comparable-period anchoring to historical persistent memory adoption curves calibrated the projection horizon across product type, end user, technology, and application dimensions. Segmentation modeling incorporated interface architecture adoption patterns, foundry location compliance clusters, and workload-specific latency requirements. CAGRs derived from fitted adoption curves and foundry capacity expansion announcements, with EUV lithography tool delivery schedules and fluorinated gas substitution timelines as critical forecast inputs.
The model holds under stable EU F-Gas Regulation phase-down timelines and continued hyperscale capex commitment to persistent memory tiers; deviation in etching chemistry substitution rates or DRAM spot-price collapse would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
APAC SSD Caching Market
Data Storage
Middle East Data Center Storage Market
Data Storage
North America SSD Caching Market
Data Storage
USB Key Market
Data Storage
Serial EEPROM Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Powered Storage Devices Market
Data Storage
Global Hard Disk Drive (HDD) Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Object-Based Storage Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
China Solid-State Drive Market
Data Storage
Enterprise-Class Hybrid Storage Market