
 Powered Storage Devices Market | 2026-2036
Powered Storage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Powered Storage Devices Market Analytics
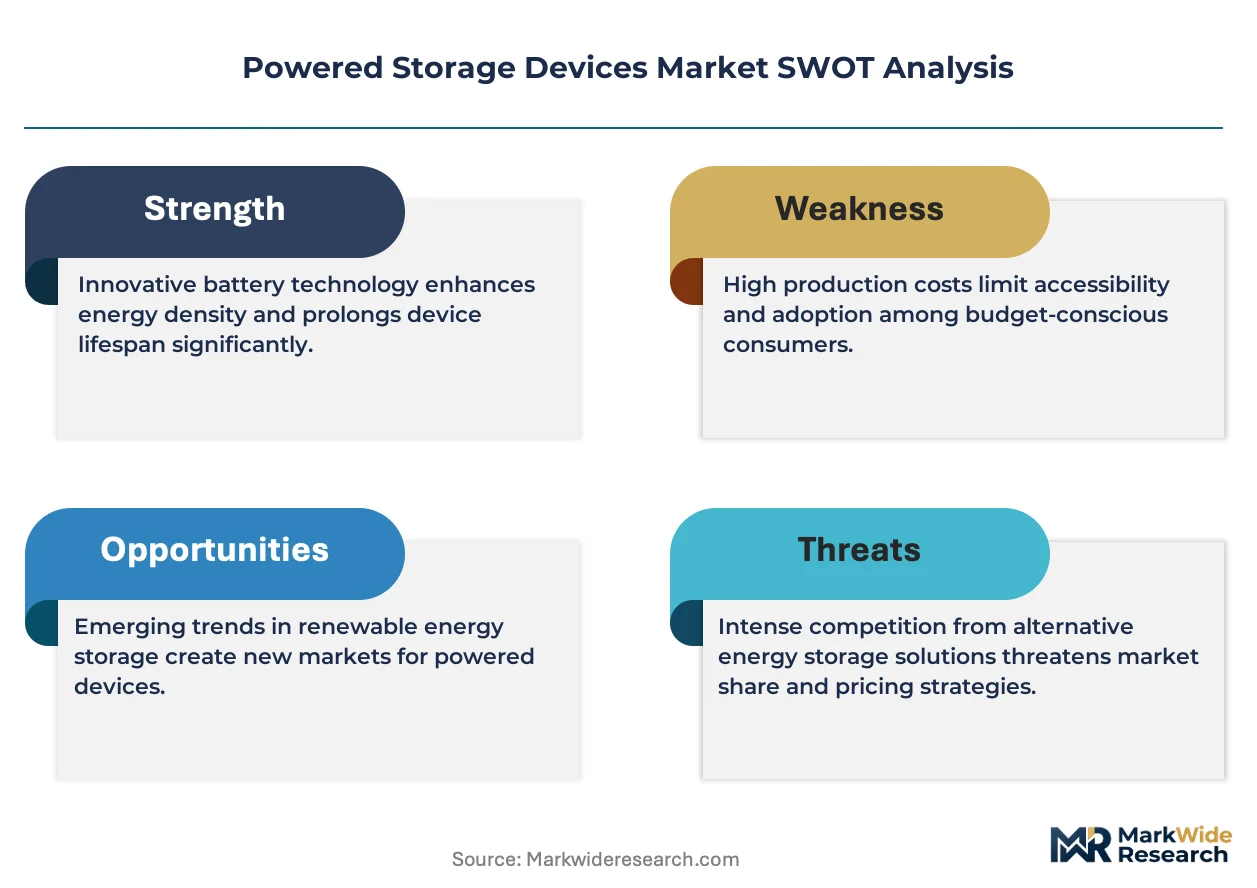
Utility-scale renewable integration is restructuring procurement priorities across the powered storage landscape. AES Corporation leverages its fluence partnership to dominate grid-scale battery installations in North American ISO markets. LG Chem sustains cathode material leadership through captive supply of nickel-manganese-cobalt precursors. General Electric anchors its position with integrated power electronics and turbine-to-storage control systems.
Powered storage devices encompass electrochemical and solid-state systems engineered to store electrical energy for subsequent discharge, typically operating at voltages from 48V to 1500V DC with cycle efficiencies exceeding 85%. These systems buffer intermittency from renewable generation, stabilize grid frequency, and provide backup power for critical infrastructure. Solid-state storage leads technology investment due to superior energy density and thermal stability versus magnetic storage alternatives. Enterprise end users represent the fastest-expanding demand pool as hyperscale facilities consolidate procurement around 8TB-class modular battery racks. Flash storage occupies premium margin tiers in consumer and industrial edge applications where form factor constraints dominate design.
FERC Order 841 and state-level clean portfolio standards in California, New York, and Texas reshape market access rules for storage resources participating in wholesale electricity markets. EPA emissions guidelines and OSHA battery safety standards constrain installation practices and fire suppression system specifications. NHTSA crashworthiness protocols for electric vehicle battery packs indirectly influence stationary storage enclosure designs. Stakeholders must monitor evolving interconnection queue reforms and capacity market rule changes that determine project revenue stacks.
Market Dynamics
AI training clusters are forcing hyperscale data centers to triple rack-level power density, driving procurement of 1500V DC solid-state arrays over legacy 48V architectures and compressing replacement cycles for thermal management infrastructure.
Growth Catalysts
- FERC Order 841:Wholesale market participation rules now compensate battery resources for frequency regulation and capacity services in US ISO markets.
- Lithium iron phosphate chemistry:Extended cycle life beyond 6000 cycles at 80% depth of discharge enables grid-scale deployments with 20-year amortization profiles.
- China utility mandates:Provincial renewable integration quotas require co-located storage for new solar and wind installations exceeding 50MW capacity.
Market Restraints
- Cathode material concentration:Nickel-manganese-cobalt precursor supply concentrates in Chinese refining corridors, exposing procurement to export license volatility.
- Cell thermal runaway:Lithium-ion energy density limits constrain packing density in urban substations where fire suppression footprint competes for real estate.
- Interconnection queue backlog:US transmission study timelines now exceed 36 months for utility-scale battery projects, freezing capital deployment.
Strategic Opportunities
- India grid modernization:Central Electricity Authority mandates for 27GW non-fossil capacity by 2030 create procurement corridors for 4-hour duration battery systems.
- Behind-the-meter C&I:Commercial and industrial peak shaving applications remain underpenetrated where tariff structures lack real-time price exposure.
- Solid-state electrolyte convergence:Sulfide-based ceramic separators are converging with silicon anode architectures to eliminate flammable liquid electrolytes in next-generation cells.
Industry Challenges
- Battery management system firmware:Functional safety certification to IEC 61508 SIL-2 standards requires 18-month validation cycles that delay product launches.
- Electrolyte supply reconfiguration:Transition from carbonate solvents to ionic liquid formulations forces solvent producers to retool purification lines without guaranteed offtake volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powered Storage Devices Market |
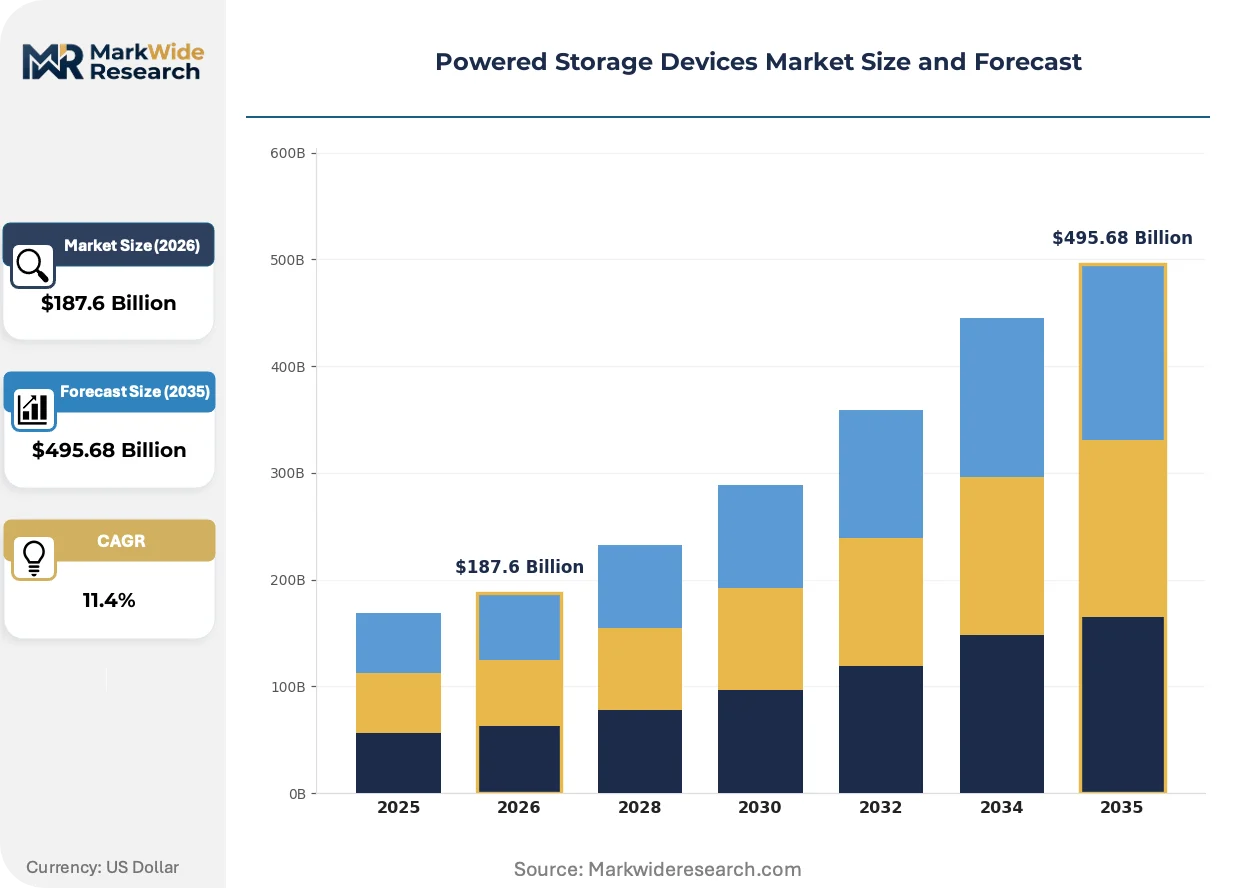
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $495.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Hard Drives, USB Flash Drives, SSDs, Hybrid Drives End User: Individuals, Small Businesses, Enterprises, Government Agencies Technology: Magnetic Storage, Solid-State Storage, Optical Storage, Flash Storage Capacity: 1TB, 2TB, 4TB, 8TB |
| Companies Covered | AES Corporation, Convergent Energy and Power, Eos Energy Storage, General Electric, Hawaiian Electric Company, LG Chem, SandC Electric Company, Sonnen, Western Digital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powered Storage Devices Market Evolving Landscape
Silicon carbide power electronics and immersive cooling architectures are collapsing thermal overhead in high-voltage battery racks, enabling footprint reduction that reshapes data center floor planning and substation civil works.
Solid-state lithium-metal cells are converging with dry electrode coating processes to eliminate toxic solvent recovery systems and cut electrode drying energy by 40%. Automotive cell producers are piloting these lines for 2026 stationary storage derivatives. The structural consequence is converging with gigafactory capital efficiency targets that now prioritize process intensification over scale replication.
The EU Battery Regulation's carbon footprint declaration requirements are forcing cell producers to document upstream mining emissions and recycling content percentages. Industrial consequence includes supply chain re-documentation costs exceeding 2% of cell value for non-EU producers. Grid-scale integrators serving European utilities are now requiring passport-compliant cells for 2027 delivery windows.
Hyperscale buyers are consolidating procurement around 8TB-class modular racks with 15-year service agreements that unbundle hardware from software-defined charge management. Traditional channel distributors lose margin to direct manufacturer relationships. This pattern concentrates in Northern Virginia and Frankfurt data center clusters where single buyers represent multi-gigawatt annual demand.
Powered Storage Devices Market Segmentation
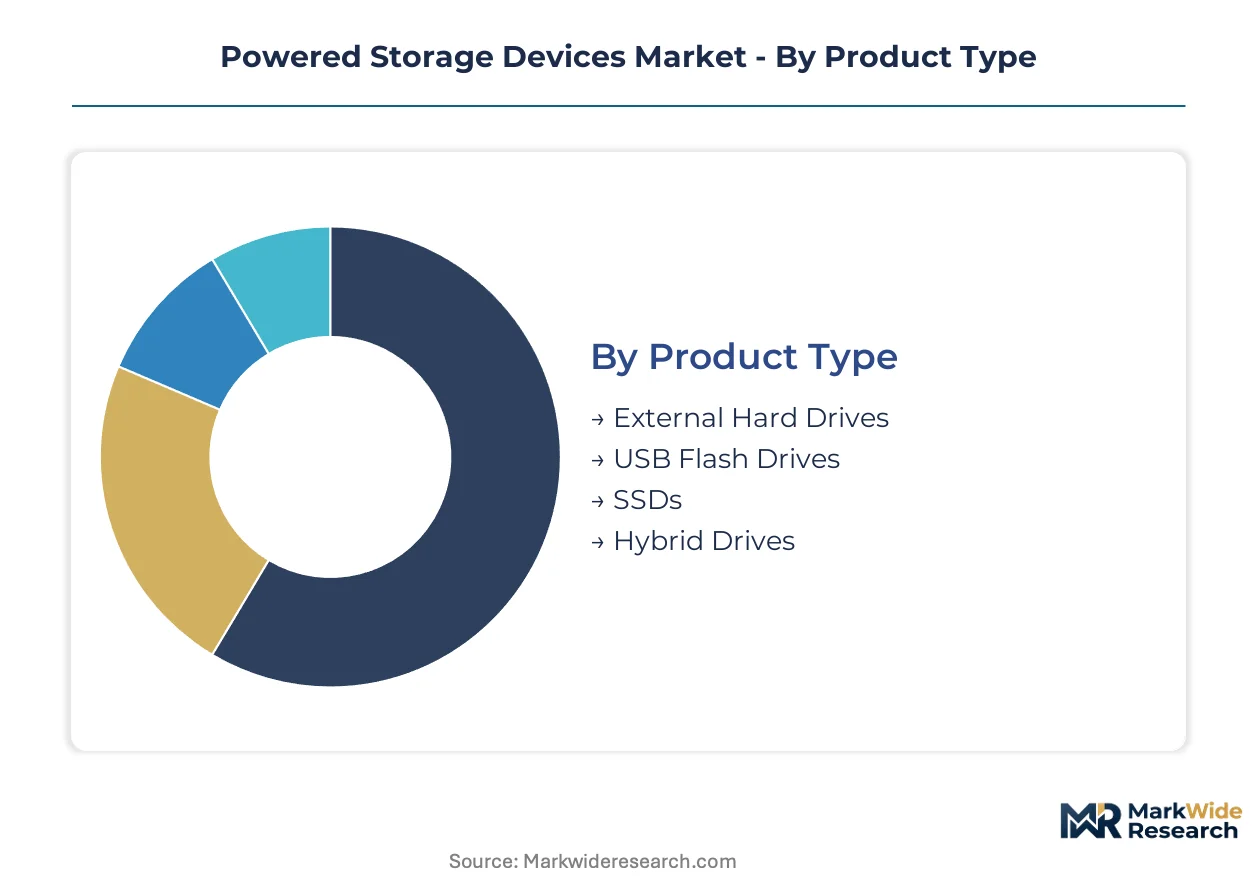
Procurement patterns across powered storage devices diverge sharply by application voltage, cycle duty, and thermal envelope. Understanding segment boundaries clarifies why hyperscale buyers consolidate around 1500V DC solid-state architectures while industrial edge deployments tolerate 48V magnetic alternatives.
Product Type:
Replacement cycles compress fastest where power density requirements outstrip legacy thermal management capacity.
- SSDs:Solid-state arrays operate at 1500V DC with cycle efficiencies exceeding 85%, eliminating mechanical latency. Hyperscale data centers in Northern Virginia and Frankfurt now specify 8TB-class modular racks with 15-year service agreements, forcing direct manufacturer relationships that bypass traditional distributors.
- External Hard Drives:Magnetic platters in sealed enclosures deliver cost-per-gigabyte advantages for archival workloads. Consumer backup applications and small-business cold storage in secondary cities sustain procurement volumes despite slower access speeds.
- USB Flash Drives:Portable NAND-based devices serve field technicians and mobile professionals requiring offline data transport. Form factor constraints dominate design specifications.
- Hybrid Drives:Dual-architecture units combine magnetic platters with NAND cache tiers for mid-market workstations. Boot-time acceleration justifies premium positioning over pure magnetic alternatives.
SSDs sit at the top of the volume ranking, with USB flash drives climbing the fastest.
End User:
Customer procurement scale determines whether hardware unbundles from software-defined charge management.
- Enterprises:Hyperscale facilities consolidate procurement around 8TB-class modular battery racks with immersive cooling architectures. AI training clusters force triple rack-level power density, compressing replacement cycles for thermal infrastructure.
- Small Businesses:Price-sensitive buyers prioritize cost-per-gigabyte over performance specifications. On-premise server refresh cycles extend to five years where cloud migration remains incomplete.
- Individuals:Consumer procurement concentrates in 1-2TB external drives for media archives and gaming libraries. Retail channel dependence sustains distributor margins.
- Government Agencies:Classified workloads drive demand for air-gapped solid-state systems with hardware encryption modules. FIPS 140-2 certification requirements extend procurement timelines.
Enterprises command the dominant revenue share, while government agencies expand most rapidly under cybersecurity mandates.
Technology:
Energy density and thermal stability separate premium tiers from commodity positioning.
- Solid-State Storage:Lithium-metal cells with sulfide-based ceramic separators eliminate flammable liquid electrolytes. Grid-scale integrators serving European utilities now require EU Battery Regulation passport-compliant cells.
- Flash Storage:NAND-based systems occupy premium margin tiers where form factor constraints dominate design. Consumer and industrial edge applications sustain demand despite higher cost-per-gigabyte.
- Magnetic Storage:Rotating platters retain cost advantages for sequential read workloads. Cold archival applications in regulated industries preserve installed base.
- Optical Storage:Write-once media serves legal discovery and compliance archiving with tamper-evident properties. Niche demand concentrates in healthcare and financial services.
Solid-state storage leads technology investment, with flash storage gaining share fastest in edge computing deployments.
Capacity:
Modular rack architectures now standardize around 8TB building blocks for serviceability and thermal uniformity.
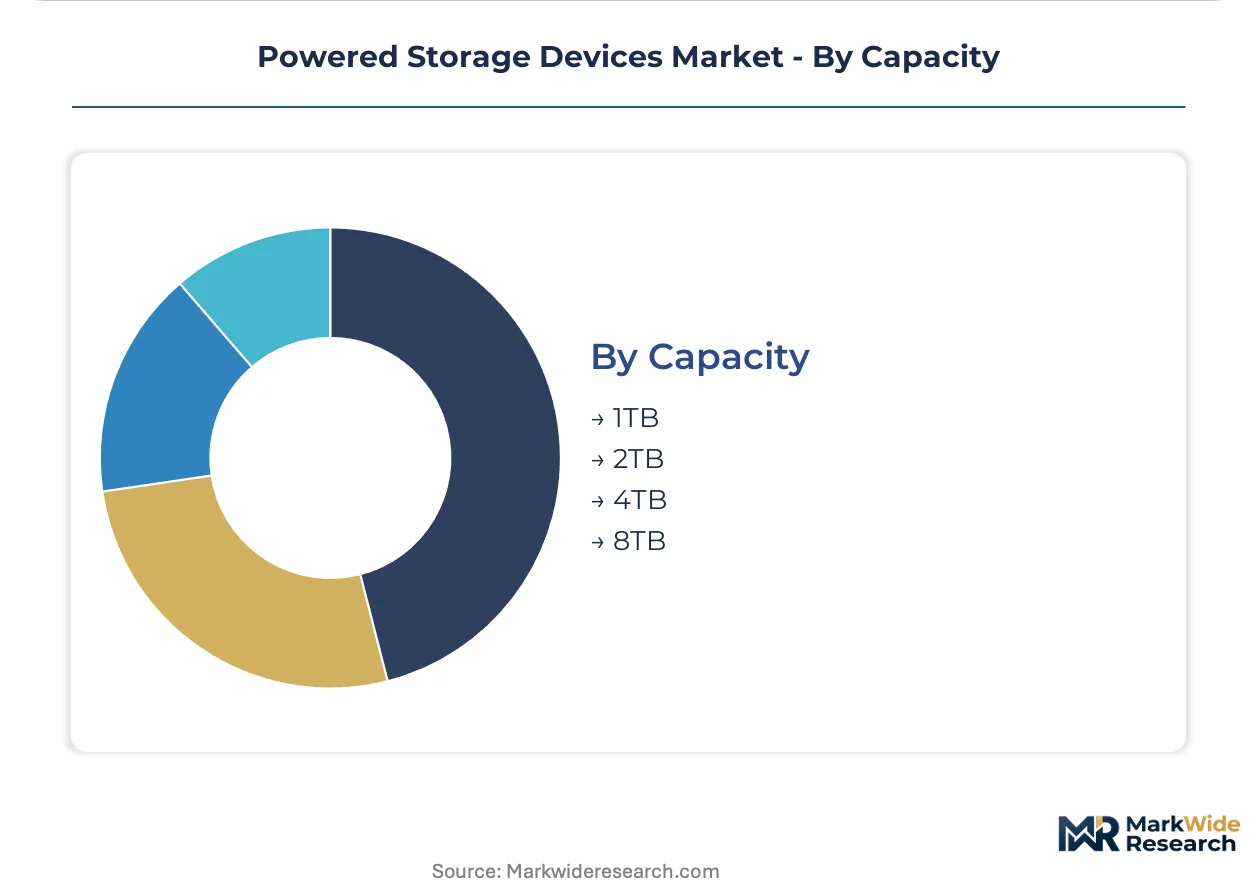
- 8TB:Modular racks with silicon carbide power electronics enable footprint reduction that reshapes data center floor planning. Hyperscale buyers unbundle hardware from software-defined charge management.
- 4TB:Mid-tier workstations and small-business servers balance cost against expansion headroom. Channel distributors retain margin influence in this segment.
- 2TB:Entry-level enterprise laptops and high-end consumer devices sustain volume. Price compression accelerates as NAND oversupply persists.
- 1TB:Budget consumer laptops and embedded industrial controllers dominate offtake. Lowest absolute price points preserve accessibility.
8TB configurations anchor hyperscale procurement, with 4TB systems expanding most quickly in mid-market enterprise refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's hyperscale data center cluster commands the largest procurement volumes for 1500V DC solid-state arrays, with Frankfurt, London, and Singapore forming secondary demand poles. Utility-scale battery deployments concentrate in jurisdictions with renewable integration mandates and wholesale market participation rules. Regulatory frameworks and industrial clustering patterns determine where capital flows fastest.
United States
FERC Order 841 enables battery resources to capture frequency regulation and capacity payments across ISO markets. State-level clean portfolio standards in California, New York, and Texas reshape project revenue stacks. Northern Virginia's data center corridor now represents multi-gigawatt annual demand as AI training clusters force triple rack-level power density.
China
Provincial renewable integration quotas require co-located storage for new solar and wind installations exceeding 50MW capacity. State-backed energy storage mandates accelerate utility-scale deployments through the Central Electricity Authority directive. Yangtze River Delta manufacturing clusters supply lithium iron phosphate cells with extended cycle life beyond 6000 cycles.
Germany
The EU Battery Regulation's carbon footprint declaration requirements force cell producers to document upstream mining emissions and recycling content percentages. Industrial clusters in North Rhine-Westphalia and Bavaria host grid-scale integrators now requiring passport-compliant cells for 2027 delivery windows. Behind-the-meter commercial and industrial peak shaving applications remain underpenetrated where tariff structures lack real-time price exposure.
India
Central Electricity Authority mandates for 27GW non-fossil capacity by 2030 create procurement corridors for 4-hour duration battery systems. State-level renewable purchase obligations in Maharashtra, Gujarat, and Karnataka drive co-located storage procurement. Telangana's emerging data center cluster imports solid-state arrays for hyperscale facilities serving domestic cloud workloads.
Japan
METI's grid stability standards prioritize battery resources for frequency regulation in islanded utility territories. Automotive cell producers in Kansai and Chubu regions pilot dry electrode coating processes for 2026 stationary storage derivatives. Silicon carbide power electronics from Nagoya industrial corridors enable thermal overhead reduction in high-voltage battery racks.
Powered Storage Devices Market Competitive Landscape
Capacity expansion dominates the current landscape as producers scale lithium iron phosphate and solid-state electrolyte lines to serve hyperscale and utility procurement. The vendor base separates into three tiers: integrated power electronics specialists with turbine-to-storage control systems, cathode material producers with captive precursor supply, and pure-play battery integrators with software-defined charge management. Strategic archetypes include utility-scale project developers, automotive cell producers pivoting to stationary derivatives, and data center infrastructure suppliers. M&A activity concentrates on battery management system firmware capabilities and solvent-to-ionic liquid electrolyte reconfiguration assets.
Among US-based energy infrastructure developers, AES Corporation anchors the utility-scale project developer archetype through its fluence partnership in North American ISO markets. LG Chem represents the cathode material leadership archetype with captive supply of nickel-manganese-cobalt precursors. General Electric occupies the integrated power electronics position with turbine-to-storage control system offerings.
| Leading Market Players |
|---|
| AES Corporation |
| Convergent Energy and Power |
| Eos Energy Storage |
| General Electric |
| Hawaiian Electric Company |
| LG Chem |
| SandC Electric Company |
| Sonnen |
| Western Digital |
| Others |
Value Network & Pricing Analysis
Lithium carbonate price indices cascading through cathode precursor contracts compress margins for non-integrated cell producers while amplifying pricing power for suppliers with captive mining assets. Input cost volatility feeds directly into three-tier pricing structures across premium certified, standard industrial, and economy consumer tiers.
Pricing Analysis
Input-cost pass-through from nickel-manganese-cobalt precursor markets dominates contract negotiations, with cathode material volatility transmitted through quarterly price adjustment clauses. Pricing stratifies across premium, standard, and economy tiers based on cycle life certification and thermal management specifications. Cost compression in the economy tier intensifies because NAND flash oversupply persists from expanded wafer capacity. Small-business buyers exhibit highest price sensitivity, while hyperscale data center operators prioritize 15-year total cost of ownership over unit acquisition cost.
Supply Chain Analysis
EU Battery Regulation passport compliance gates supplier qualification, forcing documentation of upstream mining emissions and recycling content percentages before contract eligibility. Manufacturing concentrates in China, South Korea, and Japan, with Yangtze River Delta clusters supplying lithium iron phosphate cells and Kansai producers piloting dry electrode coating. Raw material dependencies center on lithium carbonate, nickel sulfate, and cobalt hydroxide refined through Chinese processing corridors. Single-source vulnerability in cathode precursor supply exposes procurement to export license volatility. Distribution runs through direct manufacturer relationships for hyperscale buyers, while channel distributors retain influence in mid-market enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powered storage devices constitute a late-cycle quality market where procurement consolidation around 1500V DC solid-state architectures rewards suppliers with certified cycle life and immersive cooling integration.
For Market Incumbents: Deploy captive cathode material supply as the primary defensive lever against price volatility from Chinese refining corridors. Incumbent producers should consolidate battery management system firmware capabilities through targeted capability acquisitions, as IEC 61508 SIL-2 certification requirements extend validation cycles and raise barriers for unqualified entrants. Capacity addition in India serves as a secondary hedge against interconnection queue backlogs freezing North American capital deployment. For New Entrants and Emerging Players: Commercial and industrial peak shaving applications in tariff structures lacking real-time price exposure represent the most penetrable white-space target for specialized integrators. New entrants should prioritize behind-the-meter deployments in Germany and India where incumbent coverage remains thin. A software-defined charge management overlay on commodity hardware offers the clearest go-to-market angle against bundled legacy offerings. For Investors and Strategic Acquirers: Asymmetric upside sits with solid-state electrolyte specialists converging sulfide-based ceramic separators with silicon anode architectures. Long-term viability favors acquisition targets with process intensification capabilities over scale replication, as gigafactory capital efficiency priorities shift toward dry electrode coating and solvent elimination. The inflection signal to watch is EU Battery Regulation passport compliance becoming mandatory for grid-scale integrator procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expands lithium iron phosphate cell supply to serve utility-scale procurement corridors in India and China. |
| Backward Integration | Captures cathode precursor supply to insulate margins from nickel-manganese-cobalt price volatility. |
| Technology Licensing | Monetizes dry electrode coating processes for automotive producers pivoting to stationary storage derivatives. |
| Long-term Supply Agreement | Locks in hyperscale data center offtake for 8TB-class modular racks with 15-year service terms. |
| Green Certification Program | Secures EU Battery Regulation passport compliance for European utility procurement eligibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, hyperscale data center procurement leads, battery integrator project developers, and cathode material supply specialists with secondary validation. EIA electricity storage databases, FERC interconnection queue filings, IEA renewable integration reports, and SEC hyperscaler capex disclosures anchored the quantitative foundation. Bottom-up project-level aggregation and top-down market sizing triangulated volume estimates.
Segment-weighting across product type, end user, technology, and capacity dimensions shaped the analytical framework. CAGRs were derived from fitted growth curves applied to segment-level baselines, with technology adoption S-curves and regulatory mandate timelines serving as key forecast inputs. Regional grid stability standards and renewable integration quotas informed geographic allocation models.
Underlying measurement precision varies by segment; hyperscale enterprise procurement carries tighter precision than fragmented consumer backup applications. Forecasts reflect assumptions about interconnection queue clearance rates, cathode material supply elasticity, and solid-state electrolyte commercialization timelines. A model refresh is warranted upon material change in FERC Order 841 implementation scope or EU Battery Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Europe Flash Memory Market
Data Storage
Flash-Based Array Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Data Storage Market
Data Storage
Channel Storage Systems Market
Data Storage
Middle East Data Center Storage Market
Data Storage
NAND Flash Market
Data Storage
Blu-Ray Drive Market
Data Storage
Transparent Cache Market
Data Storage
NAND Flash Memory Market
Data Storage
AI Powered Storage Market
Data Storage
North America Next Generation Storage Market
Data Storage
Object-Based Storage Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Serial (SPI) NOR Flash Market
Data Storage
Universal Flash Storage Market