
 Global Purpose-Built Backup Appliance (PBBA) Market | 2026-2036
Global Purpose-Built Backup Appliance (PBBA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Purpose-Built Backup Appliance (PBBA) Market Foresight
The capital-intensity divergence between integrated systems vendors and point-product specialists is collapsing as cloud-integrated architectures commoditize hardware margins. Dell Technologies leverages its server-storage convergence to sustain integrated backup sales across enterprise accounts. International Business Machines Corporation anchors mainframe-attached tape libraries in regulated industries. Hewlett Packard Enterprise Company competes through composable infrastructure that embeds deduplication at the array level.
A purpose-built backup appliance is a dedicated hardware-software system engineered for data protection workflows, typically incorporating inline deduplication, compression algorithms, and native replication protocols to minimize recovery point objectives. These systems serve commercial and industrial users by isolating backup traffic from production networks and enforcing immutable snapshot retention. Disk-based and deduplication appliances dominate current revenue as enterprises retire tape-centric operations, while cloud-integrated and hybrid backup configurations capture the fastest expansion as organizations distribute retention across on-premises and multi-cloud tiers. Deployment models now favor hybrid systems over pure on-premises installations where latency constraints and compliance requirements overlap.
FDA 21 CFR Part 11 guidelines for electronic records, EU GDPR data retention and erasure mandates, and NIST SP 800-53 security controls collectively shape product certification requirements and procurement checklists for backup infrastructure. HIPAA safeguards for healthcare entities and SEC recordkeeping rules for broker-dealers further segment compliance-driven demand. Stakeholders must weigh immutable storage certifications against cloud egress economics when architecting long-term retention strategies.
Market Dynamics
Immutable storage architectures are compressing hardware refresh cycles as ransomware mandates from US financial regulators and EU data sovereignty laws force enterprises toward air-gapped, write-once backup infrastructure.
Growth Catalysts
- NIST SP 800-53 security controls:Federal contractors in the United States must deploy certified backup systems with cryptographic erasure capabilities, creating procurement pull through defense and civilian agencies.
- Healthcare data retention:HIPAA safeguards mandate seven-year retention for electronic protected health information, driving hospital systems toward dedicated appliances with native encryption.
- Japan's data localization:METI guidance on critical infrastructure protection compels domestic financial institutions to maintain on-premises backup arrays rather than cross-border cloud alternatives.
Market Restraints
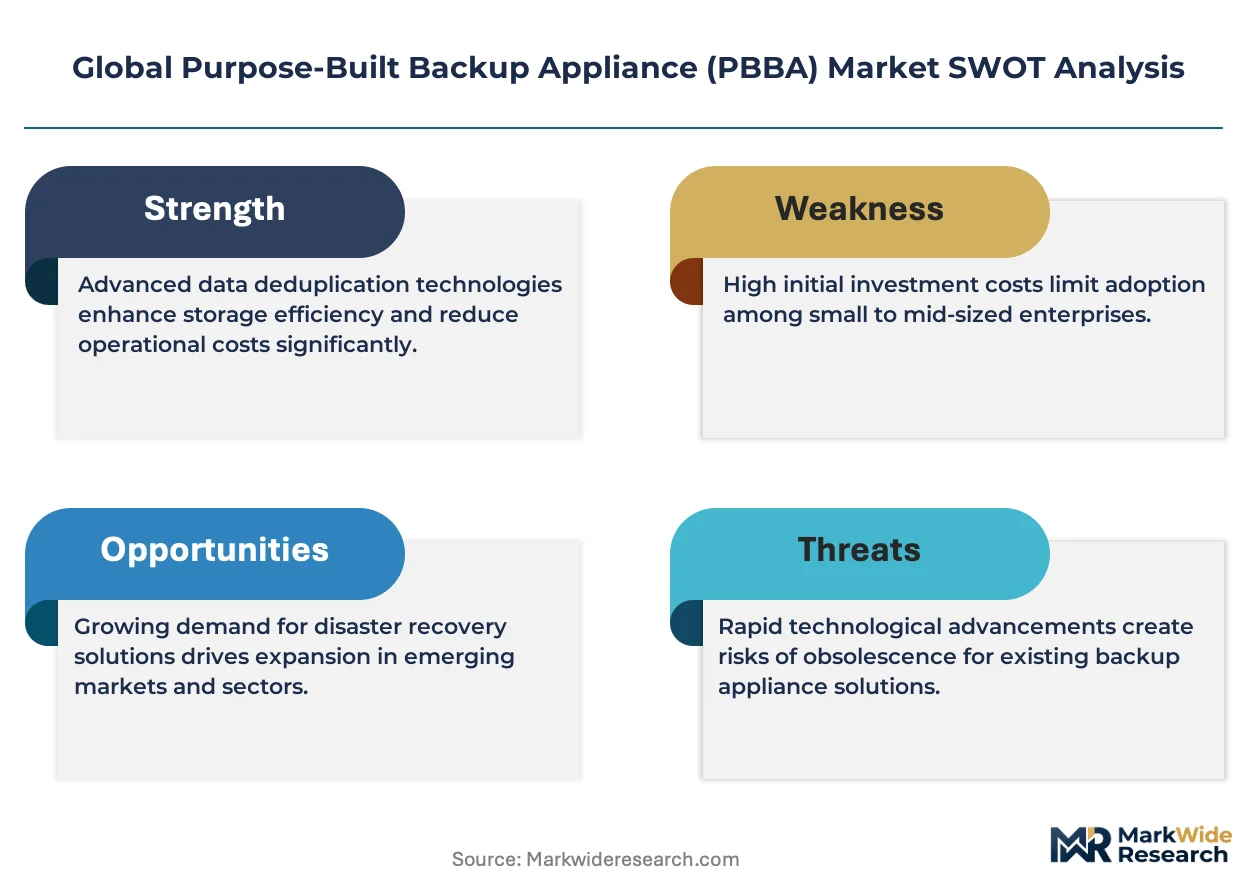
- Flash memory cost volatility:NAND pricing swings compress margins for all-flash backup appliance vendors, forcing hedging strategies or hybrid disk-flash configurations.
- Taiwan semiconductor concentration:Controller chip and SSD component sourcing relies heavily on single-source foundry capacity, exposing supply continuity risk.
- Tape library persistence:Long-term archival economics favor robotic tape for petabyte-scale cold storage, limiting disk-based appliance penetration in media and scientific computing.
Strategic Opportunities
- India's digital sovereignty push:RBI data localization rules for payment systems and SEBI market infrastructure mandates create first-mover advantage for localized appliance manufacturing.
- Edge-to-core orchestration:Convergence of Kubernetes-native backup controllers with hardware appliances enables unified policy management across distributed retail and manufacturing sites.
- EU CSRD sustainability disclosure:Corporate sustainability reporting requirements on data center energy intensity position efficient deduplication appliances as compliance instruments.
Industry Challenges
- Immutable storage certification timelines:Common Criteria EAL4+ evaluation for tamper-proof hardware modules extends product launch windows by 12-18 months.
- Legacy mainframe integration:IBM z/OS environments require proprietary tape emulation protocols, complicating vendor-neutral appliance deployments in banking and insurance.
- Multi-cloud orchestration complexity:Enterprises struggle to maintain consistent recovery point objectives across AWS, Azure, and on-premises tiers without specialized engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Purpose-Built Backup Appliance (PBBA) Market |
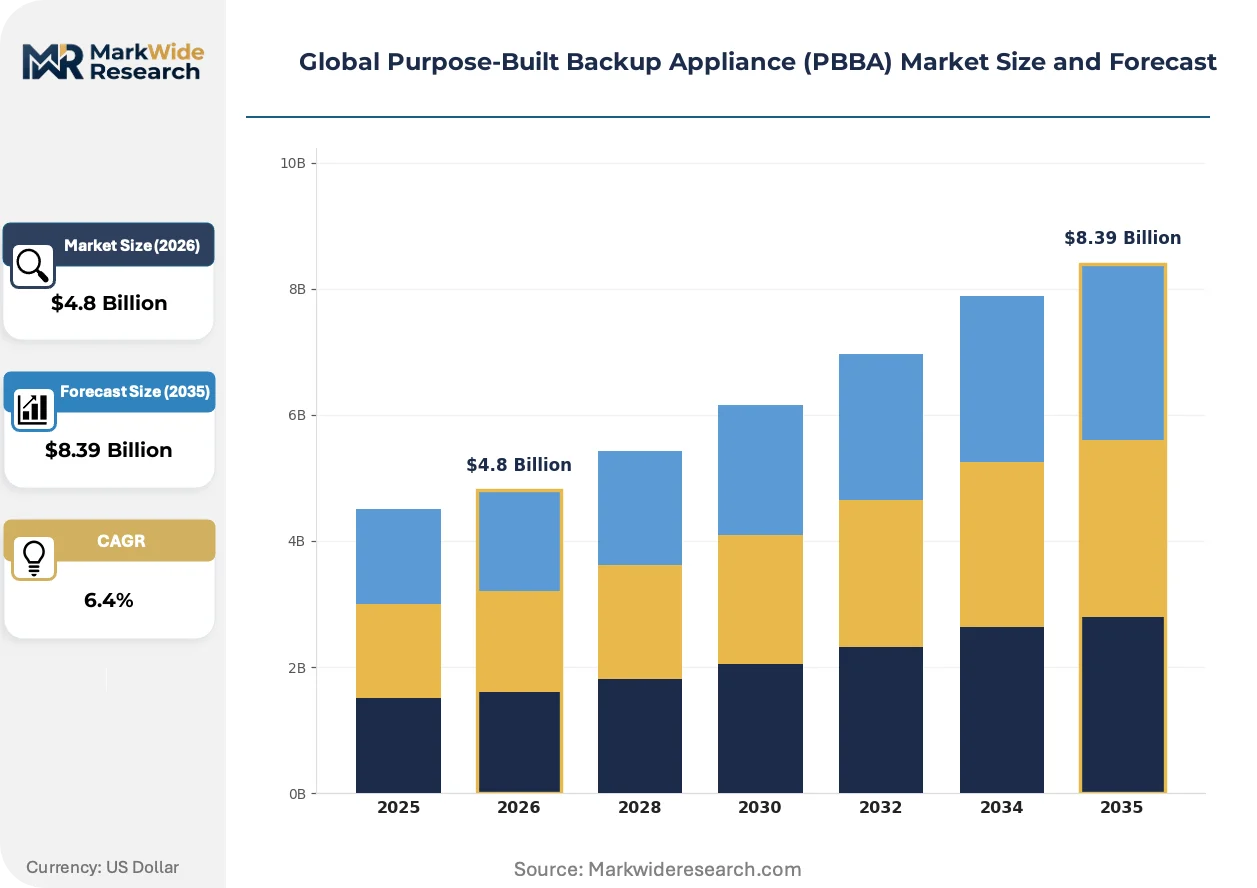
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disk-Based, Tape-Based, Hybrid Backup, Cloud-Integrated, Deduplication Appliances Deployment Model: On-Premises, Virtual, Cloud-Hosted, Hybrid Systems, Multi-Cloud Application: Data Archiving, Disaster Recovery, Continuous Data Protection, Compliance Management, Backup Optimization End User: Telecommunications, BFSI, Government Agencies, IT & Telecom Service Providers, Educational Institutions |
| Companies Covered | Dell Technologies, International Business Machines Corporation, Veritas Technologies, Hewlett Packard Enterprise Company, Quantum Corporation, NetApp, Commvault Systems, Veeam Software, Barracuda Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Purpose-Built Backup Appliance (PBBA) Market Shifts & Advancements
Software-defined backup controllers are decoupling data path intelligence from physical storage, enabling commodity hardware to host enterprise-grade deduplication and replication services previously locked to proprietary appliances.
Object storage backends with S3-compatible APIs are supplanting traditional NAS-attached backup targets in enterprise data centers. Pharmaceutical manufacturers under FDA 21 CFR Part 11 guidelines are migrating validation workloads to these scalable pools. This shift is compressing mid-range appliance margins as software licensing becomes the primary value capture mechanism.
EU GDPR Article 17 right-to-erasure mandates are forcing backup vendors to engineer cryptographic shredding capabilities that invalidate encrypted snapshots without full data rewrite. Healthcare providers and cloud service processors face the steepest compliance burden. German automotive suppliers have pioneered automated retention policy engines that propagate erasure commands across distributed appliance clusters.
Consumption-based financing models are displacing perpetual license purchases among mid-market enterprises. Managed service providers in the United States now bundle appliance hardware with operational support under single monthly fees. This restructuring concentrates buyer power with regional systems integrators and compresses direct vendor relationships.
Global Purpose-Built Backup Appliance (PBBA) Market Segmentation
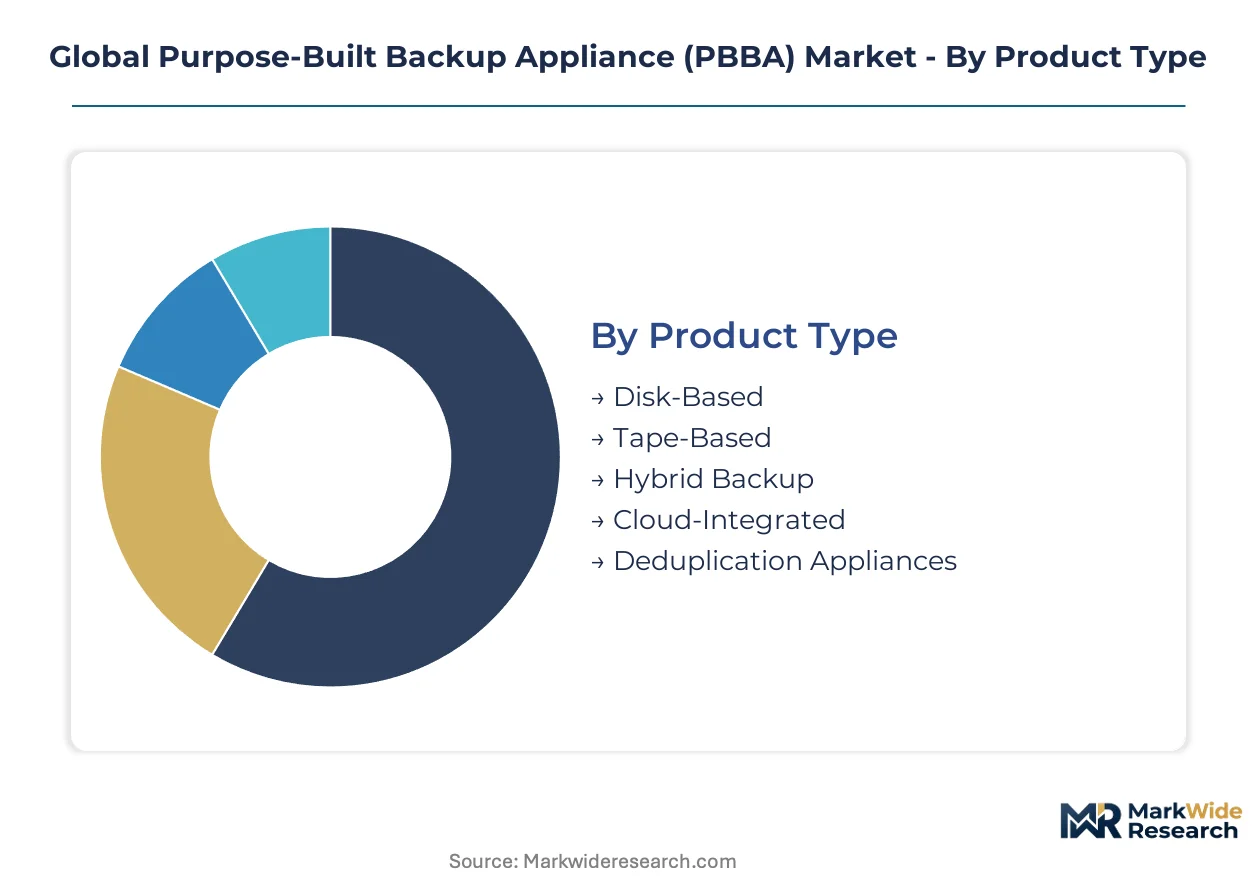
PBBA procurement specifications diver sharply across regulatory regimes, with immutable storage mandates from US financial regulators and EU data sovereignty laws dictating hardware architecture choices. Segmentation reveals how compliance-driven buyers prioritize air-gapped, write-once systems over cost-optimized alternatives.
Product Type:
FDA 21 CFR Part 11, EU GDPR Article 17, and NIST SP 800-53 each impose distinct technical requirements on backup infrastructure, forcing product-level specialization.
- Disk-Based:Inline deduplication and compression algorithms minimize physical footprint for primary backup workloads. Demand concentrates in United States hospital systems where HIPAA safeguards mandate encrypted, seven-year retention for electronic protected health information.
- Deduplication Appliances:Purpose-built hardware accelerates hash-based redundancy elimination at line speed. German automotive suppliers under EU CSRD sustainability disclosure rules favor these systems to reduce data center energy intensity and meet corporate reporting requirements.
- Tape-Based:Robotic libraries serve petabyte-scale cold archival for media and scientific computing where retrieval latency tolerance permits.
- Hybrid Backup:Combines disk front-end caching with tape back-end economics for tiered retention policies.
- Cloud-Integrated:Native replication protocols distribute snapshots across AWS, Azure, and on-premises tiers for distributed enterprises.
Established volume favors disk-based configurations; emerging adoption favors cloud-integrated architectures.
Deployment Model:
Latency constraints and data residency requirements segment procurement across customer scale and geographic dispersion.
- Hybrid Systems:Policy engines orchestrate retention across on-premises arrays and multi-cloud tiers, enabling consistent recovery point objectives. Japanese financial institutions under METI critical infrastructure guidance deploy these to satisfy data localization without sacrificing geographic redundancy.
- On-Premises:Air-gapped, physically isolated infrastructure serves ransomware recovery mandates from US SEC and CFTC for broker-dealers and futures commission merchants.
- Cloud-Hosted:Fully managed backup-as-a-service reduces capital burden for mid-market enterprises without dedicated storage engineering.
- Virtual:Software-defined controllers on commodity hardware decouple intelligence from physical storage.
- Multi-Cloud:Vendor-agnostic replication across AWS, Azure, and Google Cloud mitigates single-provider concentration risk.
Procurement patterns favor hybrid systems where compliance and flexibility overlap; pure cloud-hosted models gain traction in cost-constrained mid-market accounts.
Application:
Recovery time and recovery point objectives determine appliance specification, with regulatory deadlines hard-coding performance floors.
- Disaster Recovery:Synchronous replication and automated failover orchestration minimize business interruption. United States financial services firms drive hardware refresh cycles as ransomware recovery mandates tighten operational resilience requirements.
- Compliance Management:Immutable snapshot retention with cryptographic erasure capabilities satisfies EU GDPR Article 17 right-to-erasure and SEC recordkeeping rules. German healthcare providers and cloud processors face the steepest engineering burden for automated policy propagation.
- Data Archiving:Long-term retention with retrieval guarantees for litigation hold and audit response.
- Continuous Data Protection:Journal-based recovery to any point-in-time for transactional systems.
- Backup Optimization:Deduplication and compression ratio improvement for storage efficiency gains.
Mature spend concentrates in disaster recovery; compliance management exhibits the steepest expansion trajectory as regulatory scope broadens.
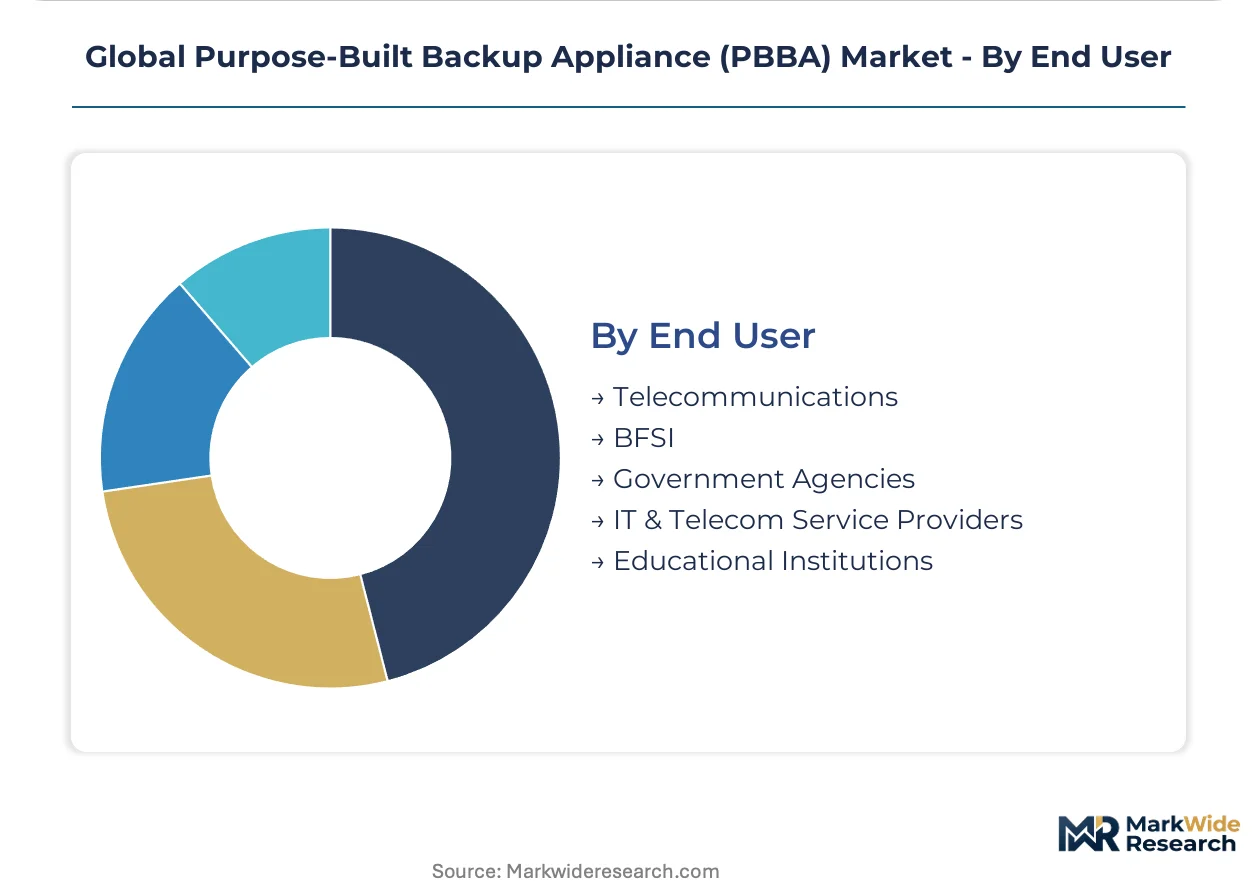
End User:
Sector-specific retention rules and threat models shape appliance configuration, with regulated industries commanding premium specifications.
- BFSI:Immutable storage with Common Criteria EAL4+ certification for tamper-proof hardware modules. India's RBI data localization rules for payment systems and SEBI market infrastructure mandates create localized manufacturing demand.
- Government Agencies:NIST SP 800-53 cryptographic erasure capabilities for federal contractors in defense and civilian agencies.
- Telecommunications:Distributed edge-to-core orchestration for retail and manufacturing site protection.
- IT & Telecom Service Providers:Multi-tenant backup platforms with customer-isolated policy domains.
- Educational Institutions:Cost-optimized configurations with consumption-based financing from regional systems integrators.
Revenue concentration sits with BFSI procurement; government agencies represent the fastest-climbing segment as federal cybersecurity frameworks harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in purpose-built backup appliances tilt toward deficit positions in data-sovereignty-conscious economies, with localized manufacturing incentives reshaping import substitution patterns across major consuming markets.
United States
Financial services procurement drives hardware refresh cycles as SEC and CFTC ransomware recovery mandates tighten operational resilience requirements. NIST SP 800-53 security controls compel federal contractors to deploy certified backup systems with cryptographic erasure capabilities. The New York-Washington corridor concentrates demand from defense agencies and broker-dealers seeking air-gapped infrastructure.
Germany
Automotive suppliers under EU CSRD sustainability disclosure rules favor deduplication appliances to reduce data center energy intensity and meet corporate reporting requirements. EU GDPR Article 17 right-to-erasure mandates force engineering of cryptographic shredding capabilities across distributed appliance clusters. Bavaria hosts pioneering automated retention policy engines that propagate erasure commands across manufacturing sites.
Japan
METI guidance on critical infrastructure protection compels domestic financial institutions to maintain on-premises backup arrays rather than cross-border cloud alternatives. Data localization requirements from the country's central bank and financial regulator shape procurement specifications for hybrid systems. The Tokyo-Osaka axis concentrates demand from megabanks and insurance groups seeking geographic redundancy without sovereignty compromise.
India
RBI data localization rules for payment systems and SEBI market infrastructure mandates create first-mover advantage for localized appliance manufacturing. The country's digital sovereignty push accelerates domestic production capacity for backup infrastructure serving financial and government sectors. Maharashtra and Karnataka emerge as manufacturing clusters where vendors establish assembly operations to satisfy public sector procurement preferences.
United Kingdom
Post-Brexit data adequacy arrangements with the EU sustain demand for backup infrastructure satisfying both UK and continental retention requirements. Financial services firms in the City of London maintain dual-compliance architectures as regulatory divergence risks accumulate. The Southeast England technology corridor hosts cloud-integrated deployment models spanning on-premises and multi-cloud tiers for multinational enterprises.
Global Purpose-Built Backup Appliance (PBBA) Market Competitive Landscape
Concentration sits with diversified infrastructure conglomerates that leverage server-storage convergence to sustain integrated backup sales across enterprise accounts. The vendor base spans three tiers: integrated systems specialists with full-stack data center portfolios, point-product backup software vendors seeking hardware partnerships, and tape-centric archival specialists defending long-term cold storage economics. Strategic moves center on cloud-integrated architecture development and consumption-based financing model expansion to capture mid-market accounts.
Within the integrated systems tier, Dell Technologies and Hewlett Packard Enterprise Company exemplify hardware-software convergence strategies that embed deduplication at the array level. International Business Machines Corporation occupies a distinct position anchoring mainframe-attached tape libraries in regulated industries requiring proprietary protocol support. These three entities represent divergent responses to cloud-integrated commoditization pressure.
| Leading Market Players |
|---|
| Dell Technologies |
| International Business Machines Corporation |
| Veritas Technologies |
| Hewlett Packard Enterprise Company |
| Quantum Corporation |
| NetApp |
| Commvault Systems |
| Veeam Software |
| Barracuda Networks |
| Others |
Supply & Pricing Matrix
Ninety-day controller chip lead times concentrate procurement leverage with Taiwan-based foundries, amplifying pricing power for integrated appliance vendors while compressing margins for assembly-only competitors. This inventory-to-pricing dynamic intensifies as NAND flash cost volatility forces hybrid disk-flash configurations into mainstream backup architectures.
Pricing Analysis
The customization-premium spread separates configured-to-order appliances with Common Criteria EAL4+ certification from standard disk-based configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in mid-market segments is intensifying because consumption-based financing models displace perpetual licenses. Educational institutions and regional systems integrators exhibit highest price sensitivity, while BFSI procurement teams prioritize immutable storage certifications over unit economics.
Supply Chain Analysis
Strategic-stockpile preferences dominate controller chip procurement as Taiwan semiconductor concentration exposes single-source vulnerability. Component sourcing draws from Taiwan, South Korea, and Japan for SSD controllers, NAND flash, and specialized ASICs. Tariff exposure on cross-border hardware shipments compounds logistics chokepoint risks through major port corridors. Distribution runs through direct enterprise sales teams for large accounts and regional systems integrators for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PBBA market functions as a service-attach opportunity where managed backup-as-a-service recurring revenue layers expand faster than hardware depreciation cycles. Operational support bundling now captures margin pools previously locked to perpetual license transactions.
For Market Incumbents: Shield installed base relationships through backward integration into controller chip supply chains, reducing Taiwan foundry dependency. Deepen certification investment in Common Criteria EAL4+ evaluation pipelines to extend product launch windows ahead of cloud-native substitute technologies. Channel control through exclusive systems integrator partnerships defends against software-defined backup controller commoditization. For New Entrants and Emerging Players: Anchor in India's localized manufacturing clusters where RBI data localization rules and SEBI market infrastructure mandates create first-mover advantage for domestic assembly operations. Target edge-to-core orchestration white space in distributed retail and manufacturing sites underserved by centralized appliance architectures. Kubernetes-native backup controller positioning enables unified policy management differentiation against legacy hardware vendors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified infrastructure conglomerates seeking to divest non-core backup appliance divisions amid cloud-integrated commoditization pressure. Five-to-ten year viability hinges on software licensing revenue transition from hardware-locked perpetual models. Monitor hyperscaler backup partnership announcements as inflection indicator for cloud-native substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Immutable Storage Certification Investment | Common Criteria EAL4+ evaluation satisfies SEC and CFTC ransomware recovery mandates for broker-dealers. |
| Cloud-Integrated Architecture Development | Native AWS and Azure replication protocols capture hybrid deployment model expansion in distributed enterprises. |
| Consumption-Based Financing Expansion | Monthly operational support bundling concentrates buyer power with regional systems integrators in mid-market accounts. |
| Edge-to-Core Orchestration Platform | Kubernetes-native controllers enable unified policy management across manufacturing and retail site protection. |
| Localized Manufacturing Footprint | Domestic assembly in Maharashtra and Karnataka satisfies India's RBI and SEBI data sovereignty procurement preferences. |
Research Methodology
The analysis maps disk-based, deduplication, tape-based, hybrid backup, and cloud-integrated product categories, each validated through infrastructure procurement officers, data center operations directors, and channel partner sales leads. Primary interviews with storage engineering teams and compliance officers at BFSI and healthcare organizations combined with secondary validation from SEC 10-K filings, hyperscaler capex disclosures, and NIST cybersecurity framework documentation. Bottom-up unit shipment estimates and top-down revenue triangulation anchored segmentation-specific projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, deployment architecture, application workload, and end-user vertical with regional regulatory cluster overlay. CAGRs derived from regression analysis of hardware refresh cycle timing, compliance mandate implementation schedules, and cloud migration velocity indices. NAND pricing volatility curves and Taiwan foundry capacity utilization served as industry-specific forecast sensitivity inputs.
Material uncertainties — Taiwan semiconductor supply disruption, flash memory cost spikes, and regulatory timeline acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about immutable storage mandate adoption rates and cloud egress economics stability. Revision becomes warranted when hyperscaler backup partnership penetration crosses mid-market threshold levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
OTG Pen Drive Market
Data Storage
Europe Next Generation Storage Market
Data Storage
Next Generation Data Storage Market
Data Storage
Distributed Storage System Market
Data Storage
Next-Generation Storage Market
Data Storage
Recordable Optical Disc Market
Data Storage
Ethernet Storage Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
Middle East and Africa SSD Caching Market
Data Storage
NOR Flash Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Storage Area Network Market
Data Storage
Australia Data Center Storage Market
Data Storage
Data Storage Market
Data Storage
NAND Flash Market