
 APAC SSD Caching Market | 2026-2036
APAC SSD Caching Market Size, Share, and Industry Trends Forecast 2026-2036
APAC SSD Caching Market Outlook
QLC NAND flash is displacing TLC in read-intensive caching tiers, which is realigning cost-per-gigabyte economics for data center operators. Samsung Electronics leverages captive NAND fabrication to sustain margin control across the NVMe stack. SK Hynix anchors supply security through backward integration into memory wafer production. Intel Corporation competes on controller silicon specialization for enterprise caching workloads.
SSD caching deploys high-speed solid-state drives as an intermediary storage layer between DRAM and hard disk drives, typically using NVMe protocols to achieve sub-100-microsecond latency for hot data retrieval. The architecture accelerates virtualization, database queries, and web serving by reducing mechanical storage bottlenecks. NVMe SSD products command premium positioning due to PCIe bandwidth advantages, while SATA SSD segments face margin compression in legacy refresh cycles. Cloud service providers represent the fastest-expanding end user category, driven by hyperscale buildouts in India, Australia, and Indonesia.
Japan's METI enforces data center energy efficiency standards that favor low-power flash caching over spinning media, while China's MIIT mandates domestic encryption protocols for government-adjacent storage deployments. South Korea's K-ISMS certification shapes security requirements for financial sector caching infrastructure. Stakeholders must weigh localization mandates against supply chain concentration risks when selecting controller and NAND sourcing strategies.
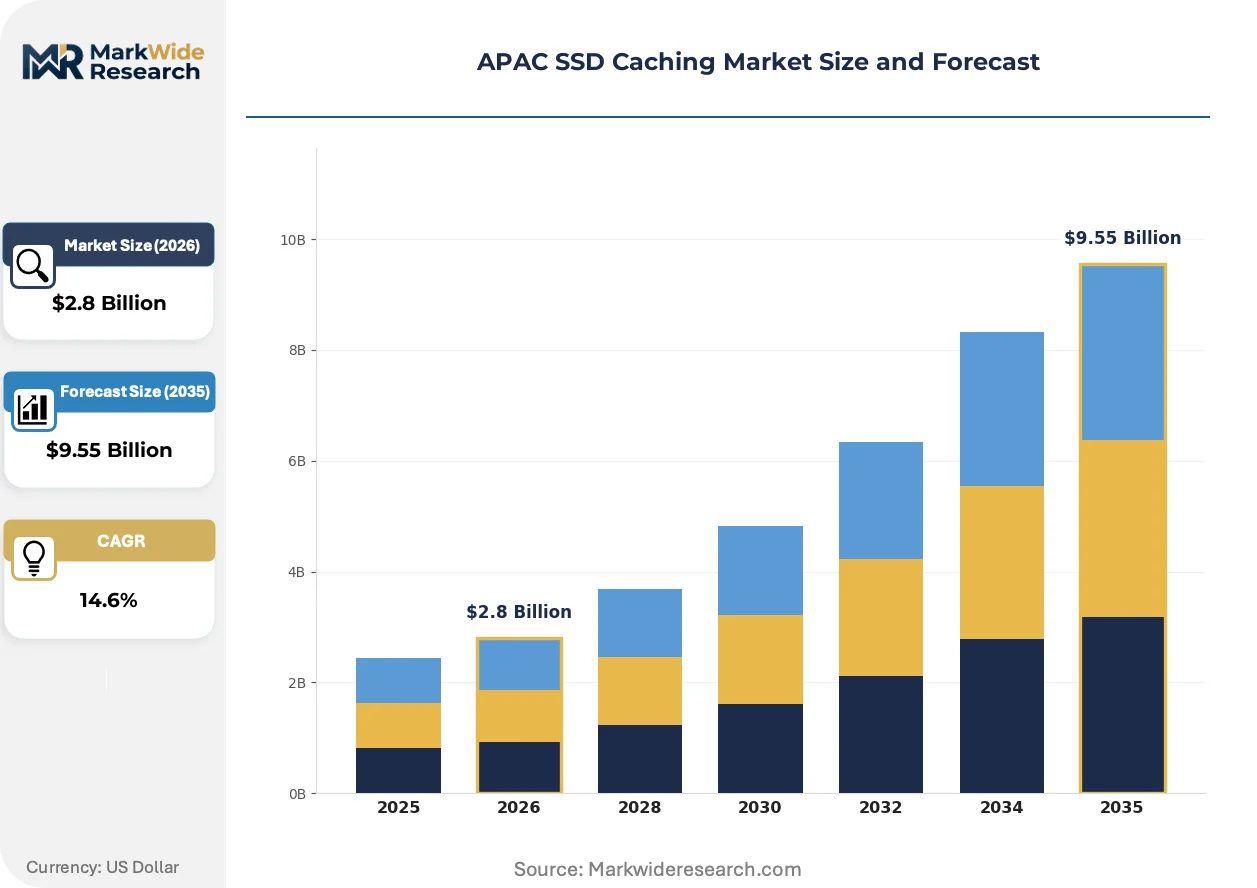
Market Dynamics
China's MIIT mandates and dual carbon goals are compressing data center power budgets, forcing operators toward NVMe-based caching architectures that deliver IOPS per watt advantages over mechanical storage tiers.
Growth Catalysts
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology enforces data center power usage effectiveness thresholds that disqualify legacy HDD-heavy architectures from new facility licensing.
- Cloud Database Workloads:Indian and Indonesian hyperscale operators deploy flash caching layers to cut latency for transactional databases serving financial services and e-commerce platforms.
- Seoul Hyperscale Cluster:South Korea's concentration of cloud regions around Samsung Electronics and SK Hynix fabrication sites creates captive supply advantages for domestic caching deployments.
Market Restraints
- NAND Wafer Concentration:Memory die supply concentrates among Korean and Chinese fabricators, exposing procurement costs to geopolitical trade friction and export control volatility.
- Controller Silicon Dependency:Enterprise NVMe controller design requires specialized ASIC capabilities concentrated among a limited vendor set, constraining second-source options.
- QLC Endurance Limitations:Quad-level cell flash exhibits reduced write endurance versus TLC alternatives, restricting deployment to read-heavy caching tiers and complicating mixed-workload architectures.
Strategic Opportunities
- Vietnam Data Center Buildout:Emerging cloud regions in Hanoi and Ho Chi Minh City lack established caching infrastructure, creating first-mover positioning for NVMe solution providers.
- Japan METI Low-Power Standards:Tokyo's energy efficiency certification program for data center equipment creates preference pull for flash caching solutions that demonstrate measured wattage reductions versus disk arrays.
- PCIe Gen5 Convergence:The interface transition enables bandwidth pooling architectures that combine NVMe caching with computational storage functions in single-slot deployments.
Industry Challenges
- Firmware Integration Complexity:Custom controller firmware must synchronize with hypervisor storage stacks across VMware, KVM, and proprietary cloud orchestration layers, extending qualification timelines.
- K-ISMS Certification Burden:South Korean financial sector deployments require Korea Internet and Security Agency certification for encryption modules, adding documentation and testing overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC SSD Caching Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
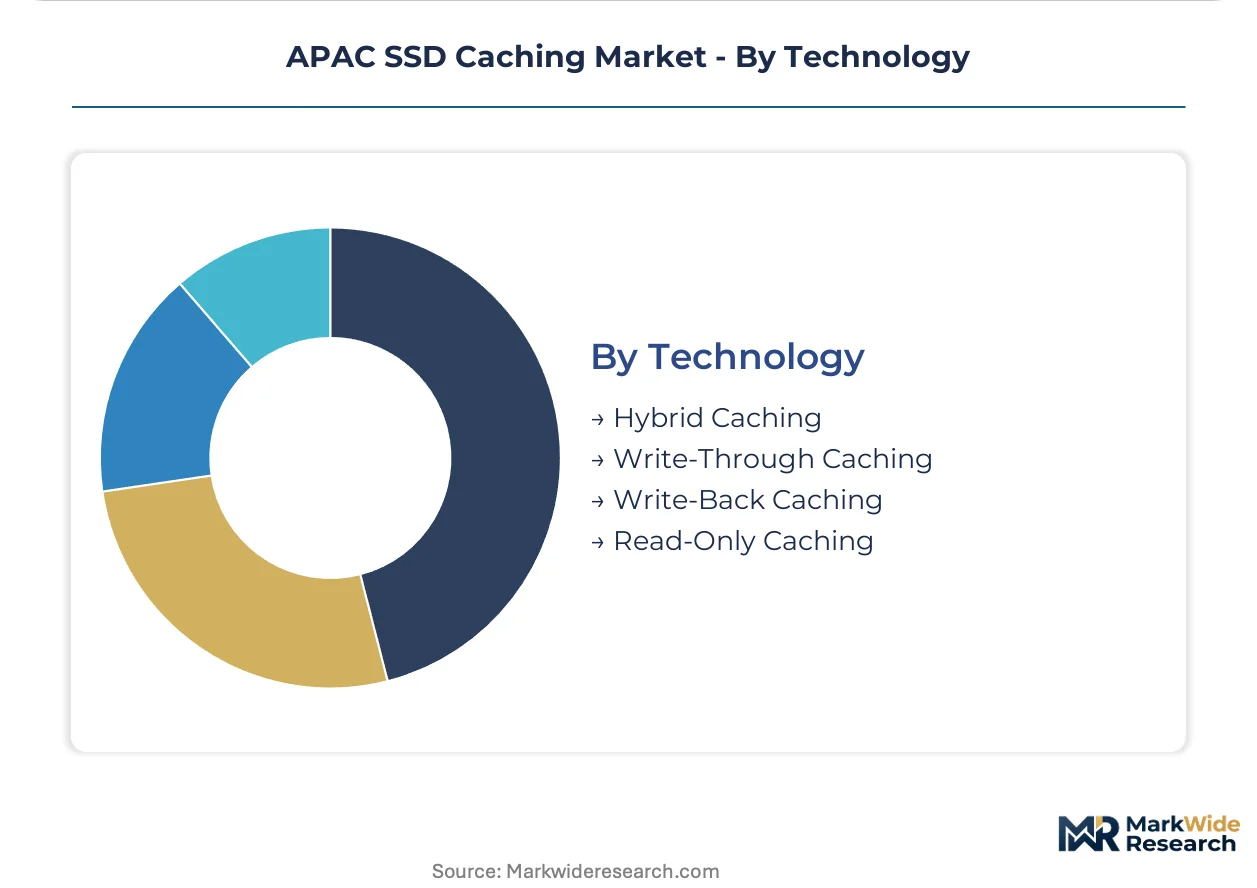
| Segmentation | Product Type: SATA SSD, NVMe SSD, PCIe SSD, SAS SSD End User: SMEs, Large Enterprises, Cloud Service Providers, Data Centers Application: Web Hosting, Virtualization, Database Acceleration, Gaming Technology: Hybrid Caching, Write-Through Caching, Write-Back Caching, Read-Only Caching |
| Companies Covered | Intel Corporation, Samsung Electronics Co. Ltd, Micron Technology Inc., Western Digital Corporation, QNAP Systems Inc., NetApp Inc., Kioxia, SK Hynix Inc., Inspur Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC SSD Caching Market Strategic Shifts
Storage-class memory hierarchies are compressing latency boundaries between DRAM and flash tiers, while regulatory pressure on data center energy intensity accelerates architectural transitions away from mechanical media.
Computational storage drives are modularizing caching architectures by embedding processing cores directly on NVMe devices, enabling data reduction and encryption functions at the storage layer rather than host CPU. Hyperscale operators in Singapore and Sydney deploy these devices to free server cores for revenue-generating compute. The approach is modularizing rack-level power allocation by offloading storage processing from x86 sockets.
Japan's METI enforces data center energy efficiency standards that favor flash caching over spinning media through measurable power consumption benchmarks tied to facility licensing. Operators must submit verified PUE calculations that penalize HDD-heavy configurations. Financial services caching infrastructure in Osaka and Tokyo faces the strictest compliance thresholds under this framework.
Cloud service procurement is consolidating around direct engagements with NAND fabricators for guaranteed allocation, bypassing traditional distribution channels. Australian and Indian hyperscalers now negotiate quarterly die supply agreements rather than purchasing finished drives through integrators. This pattern concentrates most visibly among database-as-a-service providers operating multi-tenant caching layers across Mumbai, Bangalore, and Sydney regions.
APAC SSD Caching Market Segmentation

SSD caching architectures diverge sharply across protocol generations, customer scale, workload patterns, and data persistence models. Each segmentation axis reveals distinct procurement behaviors and margin structures that shape vendor positioning across the APAC region.
Product Type:
The customization-to-standardization spectrum spans legacy SATA interfaces at the commoditized end through PCIe Gen5 NVMe at the fully customized tier.
- NVMe SSD:PCIe-based protocols deliver sub-100-microsecond latency through direct CPU attachment, bypassing legacy storage controller bottlenecks. Cloud service providers in Singapore and Sydney concentrate procurement here, driven by database-as-a-service latency requirements under customer SLAs.
- PCIe SSD:Direct lane attachment enables bandwidth pooling for computational storage functions, with Indian hyperscale operators deploying these for encryption offload and data reduction at the device layer.
- SATA SSD:Legacy 6Gb/s interfaces serve refresh cycles in cost-constrained Indonesian and Vietnamese data centers where mechanical storage replacement drives procurement.
- SAS SSD:Dual-ported 12Gb/s architectures persist in South Korean financial sector deployments requiring K-ISMS-certified failover paths for trading infrastructure.
Most installed capacity flows through NVMe SSD. Expansion is steepest in PCIe SSD as Gen5 convergence enables bandwidth pooling architectures.
End User:
Volume concentration scales inversely with customization requirements, from standardized high-volume cloud procurement to bespoke enterprise configurations.
- Cloud Service Providers:Hyperscale operators in Mumbai, Bangalore, and Jakarta negotiate direct NAND die supply agreements, bypassing distribution channels for guaranteed quarterly allocation. Their caching layers serve multi-tenant database workloads with strict latency SLAs.
- Large Enterprises:Japanese financial institutions in Osaka and Tokyo deploy flash caching under METI energy efficiency mandates that penalize HDD-heavy PUE calculations. Procurement emphasizes verified wattage reductions versus disk arrays.
- Data Centers:Colocation operators across Australia's eastern seaboard face margin pressure from legacy SATA refresh cycles, with NVMe migration constrained by rack-level power reconfiguration costs.
- SMEs:Small and medium enterprises in Vietnam and Philippines rely on channel-assembled caching solutions with limited firmware customization, prioritizing upfront cost over workload-specific optimization.
Cloud service providers command the highest absolute volume. Large enterprises deliver the steepest margin expansion through certified, compliance-heavy deployments.
Application:
Workload characteristics determine cache persistence models, with read-heavy applications tolerating QLC endurance limitations while mixed workloads demand TLC or persistent memory tiers.
- Database Acceleration:Transactional workloads in Indian financial services and Indonesian e-commerce platforms drive the steepest expansion trajectory, with flash caching cutting query latency for MySQL and PostgreSQL clusters serving real-time payment verification.
- Virtualization:VMware and KVM hypervisor integration requires custom controller firmware synchronization, extending qualification timelines for South Korean and Japanese enterprise deployments.
- Web Hosting:Content delivery networks across Australia's Sydney and Melbourne regions deploy read-only caching tiers using QLC NAND for static asset acceleration, accepting endurance tradeoffs for cost-per-gigabyte economics.
- Gaming:Low-latency requirements in South Korea's Seoul cluster and Japan's Tokyo region push NVMe adoption for multiplayer session state management, though absolute volume remains concentrated in cloud database segments.
Database acceleration absorbs the most flash capacity. Web hosting delivers the fastest share gain through QLC displacement of SATA SSD in read-intensive tiers.
Technology:
Data persistence guarantees separate enterprise-grade write-back architectures from read-optimized configurations where data loss tolerance enables cost reduction.
- Write-Back Caching:Acknowledges write completion at the cache layer before destaging to backend storage, delivering lowest latency for transactional workloads. South Korean financial sector deployments require battery-backed or supercapacitor-protected implementations under K-ISMS certification.
- Hybrid Caching:Combines DRAM and flash tiers with automated hot-data promotion, with Chinese cloud operators deploying these architectures to satisfy MIIT power efficiency mandates through reduced mechanical storage spin-up.
- Write-Through Caching:Synchronous backend persistence suits compliance-heavy Japanese government-adjacent storage where MIIT-mandated domestic encryption protocols apply to cached data.
- Read-Only Caching:Stateless acceleration for static content enables lowest-cost QLC deployment, with Vietnamese and Indonesian operators adopting this model for emerging cloud regions lacking established infrastructure.
Write-back caching dominates enterprise revenue. Hybrid caching climbs fastest as power-constrained operators seek DRAM-flash tier optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Seoul Capital Area anchors flash storage demand across Asia-Pacific, with Samsung Electronics and SK Hynix fabrication sites creating captive supply advantages for domestic cloud operators.
China
MIIT power usage effectiveness thresholds disqualify HDD-heavy architectures from new facility licensing. The dual carbon goals compress data center budgets toward NVMe-based caching. Yangtze River Delta operators in Shanghai and Hangzhou deploy these architectures to satisfy efficiency mandates.
Japan
METI enforces measurable power consumption benchmarks that penalize disk-heavy configurations through verified PUE calculations. Financial institutions in Osaka and Tokyo face strictest compliance thresholds. Kanto region data centers prioritize flash caching to meet facility licensing requirements.
South Korea
K-ISMS certification shapes security requirements for financial sector caching infrastructure, adding documentation overhead for encryption modules. The Seoul Capital Area concentrates cloud regions around domestic NAND fabrication sites. Busan-Ulsan corridor supplements this concentration with secondary logistics capacity.
India
Hyperscale operators in Mumbai and Bangalore negotiate direct NAND die supply agreements, bypassing distribution channels for guaranteed quarterly allocation. Database-as-a-service providers drive procurement concentration. Maharashtra and Karnataka states host the steepest expansion trajectory for transactional workload caching.
Australia
Colocation operators across New South Wales and Victoria face margin pressure from legacy SATA refresh cycles, with NVMe migration constrained by rack-level power reconfiguration costs. Sydney and Melbourne regions deploy read-only QLC tiers for content delivery acceleration. Energy efficiency certification programs create preference pull for verified wattage reductions.
APAC SSD Caching Market Competitive Environment
Global majors compete with regional champions across NAND fabrication and controller silicon specialization. The vendor base concentrates around memory die producers with captive wafer capacity and fabless controller designers serving enterprise qualification requirements. Three archetypes dominate: integrated fabricators controlling upstream wafer supply, controller specialists focusing on ASIC design for NVMe protocols, and systems integrators packaging third-party silicon into caching appliances. Capacity expansion and backward integration into memory wafer production represent the dominant competitive moves.
Within the integrated fabrication tier, Samsung Electronics Co. Ltd and SK Hynix Inc. exemplify captive supply strategies, while Intel Corporation occupies a position on the controller specialization vector. These three anchors represent distinct approaches to margin control across the NVMe stack.
| Leading Market Players |
|---|
| Intel Corporation |
| Samsung Electronics Co. Ltd |
| Micron Technology Inc. |
| Western Digital Corporation |
| QNAP Systems Inc. |
| NetApp Inc. |
| Kioxia |
| SK Hynix Inc. |
| Inspur Group |
| Others |
Value Chain & Pricing Dynamics
NAND wafer costs cascade through three distinct pricing tiers before reaching end buyers, with Korean and Chinese fabrication concentration compressing margins at the controller and module integration stages while hyperscale direct procurement bypasses traditional distribution markups entirely.
Pricing Analysis
Input-cost pass-through from NAND wafer spot markets drives quarterly price adjustments across NVMe controller and module tiers. Three-tier pricing structure across premium, standard, and economy levels separates K-ISMS-certified enterprise configurations from channel-assembled SME solutions. Pricing pressure stems from QLC NAND oversupply in read-intensive segments, eroding SATA SSD replacement economics in Indonesian and Vietnamese markets. Cloud service providers exhibit lowest price sensitivity through die-level direct contracts, while colocation operators in Australia face acute margin compression from legacy infrastructure refresh cycles.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for quarterly NAND die allocation, while distribution partners serve SME and mid-market segments with assembled caching appliances. Geographic supply concentrates in South Korea, China, and Taiwan, with memory wafer fabrication anchored around Seoul and Yangtze River Delta clusters. Raw material dependencies center on silicon wafers, controller ASICs, and supercapacitor components for power-loss protection. Single-source vulnerability in enterprise NVMe controller design constrains second-source options for financial sector deployments. Distribution runs through domestic system integrators in India and Australia, supplemented by direct Samsung and SK Hynix engagements for hyperscale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as cloud database workloads shift toward NVMe latency specifications that disqualify mechanical storage architectures from new facility licensing across MIIT and METI jurisdictions.
For Market Incumbents: Deploy captive NAND fabrication capacity to defend margin control against controller-specialist competition from Intel and fabless ASIC designers. Expand backward integration into memory wafer production to secure supply allocation for hyperscale direct contracts. Counter QLC endurance limitations through firmware-tiering architectures that segment read-heavy caching from mixed workloads. For New Entrants and Emerging Players: The premium-economy price-point gap in K-ISMS-certified financial storage creates white-space positioning for modular caching appliances with pre-validated encryption modules. Target Vietnam's emerging Hanoi and Ho Chi Minh City cloud regions where established caching infrastructure remains underdeveloped. Pursue channel partnership models with Australian colocation operators seeking NVMe migration without rack-level power reconfiguration capital. For Investors and Strategic Acquirers: Consolidation pressure builds where controller ASIC specialization concentrates among limited vendor sets with enterprise qualification capabilities. Long-term viability favors integrated fabricators with captive wafer supply and hyperscale direct relationships over module assemblers dependent on spot NAND procurement. Monitor PCIe Gen5 convergence adoption rates across Indian hyperscale operators as inflection indicator for bandwidth-pooling architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Memory Wafer Production | SK Hynix and Samsung Electronics secure supply allocation priority for domestic cloud operators through captive fabrication. |
| K-ISMS Certification Investment | South Korean financial institutions mandate Korea Internet and Security Agency validation for encryption module deployment. |
| Direct NAND Die Supply Agreements | Indian and Australian hyperscalers bypass distribution channels to negotiate quarterly allocation with fabricators. |
| PCIe Gen5 Platform Convergence | Bandwidth pooling architectures enable computational storage functions that offload encryption from host CPUs. |
| Vietnam Data Center Market Entry | Emerging cloud regions in Hanoi and Ho Chi Minh City lack established caching infrastructure for first-mover positioning. |
Study Parameters
Bottom-up cloud service provider and enterprise demand modeling reconciled against top-down NAND fabrication capacity tracking forms the analytical core of this study. Primary interviews with data center procurement officers, storage architects at hyperscale operators, NAND supply chain managers, and controller ASIC designers combined with secondary validation from MIIT efficiency mandate filings, METI PUE certification databases, hyperscaler capex disclosures, and Korean semiconductor trade statistics. Triangulation across these sources ensures demand-side consumption estimates align with supply-side wafer allocation data.
Historical trendline analysis of NVMe adoption curves across database acceleration and virtualization workloads informed projection frameworks across the analysis window. Segmentation dimensions modeled include protocol generation, end-user scale tier, workload persistence model, and regional regulatory cluster. CAGRs derived from slope analysis of technology substitution patterns and efficiency mandate compliance timelines. Industry-specific forecast inputs incorporate MIIT licensing thresholds and K-ISMS certification penetration rates for financial sector deployments.
Caveats apply where NAND wafer spot price volatility or export control expansion could materially shift procurement cost structures and hyperscale buildout timelines. Forecasts reflect assumptions regarding PCIe Gen5 controller availability and QLC endurance improvements for mixed workloads. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Channel Storage Systems Market
Data Storage
Global 3D Nand Flash Memory Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Ethernet Storage Market
Data Storage
Hardware Storage Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
China Solid-State Drive Market
Data Storage
Enterprise Flash Storage Market
Data Storage
HDD Head Assembly Market
Data Storage
Japan Data Center Storage Market
Data Storage
Powered Storage Devices Market
Data Storage
Americas Flash Memory Market
Data Storage
AI Powered Storage Market
Data Storage
Enterprise Hard Drive Market
Data Storage
North America Next Generation Storage Market
Data Storage
USB 3.1 Flash Drive Market