
 Serial EEPROM Market | 2026-2036
Serial EEPROM Market Size, Share, and Industry Trends Forecast 2026-2036
Serial EEPROM Market Analytics
Modular sensor packaging is recalibrating how OEMs specify Serial EEPROM alongside microcontrollers and power management ICs in single substrate solutions. STMicroelectronics leverages its European automotive certification base to anchor premium socket positions in engine control modules. Renesas Electronics sustains Japanese industrial demand through tight coupling with its MCU portfolio. Microchip Technology competes across the Americas with broad distribution and extensive 128K density availability.
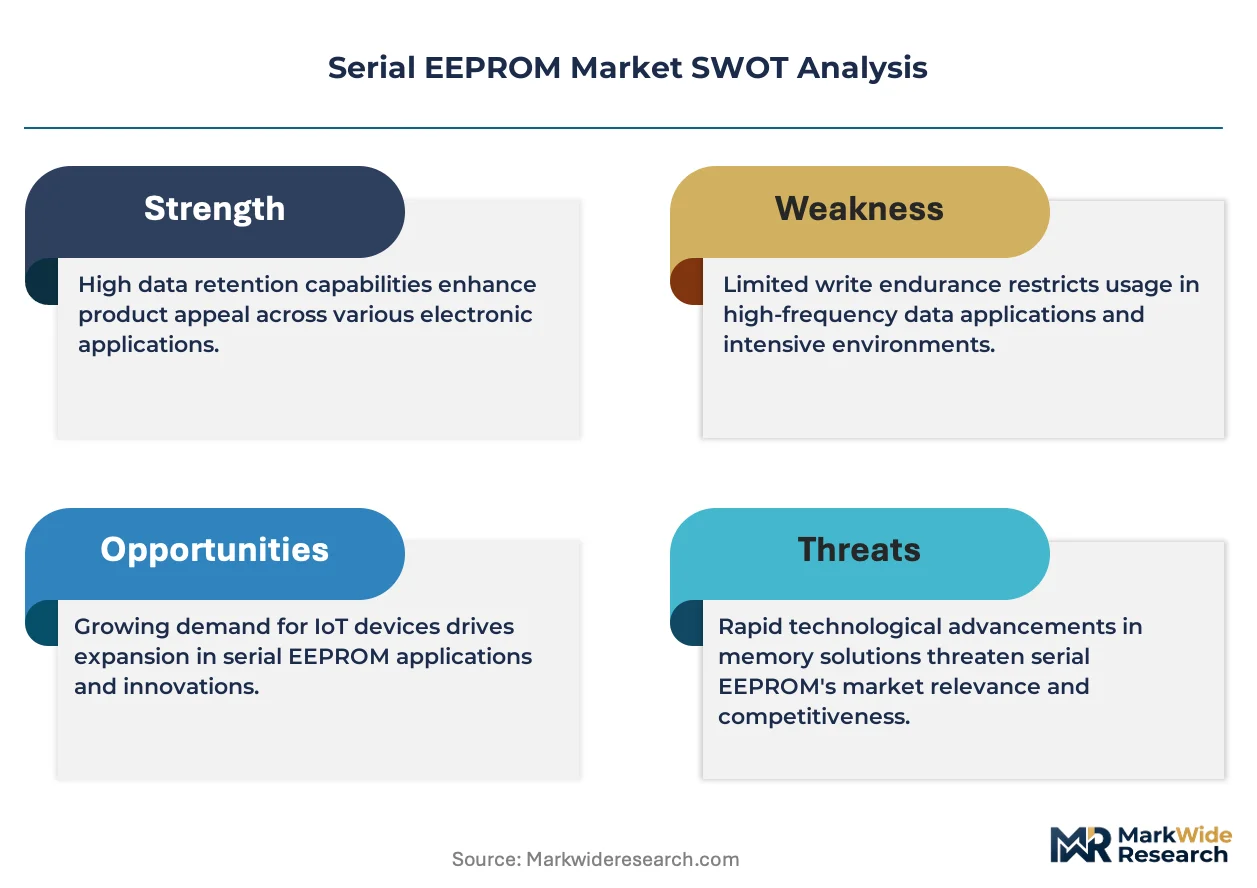
Serial Electrically Erasable Programmable Read-Only Memory stores small data payloads in byte-addressable arrays from 16K to 128K bits, using two-wire I2C or three-wire SPI buses with write endurance typically exceeding one million cycles and retention spanning decades. The technology serves configuration storage, calibration constants, and firmware patches where non-volatile memory must survive power cycling without flash block erase overhead. Automotive end users dominate value pools as safety-critical ECUs require AEC-Q100 qualified devices with extended temperature ranges. Consumer electronics applications in smartphones and wearables represent the fastest-growing volume segment as manufacturers add NFC payment authentication and biometric calibration fields. Ferroelectric technology variants capture niche medical and industrial slots where radiation tolerance or ultra-fast write speeds justify premium positioning.
FDA device traceability rules and EU MDR Unique Device Identification requirements are expanding EEPROM content in implantable and diagnostic equipment across North America and Europe. China's GB standards for automotive electronics and MIIT semiconductor self-sufficiency directives are redirecting supply chain qualification toward domestic foundries. REACH substance restrictions and RoHS recast rules in Europe constrain molding compound and lead frame material choices, elevating compliance costs for legacy package formats. Stakeholders must monitor foundry capacity allocation between automotive-grade and consumer-grade qualification queues as IDM and fabless competitors negotiate priority wafer starts.
Market Dynamics
Automotive module suppliers are consolidating EEPROM procurement specifications around AEC-Q100 qualified devices as ADAS calibration and battery management traceability mandates expand across multiple regulatory jurisdictions.
Growth Catalysts
- EU MDR Unique Device Identification:Implantable and diagnostic equipment manufacturers in Europe are embedding EEPROM for FDA-compliant traceability chains, expanding memory content per device.
- MIIT semiconductor self-sufficiency directives:China's domestic wafer fabs are accelerating qualification of local EEPROM suppliers for white-goods and EV controller modules.
- Ferroelectric RAM variants:Medical and industrial buyers are specifying radiation-tolerant alternatives where ultra-fast write speeds justify premium socket positioning.
Market Restraints
- Foundry capacity allocation bottlenecks:IDM and fabless competitors negotiate priority wafer starts as automotive-grade qualification queues compete with consumer-grade demand.
- REACH substance restrictions:European ECHA rules constrain halogen-free molding compound and lead frame material choices, elevating compliance costs for legacy package formats.
- NOR flash substitution:Higher-density code storage applications are migrating to unified flash architectures that absorb EEPROM functions.
Strategic Opportunities
- Modular sensor packaging convergence:Single-substrate solutions integrating microcontrollers, power management ICs, and EEPROM are recalibrating OEM specification patterns.
- GB standards compliance in China:Domestic automotive electronics certification is redirecting supply chain qualification toward captive foundry partnerships.
- Biometric calibration fields:Smartphone and wearable manufacturers are expanding NFC payment authentication payloads, opening new density tiers.
Industry Challenges
- AEC-Q100 certification timelines:Extended temperature range qualification for safety-critical ECUs stretches development cycles and strains engineering resources.
- Legacy I2C/SPI integration:Byte-addressable arrays must interface with newer serial peripheral architectures without firmware overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serial EEPROM Market |
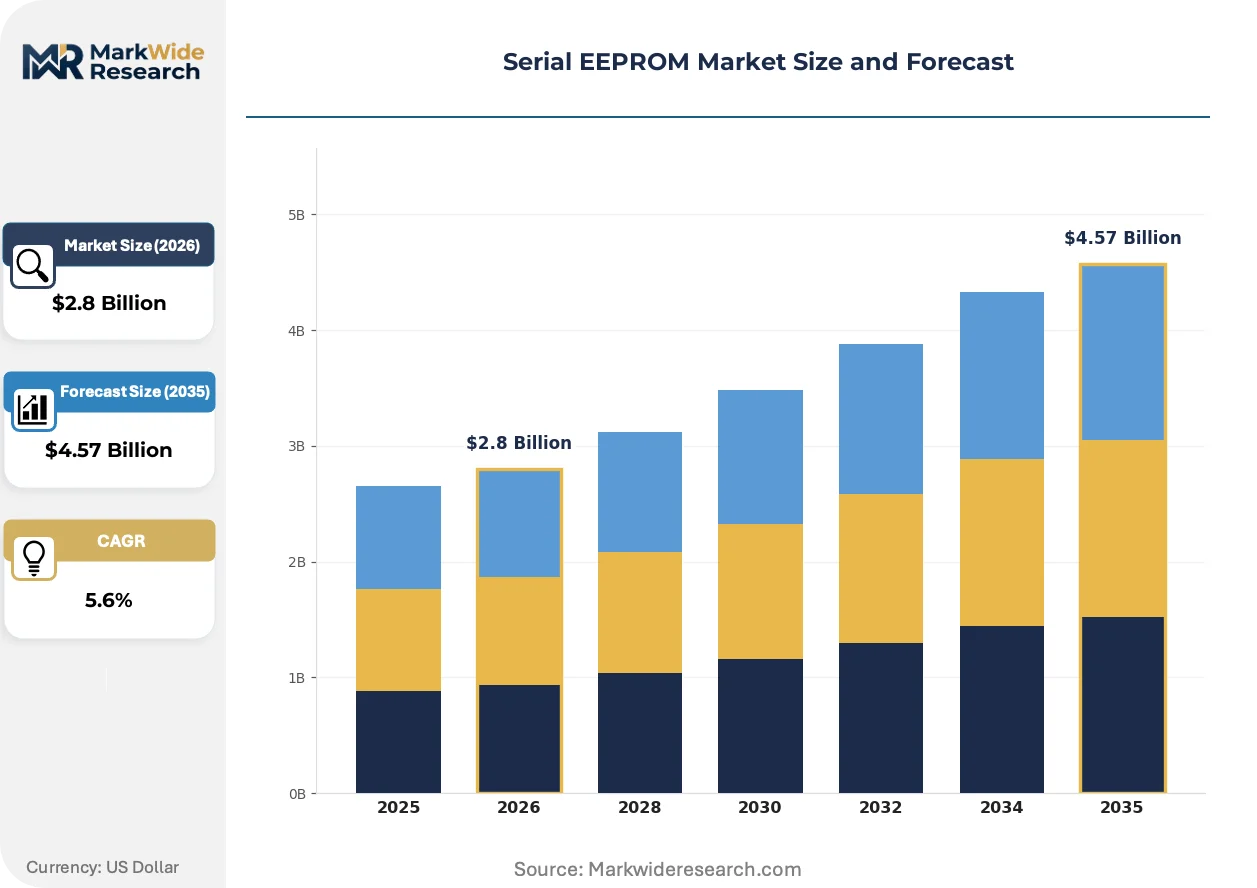
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 16K, 32K, 64K, 128K Technology: Flash, NAND, NOR, Ferroelectric End User: Consumer Electronics, Automotive, Industrial, Medical Application: Data Logging, Configuration Settings, Firmware Storage, Code Execution |
| Companies Covered | ON Semiconductor, Renesas Electronics, STMicroelectronics, Fudan Microelectronics, ABLIC, Microchip Technology, ROHM Semiconductor, Puya Semiconductor, Giantec Semiconductor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serial EEPROM Market Evolving Landscape
Packaging integration and interface standardization are compressing how OEMs specify memory alongside compute and power components in space-constrained modules.
System-in-package configurations embedding EEPROM die alongside microcontrollers are overtaking discrete component procurement in engine control modules. Tier-1 automotive suppliers are specifying these stacked solutions to reduce board area and improve signal integrity. The shift is compressing socket counts for standalone memory devices in powertrain applications.
REACH recast rules and RoHS substance restrictions from ECHA are forcing foundries to reformulate molding compounds and lead frame alloys. European packaging houses are qualifying halogen-free alternatives ahead of enforcement windows. Consumer-grade suppliers face steeper cost curves than automotive-certified competitors with established green material supply chains.
Consolidated procurement specifications from tier-1 automotive module suppliers are narrowing qualified vendor lists for 128K density devices. Buyers are bundling EEPROM sourcing with microcontroller and power management IC awards to simplify supply chain management. This concentration is most visible in Germany and Japan where KBA and METI certification requirements reinforce supplier stickiness.
Serial EEPROM Market Segmentation
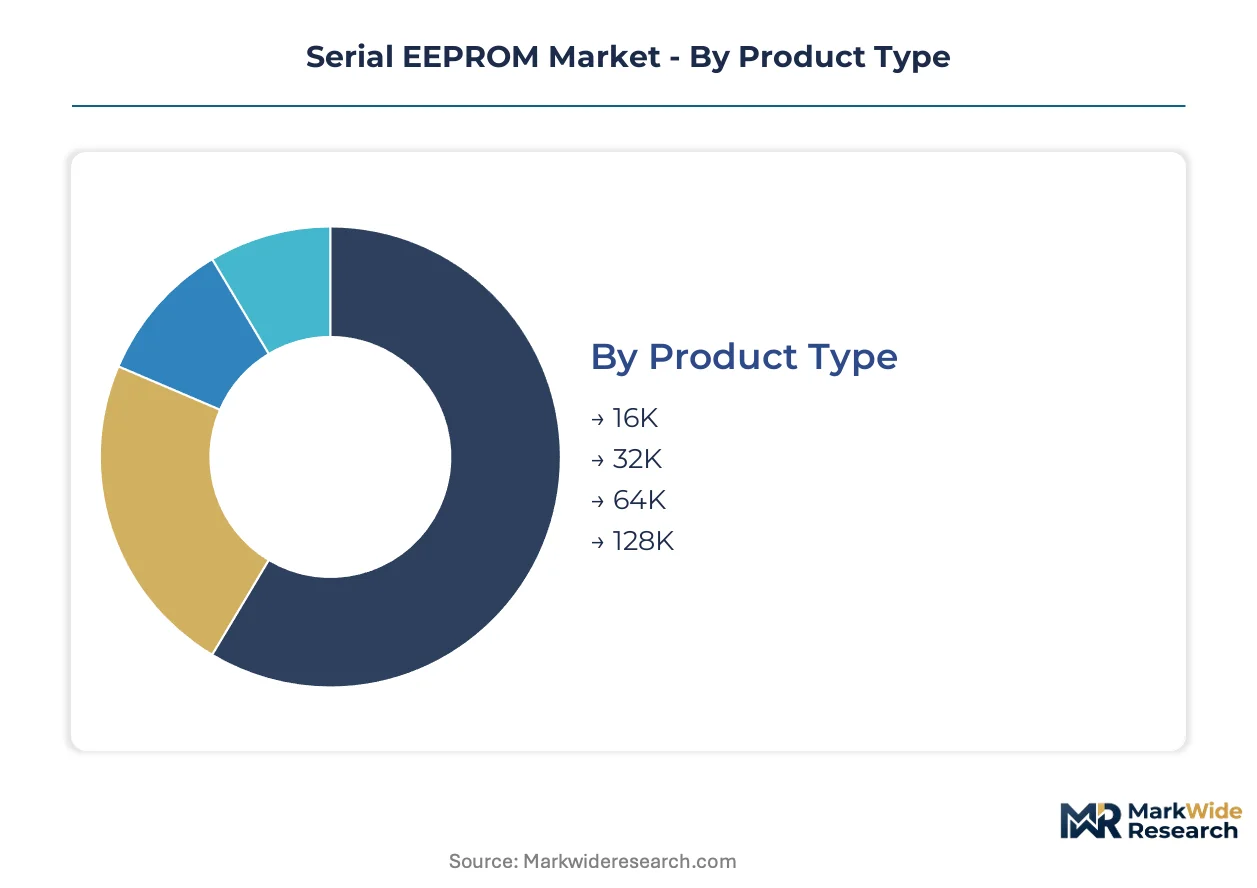
Serial EEPROM specifications fragment across density tiers, interface protocols, and qualification grades that directly determine socket eligibility in automotive safety systems versus consumer cost-optimized boards. Procurement teams negotiate these categories simultaneously, with density and temperature grade often locked before technology type enters discussion.
Product Type:
Volume applications cluster at lower densities where unit economics dominate, while premium sockets concentrate at 128K where AEC-Q100 qualification commands price multiples.
- 128K:Maximum byte-addressable density supports complex calibration tables and multi-parameter firmware patches in engine control modules. German KBA certification requirements and Japanese METI automotive standards concentrate procurement around qualified 128K suppliers for powertrain ECUs.
- 64K:Mid-range density captures battery management systems requiring traceability fields without the cost overhead of maximum capacity. Chinese EV controller modules and European ADAS calibration units represent the fastest-expanding demand pool.
- 32K:Balances payload capacity against die size for white-goods controllers and industrial sensor nodes.
- 16K:Minimum viable density for configuration bit storage in cost-constrained consumer peripherals and legacy industrial equipment.
Today's leader: 64K. Tomorrow's challenger: 128K.
Technology:
Interface architecture and write endurance separate commodity sockets from premium medical and aerospace applications where radiation tolerance justifies non-standard process nodes.
- Flash:Dominant floating-gate technology achieves million-cycle endurance across I2C and SPI interfaces with decades-long retention. European REACH substance restrictions and RoHS recast rules are forcing foundry migration to halogen-free molding compounds for flash-based packages.
- Ferroelectric:Polarization-based switching delivers sub-microsecond writes and inherent radiation hardness without erase-before-write overhead. FDA device traceability mandates and EU MDR Unique Device Identification requirements are expanding ferroelectric EEPROM content in implantable cardiac monitors and diagnostic imaging systems.
- NOR:Code-execute capability absorbs microcontroller boot functions in unified memory architectures.
- NAND:Page-addressable density for data logging applications requiring higher payload capacity than byte-addressable alternatives.
Flash dominates unit volume. Ferroelectric commands premium expansion.
End User:
Automotive qualification timelines and consumer volume scale create divergent margin structures across customer categories.
- Automotive:AEC-Q100 Grade 0 devices with 150°C operation support safety-critical ECUs where calibration data integrity affects emissions compliance and crash avoidance. Chinese GB standards for automotive electronics and MIIT semiconductor self-sufficiency directives are redirecting supply chain qualification toward domestic foundry partnerships for EV controller modules.
- Consumer Electronics:Smartphone biometric calibration fields and NFC payment authentication payloads are expanding density requirements in wearables and mobile devices. This segment climbs fastest in unit terms as manufacturers add secure element companion memory.
- Industrial:Extended temperature operation and high write endurance serve factory automation and smart metering.
- Medical:FDA and EU MDR traceability chains mandate non-volatile storage for implantable device serialization and usage logging.
Automotive anchors value concentration. Consumer electronics drives steepest volume expansion.
Application:
Functional requirements determine interface selection and endurance specifications more than density alone.
- Configuration Settings:Boot-time parameter loading for microcontrollers and power management ICs demands high read speed with minimal write frequency. Modular sensor packaging trends are integrating this function into system-in-package configurations alongside compute die.
- Firmware Storage:Field-upgradable code patches require sector erase capability and error correction. Battery management traceability mandates across multiple regulatory jurisdictions are expanding firmware payload sizes in automotive modules.
- Data Logging:Continuous write applications in industrial sensors and medical monitors stress endurance specifications.
- Code Execution:Execute-in-place requirements favor NOR architectures with random access read performance.
Configuration settings dominates socket count. Firmware storage gains fastest in content per device.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Serial EEPROM manufacturing originated in Japan and the United States during the 1980s, with European automotive certification later establishing premium qualification standards. Production now clusters across East Asian foundry networks and European automotive supply chains.
China
Domestic wafer fabs are accelerating qualification of local EEPROM suppliers for white-goods controllers and EV battery management modules. MIIT semiconductor self-sufficiency directives redirect procurement toward captive foundry partnerships in the Yangtze River Delta. Shanghai and Suzhou host the densest concentration of emerging fabless EEPROM design houses serving automotive Tier-1s.
Germany
KBA certification requirements for powertrain ECUs concentrate procurement around qualified 128K density suppliers with extended temperature grades. ECHA REACH substance restrictions force foundries toward halogen-free molding compounds ahead of enforcement windows. Bavarian automotive clusters around Munich and Ingolstadt anchor European demand for AEC-Q100 Grade 0 devices.
United States
FDA device traceability rules expand EEPROM content in implantable cardiac monitors and diagnostic imaging systems across North American medical device manufacturing. EPA and OSHA workplace standards intersect with semiconductor fabrication compliance in Arizona and Texas fab corridors. Greater Phoenix and Austin host the primary domestic assembly and test facilities serving automotive and industrial sockets.
Japan
METI automotive standards reinforce supplier stickiness for Japanese industrial demand through tight MCU portfolio coupling. JIS quality certification maintains premium positioning for domestic EEPROM suppliers in factory automation and smart metering applications. Tokyo-Osaka-Nagoya industrial corridors concentrate design engineering and Tier-1 module supplier headquarters.
South Korea
MFDS medical device regulations and automotive electronics certification expand EEPROM qualification queues at domestic foundries. Seoul Capital Area fabs allocate capacity between consumer-grade and automotive-grade device production. Suwon and Pyeongtaek host the primary packaging houses serving smartphone biometric calibration and NFC authentication memory demand.
Serial EEPROM Market Competitive Landscape
Premium-margin players sit above commodity-margin players across AEC-Q100 certification density, with automotive-grade qualification timelines creating tiered access to safety-critical ECU sockets. The vendor base organizes around three strategic archetypes: integrated device manufacturers with captive fabs, fabless specialists with automotive certification depth, and diversified memory suppliers with broad distribution networks. Dominant competitive moves include backward integration into wafer fabrication capacity and strategic partnerships with automotive Tier-1 module suppliers for system-in-package configurations.
Among diversified memory suppliers, Microchip Technology occupies a position exemplifying broad density availability across Americas distribution channels. Within the automotive-certified tier, STMicroelectronics and Renesas Electronics anchor European and Japanese demand pools respectively through MCU portfolio coupling. Chinese fabless specialists including Fudan Microelectronics and Puya Semiconductor represent emerging competitive pressure in cost-optimized consumer and industrial sockets.
| Leading Market Players |
|---|
| ON Semiconductor |
| Renesas Electronics |
| STMicroelectronics |
| Fudan Microelectronics |
| ABLIC |
| Microchip Technology |
| ROHM Semiconductor |
| Puya Semiconductor |
| Giantec Semiconductor Corporation |
| Others |
Value Network & Pricing Analysis
Halogen-free molding compound costs cascade through three distinct pricing tiers as European ECHA enforcement windows compress foundry margins and redirect procurement toward automotive-certified suppliers with established green material supply chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q100 Grade 0 automotive devices from industrial-grade alternatives and cost-optimized consumer variants. Price differentiation hinges on certification depth and volume scale, with 128K density automotive sockets commanding multiples over equivalent consumer densities. Pricing pressure stems from Chinese domestic foundry expansion in 64K and 32K tiers, where local qualification for white-goods and EV controllers erodes margin buffers. Consumer electronics buyers exhibit highest price sensitivity, while German and Japanese Tier-1 automotive module suppliers prioritize qualification stickiness over unit cost.
Supply Chain Analysis
Photoresist and specialty chemical supply rests on Japanese producers Shin-Etsu and JSR, while wafer fabrication concentrates in Taiwan, South Korea, and China. Silicon wafer, gold wire, and epoxy molding compound dependencies create multi-point vulnerability to commodity price swings and logistics chokepoints at East Asian port clusters. Tariff exposure on Chinese-packaged devices entering North American automotive supply chains represents the dominant structural risk. Distribution runs through authorized distributors serving Tier-1 module suppliers and direct OEM contracts for high-volume consumer sockets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR Unique Device Identification mandates and FDA traceability rules mechanically expand EEPROM content per device across medical and automotive end uses.
For Market Incumbents: Deploy AEC-Q100 certification depth as a defensive moat against Chinese fabless specialists qualifying for domestic EV controller modules. Prioritize captive wafer allocation to automotive-grade queues as foundry capacity competition intensifies with consumer-grade demand. Secure halogen-free molding compound supply agreements ahead of ECHA enforcement windows to lock in green material cost positions. For New Entrants and Emerging Players: Capture white-space in Chinese domestic qualification for GB standards-compliant automotive electronics, where MIIT self-sufficiency directives redirect procurement toward local foundry partnerships. Target 64K density battery management traceability sockets in European and North American EV supply chains as the fastest-penetrable tier. Lead with ferroelectric radiation-tolerant variants for medical implantable devices where FDA device traceability rules justify premium positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where automotive certification timelines stretch engineering resources and strain capital deployment across extended qualification cycles. Long-term viability favors vertically integrated IDMs with captive fab capacity and established Tier-1 module supplier relationships over fabless competitors exposed to foundry allocation bottlenecks. Watch Chinese fabless qualification success at domestic automotive Tier-1s as the inflection signal for regional pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Grade 0 Certification Investment | Unlocks safety-critical ECU sockets in German KBA and Japanese METI regulated supply chains. |
| Halogen-Free Packaging Transition | Positions suppliers ahead of ECHA REACH recast enforcement in European automotive modules. |
| System-in-Package Integration Partnership | Compresses board area for Tier-1 powertrain suppliers specifying stacked MCU-memory configurations. |
| Domestic Chinese Foundry Qualification | Aligns with MIIT semiconductor self-sufficiency directives for white-goods and EV controller demand. |
| Ferroelectric Technology Line Extension | Captures premium medical sockets where FDA traceability mandates require radiation-tolerant storage. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with automotive Tier-1 procurement officers, fabless EEPROM design house executives, foundry capacity planners, medical device regulatory affairs leads, and industrial sensor OEM technical directors with secondary validation against SEC 10-K filings, MIIT semiconductor industry bulletins, ECHA substance restriction updates, and customs trade flow databases. Bottom-up density-tier shipment estimates triangulated against top-down automotive ECU and consumer electronics production forecasts.
Comparable-period anchoring linked forward projections to historical qualification cycle timelines and foundry capacity buildout trajectories across the analysis window. Segmentation modeling spanned density tiers, interface protocols, temperature grades, and end-use regulatory clusters. CAGRs derived from shipment-volume elasticity to automotive production schedules and consumer electronics bill-of-materials expansion. Industry-specific inputs included AEC-Q100 certification queue lengths and ECHA enforcement phase-in calendars.
Foundry allocation shifts between automotive-grade and consumer-grade qualification queues, ECHA substance restriction enforcement timing, and Chinese domestic supplier qualification success at automotive Tier-1s are the dominant revision risks to modeled outputs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Next-Generation Storage Market
Data Storage
Data Center Ssds Market
Data Storage
APAC Next Generation Storage Market
Data Storage
North America AMH and Storage Systems Market
Data Storage
North America Next Generation Storage Market
Data Storage
Global Portable Data Storage Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Blu-Ray Drive Market
Data Storage
North America SSD Caching Market
Data Storage
Next Generation Data Storage Market
Data Storage
Middle East Data Center Storage Market
Data Storage
Multiprotocol Storage Market
Data Storage
Ceph Storage Solutions Market
Data Storage
AI Powered Storage Market
Data Storage
Solid State Array Market
Data Storage
Object-Based Storage Market