
 Storage Area Network (SAN) Solutions Market | 2026-2036
Storage Area Network (SAN) Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Storage Area Network (SAN) Solutions Market Analytics
NVMe-grade performance tiers is reorganizing procurement standards across enterprise storage refresh cycles. Dell Technologies leverages its server-to-storage integration depth to anchor large-scale federal deployments. Pure Storage differentiates through all-flash array specialization that eliminates hybrid disk dependencies. Huawei Technologies competes on cost-optimized Fibre Channel switch portfolios across Asia-Pacific and Middle Eastern installations.
A Storage Area Network (SAN) Solutions architecture constitutes a dedicated high-speed network interconnecting servers to consolidated block-level storage arrays, typically employing Fibre Channel or iSCSI protocols with switching fabric latencies below 10 microseconds for transaction-critical workloads. Fibre Channel technology retains dominance in financial services and telecommunications end-user segments where deterministic throughput outweighs Ethernet cost advantages, while hyper-converged infrastructure product types capture fastest-growing adoption among mid-market enterprises seeking collapsed compute-storage management planes. High-end SAN systems concentrate margin pools through custom ASIC controller development and proprietary fabric operating systems that lock in multi-year support contracts.
ISO 27001 information security management standards and SOC 2 Type II attestation frameworks shape procurement eligibility for healthcare and government end users, while the EU AI Act and GDPR impose data residency and audit trail requirements that elevate encrypted-at-rest SAN configurations. The Federal Risk and Authorization Management Program in the United States gates cloud-adjacent SAN deployments for federal contractors. Stakeholders must monitor protocol convergence timelines between NVMe-oF and mature Fibre Channel investments to avoid stranded infrastructure commitments.
Market Dynamics
NVMe-oF protocol maturation is compressing Fibre Channel refresh cycles while forcing incumbent vendors to rearchitect controller silicon around disaggregated storage pools.
Growth Catalysts
- FedRAMP Authorization:Federal contractors in the United States must achieve FedRAMP Moderate or High baselines to deploy cloud-adjacent SAN infrastructure, mandating encrypted fabric configurations and continuous monitoring capabilities.
- Central Bank Digital Currency Infrastructure:Central banks in Germany and Japan are procuring sub-10 microsecond latency storage fabrics to support real-time settlement ledgers and cryptographic transaction validation.
- Custom ASIC Development:Proprietary controller silicon from established vendors locks healthcare and telecommunications operators into multi-year support contracts with deterministic performance guarantees.
Market Restraints
- Controller Silicon Supply Concentration:Advanced 7nm and 5nm fabrication for storage ASICs concentrates among Taiwan-based foundries, exposing procurement timelines to geopolitical fab utilization constraints.
- Fibre Channel Skill Scarcity:Enterprise IT organizations face acute shortages of certified fabric architects capable of zoning, masking, and troubleshooting multi-switch director-class deployments.
- Hyper-Converged Infrastructure Substitution:Mid-market enterprises are collapsing compute-storage-network management planes into single-vendor HCI stacks, bypassing dedicated SAN fabric investments entirely.
Strategic Opportunities
- India Data Center Expansion:PLI scheme incentives for electronics manufacturing are attracting hyperscale facility investments in Mumbai and Chennai, creating greenfield SAN deployment opportunities outside legacy Fibre Channel footprints.
- EU AI Act Data Residency:GDPR and the EU AI Act impose audit trail and encryption-at-rest mandates that elevate certified SAN configurations for AI training clusters across Frankfurt and Amsterdam.
- NVMe-oF over TCP Convergence:RDMA-free transport layers are enabling Ethernet-native storage fabrics to penetrate cost-sensitive enterprise segments previously reserved for iSCSI.
Industry Challenges
- Fabric Zoning Certification Bottlenecks:ISO 27001 and SOC 2 Type II attestation timelines stretch 9-14 months for healthcare providers, delaying production cutover of patient data archives.
- Interoperability Testing Overhead:Multi-vendor SAN environments require exhaustive HBA-switch-array qualification matrices that consume engineering resources and compress margin on professional services engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Storage Area Network (SAN) Solutions Market |
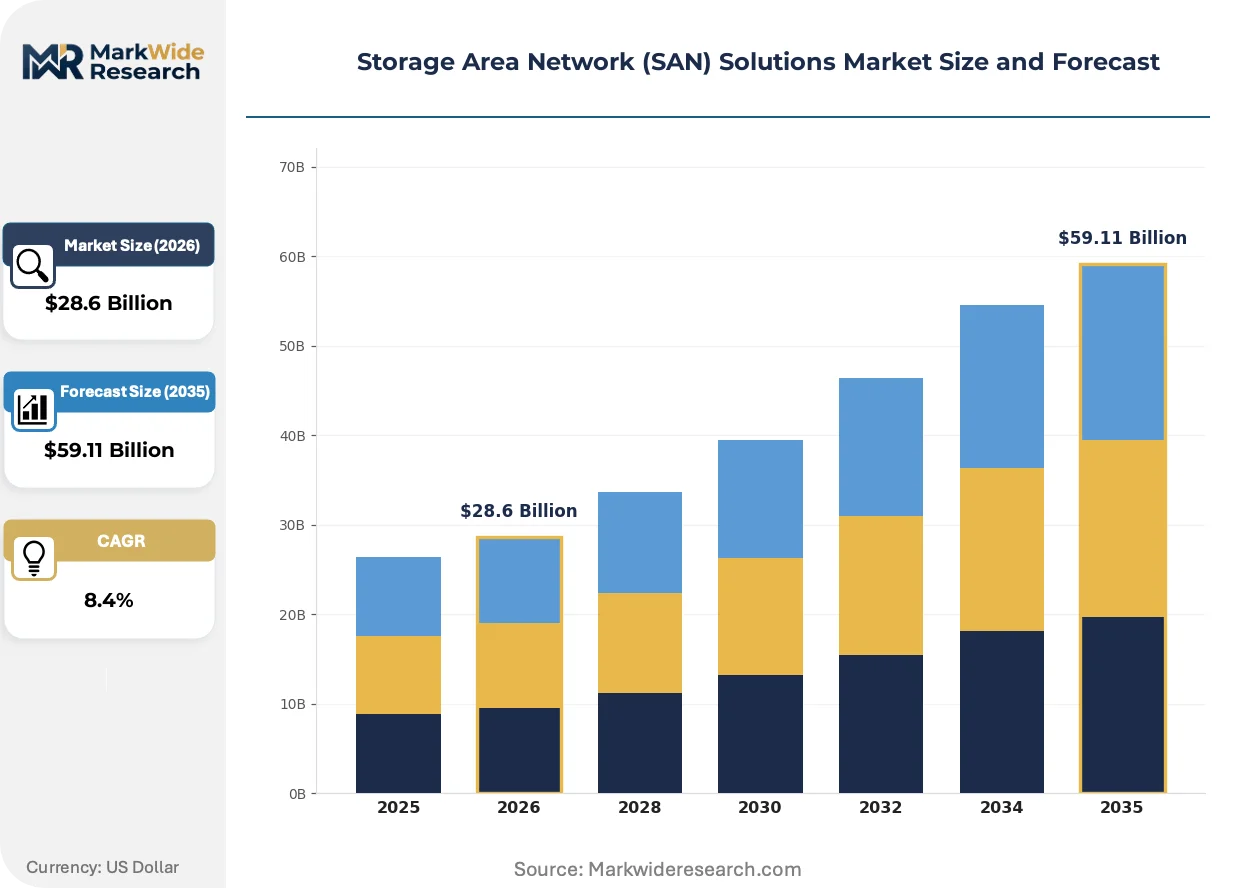
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Entry-Level SAN, Mid-Range SAN, High-End SAN, Hyper-Converged Infrastructure Technology: Fibre Channel, iSCSI, FCoE, NAS End User: Telecommunications, Financial Services, Government, Healthcare Service Type: Managed Services, Professional Services, Support Services, Consulting |
| Companies Covered | IBM Corporation, Hitachi Vantara, Dell Technologies, Broadcom, Pure Storage, Hewlett Packard Enterprise, Cisco Systems, Huawei Technologies, NetApp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Storage Area Network (SAN) Solutions Market Evolving Landscape
Protocol convergence and regulatory encryption mandates are fragmenting procurement standards while compressing vendor differentiation around controller architecture and fabric operating system maturity.
Computational storage drives with embedded processing capabilities are supplanting traditional dumb flash modules in latency-sensitive financial trading environments. High-frequency trading firms in Chicago and London are deploying these intelligent devices to execute erasure coding and encryption at the media level. This shift is supplanting host-side CPU cycles and collapsing network traffic volumes that previously traversed switch fabrics for parity calculations.
The EU AI Act's risk-based classification system imposes data lineage and immutability requirements on high-risk AI systems deployed across European financial institutions. SAN vendors must now certify write-once-read-many capabilities and cryptographic proof-of-retention for model training datasets. German automotive manufacturers integrating AI-driven quality control are driving encrypted-at-rest array configurations to satisfy these audit requirements.
Subscription-based capacity pricing is displacing perpetual license models among mid-market enterprises refreshing five-year-old hybrid arrays. Channel partners in Japan are unbundling hardware acquisition from professional services, offering consumption-aligned financing through captive leasing subsidiaries. This model concentrates buyer power with distributors who aggregate demand across multiple end-user verticals.
Storage Area Network (SAN) Solutions Market Segmentation
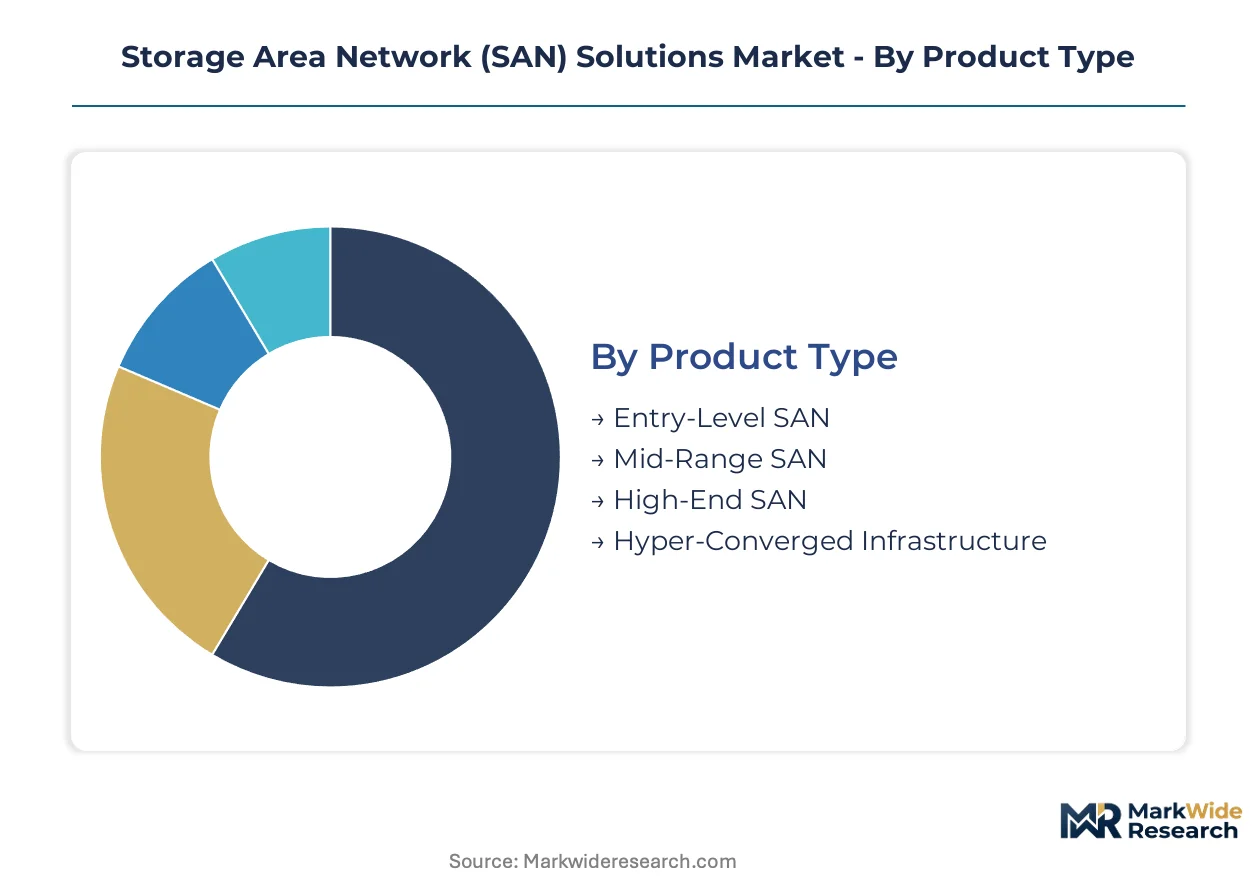
Segmentation in SAN procurement reflects divergent infrastructure maturity across enterprise tiers. Channel economics vary sharply between direct sales for high-end systems and distributor-led fulfillment for mid-market deployments. Understanding these segment boundaries clarifies where protocol transitions and pricing pressures concentrate.
Product Type:
Channel mix splits sharply: high-end systems flow through direct vendor relationships with multi-year support contracts, while entry-level and mid-range products move through value-added distributors and systems integrators.
- High-End SAN:Custom ASIC controllers and proprietary fabric operating systems define this tier. Financial services institutions in Frankfurt and Chicago deploy these systems for sub-10 microsecond latency requirements in high-frequency trading environments. FedRAMP High baseline mandates for federal contractors reinforce vendor lock-in through encrypted fabric configurations.
- Hyper-Converged Infrastructure:Collapsed compute-storage-network management planes characterize this architecture. Mid-market enterprises across Japan are bypassing dedicated Fibre Channel investments entirely, consolidating procurement through single-vendor HCI stacks with subscription-based capacity pricing.
- Mid-Range SAN:Hybrid flash-disk configurations serve healthcare providers modernizing patient data archives. ISO 27001 attestation timelines stretch deployment cycles.
- Entry-Level SAN:iSCSI-based systems target cost-sensitive education and retail segments. Channel partners aggregate demand across multiple verticals.
High-End SAN dominates installed base. Hyper-Converged Infrastructure is where expansion concentrates.
Technology:
Cost tier alignment shapes procurement: Fibre Channel commands premium pricing for deterministic throughput, while Ethernet-native alternatives compete on infrastructure reuse.
- Fibre Channel:32G and 64G switching fabrics deliver deterministic latency below 10 microseconds for transaction-critical workloads. German and Japanese central banks procuring real-time settlement ledgers drive refresh cycles in this segment despite NVMe-oF convergence pressures.
- iSCSI:Ethernet transport over standard network interface cards eliminates specialized HBA investments. Mid-market enterprises in India leverage existing switch infrastructure for greenfield data center deployments under PLI scheme incentives.
- FCoE:Converged network adapters reduce cable plant complexity. Adoption concentrates in legacy enterprise data centers avoiding forklift upgrades.
- NAS:File-level protocols serve unstructured data workloads outside block-storage SAN architectures. Media and entertainment verticals deploy parallel file systems.
Fibre Channel retains the largest revenue pool. NVMe-oF over TCP is climbing the fastest among emerging transport options.
End User:
Application criticality determines margin structure: financial services and telecommunications pay premiums for deterministic performance, while healthcare and government segments prioritize compliance certification.
- Financial Services:High-frequency trading firms and central bank digital currency infrastructure demand sub-10 microsecond storage fabrics. Real-time settlement ledgers in Germany and Japan require cryptographic transaction validation with erasure coding at the media level.
- Government:Federal contractors in the United States face FedRAMP Moderate or High baselines for cloud-adjacent SAN deployments. Continuous monitoring capabilities and encrypted fabric configurations gate procurement eligibility.
- Telecommunications:5G core network functions drive low-latency storage requirements. Custom ASIC development locks operators into multi-year support contracts.
- Healthcare:Patient data archives require SOC 2 Type II attestation and HIPAA compliance. Certification bottlenecks stretch production cutover timelines.
Financial Services commands the highest average selling prices. Government is gaining share fastest through digital infrastructure modernization.
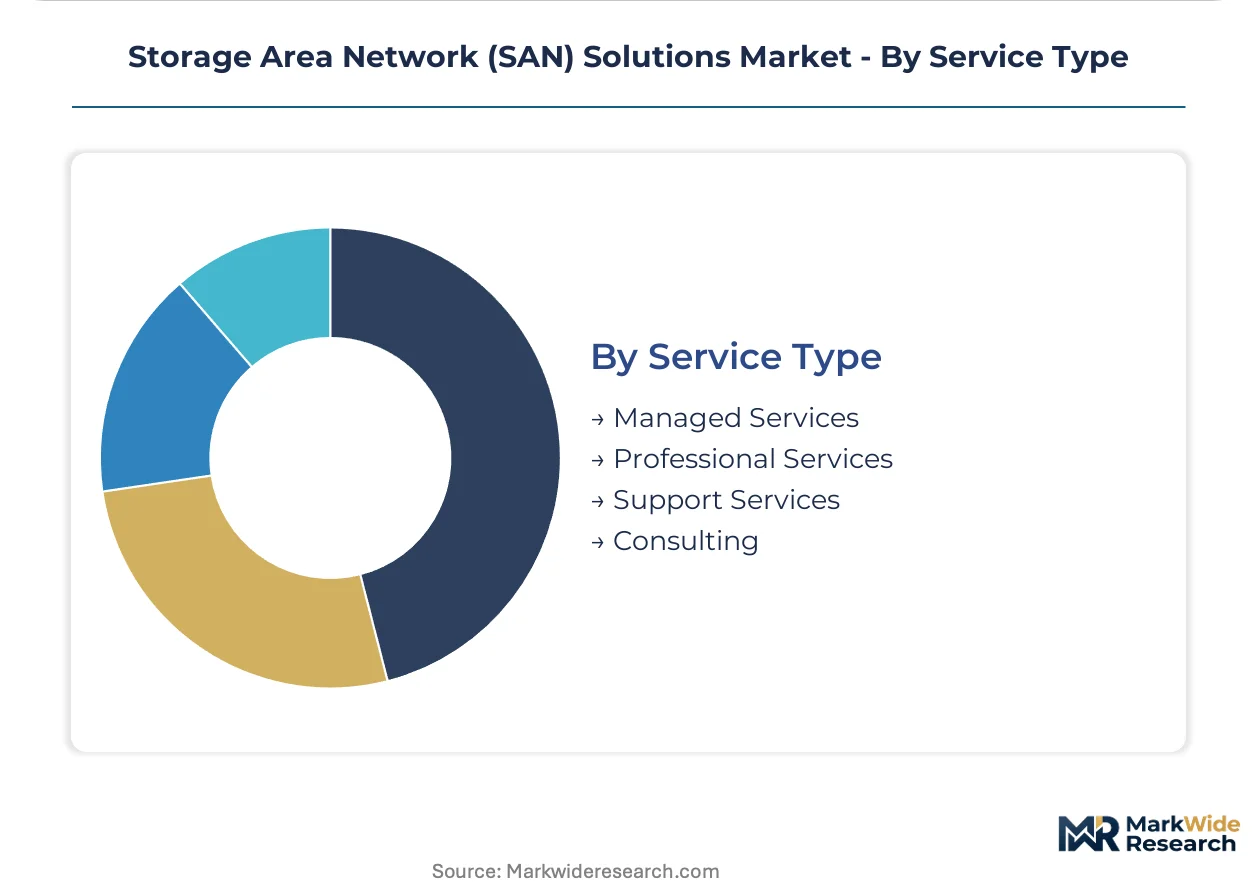
Service Type:
Customer maturity dictates service mix: enterprises with scarce Fibre Channel expertise consume professional services heavily, while cloud-native operators prefer managed service outcomes.
- Professional Services:Fabric zoning, masking, and multi-switch director-class deployments require certified architects. Acute skill scarcity in Fibre Channel troubleshooting extends implementation timelines and concentrates margin with systems integrators.
- Managed Services:Outcome-based capacity and performance SLAs appeal to mid-market enterprises unbundling hardware from operational support. Japanese channel partners offer consumption-aligned financing through captive leasing subsidiaries.
- Support Services:Multi-year contracts with deterministic performance guarantees attach to proprietary controller silicon. Vendor lock-in reinforces recurring revenue streams.
- Consulting:NVMe-oF migration assessments and protocol convergence roadmaps address stranded infrastructure risks. Interoperability testing overhead consumes engineering resources.
Professional Services captures the largest services revenue. Managed Services shows the steepest expansion trajectory as subscription models displace perpetual licenses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Mid-market enterprises in India negotiate aggressively on Fibre Channel switch costs, while financial institutions in the United States and Germany accept substantial premiums for sub-10 microsecond latency guarantees.
United States
Federal contractors drive encrypted fabric procurement under FedRAMP Moderate and High baselines. The SEC mandates continuous monitoring capabilities for cloud-adjacent storage infrastructure serving financial services clients. Chicago hosts high-frequency trading firms deploying computational storage drives for media-level erasure coding.
Germany
Deutsche Bundesbank infrastructure for central bank digital currency settlement requires deterministic throughput below 10 microseconds. The EU AI Act imposes data lineage and immutability requirements on AI training clusters. Frankfurt anchors encrypted-at-rest array deployments for automotive manufacturers integrating AI-driven quality control systems.
Japan
Bank of Japan real-time settlement ledgers demand cryptographic transaction validation with sub-10 microsecond fabric latency. METI oversees data residency requirements for financial infrastructure modernization. Tokyo channel partners unbundle hardware acquisition from professional services, offering consumption-aligned financing through captive leasing subsidiaries.
India
Hyperscale facility investments in Mumbai and Chennai create greenfield deployment opportunities outside legacy Fibre Channel footprints. The PLI scheme for electronics manufacturing attracts data center construction with cost-optimized procurement expectations. Indian mid-market enterprises leverage existing Ethernet switch infrastructure for iSCSI-based greenfield installations.
United Kingdom
Financial services firms in the City of London procure NVMe-grade performance tiers for latency-sensitive trading workloads. GDPR and emerging AI governance frameworks impose audit trail requirements on storage configurations. London hosts interoperability testing facilities for multi-vendor SAN qualification matrices serving European telecommunications operators.
Storage Area Network (SAN) Solutions Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Incumbent vendors with proprietary fabric operating systems command premium pricing through custom ASIC controller development, while Asia-based competitors penetrate price-sensitive segments with standardized switch portfolios. Two strategic archetypes dominate: integrated infrastructure providers leveraging server-to-storage integration depth, and all-flash specialists eliminating hybrid disk dependencies. Competitive moves concentrate on protocol convergence roadmaps and disaggregated storage pool architectures.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise occupy positions anchored by federal deployment relationships and multi-year support contracts. Pure Storage exemplifies the all-flash specialist archetype, representing vendors that bypass hybrid configurations entirely. Huawei Technologies sits within the cost-optimized tier, competing on Fibre Channel switch portfolios across Asia-Pacific and Middle Eastern installations where procurement timelines face geopolitical fab utilization constraints.
| Leading Market Players |
|---|
| IBM Corporation |
| Hitachi Vantara |
| Dell Technologies |
| Broadcom |
| Pure Storage |
| Hewlett Packard Enterprise |
| Cisco Systems |
| Huawei Technologies |
| NetApp |
| Others |
Value Network & Pricing Analysis
NVMe-oF protocol substitution for legacy Fibre Channel is redrawing supply geography toward Ethernet-native component ecosystems while compressing pricing premiums previously anchored to proprietary ASIC controller development. This technology transition simultaneously fragments procurement patterns across enterprise tiers and redirects margin pools from custom silicon vendors toward standardized switch fabric suppliers.
Pricing Analysis
Multi-year support and maintenance contracts drive lifetime value in high-end SAN deployments, with recurring revenue streams often exceeding initial hardware acquisition costs over a seven-to-ten year operational horizon. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-certified federal configurations from mid-market hybrid arrays and entry-level iSCSI systems. Cost compression in mid-range Fibre Channel switches is intensifying because Asia-based competitors are penetrating price-sensitive segments with standardized portfolios. Indian mid-market enterprises exhibit the highest price sensitivity, leveraging existing Ethernet infrastructure for greenfield iSCSI installations, while German central banks accept substantial premiums for sub-10 microsecond latency guarantees.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes and container availability constraints on trans-Pacific routes are elevating inbound logistics costs for specialized storage controllers and custom ASIC components. Advanced 7nm and 5nm fabrication for storage ASICs concentrates among Taiwan-based foundries, with secondary supply nodes in South Korea and the United States. Controller silicon supply rests on concentrated semiconductor manufacturing, NAND flash memory supply, and specialized Fibre Channel transceiver modules. Single-source vulnerability around Taiwan-based foundry utilization exposes procurement timelines to geopolitical disruption. Distribution runs through direct vendor relationships for high-end systems and value-added distributor networks for mid-market and entry-level deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around protocol convergence, as NVMe-oF maturation creates distinct competitive arenas for disaggregated storage specialists alongside incumbent Fibre Channel vendors serving latency-sensitive financial infrastructure.
For Market Incumbents: Consolidate proprietary fabric operating system advantages through deeper custom ASIC controller integration, locking healthcare and telecommunications operators into deterministic performance guarantees. Expand encrypted fabric certification pipelines to accelerate FedRAMP authorization timelines for federal contractors. Channel control represents the critical lever against Asia-based cost competitors penetrating price-sensitive segments.
For New Entrants and Emerging Players: SOC 2 Type II fast-track certification enables penetration of healthcare patient data archive modernization cycles, where attestation bottlenecks stretch 9-14 months and incumbent professional services margins concentrate. Target India's PLI scheme-driven hyperscale facility investments in Mumbai and Chennai for greenfield NVMe-oF over TCP deployments outside legacy Fibre Channel footprints. Consumption-aligned financing partnerships with captive leasing subsidiaries offer the strongest go-to-market angle against entrenched vendor relationships.
For Investors and Strategic Acquirers: The market sits at a protocol transition phase that favors disaggregated storage architecture specialists over incumbent vertically integrated infrastructure providers. Long-term viability across a five-to-ten year window favors vendors with controller silicon independence and multi-cloud fabric management capabilities. Acquisition target archetype: all-flash array specialists with established NVMe-oF roadmaps and healthcare compliance certifications. The signal to watch is central bank digital currency infrastructure procurement velocity in Germany and Japan as a leading indicator for high-end SAN refresh cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-oF Controller Architecture Migration | Disaggregated storage pools reduce stranded Fibre Channel infrastructure risk for federal contractors under FedRAMP mandates. |
| Custom ASIC Development Investment | Proprietary silicon locks Deutsche Bundesbank and Bank of Japan settlement ledger deployments into multi-year support contracts. |
| Encrypted Fabric Certification Pipeline | Accelerated SOC 2 Type II attestation timelines capture healthcare patient data archive modernization cycles. |
| Consumption-Aligned Financing Subsidiary | Japanese channel partners unbundle hardware acquisition to aggregate mid-market demand across multiple verticals. |
| Computational Storage Drive Integration | Media-level erasure coding collapses network traffic volumes for Chicago high-frequency trading firms. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with data center infrastructure architects, storage procurement officers at financial institutions, Fibre Channel fabric administrators, and cloud-adjacent SAN deployment specialists; and secondary validation against SEC 10-K filings, hyperscaler capex disclosures, FedRAMP authorization databases, and ISO 27001 certification registries. Bottom-up triangulation across vendor shipment disclosures and top-down reconciliation against enterprise storage refresh cycle surveys anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand across product type, protocol technology, end-user vertical, and service engagement model dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included central bank digital currency infrastructure procurement timelines and NVMe-oF protocol standardization milestones.
Decision-makers should treat outputs as directional under assumptions of continued Fibre Channel skill scarcity and stable Taiwan-based foundry utilization; material deviation in semiconductor supply geography or protocol convergence velocity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
All Flash Storage Market
Data Storage
Blu-Ray Drive Market
Data Storage
Zoned Flash Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
Archival Grade Blu-Ray Discs Market
Data Storage
Recordable Optical Disc Market
Data Storage
Wi-Fi SD Cards Market
Data Storage
Transparent Caching Market
Data Storage
Substrates for Magnetic Disks Market
Data Storage
Hardware Storage Market
Data Storage
AI Powered Storage Market
Data Storage
Europe Flash Memory Market
Data Storage
Serial EEPROM Market
Data Storage
OTG Pen Drive Market
Data Storage
Global Portable Data Storage Market
Data Storage
Object-Based Storage Market