
 Non-Volatile Memory (NVM) Market | 2026-2036
Non-Volatile Memory (NVM) Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Volatile Memory (NVM) Market Analytics
Aftermarket firmware licensing is rewriting margin economics across the NVM value chain. Samsung Electronics Co. Ltd. anchors high-volume 3D NAND wafer output through captive foundry control. SK Hynix Inc. competes aggressively in HBM and advanced packaging nodes for AI servers. Intel Corporation leverages its Optane legacy to sustain enterprise SSD controller design leadership.
Non-volatile memory retains stored data without continuous power, using floating-gate transistors, magnetic tunnel junctions, or phase-change materials to achieve retention spans exceeding ten years at operating temperatures up to 85°C. Flash Memory dominates product-level revenue, with 3D NAND layers now exceeding 200 vertical tiers and pushing bit-cost reductions. Phase Change Memory occupies niche high-endurance segments in automotive ECUs, while Spintronics-based MRAM is gaining traction in edge AI inference devices requiring instant-on functionality.
FDA oversight of medical device data integrity and EPA hazardous substance rules for semiconductor manufacturing both elevate compliance costs for NVM suppliers serving regulated end markets. REACH restrictions on fluorinated greenhouse gases constrain etching chemistries in European fabs, while China's MEE enforces wastewater discharge limits that affect yield economics. Stakeholders must monitor how export control harmonization between the US, Japan, and the Netherlands reshapes equipment access for advanced node expansion.
Market Dynamics
Flash memory density scaling through 200-plus layer 3D NAND architectures is compressing bit costs while concentrating wafer output in South Korea's Hsinchu-to-Seoul memory corridor, reshaping procurement leverage for enterprise storage buyers.
Growth Catalysts
- AI Training Workload Surge:Enterprise data centers are expanding flash-based storage arrays to handle generative AI model training datasets. Hyperscalers in the United States and China are driving petabyte-scale NAND procurement.
- EU F-Gas Regulation:Tightening fluorinated gas emission limits for semiconductor etching processes are accelerating fab equipment upgrades. European memory suppliers are investing in alternative chemistries to maintain production licenses.
- Automotive ECU Data Logging:Phase Change Memory's high-endurance characteristics suit powertrain control modules requiring ten-year data retention. Tier-1 suppliers in Germany and Japan are qualifying PCM for next-generation vehicle platforms.
Market Restraints
- Extreme Ultraviolet Lithography Dependency:Advanced node scaling requires ASML EUV equipment access constrained by trilateral export controls between the United States, Japan, and the Netherlands. Equipment scarcity limits capacity expansion timelines.
- Fluorinated Greenhouse Gas Supply:REACH restrictions on etching chemistries constrain process gas availability for European 3D NAND fabs. Alternative precursor development remains immature.
- Spin-Transfer Torque MRAM Density Ceiling:Current STT-MRAM cell sizes limit cost-competitive displacement of SRAM in cache hierarchies. Density improvements require materials breakthroughs in magnetic tunnel junction stacks.
Strategic Opportunities
- Edge AI Inference Instant-On:Spintronics-based MRAM's zero standby power suits battery-constrained IoT sensors. Deployment is concentrating in Japanese industrial automation and German automotive sensor modules.
- India PLI Scheme Incentives:Production-linked incentives for electronics manufacturing are attracting NAND packaging and module assembly investments. Domestic data center buildouts create captive demand pull.
- Controller Firmware Licensing:Aftermarket firmware customization for enterprise SSDs opens recurring revenue streams. Independent software vendors are penetrating cloud service provider procurement channels.
Industry Challenges
- Advanced Packaging Talent Scarcity:Hybrid bonding and through-silicon via expertise for HBM stacking resides with a limited pool of engineers in South Korea and Taiwan. Compensation inflation is compressing R&D margins.
- Multi-Generational Interface Migration:PCIe 5.0 and CXL memory fabric adoption requires simultaneous controller, firmware, and system BIOS updates. Validation cycles extend product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Volatile Memory (NVM) Market |
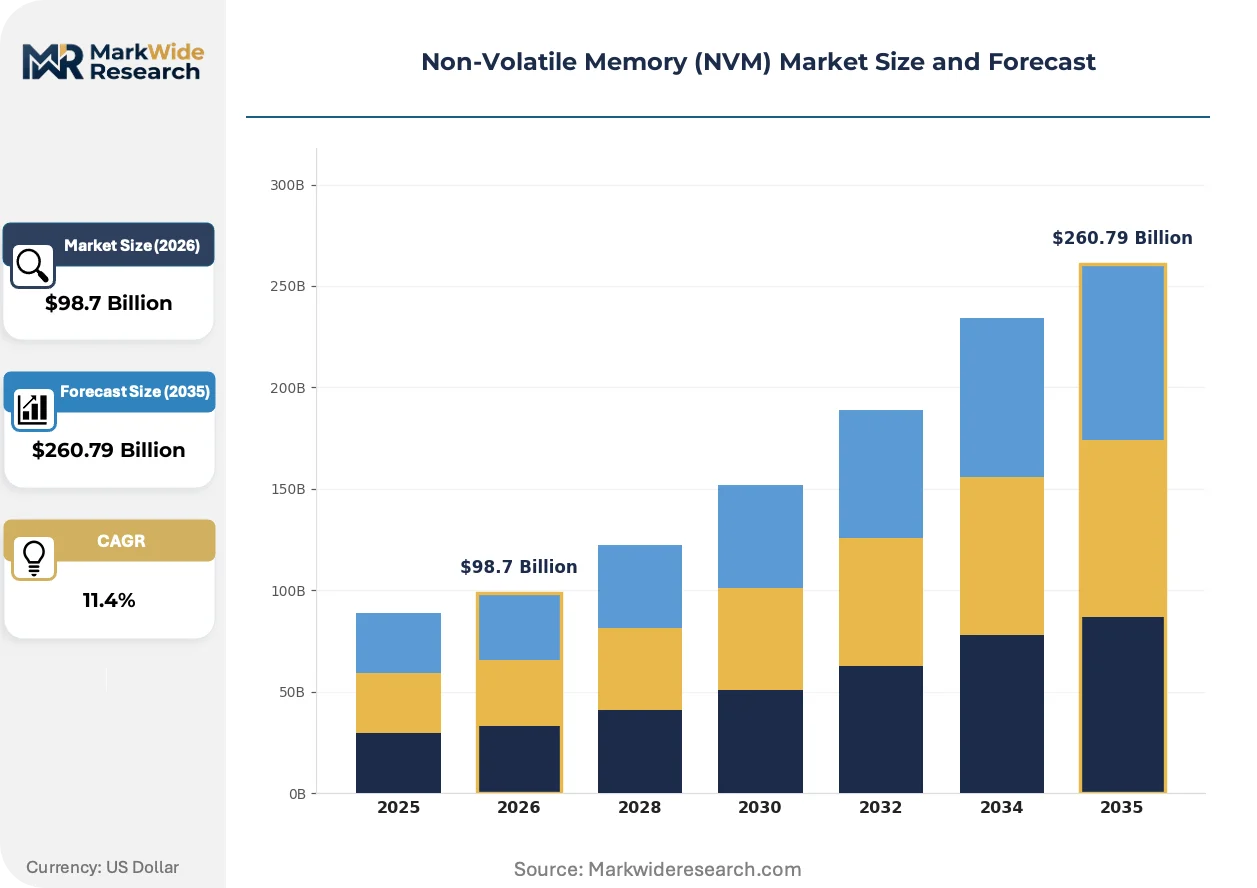
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
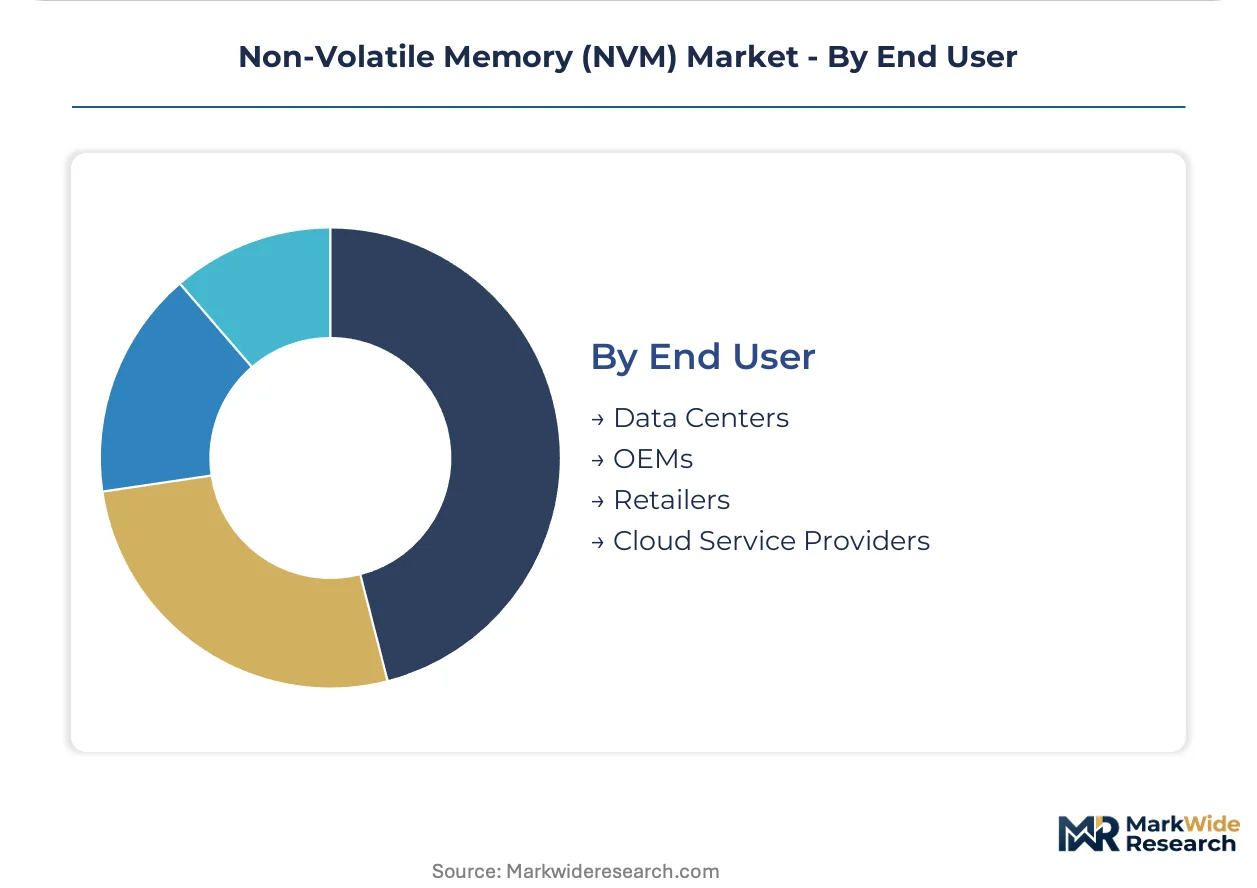
| Segmentation | Product Type: Flash Memory, ROM, EEPROM, MRAM Application: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Technology: 3D NAND, NOR Flash, Phase Change Memory, Spintronics End User: Data Centers, OEMs, Retailers, Cloud Service Providers |
| Companies Covered | Western Digital Corporation, Intel Corporation, Samsung Electronics Co. Ltd., NXP Semiconductors N.V., Toshiba Corporation, Micron Technology Inc., KIOXIA Holdings Corporation, STMicroelectronics N.V., SK Hynix Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Volatile Memory (NVM) Market Evolving Landscape
Memory architecture decisions are increasingly decoupled from processor roadmaps as disaggregated data center designs prioritize storage-class memory hierarchies independent of CPU socket constraints.
Charge-trap flash technology is migrating from consumer SSDs to enterprise QLC deployments. Cloud storage operators are adopting 176-layer and 232-layer QLC NAND for warm data tiers previously served by hard disk drives. This transition is compressing $/GB metrics while extending endurance requirements through advanced error correction firmware.
China's MIIT dual carbon enforcement and MEE wastewater discharge limits are forcing memory fabs to recirculate process chemicals and capture fluorinated byproducts. Yield economics suffer from added purification steps. South Korean suppliers with existing zero-liquid-discharge infrastructure are capturing capacity expansion permits faster than competitors.
Hyperscale buyers are consolidating SSD procurement through direct NAND wafer purchasing rather than finished drive acquisition. Cloud service providers in the United States are negotiating long-term supply agreements with captive foundry operators. This disintermediation of module assemblers is visible in Virginia and Oregon data center clusters where direct wafer-to-drive integration lines are being installed on-site.
Non-Volatile Memory (NVM) Market Segmentation

Technology heterogeneity across NVM architectures creates distinct procurement patterns. Buyers segment by endurance requirements, retention specifications, and interface compatibility rather than density alone.
Product Type:
Cost tier differentiation separates commodity bit storage from premium persistent memory solutions.
- Flash Memory:Charge-trap and floating-gate cells dominate petabyte-scale deployments. Hyperscalers in the United States negotiate direct wafer supply agreements for QLC and TLC NAND to bypass module markup.
- MRAM:Magnetic tunnel junction arrays deliver unlimited write endurance with zero standby power. Japanese industrial automation vendors are qualifying STT-MRAM for sensor fusion modules requiring instant-on reliability.
- EEPROM:Byte-addressable electrical erasure suits configuration storage in network equipment. Cisco Systems and Juniper Networks maintain multi-source qualification lists for 1Mb to 128Mb densities.
- ROM:Mask-programmed content persists without power for firmware bootstrap routines. Automotive ECU suppliers in Germany specify one-time programmable variants for airbag controller immutable code storage.
Flash Memory commands the established base. The steepest expansion runs through MRAM.
Application:
End-use environment dictates reliability grades, temperature specifications, and qualification protocols.
- Automotive:Powertrain control modules require AEC-Q100 Grade 0 compliance for 150°C ambient operation. Phase Change Memory from Intel's legacy roadmap is penetrating German Tier-1 data logging specifications.
- Consumer Electronics:UFS 4.0 and NVMe BGA packages dominate smartphone storage subsystems. South Korean handset OEMs specify 512GB to 1TB 3D NAND stacks with integrated controllers.
- Industrial Automation:Programmable logic controllers demand 20-year retention for recipe and calibration data. Siemens and Rockwell Automation specify industrial-grade SLC NAND for deterministic write latency.
- Telecommunications:Baseband units and radio heads buffer streaming data through high-endurance storage. Ericsson and Nokia are qualifying 176-layer TLC for 5G massive MIMO deployment.
Automotive commands the established base. The steepest expansion runs through Industrial Automation.
Technology:
Process maturity and lithography requirements stratify manufacturing economics across memory architectures.
- 3D NAND:Vertical stacking of 200-plus charge-trap layers compresses bit costs below hard disk parity. SK Hynix and Samsung Electronics anchor wafer output in South Korea's Hsinchu-to-Seoul corridor.
- Spintronics:Magnetic tunnel junction physics enables non-volatile cache hierarchies with SRAM-competitive speed. Everspin Technologies supplies discrete MRAM to aerospace contractors requiring radiation tolerance.
- NOR Flash:Fast random read access supports execute-in-place code storage for boot firmware. Macronix and Winbond concentrate supply for automotive instrument cluster graphics buffering.
- Phase Change Memory:Chalcogenide alloy phase transitions deliver DRAM-class byte addressability with persistence. Intel's Optane discontinuation has shifted automotive PCM demand to STMicroelectronics and Micron Technology roadmaps.
3D NAND commands the established base. The steepest expansion runs through Spintronics.
End User:
Procurement scale and technical integration depth determine supplier relationship structures.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud negotiate multi-year NAND wafer offtake agreements. Direct foundry relationships disintermediate traditional SSD assemblers for Virginia and Oregon data center buildouts.
- Data Centers:Enterprise colocation operators specify NVMe-oF fabrics and storage-class memory tiers. Equinix and Digital Realty are deploying CXL 2.0 memory expansion modules for AI training clusters.
- OEMs:Original equipment manufacturers integrate NVM at board level with custom firmware stacks. Dell Technologies and Hewlett Packard Enterprise maintain controller design teams for enterprise SSD differentiation.
- Retailers:Distribution channels serve prosumer and small business segments through branded external storage. Best Buy and Amazon segment SKUs by interface generation and warranty tier rather than NAND source.
Cloud Service Providers command the established base. The steepest expansion runs through Data Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in South Korea and China exhibit low price elasticity for high-layer 3D NAND, while Indian and Southeast Asian module assemblers remain highly sensitive to wafer cost fluctuations. This demand-elasticity contrast shapes regional procurement strategies.
United States
Hyperscalers in Virginia and Oregon data center clusters negotiate direct NAND wafer offtake agreements, bypassing traditional SSD assemblers. EPA hazardous substance rules for semiconductor manufacturing elevate compliance costs for fabs serving medical and automotive end markets. Austin and Phoenix anchor captive foundry expansion for enterprise storage controller design.
South Korea
AI training workload concentration drives petabyte-scale procurement from cloud service providers anchored in Seoul. The Ministry of Environment enforces wastewater discharge limits that favor suppliers with zero-liquid-discharge infrastructure. The Hsinchu-to-Seoul memory corridor concentrates 200-plus layer 3D NAND wafer output.
China
Domestic data center buildouts create captive demand pull for NAND packaging and module assembly. MIIT dual carbon enforcement and MEE wastewater regulations force memory fabs to recirculate process chemicals and capture fluorinated byproducts. Yangtze Memory Technologies anchors capacity in the Yangtze River Delta cluster.
Germany
Tier-1 automotive suppliers qualify Phase Change Memory for powertrain control modules requiring AEC-Q100 Grade 0 compliance. EU F-Gas Regulation tightens fluorinated gas emission limits for semiconductor etching processes. Dresden and Munich anchor automotive ECU firmware development clusters.
Japan
Industrial automation vendors qualify STT-MRAM for sensor fusion modules requiring instant-on reliability. METI standards guide magnetic tunnel junction stack development for radiation-tolerant applications. Tokyo and Nagoya concentrate spintronics research for edge AI inference devices.
Non-Volatile Memory (NVM) Market Competitive Landscape
Captive foundry operators and independent memory specialists split the market into distinct strategic tiers. Consolidation characterizes high-volume 3D NAND supply, where wafer output concentrates among vertically integrated conglomerates. Three archetypes dominate: captive foundry giants controlling lithography and etching assets, fabless controller designers licensing firmware stacks, and specialty memory fabricators serving radiation-tolerant and automotive-grade niches. Competitive moves center on direct hyperscaler wafer agreements and advanced packaging talent acquisition for HBM stacking.
Within the captive foundry tier, Samsung Electronics Co. Ltd. and SK Hynix Inc. exemplify scale-driven vertical integration, while Intel Corporation occupies a position bridging enterprise SSD controller design with legacy persistent memory expertise. These three anchors represent contrasting geographic and structural approaches to NVM supply.
| Leading Market Players |
|---|
| Western Digital Corporation |
| Intel Corporation |
| Samsung Electronics Co. Ltd. |
| NXP Semiconductors N.V. |
| Toshiba Corporation |
| Micron Technology Inc. |
| KIOXIA Holdings Corporation |
| STMicroelectronics N.V. |
| SK Hynix Inc. |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation exposure determines both the spread between premium-grade and commodity NAND pricing and the geographic configuration of etching chemical supply networks. Memory fabs in Germany and France face elevated compliance costs that compress margins on standard-tier products while pushing high-reliability segments toward South Korean zero-liquid-discharge facilities.
Pricing Analysis
Aftermarket firmware licensing drives lifetime value for enterprise SSD suppliers. Three-tier pricing structure across premium, standard, and economy levels separates cloud-optimized QLC wafers from industrial-grade TLC modules and consumer SATA drives. Cost compression in commodity NAND intensifies because hyperscalers negotiate direct wafer offtake agreements. Cloud service providers exhibit the lowest price sensitivity, while Indian module assemblers face acute margin pressure from wafer cost volatility.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for equipment-dependent capacity expansion. Wafer output concentrates in South Korea, China, and Japan, with advanced lithography tools drawing from Dutch and Japanese suppliers. Fluorinated precursor availability presents single-source vulnerability for European etching operations. Distribution runs through captive foundry direct sales to hyperscalers, bypassing traditional module integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI training workload proliferation is reshaping NVM demand structures, with the EU F-Gas Regulation acting as the decisive regulatory inflection that will partition competitive survivors from stranded capacity.
For Market Incumbents: Build captive controller firmware ecosystems to lock in hyperscaler procurement relationships. Secure zero-liquid-discharge permits in South Korea's Hsinchu-to-Seoul corridor ahead of competitors. Acquire advanced packaging talent pools in Taiwan to defend HBM stacking leadership against emerging Chinese entrants. For New Entrants and Emerging Players: Establish a beachhead in Indian PLI-subsidized packaging and module assembly to capture domestic data center demand. Target automotive PCM qualification in Germany where Intel's Optane discontinuation has opened Tier-1 supplier relationships. Lead with radiation-tolerant MRAM for Japanese aerospace and industrial automation sensor fusion. For Investors and Strategic Acquirers: US-Japan-Netherlands export control harmonization reshapes the acquisition landscape for EUV-dependent memory capacity. Five-to-ten-year viability hinges on foundry operators with existing advanced node equipment access. Monitor ASML equipment delivery timelines as the critical inflection signal for capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Direct NAND Wafer Offtake Agreements | Hyperscalers in Virginia and Oregon bypass module assemblers to compress $/GB metrics. |
| Zero-Liquid-Discharge Infrastructure Investment | South Korean suppliers capture capacity permits faster under MEE wastewater enforcement. |
| Advanced Packaging Talent Acquisition | HBM stacking expertise in Taiwan and South Korea commands compensation premiums that compress R&D margins. |
| Alternative Etching Chemistry Development | European fabs secure production licenses under REACH fluorinated gas restrictions. |
| Controller Firmware Licensing Expansion | Independent software vendors penetrate cloud service provider procurement channels with recurring revenue. |
Research Methodology
Desk research of SEC 10-K filings, hyperscaler capex disclosures, and customs trade data preceded structured interviews with NAND foundry operations executives, enterprise SSD procurement managers, and advanced packaging engineers. Primary fieldwork with cloud service provider infrastructure teams and automotive Tier-1 supplier quality directors validated secondary projections. Bottom-up wafer output estimates and top-down storage demand forecasts underwent cross-triangulation.
Assumptions held EU F-Gas Regulation enforcement timelines and US-Japan-Netherlands export control scope fixed, while AI training workload intensity and China MIIT dual carbon compliance costs varied across scenarios. Segmentation modeling spanned technology node, application environment, and end-user procurement scale. CAGR derivation drew from layer-count ramp schedules and bit-cost compression curves, with foundry utilization rates and etching chemistry yields as NVM-specific sensitivity inputs.
Sensitivities concentrate around ASML equipment delivery delays, REACH fluorinated precursor supply disruptions, and hyperscaler capital expenditure cycle turns. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology migration timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Memory Chips
Magnetoresistive Random Access Memory (MRAM) Market
Memory Chips
China Flash Memory Market
Memory Chips
Static Random-Access Memory (SRAM) Market
Memory Chips
Japan Semiconductor Memory Market
Memory Chips
Smartphone RAM Market
Memory Chips
Contactless Memory Market
Memory Chips
Mobile DRAM Market
Memory Chips
Global Standalone Memory Market
Memory Chips
Memory Interface Chip Market
Memory Chips
Embedded Non-Volatile Memory Market
Memory Chips
In-Memory Grid Market
Memory Chips
Memory IC Market
Memory Chips
eMMC Master Control Chip Market
Memory Chips
Japan Flash Memory Market
Memory Chips
Next Generation Non Volatile Memory Market
Memory Chips
Next Generation Memory Market