
 China Solid-State Drive Market | 2026-2036
China Solid-State Drive Market Size, Share, and Industry Trends Forecast 2026-2036
China Solid-State Drive Market Outlook
Yangtze Memory Technologies Co., Ltd. is shifting toward captive NAND supply for domestic OEMs, altering how Chinese SSD vendors source flash memory. Samsung Electronics Co., Ltd. leverages its vertically integrated 3D NAND foundries to sustain price competitiveness in enterprise channels. SK Hynix Inc. anchors high-performance NVMe portfolios for data center operators seeking low-latency storage.
A solid-state drive stores data in semiconductor flash memory cells rather than magnetic platters, with NVMe protocols delivering sequential read speeds exceeding 3,500 MB/s for latency-sensitive workloads. NAND flash density, measured in layers per die, determines cost-per-gigabyte and endurance ratings across client and enterprise tiers. NVMe SSDs command premium positioning in data center deployments where throughput density reduces rack-level power consumption, while SATA SSDs retain volume share in cost-optimized consumer electronics refreshes. TLC NAND balances cell longevity with wafer yield economics, capturing the bulk of mainstream enterprise procurement.
MIIT enforces GB standard compliance for electromagnetic compatibility and data encryption across domestically sold storage devices, compelling firmware-level security integration. SAMR scrutinizes flash memory pricing under anti-monopoly provisions, influencing how NAND suppliers contract with downstream SSD assemblers. The country's dual carbon goals pressure fab operators to decarbonize wafer production, adding compliance layers to supply qualification. Stakeholders must weigh captive NAND availability against import-dependent controller sourcing as geopolitical friction reshapes component trade flows.
Market Dynamics
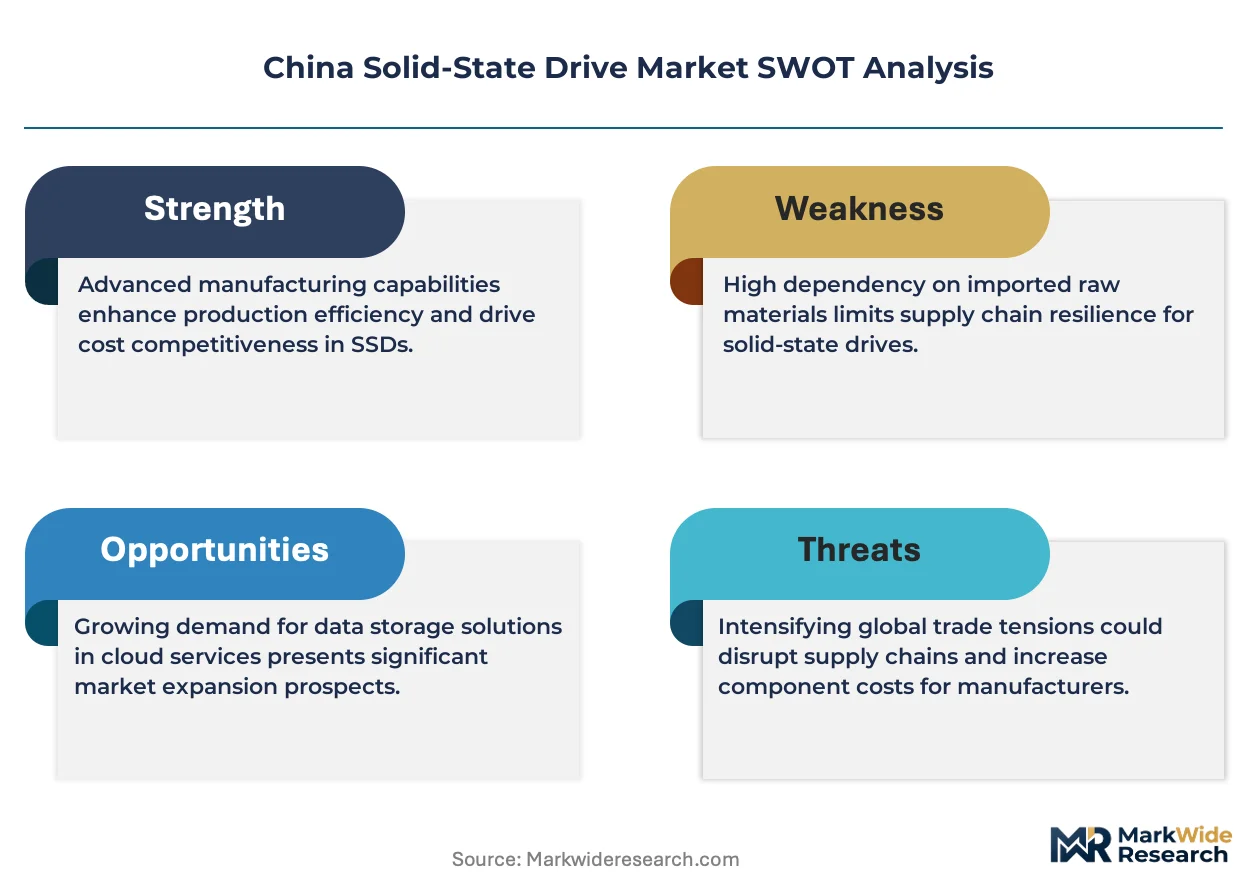
TLC NAND cost economics and NMPA-aligned data security mandates are restructuring how Chinese SSD vendors source flash memory and integrate encryption firmware, compressing margins for import-dependent controller suppliers while rewarding captive NAND producers.
Growth Catalysts
- Yangtze River Delta server procurement:Hyperscale data center operators in Shanghai and Hangzhou are expanding NVMe storage racks for AI training workloads, pulling enterprise-grade SSD volumes upward.
- MIIT electromagnetic compatibility standards:Mandatory GB compliance for electromagnetic interference is forcing firmware-level security integration, creating qualified supplier lists that favor domestic controller designers.
- 3D NAND layer stacking:Advances in vertical cell density are reducing cost-per-gigabyte for TLC configurations, enabling broader substitution of mechanical hard drives in surveillance and industrial edge applications.
Market Restraints
- Controller import dependency:PCIe 4.0 and 5.0 controller silicon remains concentrated among Taiwanese and US fabless designers, exposing assemblers to export control friction and lead time volatility.
- Dual carbon compliance costs:MEE enforcement of fab decarbonization targets is adding energy audit layers to wafer qualification, raising effective NAND input costs for domestic SSD packagers.
- QLC endurance limitations:Quad-level cell flash exhibits lower program-erase cycle ratings than TLC alternatives, restricting penetration into write-intensive database and logging workloads.
Strategic Opportunities
- Chengdu-Chongqing electronics corridor:Western China manufacturing hubs are attracting SSD assembly investment through land and tax incentives, diversifying production geography beyond Shenzhen.
- Automotive zonal storage:Domain controller architectures in electric vehicles are creating demand for AEC-Q100 qualified SSDs with extended temperature tolerance, a segment with limited qualified domestic suppliers.
- GB/T data encryption mandates:NMPA-aligned requirements for hardware-level encryption are opening firmware customization contracts for security-certified domestic vendors.
Industry Challenges
- PCIe 5.0 signal integrity engineering:Fewer than ten domestic design houses possess the high-speed SerDes expertise required for next-generation enterprise controller development, creating talent scarcity.
- SAMR pricing scrutiny:Anti-monopoly investigations into NAND flash contracting terms are forcing vendors to document transfer pricing methodologies, extending sales cycle duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Solid-State Drive Market |
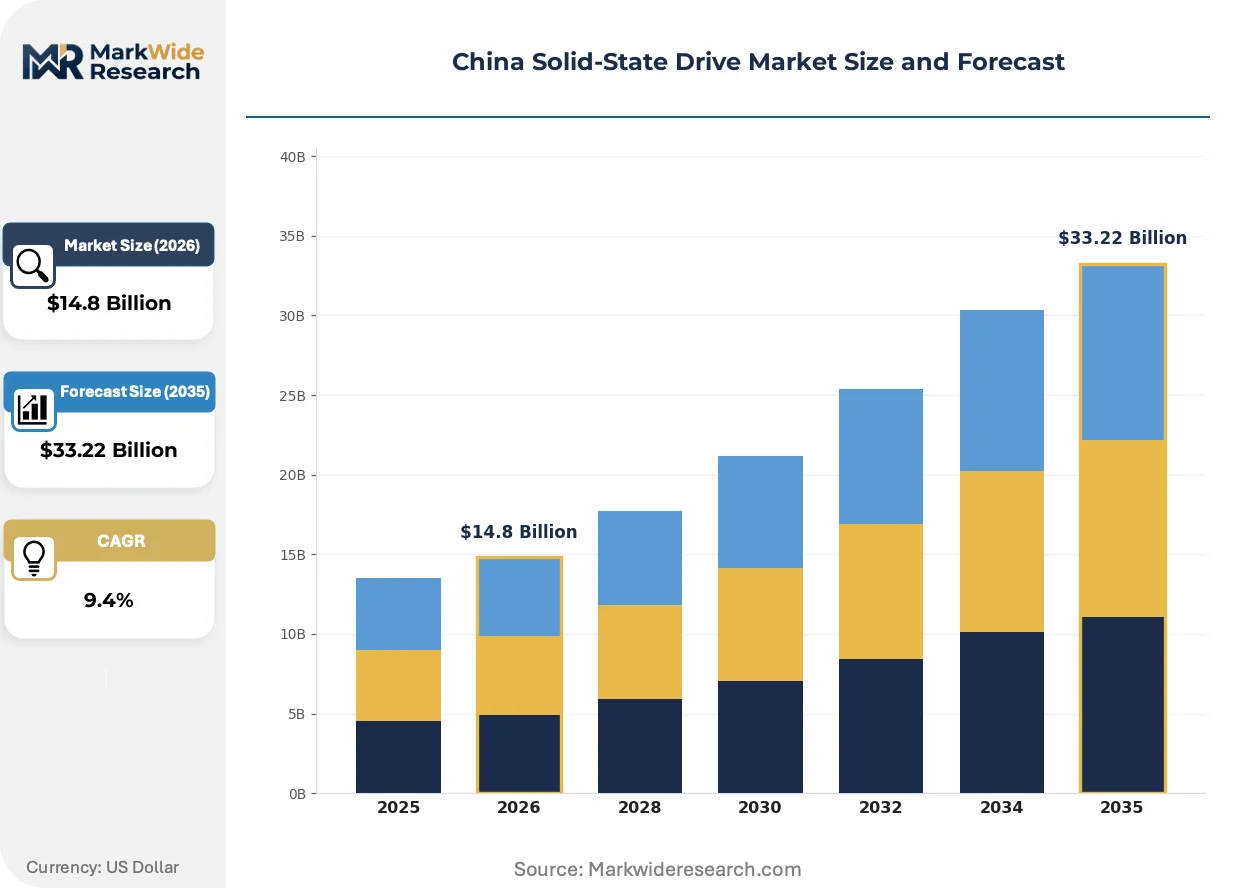
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SATA SSD, NVMe SSD, M.2 SSD, PCIe SSD, U.2 SSD Technology: 3D NAND, SLC NAND, MLC NAND, TLC NAND, QLC NAND Application: Enterprise Servers, Data Centers, Consumer Electronics, Gaming Systems, Workstations End User: IT Service Providers, Cloud Service Firms, E-Commerce Companies, Content Delivery Networks |
| Companies Covered | Kingston Technology Company, Inc., SK Hynix Inc., Yangtze Memory Technologies Co., Ltd., Biwin, Kimtigo, Union Memory, Western Digital Corporation, Shenzhen KingSpec Electronics Technology Co., Ltd., Samsung Electronics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Solid-State Drive Market Strategic Shifts
Flash memory architecture, regulatory encryption mandates, and procurement consolidation are converging to reshape how Chinese SSD vendors compete on cost, security certification, and supply assurance.
PCIe 5.0 NVMe controllers are electrifying enterprise storage performance benchmarks by doubling sequential throughput over Gen4 predecessors. Financial services and real-time analytics operators in Shanghai are piloting these devices for high-frequency trading infrastructure. The technology is compressing latency-sensitive workload economics by reducing rack-level drive counts.
MIIT's GB/T 35273 data security implementation guidelines are mandating hardware encryption modules for all storage devices processing personal information. This regulatory pressure is fragmenting firmware development roadmaps as vendors maintain separate SKUs for domestic and export markets. Enterprise channels are responding by pre-qualifying suppliers with certified encryption stacks.
Hyperscale direct procurement is displacing traditional distribution layers for high-volume enterprise SSD contracts. Alibaba Cloud and ByteDance infrastructure teams are negotiating annual supply agreements directly with NAND flash foundries and controller designers. This pattern concentrates most visibly in Shenzhen's electronics manufacturing corridor where contract assembly houses serve as fulfillment nodes rather than independent distributors.
China Solid-State Drive Market Segmentation
Segmentation in the China SSD market reveals how procurement power concentrates along protocol hierarchies and NAND density tiers. Vendors must align product roadmaps with MIIT certification requirements and the Yangtze River Delta's hyperscale procurement patterns.
Product Type:
Supply concentration in controller silicon shapes competitive dynamics across interface standards, with domestic firmware capabilities lagging behind NAND flash availability.
- NVMe SSD:PCIe-based protocol delivers sequential read speeds exceeding 3,500 MB/s through optimized command queuing. Hyperscale operators in Shanghai and Hangzhou deploy these in AI training clusters where latency reduction directly compresses rack-level power consumption. PCIe 5.0 transitions are accelerating as signal integrity engineering matures among domestic design houses.
- SATA SSD:Legacy AHCI protocol caps throughput at approximately 600 MB/s but retains cost advantages for cold storage and surveillance applications. Shenzhen's contract assemblers source these in volume for consumer electronics refreshes where mechanical hard drive substitution drives procurement.
- M.2 SSD:Compact form factor integrates directly onto motherboards, eliminating cable infrastructure. Gaming system builders in the Pearl River Delta specify these for thermal-constrained chassis.
- PCIe SSD:Add-in card format enables enhanced thermal dissipation for sustained write workloads. Financial services operators in Shanghai pilot these for high-frequency trading infrastructure.
- U.2 SSD:Hot-swappable 2.5-inch enclosure supports enterprise backplane compatibility. Data center operators prefer these for serviceability in dense storage arrays.
Today's leader: NVMe SSD. Tomorrow's challenger: PCIe 5.0 U.2 configurations.
Technology:
Wafer yield economics and endurance specifications stratify NAND flash procurement, with layer-stacking advances compressing cost-per-gigabyte curves.
- TLC NAND:Three bits per cell balances program-erase cycle longevity against wafer output efficiency. Enterprise server procurement across the Yangtze River Delta concentrates here, driven by NMPA-aligned data security mandates that require hardware-level encryption modules compatible with mainstream density tiers.
- 3D NAND:Vertical cell stacking architecture increases bit density per wafer, reducing effective input costs for SSD packagers. Yangtze Memory Technologies Co., Ltd. has expanded captive supply to domestic OEMs, altering sourcing patterns for controller-dependent assemblers.
- SLC NAND:Single-bit cells deliver highest endurance ratings for industrial and military applications. Limited volume constrains mainstream adoption.
- MLC NAND:Two-bit configuration occupies shrinking niche between TLC cost economics and SLC durability. Legacy workstation deployments sustain residual demand.
- QLC NAND:Four-bit cells maximize wafer yield but exhibit reduced write endurance. Cold storage and content delivery caching represent primary addressable applications.
TLC NAND commands current procurement volumes. QLC NAND is climbing the fastest as cold storage economics improve.
Application:
Workload characteristics determine interface selection, with throughput density and thermal constraints driving specification divergence.
- Enterprise Servers:Mission-critical infrastructure demands NVMe protocols with hardware RAID compatibility and power-loss protection capacitors. Hyperscale direct procurement from Alibaba Cloud and ByteDance infrastructure teams concentrates volumes among qualified domestic packagers.
- Data Centers:Rack-scale deployments prioritize throughput density to minimize floor space and cooling loads. Western China manufacturing hubs in Chengdu-Chongqing are attracting assembly investment through land and tax incentives.
- Consumer Electronics:Cost-optimized SATA and M.2 configurations dominate laptop and desktop refreshes. Shenzhen's electronics manufacturing corridor serves as primary fulfillment node.
- Gaming Systems:Low-latency NVMe specifications reduce load times for texture streaming. Thermal-constrained chassis favor M.2 form factors with integrated heat spreaders.
- Workstations:Mixed workloads balance capacity and endurance for content creation and engineering simulation. Professional segments sustain premium pricing for qualified suppliers.
Enterprise Servers anchor revenue concentration. Automotive zonal storage is gaining share fastest as electric vehicle domain architectures proliferate.
End User:
Procurement scale and technical specification authority differentiate customer segments, with cloud infrastructure operators exercising direct foundry relationships.
- Cloud Service Firms:Alibaba Cloud and ByteDance negotiate annual supply agreements directly with NAND flash foundries, displacing traditional distribution layers. These operators specify firmware customization for encryption compliance and telemetry integration.
- IT Service Providers:Systems integrators aggregate demand across mid-market enterprises, requiring flexible SKU configurations and logistics support. Qualified supplier lists favor domestic controller designers with MIIT electromagnetic compatibility certification.
- E-Commerce Companies:Fulfillment infrastructure and recommendation engines drive storage scaling requirements. Procurement concentrates in high-volume, cost-optimized tiers.
- Content Delivery Networks:Edge caching nodes prioritize read-intensive QLC economics over write endurance. Geographic distribution across China's tiered city hierarchy shapes deployment patterns.
Cloud Service Firms dominate specification authority. Automotive tier-one suppliers represent the steepest expansion trajectory for AEC-Q100 qualified storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance arbitrage is redirecting SSD assembly investment toward western Chinese manufacturing hubs where MEE decarbonization enforcement remains less stringent than in coastal zones. Domestic controller designers exploit this regulatory gradient to qualify products under MIIT electromagnetic compatibility standards before scaling to higher-cost markets.
Yangtze River Delta
Hyperscale data center operators in Shanghai and Hangzhou anchor enterprise NVMe procurement for AI training clusters. MIIT GB standards enforcement concentrates electromagnetic compatibility audits on this corridor's qualified supplier lists. Captive NAND supply from Yangtze Memory Technologies Co., Ltd. is displacing import-dependent flash memory in domestic OEM sourcing.
Pearl River Delta
Shenzhen's contract assemblers serve as fulfillment nodes for consumer electronics refreshes and gaming system M.2 specifications. SAMR anti-monopoly scrutiny into NAND flash contracting terms extends sales cycle duration for distributors operating here. Thermal-constrained chassis builders specify integrated heat spreaders for low-latency NVMe deployments.
Beijing-Tianjin-Hebei
State-owned enterprise server procurement concentrates in this northern corridor under NMPA-aligned data security mandates. Hardware-level encryption module requirements filter qualified suppliers through GB/T 35273 certification pathways. Government cloud infrastructure teams negotiate direct annual supply agreements with domestic controller designers.
Sichuan-Chongqing
Western China manufacturing hubs attract SSD assembly investment through land and tax incentives that offset MEE energy audit compliance costs. Chengdu-based packagers exploit lower effective NAND input costs to serve cost-optimized SATA tiers for surveillance applications. Automotive zonal storage demand from electric vehicle domain controllers is emerging fastest here.
Shandong Peninsula
Industrial edge applications for mechanical hard drive substitution pull TLC NAND volumes into factory automation and logistics infrastructure. Dual carbon goals pressure local fab operators to decarbonize wafer production, raising qualification layers for domestic SSD packagers. Cold storage economics for content delivery caching favor QLC configurations in read-intensive deployments.
China Solid-State Drive Market Competitive Environment
Korean producers anchor one tier; Chinese specialists hold assembly and firmware customization capabilities. The vendor base stratifies across captive NAND foundries, fabless controller designers, and contract packagers serving hyperscale direct procurement. Three archetypes dominate: vertically integrated flash memory suppliers, security-certified domestic controller houses, and volume-driven contract assemblers. Capacity expansion in 3D NAND layer stacking and strategic partnerships for PCIe 5.0 signal integrity engineering represent the dominant competitive moves.
Within the captive NAND tier, Yangtze Memory Technologies Co., Ltd. exemplifies domestic upstream control over flash memory supply. Among Korean fabricators, Samsung Electronics Co., Ltd. and SK Hynix Inc. occupy positions anchored to vertically integrated 3D NAND foundries. These three companies represent the core supply-side concentration shaping how downstream assemblers source components and qualify for MIIT electromagnetic compatibility certification.
| Leading Market Players |
|---|
| Kingston Technology Company, Inc. |
| SK Hynix Inc. |
| Yangtze Memory Technologies Co., Ltd. |
| Biwin |
| Kimtigo |
| Union Memory |
| Western Digital Corporation |
| Shenzhen KingSpec Electronics Technology Co., Ltd. |
| Samsung Electronics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
TLC NAND wafer contract pricing cascades through controller procurement and assembly margins into three distinct tiers for enterprise, industrial, and consumer channels. MIIT electromagnetic compatibility certification costs compress assembler margins while rewarding qualified domestic controller designers with pricing power in government cloud procurement.
Pricing Analysis
Distributor margin compression in Shenzhen's electronics corridor is accelerating hyperscale direct procurement from NAND flash foundries. Three-tier pricing structure across premium NVMe, standard SATA, and economy QLC configurations differentiates on GB/T encryption certification and volume scale. Cost compression in consumer tiers is intensifying because Yangtze Memory Technologies Co., Ltd. captive supply reduces import-dependent flash premiums. Cloud service firms exhibit lowest price sensitivity; surveillance integrators in western China manufacturing hubs are most price-sensitive.
Supply Chain Analysis
Freight cost differentials between coastal Shenzhen and inland Chengdu-Chongqing hubs are redirecting SATA assembly investment toward western tax-incentive zones. Controller silicon concentrates in Taiwan and the United States; NAND flash wafer supply draws from South Korea and domestic Yangtze Memory Technologies Co., Ltd. foundries. PCIe 5.0 SerDes expertise scarcity creates single-source vulnerability for enterprise controller procurement. Distribution runs through contract assemblers serving as fulfillment nodes rather than independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as NMPA-aligned data security mandates perpetuate hardware encryption upgrade cycles across government cloud infrastructure.
For Market Incumbents: Acquire PCIe 5.0 signal integrity engineering capabilities through specialist design house partnerships to defend enterprise NVMe positioning against Korean vertically integrated competitors. Add Chengdu-Chongqing assembly capacity to exploit MEE decarbonization enforcement gradients and lower effective NAND input costs for cost-optimized tiers. For New Entrants and Emerging Players: The price-point gap between AEC-Q100 qualified automotive SSDs and unqualified industrial alternatives offers white-space entry for domestic packagers with temperature-tolerance firmware customization. Target Sichuan-Chongqing electric vehicle domain controller demand through direct tier-one supplier qualification programs bypassing Shenzhen distribution layers. For Investors and Strategic Acquirers: Asymmetric upside sits with security-certified domestic controller houses possessing MIIT electromagnetic compatibility pre-qualification and GB/T encryption stack integration. Long-term viability hinges on backward integration resilience as export control friction intensifies. Watch hyperscale direct procurement concentration as inflection indicator for distributor margin collapse.| Strategic Initiative | Industry Significance |
|---|---|
| PCIe 5.0 Controller Development | Doubles sequential throughput for Shanghai financial services high-frequency trading infrastructure. |
| Chengdu-Chongqing Assembly Expansion | Exploits western tax incentives and lower MEE energy audit compliance costs. |
| GB/T Encryption Certification Investment | Opens NMPA-aligned government cloud procurement to qualified domestic firmware vendors. |
| Automotive AEC-Q100 Qualification | Captures electric vehicle domain controller storage demand from tier-one suppliers. |
| Captive NAND Supply Agreements | Reduces import dependency exposure as geopolitical friction reshapes component trade flows. |
Study Parameters
Multiple input streams — hyperscale infrastructure procurement disclosures, NAND flash foundry capacity announcements, and MIIT certification registry updates — were reconciled against primary interviews with data center operators, SSD packager procurement leads, and controller design house engineering directors. Secondary validation drew from customs trade data, SAMR anti-monopoly investigation filings, and Yangtze River Delta industrial park investment bulletins. Bottom-up assembly volume estimates and top-down hyperscale capex allocations were triangulated.
Historical procurement patterns were cross-referenced against panel input from cloud service firm infrastructure teams and contract assembler sales directors. Segmentation modeling spanned protocol tier, NAND density configuration, end-use application, and regional regulatory cluster. CAGRs were derived from volume trajectory reconciliation across enterprise server refresh cycles and consumer electronics substitution rates. Forecast inputs included 3D NAND layer-stacking roadmaps and PCIe generational transition timelines.
Caveats apply where SAMR pricing scrutiny intensification or MEE decarbonization enforcement acceleration could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Europe Next Generation Storage Market
Data Storage
Transparent Caching Market
Data Storage
Zoned Flash Market
Data Storage
NOR Flash Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Ethernet Storage Market
Data Storage
Next-Generation Storage Market
Data Storage
North America Next Generation Storage Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market
Data Storage
Storage Area Network (SAN) Solutions Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Blu-Ray Drive Market
Data Storage
Global Personal and Entry Level Storage (PELS) Market
Data Storage
Blu-Ray Optical Disk Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
SAS Hard Disk Drives Market