
 Global Hard Disk Drive (HDD) Market | 2026-2036
Global Hard Disk Drive (HDD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hard Disk Drive (HDD) Market Foresight
Subscription-based firmware management is decoupling hardware ownership from feature access in the HDD sector. Seagate Technology Holdings PLC leverages its vertically integrated manufacturing to control cost structures across enterprise and surveillance lines. Western Digital Corporation anchors its position through specialized energy-assisted recording technologies. Toshiba Corporation competes aggressively in nearline storage for data center operators.
A hard disk drive is an electromechanical data storage device that uses magnetically coated rotating platters, typically spinning at 5400 to 15000 revolutions per minute, with read/write heads positioned by actuator arms to store and retrieve digital information. The device serves as non-volatile secondary storage for computing systems ranging from personal devices to enterprise server farms. Enterprise drives command premium positioning due to sustained workload ratings and vibration tolerance specifications demanded by hyperscale facilities. Heat Assisted Magnetic Recording technology leads innovation investment as manufacturers push areal density boundaries beyond perpendicular magnetic recording limits. Desktop and laptop segments face structural pressure from solid-state alternatives, while network attached storage applications sustain consistent replacement cycles among small business users.
The EPA regulates hazardous substance restrictions in HDD manufacturing processes, while RoHS compliance mandates limit specific material content for devices sold across European markets. REACH obligations further constrain chemical inputs in plating and coating operations, forcing suppliers to certify alternative compositions. The EU AI Act introduces data localization requirements that indirectly expand storage infrastructure needs. Stakeholders must monitor energy efficiency standards from regulators in the United States, Europe, and China as power consumption metrics become procurement criteria for cloud operators.
Market Dynamics
Heat Assisted Magnetic Recording (HAMR) is compressing manufacturing timelines while hyperscale cloud operators concentrate procurement power in fewer hands, fundamentally restructuring supplier-buyer relationships across the storage ecosystem.
Growth Catalysts
- Data Center Expansion:Hyperscale facility construction in the United States, China, and Japan is pulling enterprise-grade nearline drives into multi-petabyte deployments.
- EU AI Act:Data localization mandates within European markets are forcing infrastructure buildouts that require localized storage hardware procurement.
- Energy-Assisted Recording:Areal density gains from HAMR and Microwave-Assisted Magnetic Recording are extending platter capacity without proportional cost increases.
Market Restraints
- Neodymium Supply Concentration:Rare earth magnet sourcing clusters in Chinese processing facilities, creating single-point vulnerability for spindle motor production.
- Solid-State Substitution:NAND flash price erosion in consumer and performance-tier enterprise segments is compressing addressable volume for rotating media.
- REACH Chemical Constraints:European plating and coating restrictions are forcing reformulation of head-stack assembly materials with extended qualification timelines.
Strategic Opportunities
- India Data Center Buildout:Domestic cloud infrastructure investments under PLI scheme incentives are creating fresh demand for nearline storage deployments.
- Surveillance-Optimized Firmware:Write-intensive workloads in video analytics applications favor high-capacity drives with customized caching algorithms.
- Subscription Firmware Licensing:Feature-unlocking models decouple hardware refresh cycles from capability upgrades, extending customer lifetime value.
Industry Challenges
- Cleanroom Technician Scarcity:Head-stack assembly requires sub-micron precision skills concentrated in aging workforces across Thai and Malaysian manufacturing hubs.
- Legacy SAS Integration:Enterprise storage arrays with SATA/SAS backplanes resist NVMe-over-Fabrics transitions, complicating interface roadmap decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hard Disk Drive (HDD) Market |
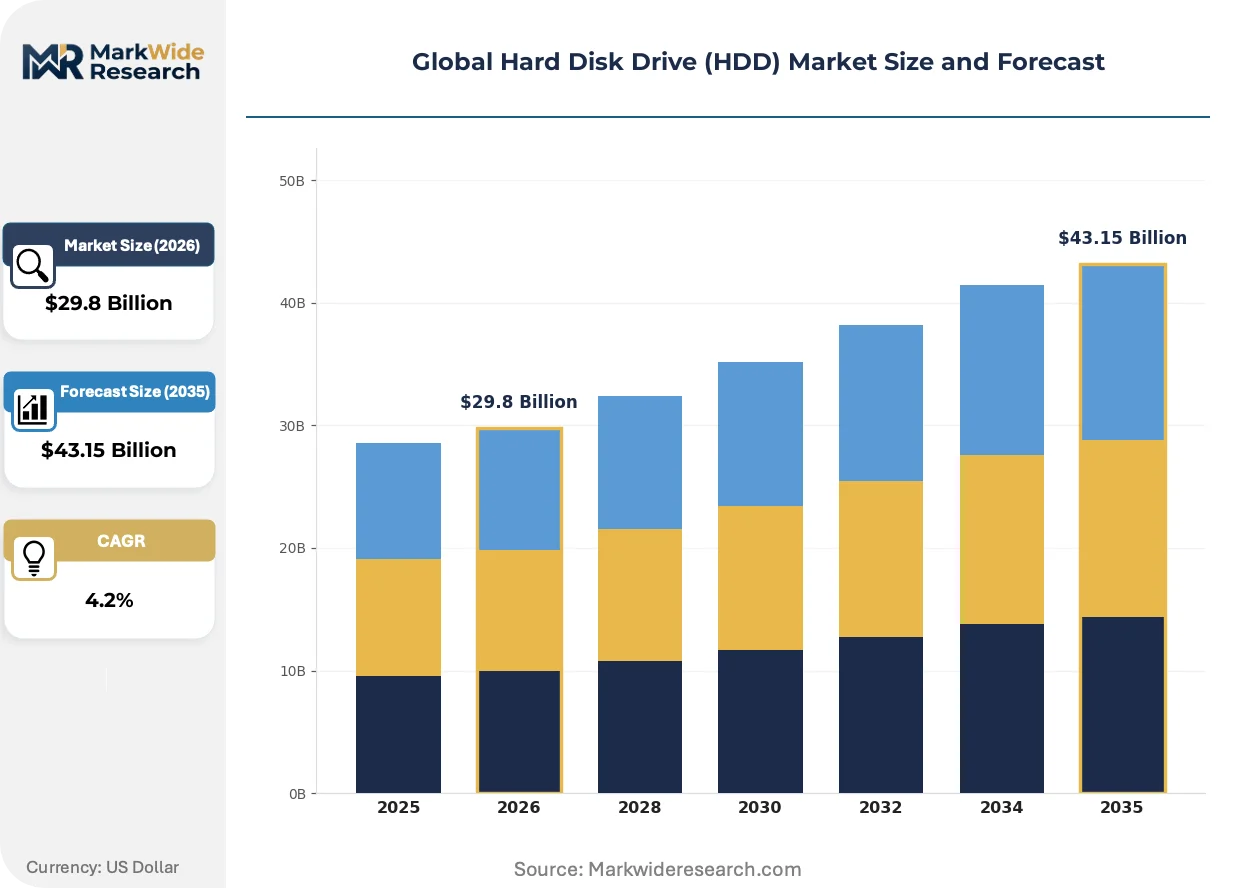
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $43.15 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
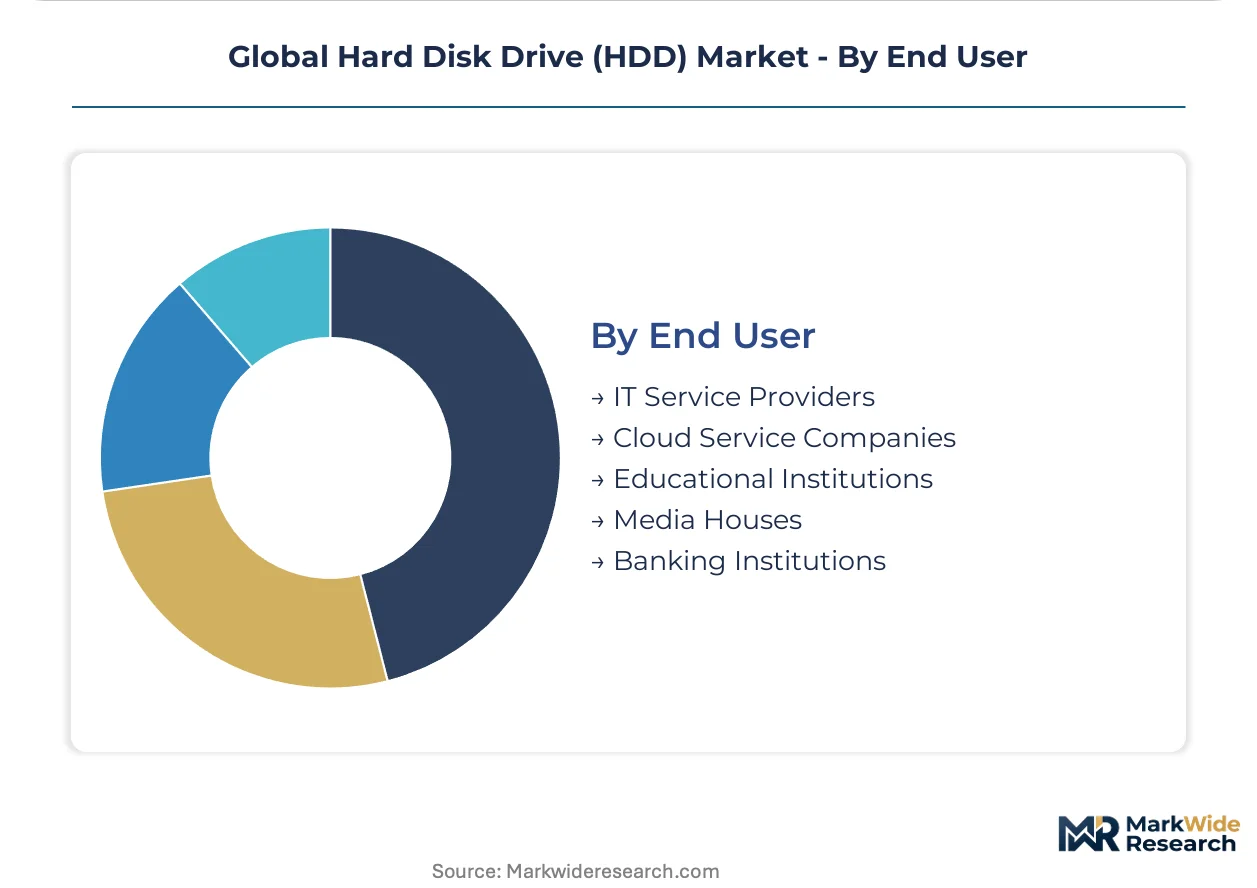
| Segmentation | Product Type: Desktop, Laptop, Enterprise, Surveillance, External Technology: Perpendicular Magnetic Recording, Shingled Magnetic Recording, Heat Assisted Magnetic Recording, Microwave Assisted Magnetic Recording Application: Data Centers, Personal Computing, Network Attached Storage, Videography, Scientific Research End User: IT Service Providers, Cloud Service Companies, Educational Institutions, Media Houses, Banking Institutions |
| Companies Covered | Sony Corporation, Transcend Information Inc., Seagate Technology Holdings PLC, Lenovo Group Limited, ADATA Technology Co. Ltd, Western Digital Corporation, Hewlett Packard Enterprise Development LP, QNAP Systems, Inc., Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hard Disk Drive (HDD) Market Shifts & Advancements
Recording physics breakthroughs and energy-efficiency mandates are forcing concurrent evolution in platter engineering and facility design. Manufacturers must balance areal density roadmaps against power consumption metrics that cloud operators now embed in procurement scorecards.
Heat Assisted Magnetic Recording (HAMR) is expanding into enterprise nearline segments as Seagate and Western Digital move beyond pilot validation. Hyperscale operators in the United States and China are qualifying 30+ terabyte HAMR drives for cold storage tiers where access latency tolerances accommodate write-time thermal overhead. The technology is expanding into archival applications previously served by tape libraries, compressing the total cost of ownership gap between rotating and linear media.
REACH and RoHS amendments in European markets are tightening restrictions on hexavalent chromium in head-stack plating and perfluorinated compounds in lubricant formulations. ECHA substance evaluation timelines are forcing suppliers to submit alternative chemistries for authorization before legacy stocks deplete. Drive manufacturers serving European data center operators are accelerating supplier audits to certify compliant material flows ahead of sunset dates.
Cloud procurement teams are consolidating storage purchasing through direct OEM negotiations rather than distributor channels, compressing margin structures for traditional value-added resellers. Amazon Web Services, Microsoft Azure, and Google Cloud Platform now specify firmware customization, failure analysis protocols, and field replacement logistics in master service agreements. This concentration is most visible in the United States, where three hyperscalers account for the majority of high-capacity drive volume, forcing manufacturers to dedicate engineering resources to single-customer qualification tracks.
Global Hard Disk Drive (HDD) Market Segmentation

HDD segmentation reveals stark divergence between commodity consumer devices and mission-critical enterprise systems. Technology roadmaps, procurement patterns, and margin structures vary dramatically across these boundaries, requiring manufacturers to maintain parallel production architectures.
Product Type:
Standalone storage appliances dominate volume in consumer and small-business deployments, while embedded drives integrate into server backplanes and surveillance appliances with minimal end-user visibility.
- Enterprise:Nearline drives rated for 24/7 operation in hyperscale data centers feature vibration compensation and dual-stage actuators. Cloud operators in the United States and Japan specify these for multi-petabyte object storage tiers where failure tolerance demands dominate cost optimization.
- Surveillance:Write-optimized firmware supports continuous video stream ingestion with workload ratings exceeding standard desktop units by 3x. Chinese smart city deployments and Indian commercial security infrastructure are pulling specialized 8TB+ units with AllFrame technology.
- Desktop:3.5-inch form factor with 5400-7200 RPM spindle speeds serves budget-constrained personal computing and workstation builds. Replacement cycles stretch as SSD penetration deepens in primary storage roles.
- Laptop:2.5-inch and slim 7mm variants face structural displacement from NAND flash in mobile form factors. Remaining demand concentrates in bulk storage roles for gaming laptops and budget portable systems.
- External:USB-connected enclosures target backup and transport use cases with plug-and-play simplicity. Small business users and creative professionals sustain replacement-driven demand for 4TB-18TB portable units.
Enterprise leads volumes today; surveillance is gaining share fastest.
Technology:
Recording physics determines cost-per-gigabyte trajectories and manufacturing capital intensity, with energy-assisted methods requiring entirely different head-stack and media formulations than conventional approaches.
- Heat Assisted Magnetic Recording:Laser-diode integration heats media grains during write operations, enabling areal density beyond 2.5 Tbit/sq.inch. Seagate and Western Digital are qualifying 30+ terabyte drives for cold storage tiers at hyperscale facilities.
- Perpendicular Magnetic Recording:Dominant legacy technology with mature tooling and qualified supply chains. Remains cost-competitive for sub-16TB capacities where areal density limits have not yet constrained platter economics.
- Shingled Magnetic Recording:Overlapping write tracks boost capacity 25% over conventional recording at cost of rewrite penalties. Archival and cold storage applications tolerate the performance tradeoff for density gains.
- Microwave Assisted Magnetic Recording:Spin-torque oscillators reduce coercivity requirements without thermal overhead. Toshiba and Western Digital development programs target intermediate density gains before full HAMR transition.
Perpendicular Magnetic Recording anchors current production; Heat Assisted Magnetic Recording shows the steepest expansion trajectory.
Application:
Workload characteristics dictate interface selection, firmware optimization, and failure-domain architecture across deployment environments.
- Data Centers:Hyperscale and colocation facilities consume nearline drives in pooled storage architectures. United States-based cloud operators specify customized firmware and direct field replacement logistics in master service agreements.
- Personal Computing:Primary storage roles for boot volumes have largely transitioned to SSD, relegating HDD to bulk media and game libraries. Enthusiast builds sustain demand for high-capacity 3.5-inch units.
- Network Attached Storage:Small business and prosumer deployments favor multi-bay appliances with RAID redundancy. Replacement cycles run 4-5 years as storage pools expand incrementally.
- Videography:4K and 8K production workflows demand sustained sequential write bandwidth for raw footage ingestion. Post-production houses in Japan and Germany specify enterprise-grade drives for direct-attached storage arrays.
- Scientific Research:Climate modeling, genomics, and particle physics generate petabyte-scale datasets with infrequent access patterns. Tape-disk hybrid tiers optimize total cost of ownership for grant-funded institutions.
Data Centers command the largest share; Network Attached Storage is expanding most quickly among non-enterprise segments.
End User:
Procurement sophistication spans from centralized technical specifications to decentralized retail purchasing, fragmenting go-to-market requirements.
- Cloud Service Companies:Amazon Web Services, Microsoft Azure, and Google Cloud Platform consolidate purchasing power through direct OEM negotiations. These buyers embed power consumption metrics and failure analysis protocols in procurement scorecards.
- IT Service Providers:Managed service providers and systems integrators aggregate demand across mid-market clients. Margin pressure from hyperscale competition forces efficiency-focused storage architectures.
- Banking Institutions:Regulatory data retention mandates in Europe and North America drive compliant archive infrastructure. Transaction logging and audit trail storage sustain predictable replacement cycles.
- Media Houses:Broadcast and streaming content libraries require high-capacity nearline storage for active archives. Japanese and South Korean entertainment conglomerates lead deployment scale.
- Educational Institutions:Research universities and K-12 districts balance constrained budgets against growing digital asset collections. Grant-funded storage expansions favor cost-optimized configurations.
Cloud Service Companies dominate procurement volume; Banking Institutions show the most consistent replacement-driven demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes enterprise-grade nearline drives at volumes exceeding Japan, yet hyperscale procurement specifications in the United States set performance benchmarks that Asian manufacturers must match. Regulatory fragmentation across these three markets is reshaping supply chain qualification requirements.
United States
Hyperscale data center construction in Northern Virginia, Dallas-Fort Worth, and Phoenix is pulling multi-petabyte drive deployments into 2024-2025 procurement cycles. EPA hazardous substance restrictions in manufacturing processes force suppliers to certify alternative plating chemistries. Seagate and Western Digital operate qualification laboratories in Silicon Valley where cloud operators test customized firmware configurations.
China
Domestic cloud infrastructure expansion under MIIT digital economy directives sustains demand for surveillance-optimized drives in smart city deployments. SAMR antitrust scrutiny of storage component pricing is altering procurement negotiation frameworks. Manufacturing clusters in Suzhou and Shenzhen assemble head-stack components with rare earth magnets processed in Jiangxi facilities.
Japan
METI energy efficiency standards for data center equipment are embedding power consumption metrics into enterprise storage procurement scorecards. Tokyo and Osaka hyperscale facilities prioritize drives with vibration tolerance specifications for dense rack configurations. Toshiba maintains development operations in Kawasaki where microwave-assisted recording technologies undergo pre-production validation.
Germany
EU AI Act data localization mandates are forcing Frankfurt and Munich facility operators to expand localized storage hardware procurement. ECHA REACH restrictions on hexavalent chromium in plating operations extend qualification timelines for head-stack assemblies. Industrial automation clusters in Baden-Württemberg integrate nearline drives into manufacturing execution system archives.
India
PLI scheme incentives for data center infrastructure are creating fresh demand for nearline storage deployments in Mumbai and Hyderabad. BIS certification requirements for electronic storage devices are tightening import documentation protocols. Chennai assembly facilities are qualifying as regional hubs for enterprise drive distribution across South Asian markets.
Global Hard Disk Drive (HDD) Market Competitive Landscape
Top-tier vendors anchor hyperscale cloud procurement, while mid-tier specialists serve surveillance and network-attached storage segments with firmware-customized offerings. The market consolidates around three vertically integrated manufacturers controlling spindle motor and platter supply chains. Strategic archetypes include scale-driven OEMs, component-integrated fabricators, and firmware-specialized niche operators. Competitive moves concentrate on direct cloud procurement negotiations and energy-assisted recording technology licensing arrangements.
Among vertically integrated manufacturers, Seagate Technology Holdings PLC, Western Digital Corporation, and Toshiba Corporation occupy positions that exemplify the tier-one archetype. Seagate represents the vertically integrated model with captive control over head-stack and media production. Western Digital sits within the technology-licensing vector through its energy-assisted recording development programs. Toshiba anchors the diversified conglomerate structure where storage operations draw on broader materials science capabilities. These three entities structure competitive dynamics through direct qualification tracks with hyperscale operators rather than distributor-channel relationships.
| Leading Market Players |
|---|
| Sony Corporation |
| Transcend Information Inc. |
| Seagate Technology Holdings PLC |
| Lenovo Group Limited |
| ADATA Technology Co. Ltd |
| Western Digital Corporation |
| Hewlett Packard Enterprise Development LP |
| QNAP Systems, Inc. |
| Toshiba Corporation |
| Others |
Supply & Pricing Matrix
Hyperscale cloud operators in the United States, China, and Japan concentrate procurement power through direct OEM negotiations, compressing margin structures and forcing manufacturers toward contract-based long-term offtake pricing with embedded volume commitments. This buyer concentration reshapes how Seagate, Western Digital, and Toshiba structure tiered pricing across enterprise nearline, surveillance-optimized, and legacy desktop segments.
Pricing Analysis
Capacity additions in Chinese and Thai assembly facilities are reshaping price floors for perpendicular magnetic recording drives while HAMR qualification timelines sustain premium positioning. Three-tier pricing structure across premium enterprise nearline, standard surveillance, and economy desktop levels reflects certification grade and volume scale differentiation. Pricing pressure stems from NAND flash substitution in consumer tiers, compressing addressable volume for rotating media below 4TB capacities. Small business NAS buyers exhibit highest price sensitivity, while hyperscale operators prioritize total cost of ownership metrics over unit acquisition cost.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping regional sourcing patterns for data center-bound drives, forcing qualification of Chennai assembly hubs. Spindle motor production draws from Chinese rare earth processing in Jiangxi, Malaysian precision machining clusters, and Thai head-stack assembly operations. Neodymium magnet sourcing creates single-point vulnerability concentrated in Chinese refining facilities. Distribution runs through direct OEM channels to hyperscale operators, bypassing traditional value-added reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's data localization mandates compound storage demand across European markets, creating regulatory-driven infrastructure buildouts that sustain enterprise HDD procurement independent of cyclical IT spending patterns.
For Market Incumbents: To counter NAND flash encroachment in performance-tier segments, Seagate and Western Digital should deepen captive control over HAMR head-stack production while accelerating direct qualification tracks with AWS, Azure, and Google Cloud Platform. Certification investment in REACH-compliant plating chemistries secures European data center access against sunset deadlines. For New Entrants and Emerging Players: Regional cloud providers in India and Southeast Asia represent underserved buyer archetypes with less stringent firmware customization requirements than tier-one hyperscalers. Surveillance-optimized drives for smart city deployments in India and China offer penetrable entry points. Go-to-market positioning should emphasize localized field replacement logistics and PLI scheme compliance documentation. For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, seeking to verticalize storage hardware procurement through captive supply arrangements. Long-term viability hinges on energy-assisted recording technology transitions over the next decade. Acquisition targets with qualified HAMR media production capabilities or microwave-assisted recording IP portfolios warrant closest attention. The signal to watch is hyperscale qualification volume for 30+ terabyte drives.| Strategic Initiative | Industry Significance |
|---|---|
| HAMR Technology Licensing | Western Digital and Toshiba IP agreements accelerate areal density roadmaps for cold storage tiers. |
| Backward Integration into Rare Earth Processing | Seagate's captive magnet sourcing reduces exposure to Chinese neodymium concentration risks. |
| Subscription Firmware Licensing | Feature-unlocking models decouple hardware refresh from capability upgrades at hyperscale facilities. |
| REACH-Compliant Material Transition | ECHA authorization timelines force reformulation of head-stack plating for European market access. |
| Direct OEM Procurement Consolidation | AWS, Azure, and Google Cloud master service agreements compress distributor margins industry-wide. |
Research Methodology
Bottom-up hyperscale capex modeling reconciled against top-down platter and head-stack production tracking forms the analytical core of this study. Primary interviews with cloud procurement officers, data center construction managers, HDD firmware engineers, and rare earth magnet suppliers combined with secondary validation against SEC 10-K filings, hyperscaler infrastructure disclosure reports, ECHA substance authorization databases, and MIIT digital economy directives. Triangulation across these sources anchors volume estimates for enterprise nearline, surveillance, and consumer segments.
Input-output matrices map areal density roadmaps, spindle motor production capacity, and hyperscale facility construction pipelines across the projection horizon. Segmentation dimensions include recording technology tier, interface protocol, workload rating, and regional regulatory cluster. CAGRs derive from fitted adoption curves for HAMR penetration and NAND flash substitution elasticities. Forecast inputs incorporate EIA data center energy consumption trajectories and EU AI Act implementation timelines.
Underlying measurement precision varies by segment; hyperscale procurement volumes carry tighter precision than distributed NAS replacement cycles due to disclosure practices. Forecasts reflect documented assumptions regarding HAMR yield ramp schedules and rare earth supply continuity. Supply chain disruptions, regulatory acceleration, or solid-state cost breakthroughs could revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Transparent Cache Market
Data Storage
NOR Flash Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
Germany Data Center Storage Market
Data Storage
Powered Storage Devices Market
Data Storage
North America Next Generation Storage Market
Data Storage
All Flash Storage Market
Data Storage
Data Storage Market
Data Storage
Data Storage Devices Market
Data Storage
Portable Storage Device Control Software Market
Data Storage
Blu-Ray Drive Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Zoned Flash Market