
 Digital Crosspoint Switches Market | 2026-2036
Digital Crosspoint Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Crosspoint Switches Market Outlook
Multi-source procurement for high-performance crosspoint silicon is pivoting toward qualified second-source arrangements as lead times for advanced node wafers remain extended. Analog Devices leverages its mixed-signal heritage to sustain design-win momentum in broadcast infrastructure. Texas Instruments anchors its position through deep integration of precision timing circuits with crosspoint cores. Broadcom competes at the data center edge with merchant switch silicon that absorbs traditional crosspoint functions into larger system-on-chip architectures.
A digital crosspoint switch is a semiconductor device that routes any input signal to any output port under electronic control, typically supporting matrix configurations from 8x8 to beyond 1024x1024 ports with bandwidths exceeding 12 Gbps per lane. Its primary commercial purpose is to enable flexible, non-blocking signal distribution across video production routers, telecom backplanes, and radar signal-processing chains. Data switchers lead product-type revenue as hyperscale cloud operators deploy massive spine-leaf fabrics requiring programmable interconnect. Hybrid switchers represent the fastest-expanding category, merging audio, video, and control-plane routing in unified broadcast production environments. Rack-mounted installations dominate physical deployment, though embedded crosspoint IP is displacing discrete chips in space-constrained military avionics systems.
FCC equipment authorization rules shape signal-integrity requirements for crosspoint devices deployed in US telecom infrastructure, while EU RoHS and REACH restrictions constrain material choices for European-bound shipments. China's GB standards and MIIT certification gates market access for imported switching components, compelling foreign suppliers to maintain dual-qualified product lines. Stakeholders must monitor how export-control expansions affecting advanced semiconductor manufacturing equipment reshape supply security for crosspoint switch vendors serving defense and aerospace end users.
Market Dynamics
The migration from 400G to 800G Ethernet standards is compressing refresh cycles and forcing infrastructure operators to requalify switching fabrics faster than historical norms, creating a structural pull for higher-density crosspoint matrices.
Growth Catalysts
- Hyperscale data center buildouts:Cloud operators in the United States are deploying spine-leaf architectures requiring programmable 1024x1024 port matrices to manage video traffic aggregation.
- REACH material compliance:European-bound shipments must satisfy RoHS substance restrictions and ECHA registration requirements, accelerating qualification of lead-free solder bump processes for crosspoint packaging.
- Domestic foundry scaling:China's MIIT certification regime and GB standards for broadcast equipment are driving captive production of custom crosspoint devices for military radar signal chains.
Market Restraints
- Advanced node wafer scarcity:Lead times for 7nm and 5nm silicon remain extended, constraining volume shipments of high-bandwidth crosspoint switches to telecom infrastructure providers.
- Merchant SoC absorption:Broadcom and Marvell are integrating crosspoint functionality into larger switch silicon, threatening discrete device volumes at the data center edge.
- FCC authorization complexity:Signal-integrity testing for US telecom deployment adds 6-9 months to product qualification timelines, delaying revenue recognition for new matrix designs.
Strategic Opportunities
- Embedded avionics integration:Space-constrained military platforms in the United States are displacing discrete chips with hardened crosspoint IP cores, opening captive semiconductor service contracts.
- Hybrid broadcast unification:Audio-video-control plane convergence in European production environments creates demand for unified routing fabrics that legacy single-function switches cannot satisfy.
- India PLI scheme leverage:Telecom infrastructure incentives under India's production-linked initiative are attracting crosspoint assembly and test investments for export to Southeast Asian markets.
Industry Challenges
- Signal-integrity engineering scarcity:The pool of engineers capable of 12 Gbps+ lane design is concentrated among legacy broadcast semiconductor firms, inflating compensation and extending development timelines.
- Dual-qualified product maintenance:Vendors must sustain parallel production lines to satisfy China's GB standards alongside FCC and CE marking requirements, fragmenting engineering resources and inventory pools.
- Legacy radar interface compatibility:Military retrofit programs demand backward compatibility with obsolete parallel bus architectures, forcing costly die area allocation to deprecated I/O standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Crosspoint Switches Market |
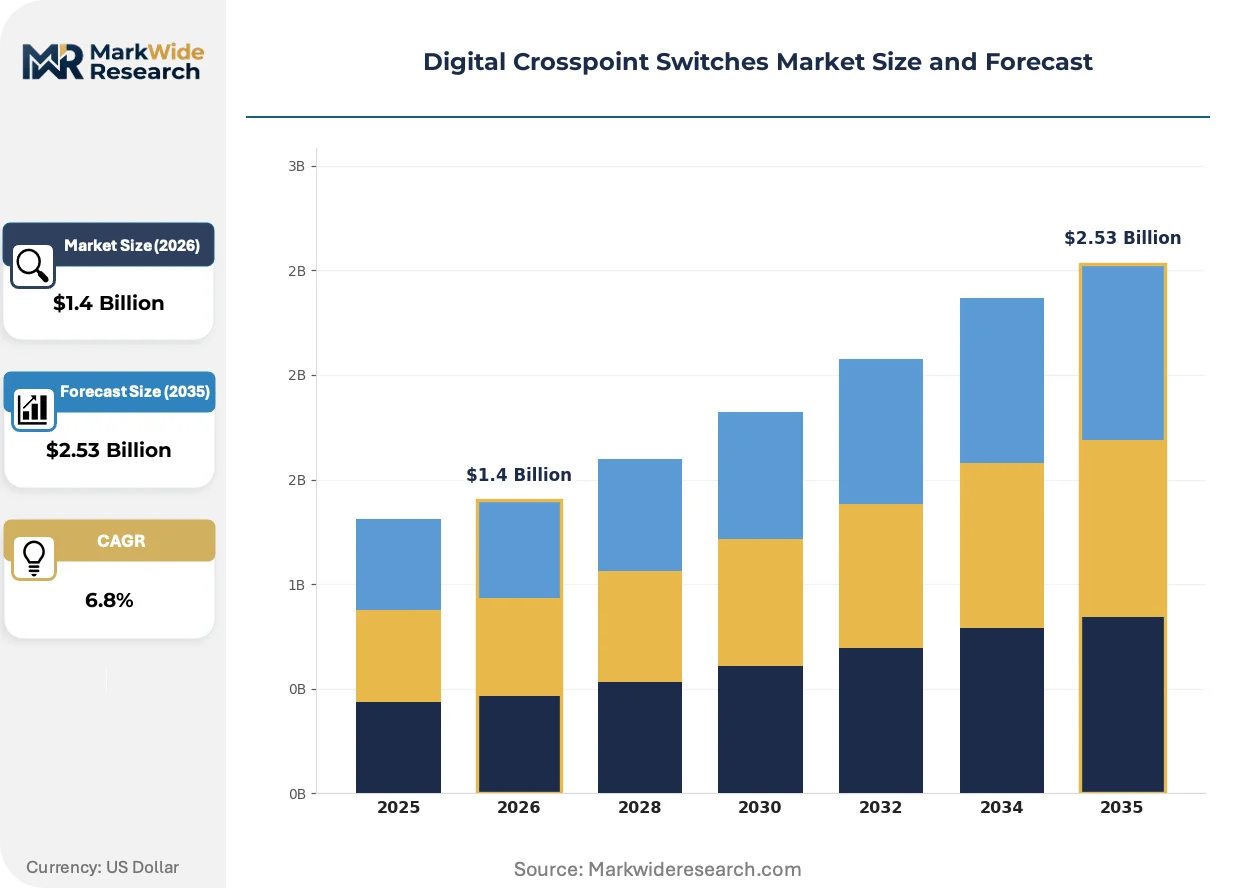
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Video Switchers, Audio Switchers, Data Switchers, Hybrid Switchers Application: Broadcasting, Telecommunication, Military, Healthcare End User: Media Companies, Corporations, Government Agencies, Educational Institutions Installation: Rack-Mounted, Wall-Mounted, Portable, Embedded |
| Companies Covered | Analog Devices, Texas Instruments, Broadcom, NXP Semiconductors, ON Semiconductor, Microchip Technology, STMicroelectronics, Lattice Semiconductor, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Crosspoint Switches Market Strategic Shifts
Silicon photonics co-packaging and software-defined routing fabrics are converging to redefine how signal distribution scales in bandwidth-intensive environments. These developments are compressing the boundary between physical layer switching and higher-layer network intelligence.
Silicon photonic crosspoint substrates are integrating optical I/O directly alongside electrical switching matrices to eliminate retimer stages in 800G backplanes. Hyperscale operators in the United States are piloting these devices in AI training clusters where copper trace losses become prohibitive beyond 50 centimeters. This integration is collapsing the traditional separation between optical transceivers and electrical switch fabrics, forcing legacy discrete vendors to develop photonic packaging competencies or cede the high-bandwidth edge.
EU F-Gas Regulation phase-down schedules are restricting fluorinated greenhouse gas use in semiconductor etching processes, compelling foundries serving European-bound crosspoint shipments to qualify alternative chemistries for via formation. The industrial consequence is yield volatility during process transition periods at 28nm and 16nm nodes. Broadcast infrastructure suppliers with European certification requirements are responding by pre-qualifying dual-source wafer supply from foundries with completed F-Gas transition audits.
Hyperscale procurement teams are consolidating vendor panels from twelve to four qualified sources for 400G+ crosspoint silicon, replacing fragmented multi-source arrangements with strategic volume commitments. This concentration is displacing traditional distribution channel markups as buyers negotiate direct foundry allocation contracts. The shift is most visible in United States data center deployments, where cloud operators now specify die-level traceability and wafer-start visibility as contractual conditions rather than optional audit rights.
Digital Crosspoint Switches Market Segmentation
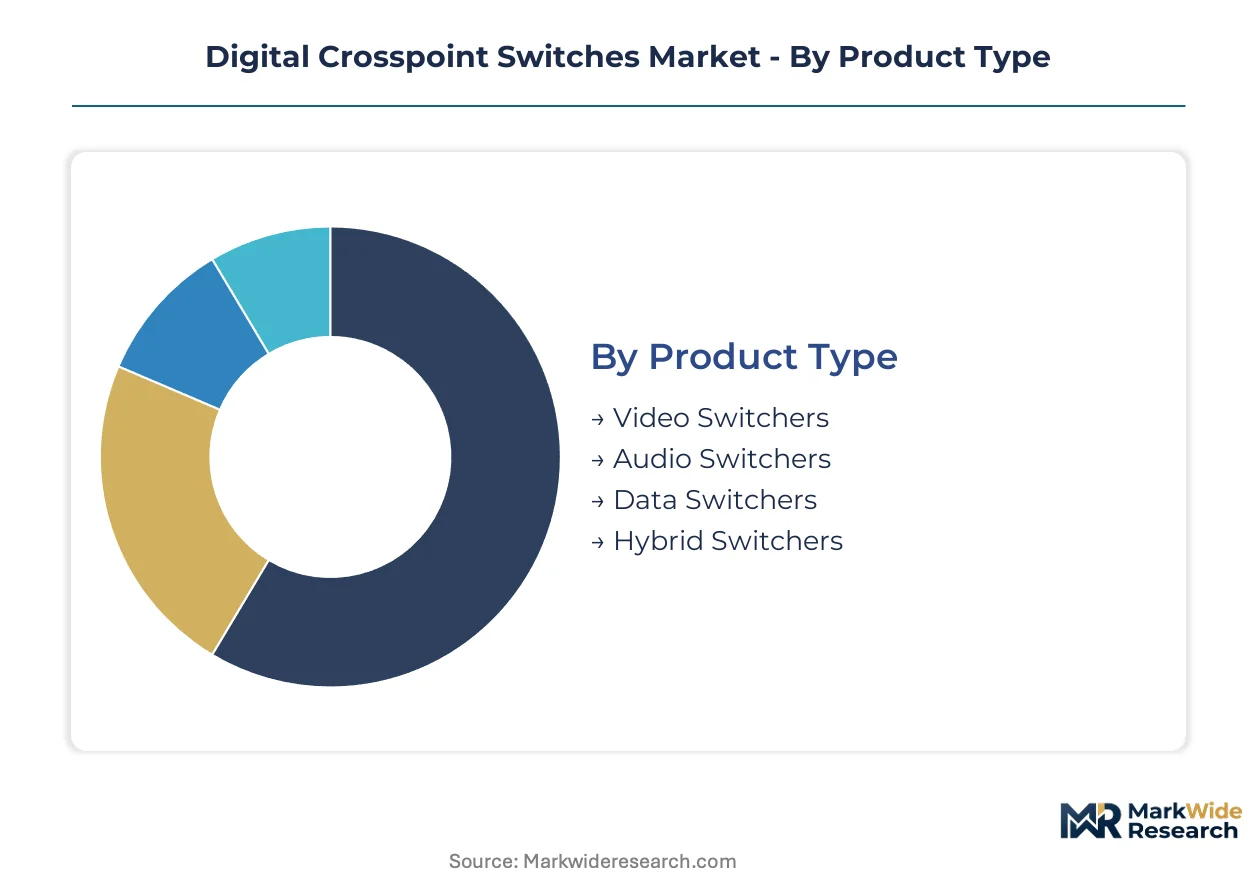
Crosspoint switch segmentation reveals how signal routing requirements diverge across bandwidth, physical form factor, and regulatory environment. Each dimension shapes procurement criteria, qualification timelines, and vendor selection priorities for infrastructure operators.
Product Type:
Standardized commodity silicon dominates high-volume data center procurement, while broadcast and military applications demand customized matrix configurations with extended temperature ranges and deterministic latency.
- Data Switchers:These devices handle digital data streams with port densities exceeding 1024x1024 configurations and per-lane bandwidth above 12 Gbps. Hyperscale cloud operators in the United States specify these for spine-leaf architectures aggregating video traffic from millions of concurrent sessions. Demand concentrates where 400G and 800G Ethernet refresh cycles compress requalification windows.
- Hybrid Switchers:Unified routing fabrics merge audio, video, and control-plane signals within single matrix devices. European broadcast production environments drive adoption as facilities consolidate legacy single-function routers to reduce rack space and power draw. These systems require precise clock domain crossing to prevent lip-sync errors across asynchronous signal paths.
- Video Switchers:Purpose-built for SDI and SMPTE ST 2110 uncompressed video routing with sub-microsecond switching latency.
- Audio Switchers:Optimized for AES67 and Dante networked audio protocols with sample-accurate synchronization across distributed installations.
Leading the category by volume: Data Switchers. Growing fastest: Hybrid Switchers.
Application:
Defense procurement cycles extend five to seven years with frozen specifications, while telecom infrastructure refresh accelerates as Ethernet standards leapfrog.
- Telecommunication:Backbone and edge infrastructure deployments require crosspoint matrices supporting non-blocking any-to-any connectivity for traffic engineering. China's domestic foundries scale production of custom devices for 5G fronthaul aggregation, driven by MIIT certification requirements that gate market access for imported components. FCC equipment authorization rules add six to nine months to US deployment timelines.
- Military:Radar signal-processing chains and electronic warfare systems demand radiation-hardened crosspoint devices with military-grade temperature specifications. Retrofit programs force backward compatibility with obsolete parallel bus architectures, consuming die area for deprecated I/O standards. Export control expansions on advanced semiconductor manufacturing equipment reshape supply security planning.
- Broadcasting:Live production routers and master control switching with frame-accurate switching for on-air reliability.
- Healthcare:Surgical video routing and medical imaging distribution requiring galvanic isolation and EMC compliance.
Dominant by deployment value: Telecommunication. Steepest expansion trajectory: Military.
End User:
Procurement sophistication varies sharply—media companies negotiate direct foundry allocation contracts while educational institutions rely on distribution channels with extended lead times.
- Media Companies:Broadcast networks and streaming platforms operate 24/7 production facilities requiring five-nines availability from switching infrastructure. These buyers consolidate vendor panels from twelve to four qualified sources, replacing fragmented multi-source arrangements with strategic volume commitments that displace traditional distribution markups.
- Government Agencies:Defense departments and civilian authorities specify die-level traceability and wafer-start visibility as contractual conditions. Dual-qualified product lines satisfy domestic content requirements while maintaining interoperability with allied systems.
- Corporations:Enterprise AV installations and corporate broadcast studios with moderate port density requirements.
- Educational Institutions:University media production programs and campus AV infrastructure with budget-constrained procurement.
Highest volume concentration: Media Companies. Fastest procurement modernization: Government Agencies.
Installation:
Physical deployment constraints determine thermal management, service accessibility, and electromagnetic compatibility requirements.
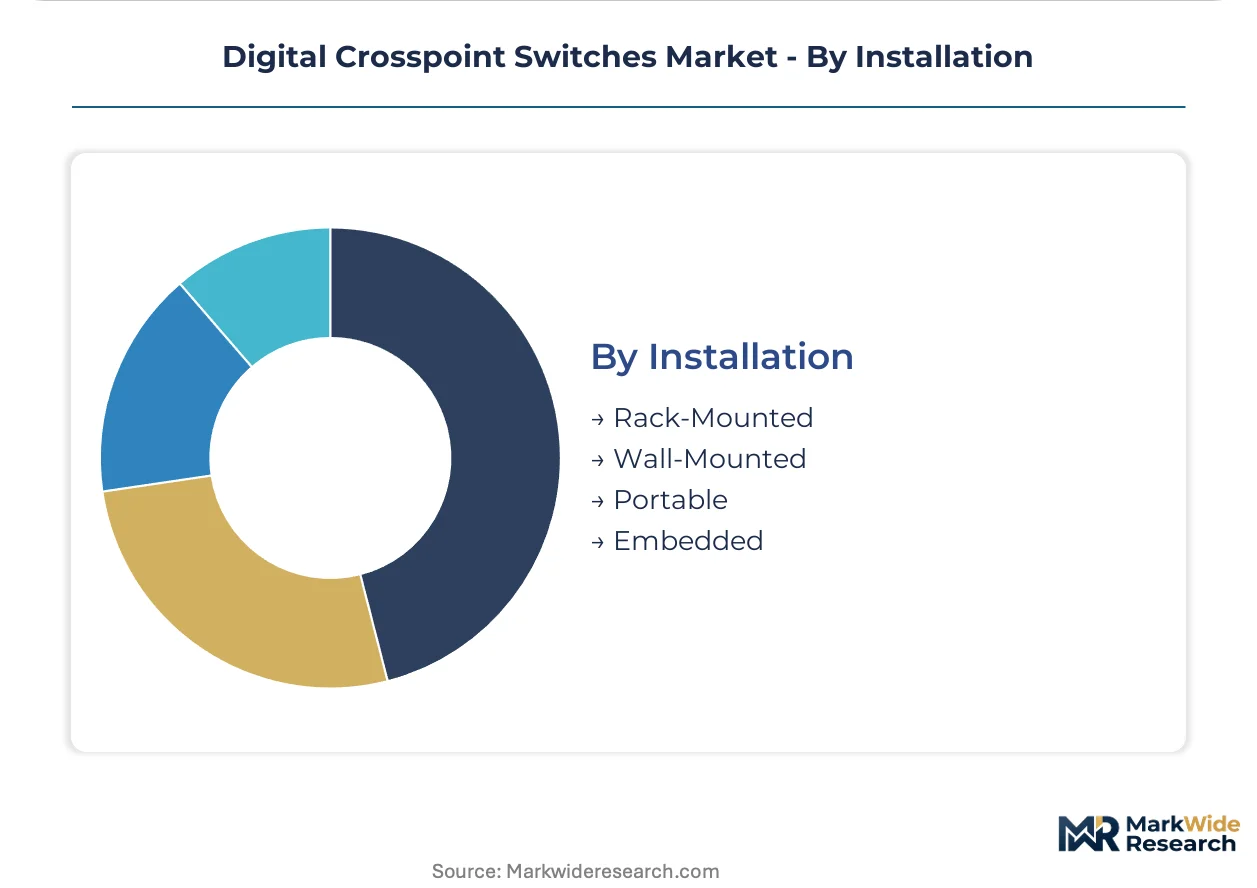
- Rack-Mounted:Standard 19-inch and 23-inch rack configurations dominate broadcast facility and data center deployments with hot-swappable redundancy. These installations support the highest port densities and power budgets, enabling active cooling for 800G-class switching fabrics.
- Embedded:Space-constrained military avionics systems displace discrete chips with hardened crosspoint IP cores. United States defense platforms drive captive semiconductor service contracts for radiation-tolerant designs with deterministic latency guarantees.
- Wall-Mounted:Compact enclosures for distributed AV installations with limited rack infrastructure.
- Portable:Field production and temporary event deployments with battery power and rapid setup requirements.
Maximum deployment base: Rack-Mounted. Fastest technology transition: Embedded.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication capacity in Taiwan and South Korea anchors the upstream supply base for high-bandwidth crosspoint devices, while downstream demand clusters in data center hubs across the United States, China, and Germany.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth deploy 1024x1024 port matrices for spine-leaf video aggregation. FCC equipment authorization rules add six to nine months to signal-integrity qualification timelines. Defense procurement in Southern California drives captive semiconductor service contracts for radiation-hardened crosspoint IP in space-constrained avionics.
China
Domestic foundries in Shanghai and Shenzhen scale production of custom crosspoint devices for 5G fronthaul and military radar signal chains. MIIT certification gates market access for imported switching components, compelling foreign suppliers to maintain dual-qualified product lines. Yangtze River Delta broadcast equipment manufacturers absorb growing volumes of locally-sourced silicon.
Germany
Industrial automation and broadcast infrastructure in Bavaria and North Rhine-Westphalia demand hybrid switchers merging audio, video, and control-plane routing. EU F-Gas Regulation phase-down schedules restrict fluorinated greenhouse gas use in semiconductor etching, forcing yield volatility during process transitions at 28nm nodes. Munich-based systems integrators pre-qualify dual-source wafer supply from F-Gas-compliant foundries.
Japan
Precision timing integration with crosspoint cores serves telecom infrastructure refresh cycles in Tokyo and Osaka metro corridors. METI industrial policy supports domestic semiconductor packaging capabilities for 800G-class switching fabrics. Nagoya-area automotive electronics suppliers evaluate crosspoint matrices for next-generation vehicle networking architectures.
South Korea
Memory and logic foundry clusters in Seoul Capital Area and Busan-Ulsan supply advanced node wafers for high-density crosspoint matrices. MFDS regulatory frameworks do not directly govern crosspoint devices, but export control alignments with allied semiconductor equipment restrictions reshape supply security planning. Pangyo technopole hosts design centers specializing in 12 Gbps+ lane signal-integrity engineering.
Digital Crosspoint Switches Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors secure foundry allocation and co-packaging capabilities for silicon photonic integration. The vendor base concentrates among three tiers: diversified analog-mixed-signal conglomerates, merchant switch silicon specialists, and programmable logic device architects. Two competitive vectors define positioning: backward integration into captive wafer supply, and forward integration into optical-electrical co-packaging for 800G backplanes.
Within the diversified analog-mixed-signal tier, Analog Devices and Texas Instruments exemplify heritage positioning through precision timing circuit integration with crosspoint cores. Broadcom occupies the merchant switch silicon vector where larger system-on-chip architectures absorb traditional discrete crosspoint functions. Lattice Semiconductor represents the programmable logic archetype, with field-programmable gate arrays enabling flexible matrix configurations for broadcast and military retrofit programs. These three anchors illustrate how competitive positioning fragments across integration depth rather than converging on uniform architectures.
| Leading Market Players |
|---|
| Analog Devices |
| Texas Instruments |
| Broadcom |
| NXP Semiconductors |
| ON Semiconductor |
| Microchip Technology |
| STMicroelectronics |
| Lattice Semiconductor |
| Infineon Technologies |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot price indices at the 300mm diameter tier cascade through foundry quotations into three distinct procurement tiers for crosspoint switch buyers. Hyperscale cloud operators with direct foundry allocation contracts capture volume discounts unavailable to broadcast infrastructure purchasers reliant on distribution channels.
Pricing Analysis
Extended warranty and signal-integrity engineering support bundles separate premium-tier procurement from unbundled economy transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and wafer-start visibility. Pricing pressure stems from merchant SoC absorption at the data center edge. Broadcast infrastructure buyers exhibit highest price sensitivity due to fragmented procurement scale.
Supply Chain Analysis
Dual-sourcing qualification mandates from United States defense procurement officers fragment engineering resources across parallel product lines. Foundry capacity concentrates in Taiwan, South Korea, and the United States. Raw material dependencies include 300mm silicon wafers, advanced photoresists, and high-purity etching gases. Single-source vulnerability persists at the 7nm and 5nm node tiers. Distribution runs through authorized semiconductor distributors to systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Advanced node wafer scarcity props pricing power for qualified vendors, constraining volume expansion regardless of downstream demand pull.
For Market Incumbents: Deploy precision timing integration as a defensive lever against merchant SoC absorption. Broadcom and Marvell threaten discrete crosspoint volumes through switch silicon integration. Analog Devices and Texas Instruments should deepen captive foundry allocation contracts in Taiwan and South Korea. Certification investment in FCC and MIIT dual-qualification maintains defense sector access. For New Entrants and Emerging Players: Regional broadcast networks in Central and Eastern Europe represent underserved buyer archetypes with unconsolidated vendor panels. Hybrid switcher unification creates white-space opportunity in audio-video-control convergence. India's PLI scheme attracts assembly investment for Southeast Asian export. Direct foundry contracting bypasses traditional distribution markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor analog-mixed-signal specialists with MIIT-certified product lines in China. Five-to-ten year viability hinges on silicon photonic co-packaging competence. Watch for hyperscale procurement consolidation from twelve to four qualified sources as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonic Co-Packaging Development | Optical-electrical integration eliminates retimer stages in 800G backplanes for AI training clusters. |
| Dual-Qualified Product Line Investment | Parallel FCC and MIIT certification maintains access to United States defense and China broadcast markets. |
| Direct Foundry Allocation Contracting | Wafer-start visibility secures volume supply for hyperscale cloud operator procurement panels. |
| Hybrid Switcher Platform Launch | Audio-video-control convergence addresses European broadcast facility consolidation requirements. |
| Radiation-Hardened IP Core Development | Embedded crosspoint designs displace discrete chips in United States military avionics platforms. |
Study Parameters
Multi-period observation of hyperscale capex disclosures, foundry utilization rates, and defense procurement awards anchored the trend analysis, supplemented by interviews with signal-integrity engineering directors, broadcast infrastructure procurement managers, semiconductor distribution channel heads, and MIIT certification consultants. Secondary validation drew from FCC equipment authorization databases, ECHA REACH registration filings, SEC 10-K semiconductor disclosures, and customs trade data for crosspoint switch classifications. Bottom-up segment sizing triangulated against top-down wafer demand models.
Segment-weighting across product type, application, end user, and installation dimensions shaped the analytical framework. CAGRs derived from regression analysis of historical volume trends against projected Ethernet standard refresh cycles. Industry-specific forecast inputs included 400G-to-800G transition timelines and silicon photonics pilot deployment schedules.
Revisions become necessary when export control expansions, foundry yield volatility, or hyperscale procurement consolidation materialize. Deviation in advanced node wafer allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
Low Voltage Switchgear Market
Switches
High-Voltage Disconnect Switch Market
Switches
Residual Current Circuit Breaker Market
Switches
Saudi Arabia Switchgear Market
Switches
Intelligent Power Switches Market
Switches
North America Low Voltage Switchgear Market
Switches
Molded Case Circuit Breaker Market
Switches
Asia-Pacific Low Voltage Switchgear Market
Switches
United States Circuit Breaker Market
Switches
Australia Switchgear Market
Switches
Asia Pacific Reed Sensors Switches Market
Switches
Pressure Switch Market
Switches
Level Switches Market
Switches
Electronic Shift-By-Wire Selector Modules Market
Switches
DC Switchgear Market
Switches
Transfer Switch Market