
 Middle East Data Center Storage Market | 2026-2036
Middle East Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Data Center Storage Market Insights
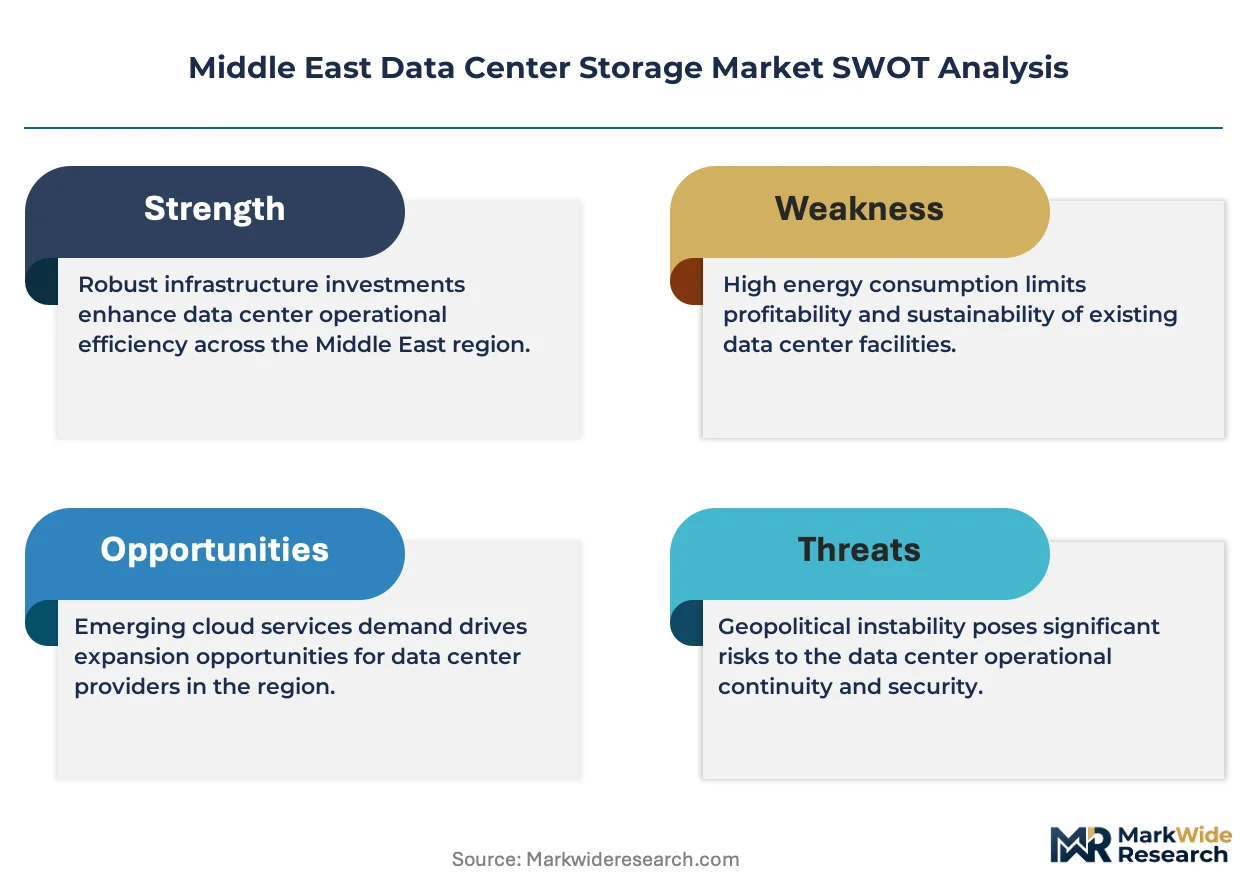
GDPR-equivalent data sovereignty frameworks across Gulf Cooperation Council member states is realigning the cost-of-entry calculus for international storage vendors seeking operating licenses. Dell Inc. leverages its established enterprise channel relationships to sustain hardware supply continuity across Emirati and Saudi government contracts. Huawei Technologies Co. Ltd. anchors its position through localized assembly partnerships that navigate procurement preferences for domestically manufactured equipment. Pure Storage differentiates via all-flash arrays optimized for low-latency AI training clusters now mandated by national artificial intelligence strategies.
Middle East data center storage encompasses electromechanical and solid-state systems engineered for persistent digital retention across enterprise and hyperscale facilities, with operational parameters spanning IOPS ratings from ten thousand to over one million per array and latency thresholds below one millisecond for flash-based tiers. These systems serve as the foundational substrate for transactional databases, real-time analytics, and machine learning pipelines that power regional digital economy agendas. Solid state drives and flash storage command premium positioning as Gulf operators prioritize performance density for generative AI workloads, while hybrid and colocation deployment models capture expanding share as enterprises balance capital constraints against sovereignty requirements. Software-defined storage architectures are gaining structural traction by decoupling hardware procurement from data management licensing, enabling multi-tenant revenue models that align with provider margin objectives.
Saudi Arabia's National Data Management Office, the UAE's Telecommunications and Digital Government Regulatory Authority, and Bahrain's National Bureau for Revenue collectively enforce data residency, encryption, and cross-border transfer protocols that dictate storage procurement specifications and facility location decisions. BIS-equivalent conformity assessment requirements in Qatar and Kuwait further segment vendor eligibility by certification status, filtering market access for uncertified equipment suppliers. Stakeholders must monitor evolving certification reciprocity agreements between Gulf regulators and whether emerging AI-specific storage performance benchmarks become embedded in government tender criteria.
Market Dynamics
Sovereign data localization mandates across Gulf Cooperation Council member states are forcing hyperscale operators to deploy petabyte-scale domestic storage infrastructure, fundamentally restructuring procurement patterns and facility location decisions for international vendors.
Growth Catalysts
- National Data Management Office mandates:Saudi Arabia's data residency requirements compel foreign cloud providers to establish domestic storage facilities, generating hardware procurement cycles.
- AI training cluster deployments:Generative AI workloads across Riyadh and Dubai are demanding all-flash arrays with sub-millisecond latency thresholds.
- Smart city data lakes:Government-backed urban digitization programs in the UAE require hybrid storage architectures for real-time analytics pipelines.
Market Restraints
- Flash memory supply concentration:NAND fabrication capacity concentrates in East Asian foundries, exposing Gulf operators to input cost volatility and logistics bottlenecks.
- BIS-equivalent certification complexity:Qatar and Kuwait enforce conformity assessment requirements that filter vendor eligibility by certification status, extending sales cycles.
- Power infrastructure constraints:Storage array density outpaces grid expansion in secondary Emirates and Saudi provinces, limiting facility scalability.
Strategic Opportunities
- Bahrain's emerging fintech licensing:The National Bureau for Revenue's data protection frameworks create demand for compliant colocation storage among payment processors.
- Edge-to-core convergence:5G rollout across Dubai and Jeddah enables distributed storage architectures that reduce backhaul costs for latency-sensitive applications.
- Software-defined revenue models:Subscription-based data management licensing aligns provider margins with multi-tenant operational expenditure preferences.
Industry Challenges
- Certified storage engineer scarcity:The talent pipeline for enterprise array administration lags deployment timelines across Saudi Arabia's NEOM and Red Sea projects.
- Legacy SAN integration friction:Government agencies maintaining decade-old Fibre Channel infrastructures face forklift upgrade costs when adopting NVMe-over-Fabrics.
- Cross-border data transfer compliance:Operators must architect redundant replication topologies that satisfy both UAE and Saudi encryption-at-rest protocols without violating either jurisdiction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Data Center Storage Market |
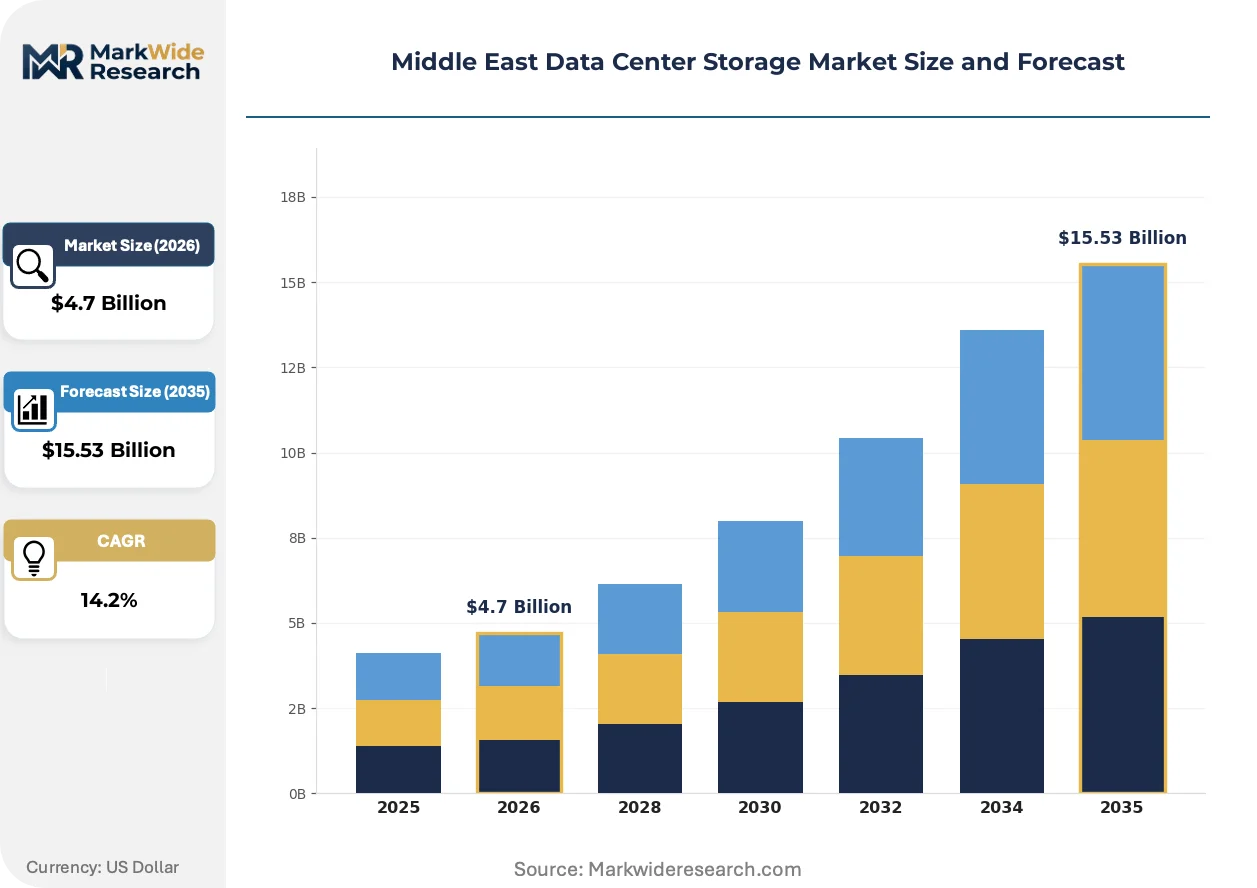
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $15.53 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Disk Drives, Solid State Drives, Tape Storage, Hybrid Storage Deployment Model: On-Premises, Cloud-Based, Hybrid, Colocation End User: Enterprise, Government, Cloud Service Providers, Telecommunications Technology: Flash Storage, Magnetic Storage, Software-Defined Storage, Object Storage |
| Companies Covered | Dell Inc., Hewlett Packard Enterprise, NetApp Inc., Huawei Technologies Co. Ltd., Kingston Technology Company Inc., Pure Storage, IBM, Hitachi Vantara, Dell EMC, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Data Center Storage Market Trends and Innovations
Computational storage architectures and sovereign cloud frameworks are compressing traditional hardware procurement cycles while elevating software-defined control planes as the primary vendor differentiator across Gulf data center deployments.
Computational storage drives with embedded processing capabilities are absorbing indexing and encryption workloads previously executed on host CPUs. Hyperscale operators in Dubai International Financial Centre and King Abdullah Financial District are deploying these devices to reduce data movement overhead. This compression of processing latency is absorbing budget allocations that previously flowed to separate compute expansion.
The UAE's Telecommunications and Digital Government Regulatory Authority has tightened data classification requirements for critical infrastructure operators, mandating air-gapped storage tiers for sovereign workloads. Industrial consequence includes mandatory dual-vendor procurement policies that prevent single-source dependencies. Financial services and healthcare verticals are responding by segmenting workloads across geographically separated availability zones.
Consumption-based capacity contracts are displacing traditional capital-intensive storage procurement among mid-market enterprises. Managed service providers in Abu Dhabi and Dammam are offering guaranteed IOPS tiers with automatic tiering between flash and object storage. This behavioral shift is most visible in fintech licensing applicants seeking to preserve balance sheet capacity while satisfying regulatory data retention periods.
Middle East Data Center Storage Market Segmentation
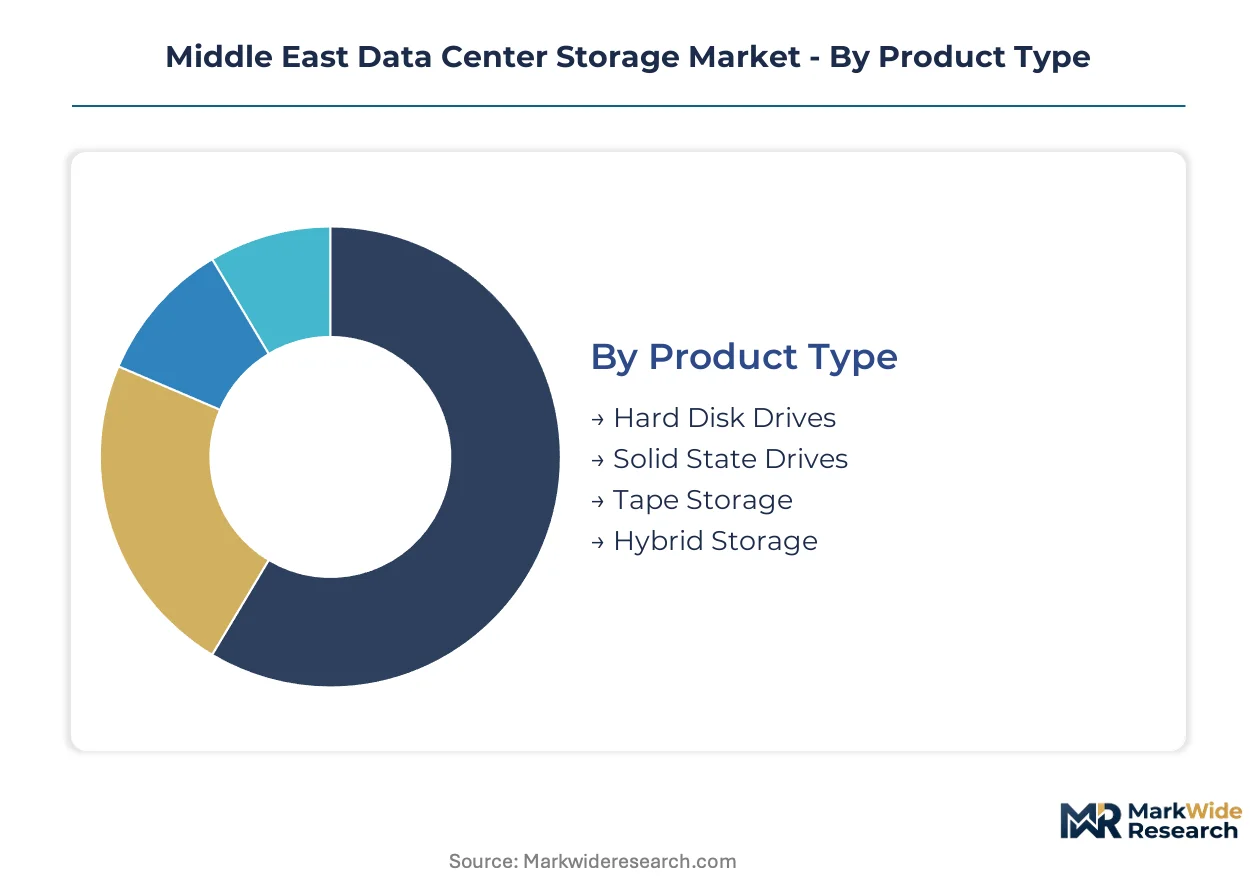
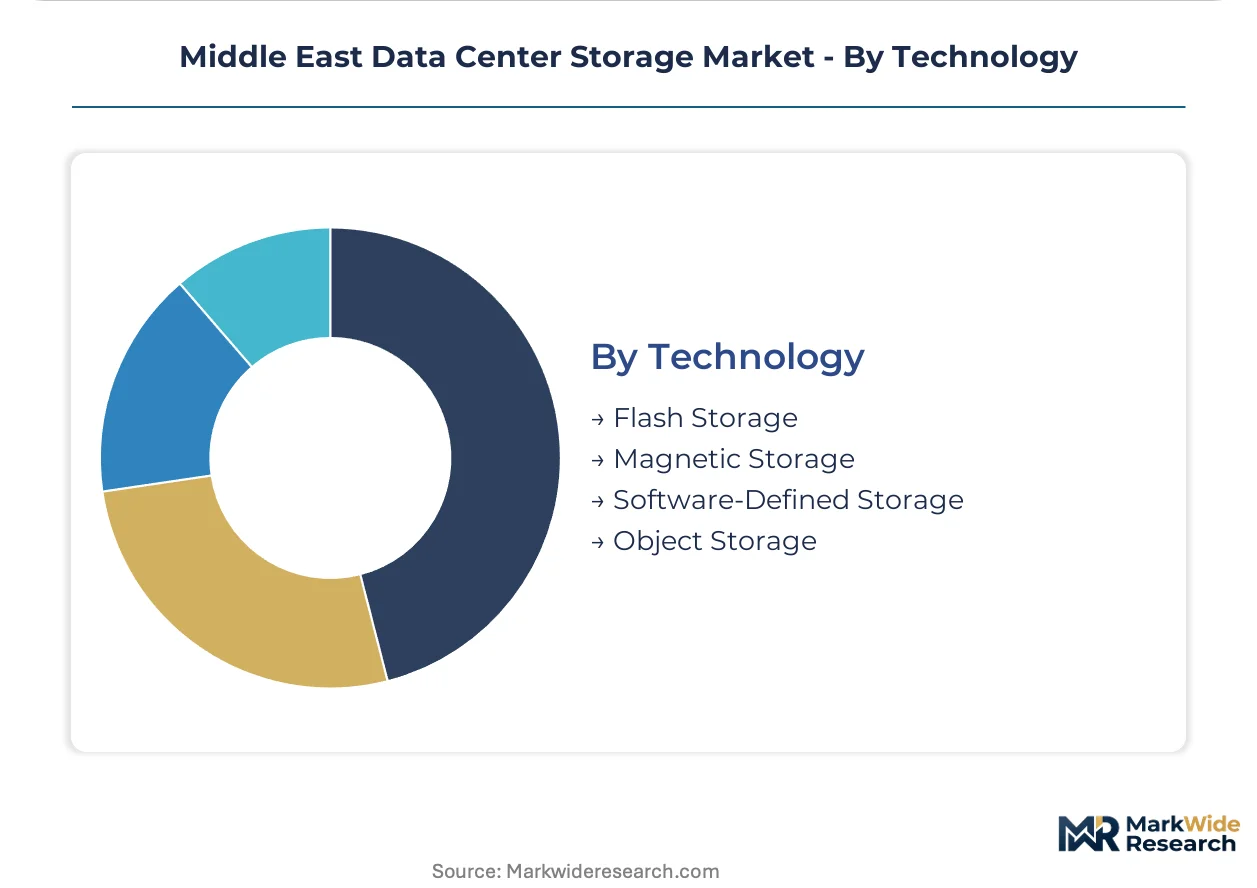
Storage procurement across the Gulf Cooperation Council bifurcates sharply between capital-intensive flash deployments for AI workloads and cost-optimized magnetic systems for archival compliance. Understanding these segment boundaries clarifies where vendor margins concentrate and which technologies face displacement pressure from sovereign cloud mandates.
Product Type:
Capital intensity varies by two orders of magnitude between electromechanical platters and enterprise-grade NAND arrays, reshaping procurement cycles across Saudi and Emirati facilities.
- Solid State Drives:NAND-based persistent storage delivers sub-millisecond latency and million-plus IOPS ratings per array. Riyadh's AI training clusters and Dubai's high-frequency trading infrastructure mandate these devices despite per-gigabyte premiums that strain budget allocations for secondary Emirates projects.
- Hard Disk Drives:Electromechanical spinning media retains cost advantages for sequential read workloads and petabyte-scale warm storage tiers. Saudi Arabia's National Data Management Office archival requirements and UAE smart city video retention policies sustain demand despite performance limitations that exclude latency-sensitive applications.
- Tape Storage:Linear magnetic media serves air-gapped backup and decade-plus retention mandates under Bahrain's fintech licensing frameworks and Qatar's critical infrastructure classifications.
- Hybrid Storage:Tiered architectures automatically migrate hot data to flash while relegating cold assets to disk, balancing performance density against capital constraints for mid-market enterprises in Abu Dhabi and Dammam.
Hard Disk Drives absorb the bulk of installed capacity; Solid State Drives are expanding most quickly.
Deployment Model:
Facility location decisions increasingly hinge on data residency certification rather than pure cost optimization, elevating domestic colocation and hybrid architectures over pure public cloud.
- On-Premises:Dedicated storage infrastructure within enterprise-owned facilities satisfies Saudi Arabia's strictest data classification tiers for defense and energy sector operators. NEOM and Red Sea development authorities mandate these deployments despite power infrastructure constraints that limit scalability in provincial locations.
- Hybrid:Workload portability between private arrays and sovereign cloud instances enables financial services operators in King Abdullah Financial District to burst compute without violating UAE Telecommunications and Digital Government Regulatory Authority encryption protocols. Procurement teams value the operational flexibility for seasonal analytics peaks.
- Cloud-Based:Fully outsourced capacity appeals to fintech licensing applicants seeking to preserve balance sheet capacity while satisfying regulatory data retention periods through consumption-based contracts.
- Colocation:Leased rack space in certified third-party facilities allows foreign cloud providers to establish domestic presence without greenfield construction, concentrating in Dubai Internet City and Riyadh's King Salman Energy Park.
On-Premises deployments retain the largest installed base; Hybrid architectures are climbing the fastest as enterprises navigate sovereignty requirements.
End User:
Budget authority and procurement sophistication diverge sharply between government entities with multi-year capital appropriations and cloud service providers optimizing for marginal cost per terabyte.
- Cloud Service Providers:Hyperscale operators across Saudi Arabia and the UAE deploy petabyte-scale infrastructure to satisfy National Data Management Office mandates and capture sovereign AI workloads. These buyers negotiate direct NAND supply agreements that bypass traditional channel margins.
- Government:Smart city programs in Dubai and Riyadh require hybrid storage architectures for real-time analytics pipelines, with procurement governed by dual-vendor policies that prevent single-source dependencies for critical infrastructure tiers.
- Enterprise:Corporate data centers in Jeddah and Abu Dhabi balance flash performance for transactional databases against disk economics for compliance archives.
- Telecommunications:5G operators in Dubai and Jeddah deploy edge-to-core storage convergence to reduce backhaul costs for latency-sensitive applications.
Government entities command the largest procurement volumes; Cloud Service Providers are gaining share fastest as sovereign localization mandates force infrastructure buildouts.
Technology:
Control plane abstraction is displacing hardware-centric procurement, with software-defined architectures decoupling capacity licensing from physical array purchases.
- Flash Storage:All-flash arrays optimized for NVMe-over-Fabrics dominate AI training clusters mandated by national artificial intelligence strategies. Pure Storage and comparable vendors differentiate through latency guarantees that satisfy generative AI workload requirements in Dubai International Financial Centre.
- Software-Defined Storage:Decoupled data management licensing enables multi-tenant revenue models and consumption-based capacity contracts that align provider margins with enterprise operational expenditure preferences across Abu Dhabi and Dammam managed service providers.
- Object Storage:Flat namespace architectures serve unstructured data lakes for smart city sensor aggregation and healthcare imaging archives under MOHAP retention requirements.
- Magnetic Storage:Rotating media and tape systems persist for sequential workloads where latency tolerance permits cost optimization.
Flash Storage commands the highest revenue concentration; Software-Defined Storage is expanding most quickly as procurement shifts toward subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Salman Energy Park and Dubai Internet City anchor regional capacity concentration through tax-advantaged licensing frameworks that reduce operational expenditure for hyperscale operators.
Saudi Arabia
Riyadh's AI training clusters and NEOM smart city infrastructure absorb premium flash storage volumes. The National Data Management Office enforces strict data residency tiers that compel domestic facility construction. King Abdullah Financial District hosts hybrid cloud deployments where financial institutions balance sovereignty requirements against burst compute needs.
United Arab Emirates
Dubai's fintech licensing regime and Abu Dhabi's sovereign wealth fund digitization drive petabyte-scale procurement. The Telecommunications and Digital Government Regulatory Authority mandates air-gapped tiers for critical infrastructure operators. Dubai Internet City concentrates colocation capacity where foreign cloud providers establish domestic presence without greenfield construction.
Qatar
Liquefied natural gas sector digitization and healthcare imaging archives sustain demand for tiered storage architectures. BIS-equivalent conformity assessment requirements filter vendor eligibility by certification status. Lusail smart city deployments require hybrid systems for real-time sensor analytics and compliance retention.
Bahrain
National Bureau for Revenue data protection frameworks create compliant colocation demand among payment processors and digital banks. The Bahrain FinTech Bay licensing cluster attracts regional headquarters seeking balance sheet preservation through consumption-based storage contracts. Secondary data center zones near Sitra handle archival workloads excluded from latency-sensitive primary tiers.
Kuwait
Oil sector digital transformation and government modernization programs sustain mid-market enterprise demand. Certification reciprocity negotiations with neighboring regulators determine vendor market access efficiency. Al-Zour and Sabiya industrial zones host emerging facility construction constrained by power infrastructure expansion timelines.
Middle East Data Center Storage Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, creating a bifurcated vendor landscape where breadth-of-portfolio and depth-of-technology represent alternative paths to contract capture. The market structure concentrates around three strategic archetypes: full-stack infrastructure conglomerates with established government channel relationships, flash-focused performance specialists optimizing for AI workload latency requirements, and Asian manufacturing champions leveraging localized assembly partnerships. Competitive dynamics center on dual-vendor policy compliance and sovereign cloud certification acquisition rather than pure price competition.
Within the diversified infrastructure tier, Dell Inc. and Hewlett Packard Enterprise occupy positions anchored by decades of enterprise server-storage integration and established public sector procurement channels. Huawei Technologies Co. Ltd. exemplifies the geographic diversification archetype through manufacturing partnerships that satisfy domestic content preferences. Pure Storage represents the performance-specialist vector with all-flash architectures targeting sub-millisecond latency mandates from national artificial intelligence strategies.
| Leading Market Players |
|---|
| Dell Inc. |
| Hewlett Packard Enterprise |
| NetApp Inc. |
| Huawei Technologies Co. Ltd. |
| Kingston Technology Company Inc. |
| Pure Storage |
| IBM |
| Hitachi Vantara |
| Dell EMC |
| Others |
Pricing and Supply Chain Analysis
Saudi Arabia's National Data Management Office data residency mandates gate qualified supply access for international storage vendors, compressing margins for uncertified equipment while enabling premium-tier pricing for compliant flash arrays serving Riyadh's AI training clusters.
Pricing Analysis
Short lead-time premiums for NAND-based flash arrays now command pricing spreads against spot inventory liquidation from secondary distributors. Subscription-based software-defined storage licensing stratifies across premium, standard, and economy tiers, with certification grade and volume scale as primary price differentiation drivers. Cost compression in magnetic storage tiers intensifies because hyperscale operators negotiate direct supply agreements that bypass traditional channel markups. Cloud service providers exhibit lowest price sensitivity due to sovereign mandate compliance requirements, while mid-market enterprises in secondary Emirates maximize operational expenditure preservation.
Supply Chain Analysis
Saudi and Emirati domestic-content procurement preferences reshape sourcing patterns, compelling assembly partnerships within King Salman Energy Park and Dubai Internet City to satisfy government tender eligibility. NAND fabrication concentrates in South Korea, Taiwan, and Japan, while controller silicon and power management components draw from Chinese and Malaysian facilities. Single-source vulnerability in advanced node flash memory exposes Gulf operators to logistics chokepoints through Red Sea shipping corridors. Distribution runs through authorized enterprise channel partners with established public sector procurement relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive NAND supply agreements and sovereign cloud certification acquisition represent the decisive upstream and downstream levers separating contract winners from margin-compressed followers.
For Market Incumbents: Cement dominance by locking multi-year direct supply agreements with East Asian foundries that secure flash memory allocation ahead of hyperscale competitor procurement cycles. Fortify position through in-house production of software-defined storage control planes that reduce licensing outflows to pure-play software vendors. The emerging threat of Huawei's localized assembly partnerships demands preemptive channel control investments across Saudi government accounts.
For New Entrants and Emerging Players: Direct-to-cloud-service-provider sales channels bypass entrenched enterprise reseller networks that Dell and HPE dominate. Target Bahrain's fintech licensing cluster as the most penetrable geography, where consumption-based contract demand from payment processors exceeds established vendor service capacity. Lead with NVMe-over-Fabrics performance guarantees that satisfy national artificial intelligence strategy latency mandates without legacy Fibre Channel integration burdens.
For Investors and Strategic Acquirers: Dual-vendor policy enforcement by UAE's Telecommunications and Digital Government Regulatory Authority is the leading indicator that sovereign certification capabilities will command acquisition premiums over pure technology differentiation. Long-term viability centers on software-defined revenue models with multi-tenancy architecture. Target acquisition archetypes are regional managed service providers with established colocation contracts in Dubai Internet City and Riyadh's King Salman Energy Park. The signal to monitor is certification reciprocity negotiations between Gulf regulators that would suddenly expand addressable market for previously excluded equipment suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Acquisition | UAE's TDRA and Saudi NDMO mandates make certification the primary contract eligibility gate. |
| Localized Assembly Partnership | Domestic manufacturing in King Salman Energy Park satisfies procurement preferences for government tenders. |
| Direct NAND Supply Agreement | Bypassing channel margins enables competitive positioning against Dell's entrenched enterprise relationships. |
| Software-Defined Storage Platform Launch | Subscription licensing aligns provider economics with cloud service provider operational expenditure preferences. |
| Edge-to-Core Architecture Development | 5G rollout across Dubai and Jeddah creates distributed storage demand for latency-sensitive applications. |
Research Methodology
Document review covered hyperscaler capex disclosures, SEC filings from listed storage vendors, and Gulf regulatory gazettes, complemented by interviews with data center infrastructure directors, cloud procurement officers, and channel sales executives at authorized distributors. Primary fieldwork engaged facility operators in King Salman Energy Park and Dubai Internet City, supplemented by technical discussions with certified storage engineers managing NEOM and Red Sea deployments. Secondary validation drew from customs import records, BIS-equivalent conformity assessment databases, and sovereign cloud framework documentation. Bottom-up facility capacity tallies triangulated against top-down procurement forecasts from government digitization program budgets.
Cross-reference between historical deployment patterns and panel input from infrastructure planners anchored the analytical framework across the projection horizon. Segmentation modeling incorporated product type, deployment model, end user category, and technology architecture dimensions, with regional regulatory cluster as an additional industry-specific layer. CAGRs were derived from facility construction timelines, NAND supply contract durations, and sovereign AI strategy implementation phases. Forecast inputs included power infrastructure expansion schedules across secondary Emirates and certification reciprocity negotiation status between Gulf regulators.
The model holds under stable data localization enforcement and continuous NAND supply availability; deviation in East Asian foundry output or regulatory reciprocity agreements would shift capacity deployment timelines. Forecasts reflect documented assumptions regarding hyperscale operator entry decisions and government appropriation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Data Center Storage Solutions Market
Data Storage
SAS Hard Disk Drives Market
Data Storage
NOR Flash Market
Data Storage
Multiprotocol Storage Market
Data Storage
Australia Data Center Storage Market
Data Storage
Non-Volatile Memory Express (Nvme) Market
Data Storage
Blu-Ray Drive Market
Data Storage
Ireland Data Center Storage Market
Data Storage
All Flash Storage Market
Data Storage
Solid State Array Market
Data Storage
Transparent Cache Market
Data Storage
Hybrid Flash Storage Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Storage Virtualization Market
Data Storage
OTG Pen Drive Market
Data Storage
Object-Based Storage Market