
 North America SSD Caching Market | 2026-2036
North America SSD Caching Market Size, Share, and Industry Trends Forecast 2026-2036
North America SSD Caching Market Foresight
The U.S. EPA ENERGY STAR for Data Center Storage is expanding procurement criteria that favor low-latency, high-density caching architectures in hyperscale facilities. Samsung Electronics Co. Ltd leverages its vertically integrated NAND fabrication to control cost curves across enterprise tiers. Intel Corporation anchors the market through Optane-adjacent controller IP and platform-level integration with Xeon architectures. Kingston Technology Company, Inc. competes on serviceable supply chains and configurable firmware for mid-market server OEMs.
SSD caching deploys non-volatile flash memory between DRAM and hard disk tiers to accelerate read/write throughput for hot data workloads, typically operating at sub-100 microsecond latency with NVMe protocol interfaces over PCIe 4.0 or 5.0 buses. The technology serves database management and virtualization environments where IOPS consistency determines application responsiveness. NVMe SSD and PCIe SSD categories lead product type segmentation due to direct-attached performance advantages in on-premises and hybrid integration levels. Cloud service providers and enterprises represent the fastest-growing end user segments as workload consolidation demands denser caching layers at the edge.
The U.S. Federal Energy Regulatory Commission and California Energy Commission shape facility-level power constraints that cascade into storage procurement specifications, while NIST cybersecurity frameworks mandate encryption-at-rest for federal caching deployments. Compliance with these overlapping standards raises engineering thresholds for cross-border hardware certification between the United States and Canada. Stakeholders must weigh firmware transparency requirements against proprietary controller optimization when qualifying suppliers for multi-tenant infrastructure refresh cycles.
Market Dynamics
Hyperscaler consolidation in Northern Virginia's data center corridor is compressing procurement cycles and forcing tier-one caching suppliers to pre-qualify firmware configurations against NIST cybersecurity frameworks before volume deployment.
Growth Catalysts
- California Title 24 efficiency codes:These building standards mandate power-density ceilings for data center storage hardware, accelerating flash-based tiering adoption over legacy disk architectures in hyperscale facilities across the state.
- Edge computing clusters:Distributed inference workloads in autonomous vehicle testing corridors and smart manufacturing zones are creating localized demand for sub-100 microsecond caching layers outside traditional cloud core regions.
- PCIe 5.0 bus proliferation:Next-generation server motherboard refreshes by enterprise OEMs are normalizing NVMe protocol interfaces, expanding addressable cache capacity per rack unit in database management environments.
Market Restraints
- NAND wafer supply concentration:Captive production at Korean and Japanese fabrication complexes creates input cost volatility when memory cycle downturns trigger supply discipline measures.
- Federal encryption-at-rest mandates:NIST framework compliance adds firmware certification timelines that extend qualification periods for multi-tenant infrastructure deployments by six to nine months.
- Compute Express Link (CXL) memory pooling:This emerging interconnect standard threatens to displace discrete caching tiers by enabling direct-attached DRAM expansion, reducing incremental SSD cache attach rates in greenfield data centers.
Strategic Opportunities
- Canada cross-border certification harmonization:Alignment between U.S. EPA ENERGY STAR criteria and Health Canada efficiency verification creates a unified procurement pathway for vendors serving the integrated North American hyperscaler supply chain.
- AI training checkpoint acceleration:Large language model workloads generate bursty write patterns that strain existing storage hierarchies, opening specialized high-endurance cache tiers for GPU cluster deployments.
- Utility-linked demand response programs:FERC Order 2222 implementation enables data center operators to monetize cached storage flexibility, creating incremental revenue streams that subsidize premium flash hardware deployment.
Industry Challenges
- Firmware transparency requirements:Federal procurement mandates for supply chain attestation conflict with proprietary controller optimization, forcing vendors to expose intellectual property or forfeit qualified supplier status.
- Legacy SAS infrastructure integration:Enterprise refresh cycles remain tethered to twelve-year depreciation schedules for existing disk arrays, complicating NVMe cache overlay deployment in financial services and healthcare verticals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America SSD Caching Market |
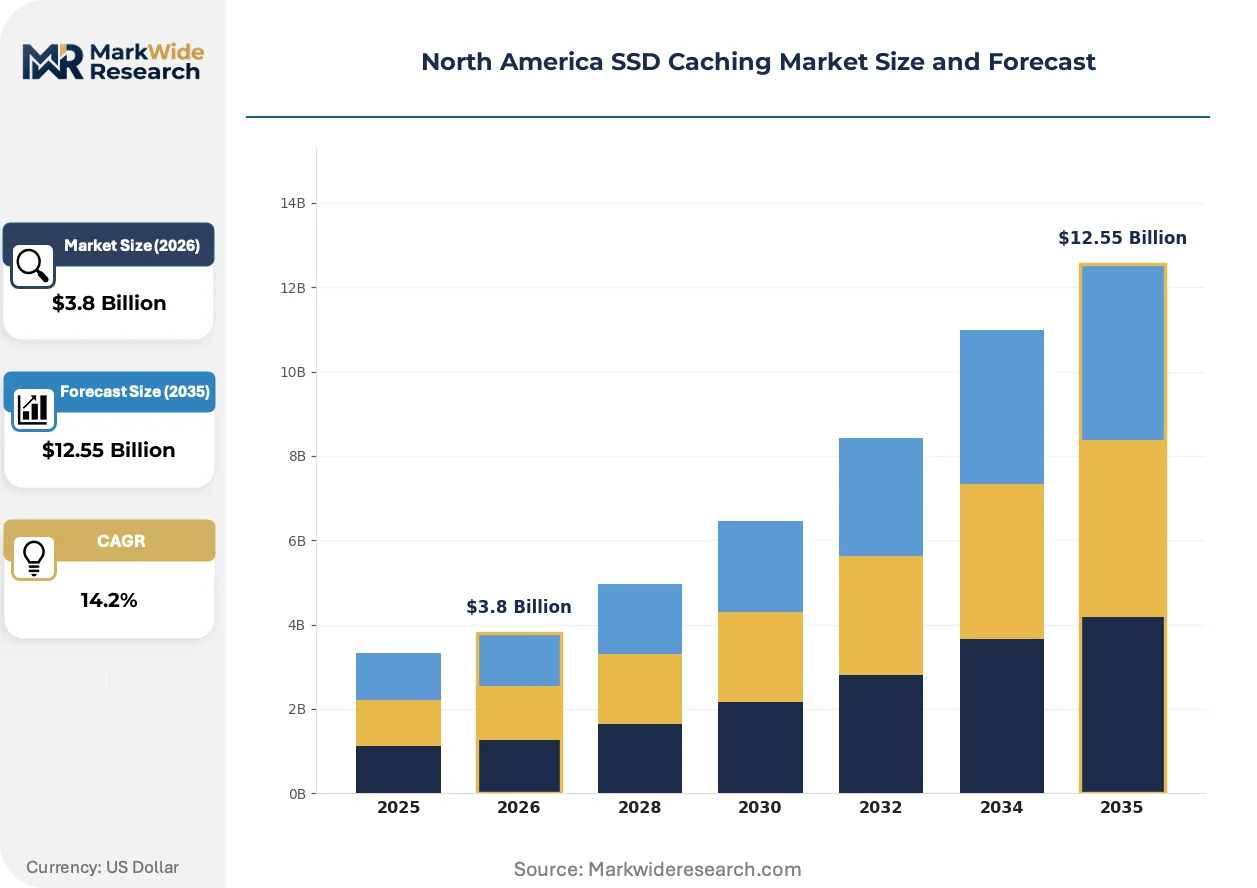
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SATA SSD, SAS SSD, NVMe SSD, PCIe SSD End User: Data Centers, Cloud Service Providers, Enterprises, SMBs Application: Database Management, Data Analytics, Virtualization, Content Delivery Integration Level: On-Premises, Cloud-Based, Hybrid, Edge |
| Companies Covered | Intel Corporation, Samsung Electronics Co. Ltd, Micron Technology Inc, Western Digital Corporation, Seagate Technology LLC, SK Hynix Inc., Kingston Technology Company, Inc., Kioxia Holdings Corporation, ADATA Technology Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America SSD Caching Market Shifts & Advancements
Intelligent tiering algorithms are compressing the boundary between hot and warm data classifications, forcing caching hardware to adapt to workload patterns that shift within seconds rather than hours.
Computational storage drives with in-situ processing capabilities are automating data reduction and encryption operations that previously consumed host CPU cycles. Hyperscalers in Northern Virginia and Dallas-Fort Worth corridors are piloting these devices at rack scale. This compression of data services into the storage layer is automating latency reduction for real-time analytics pipelines that previously required separate acceleration hardware.
The U.S. EPA ENERGY STAR for Data Center Storage program is expanding test criteria to capture idle-state power draw and thermal throttling behavior under sustained load. Hardware vendors must now submit controller firmware for third-party validation before federal procurement eligibility. Tier-two suppliers without captive NAND fabrication are responding by partnering with foundries to pre-certify reference designs, narrowing the compliance gap with vertically integrated competitors.
Consolidated buying desks at cloud service providers are compressing vendor qualification lists from twelve to four approved suppliers per caching tier, concentrating volume commitments among firms with vertically integrated controller IP. Mid-market enterprises lacking procurement scale are responding through distributor-led configuration services that aggregate demand across regional colocation facilities. This channel restructuring is most visible in secondary markets like Phoenix and Salt Lake City, where hyperscaler adjacency creates pricing leverage for smaller buyers.
North America SSD Caching Market Segmentation
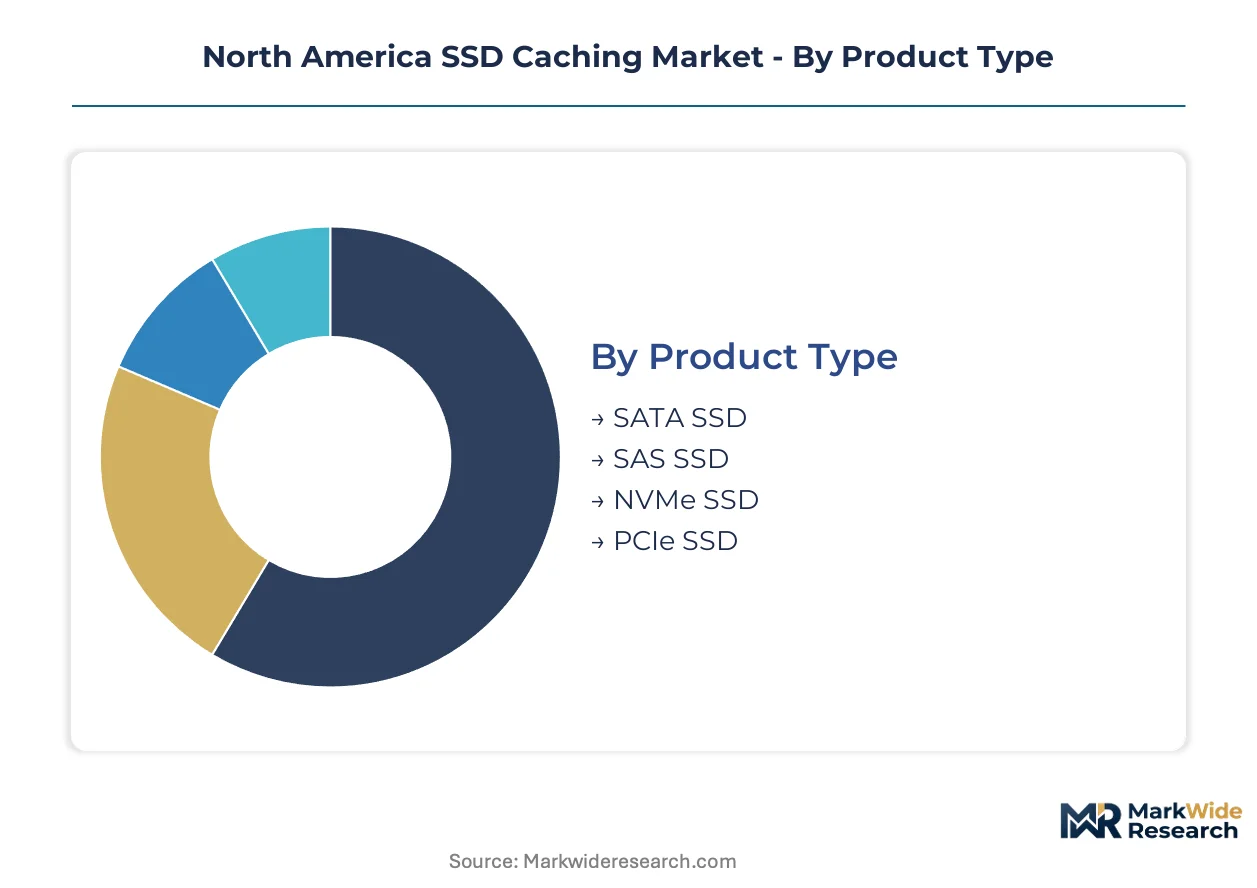
SSD caching architectures fragment across protocol generations, deployment topologies, and workload intensities. Each segmentation axis carries distinct procurement specifications that shape vendor qualification pathways and infrastructure refresh cycles across the North American data center corridor.
Product Type:
Protocol interface and bus architecture define performance ceilings and motherboard compatibility constraints for caching deployments.
- NVMe SSD:Direct-attached flash over PCIe lanes eliminates SCSI translation overhead, achieving sub-100 microsecond latency for database hot-tier acceleration. Hyperscalers in Northern Virginia pre-qualify NVMe controllers against NIST encryption-at-rest mandates before volume procurement.
- PCIe SSD:Native bus integration with Gen 4.0 and 5.0 signaling expands cache density per rack unit, supporting GPU cluster checkpoint workloads that generate bursty write patterns. Edge computing clusters in Dallas-Fort Worth corridors favor these devices for localized inference acceleration.
- SAS SSD:Dual-port 12Gb/s interfaces sustain legacy enterprise storage fabric compatibility for financial services refresh cycles tethered to twelve-year depreciation schedules.
- SATA SSD:AHCI protocol limitations constrain throughput to 600MB/s, relegating these devices to cold-tier overflow and archival caching in cost-constrained SMB environments.
Mature deployment sits with SAS SSD. Newer deployment is concentrated in NVMe SSD.
End User:
Procurement scale and qualification rigor separate volume buyers from specification-takers in the North American caching supply chain.
- Cloud Service Providers:Consolidated buying desks at hyperscalers compress vendor lists to four approved suppliers per tier, concentrating commitments among firms with captive NAND fabrication and in-house controller IP. These buyers normalize PCIe 5.0 interfaces eighteen months ahead of enterprise adoption curves.
- Enterprises:Mid-market server OEMs rely on distributor-led configuration services that aggregate regional colocation demand across Phoenix and Salt Lake City secondary markets, creating pricing leverage against hyperscaler adjacency.
- Data Centers:Multi-tenant facility operators in Northern Virginia face FERC-linked demand response program requirements that monetize storage flexibility, subsidizing premium flash hardware deployment.
- SMBs:Depreciation-schedule constraints and limited procurement scale push smaller buyers toward SATA-based tiering solutions with extended firmware support windows.
Volume concentration sits with Cloud Service Providers. Margin expansion is concentrated in Enterprises.
Application:
Workload I/O pattern and latency sensitivity determine cache tier sizing and endurance specifications.
- Database Management:OLTP environments demand consistent IOPS for transaction commit latency, driving high-endurance cache tiers with DWPD ratings above three. Financial services verticals in New York and Chicago metro areas anchor this segment.
- Virtualization:Hypervisor memory ballooning and storage vMotion operations create random read amplification that benefits from large cache working sets, expanding addressable capacity per host in enterprise private cloud deployments.
- Data Analytics:Columnar query engines scan compressed parquet files that exceed DRAM capacity, using caching layers to reduce S3 egress costs in hybrid integration configurations.
- Content Delivery:Sequential read patterns for video segment serving tolerate higher latency than interactive workloads, allowing cost-optimized QLC NAND in edge PoP locations.
Performance premium sits with Database Management. Scale deployment is concentrated in Virtualization.
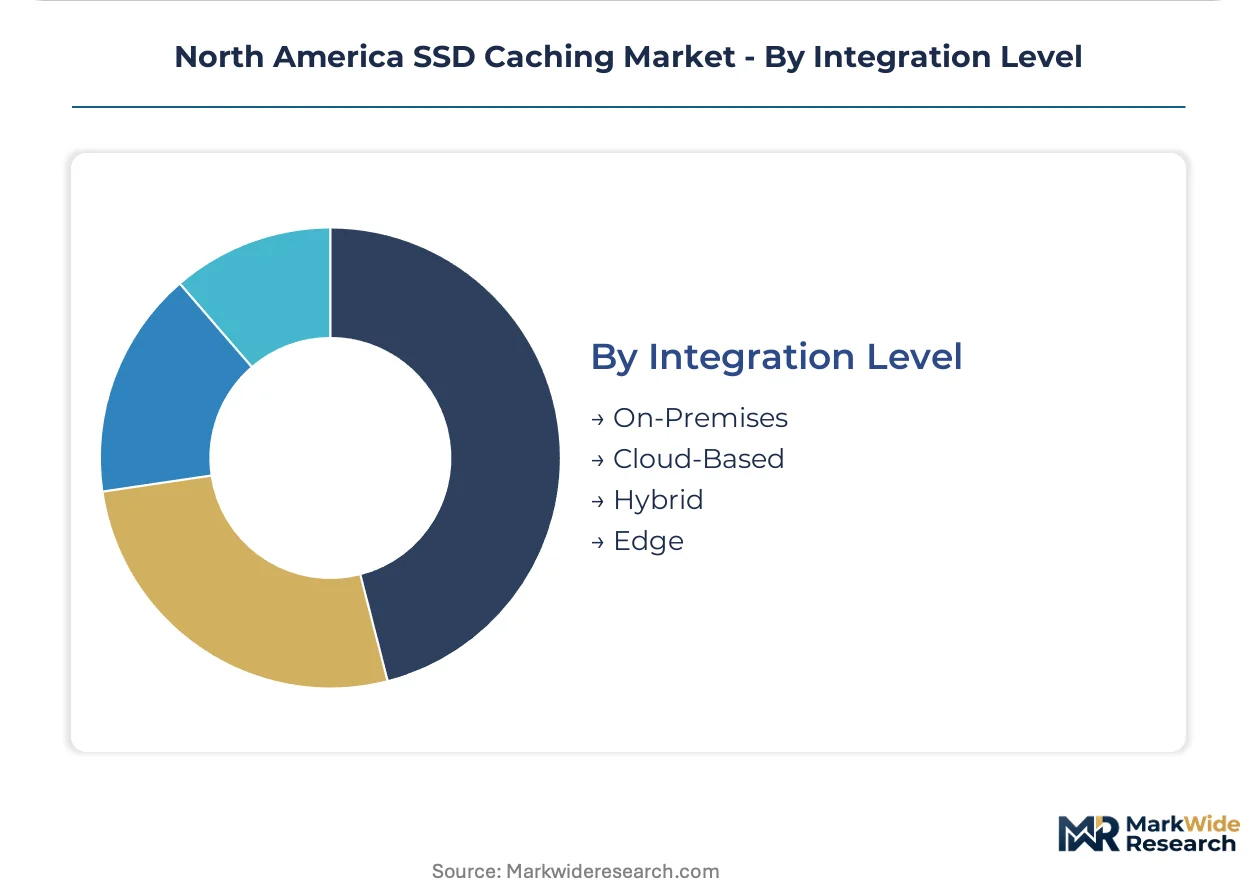
Integration Level:
Physical proximity to compute resources and control plane ownership shape caching architecture decisions.
- On-Premises:Direct-attached storage in enterprise-owned facilities retains full firmware control and audit logging for HIPAA-regulated healthcare workloads, though California Title 24 efficiency codes now mandate power-density compliance for new installations.
- Hybrid:Tiered hot-warm-cold architectures span colocated edge caches and cloud object storage, with policy-driven data placement automating latency-cost tradeoffs for analytics pipelines.
- Edge:Autonomous vehicle testing corridors and smart manufacturing zones in Michigan and Texas deploy sub-100 microsecond caching outside traditional cloud core regions, creating localized demand for ruggedized NVMe devices.
- Cloud-Based:Managed cache services abstract hardware specification from tenant visibility, though NIST framework compliance still requires encryption-at-rest attestation for federal workloads.
Control retention sits with On-Premises. Deployment velocity is concentrated in Edge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's data center corridor dominates North American SSD caching procurement, with hyperscaler consolidation in Loudoun and Prince William counties compressing vendor qualification cycles and dictating regional capacity planning.
United States
Hyperscaler demand concentrates in Northern Virginia, Dallas-Fort Worth, and Phoenix metro corridors where cloud service providers operate consolidated buying desks. The U.S. EPA ENERGY STAR for Data Center Storage program mandates third-party firmware validation for federal procurement eligibility. California Title 24 efficiency codes enforce power-density ceilings that accelerate flash-based tiering adoption in Sacramento and San Jose facility expansions.
Canada
Cross-border hyperscaler supply chains integrate Toronto and Montreal data center clusters with U.S. procurement networks. Health Canada efficiency verification aligns with EPA criteria, creating unified certification pathways for vendors. Vancouver's proximity to Seattle-Tacoma cloud corridors positions British Columbia as a secondary caching hardware distribution node serving Pacific Northwest demand.
Mexico
Nearshoring manufacturing investments in Nuevo León and Baja California generate edge computing demand for localized caching infrastructure. The country's energy regulator enforces grid stability standards that influence storage hardware procurement for automotive testing corridors around Monterrey. Guadalajara's electronics manufacturing zone anchors regional supply chain integration with U.S. distribution networks.
North America SSD Caching Market Competitive Landscape
The competitive structure tilts toward vertically integrated memory fabricators with captive NAND production and in-house controller intellectual property. Tier-one suppliers concentrate volume commitments through pre-qualified firmware configurations, while mid-market distributors aggregate regional demand to secure pricing leverage. Three archetypes dominate: captive foundry operators, fabless controller specialists, and distributor-led configuration aggregators. Capacity expansion and strategic partnerships constitute the primary competitive moves, with vendors prioritizing cross-border certification harmonization.
Among vertically integrated fabricators, Samsung Electronics Co. Ltd and Intel Corporation occupy distinct positioning archetypes. Samsung exemplifies the captive foundry model with upstream control over NAND wafer supply. Intel anchors platform-level integration through processor-adjacent controller ecosystems. Kingston Technology Company, Inc. represents the distributor-responsive tier, competing on configurable firmware and serviceable supply chains for mid-market server OEMs.
| Leading Market Players |
|---|
| Intel Corporation |
| Samsung Electronics Co. Ltd |
| Micron Technology Inc |
| Western Digital Corporation |
| Seagate Technology LLC |
| SK Hynix Inc. |
| Kingston Technology Company, Inc. |
| Kioxia Holdings Corporation |
| ADATA Technology Co. Ltd |
| Others |
Supply & Pricing Matrix
Vertically integrated NAND fabricators with sovereign-backed capital structures anchor supply-side discipline across the North American SSD caching market, translating captive wafer production into pricing power that resists cyclical margin compression. These producers leverage upstream control over flash memory supply to enforce contract-based long-term offtake pricing, while hyperscaler procurement desks in Northern Virginia extract volume discounts that compress tier-two margins.
Pricing Analysis
Value-based pricing anchored to IOPS consistency and sub-100 microsecond latency outcomes dominates enterprise procurement, with hyperscalers paying premiums for NIST-certified firmware configurations. Three-tier pricing structure across premium, standard, and economy levels separates NVMe PCIe 5.0 devices from Gen 4.0 mid-tier offerings and legacy SAS compatibility SKUs. Cost compression in the SATA tier is intensifying because distributor-led aggregations in Phoenix and Salt Lake City secondary markets consolidate SMB demand. Cloud service providers exhibit lowest price sensitivity due to consolidated buying power, while mid-market enterprises lacking procurement scale face highest cost pressure.
Supply Chain Analysis
Dual-sourcing requirements embedded in federal procurement mandates force hyperscalers to qualify controllers from at least two independent suppliers before volume deployment, fragmenting order concentration. NAND wafer supply draws from South Korea, Japan, and domestic U.S. fabrication complexes, with controller ASICs sourced from Taiwan and U.S. design houses. Single-source vulnerability concentrates in advanced node controller fabrication, where foundry capacity constraints create qualification bottlenecks. Distribution runs through authorized server OEM channels and distributor-led configuration services that aggregate regional colocation demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America SSD caching market functions as a cost-of-compliance story, where U.S. EPA ENERGY STAR third-party firmware validation requirements create a regulatory moat that screens out undercapitalized competitors. NIST cybersecurity framework attestation extends qualification timelines, concentrating volume commitments among pre-certified suppliers.
For Market Incumbents: Deploy firmware transparency investments as the primary defensive lever against Compute Express Link memory pooling threats that risk displacing discrete caching tiers. Pre-qualify controller configurations against California Title 24 efficiency codes before facility expansion waves in Sacramento and San Jose. Capture margin expansion through utility-linked demand response program participation enabled by FERC Order 2222 implementation.
For New Entrants and Emerging Players: Mid-market server OEMs lacking captive NAND fabrication represent the most penetrable buyer archetype for fabless controller specialists with configurable firmware capabilities. Target distributor-led configuration channels in Phoenix and Salt Lake City secondary markets where hyperscaler adjacency creates pricing leverage aggregation. Lead with serviceable supply chains and extended firmware support windows as the go-to-market angle against vertically integrated incumbents.
For Investors and Strategic Acquirers: Distressed-cycle entries favor fabless controller specialists with pre-certified reference designs in Toronto and Montreal corridors, where Health Canada efficiency verification alignment with EPA criteria creates unified procurement pathways. Long-term viability hinges on cross-border certification harmonization capabilities across the integrated North American hyperscaler supply chain. Watch NAND memory cycle trough timing as the inflection indicator for valuation entry points.
| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Certification Investment | NIST cybersecurity framework pre-qualification compresses hyperscaler vendor lists to four approved suppliers per tier. |
| Backward Integration into NAND Fabrication | Captive wafer production insulates margin structures from Korean and Japanese supply cycle volatility. |
| Cross-Border Certification Harmonization | Alignment between EPA ENERGY STAR and Health Canada criteria creates unified procurement pathways for Canadian expansion. |
| Utility-Linked Demand Response Participation | FERC Order 2222 enables monetization of storage flexibility, subsidizing premium flash hardware deployment. |
| Edge Computing Cluster Targeting | Autonomous vehicle testing corridors in Michigan and Texas generate localized demand outside cloud core regions. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and U.S. EPA ENERGY STAR certification databases formed the secondary backbone, supplemented by customs and trade flow records for NAND wafer and controller ASIC movements. Primary interviews with data center procurement officers, server OEM product managers, firmware engineering directors, and distributor configuration specialists validated demand assumptions and qualification timeline estimates. Bottom-up unit economics and top-down addressable market sizing were triangulated against facility expansion announcements in Northern Virginia, Dallas-Fort Worth, and Phoenix corridors.
Bottom-up modeling aggregated cache capacity per rack unit assumptions across deployment topology segments, while top-down analysis tracked hyperscaler infrastructure investment disclosures. Segmentation dimensions included protocol interface generation, integration level topology, end-user procurement scale, and workload intensity tier. CAGRs were derived from installation base growth rates and replacement cycle compression factors, with inputs from PCIe bus generation adoption curves and edge computing cluster deployment timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Compute Express Link memory pooling adoption rates and NAND supply cycle discipline measures. Forecasts reflect documented assumptions regarding hyperscaler consolidation patterns and regulatory compliance timeline stability. Deviation in CXL interoperability standardization or federal encryption mandate expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
Next-Generation Storage Market
Data Storage
External Storage Market
Data Storage
Nearline Hard Disk Drive Market
Data Storage
Storage and Management Market
Data Storage
Ceph Storage Solutions Market
Data Storage
Next Generation Data Storage Market
Data Storage
Asia Pacific Transparent Caching Market
Data Storage
Global Purpose-Built Backup Appliance (PBBA) Market
Data Storage
Enterprise-Class Hybrid Storage Market
Data Storage
Middle East and Africa Data Storage Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
USB Key Market
Data Storage
Powered Storage Devices Market
Data Storage
All Flash Storage Market
Data Storage
NAND Flash Market
Data Storage
Heat-Assisted Magnetic Recording (HAMR) Device Market