
 Stone Flooring Market | 2026-2036
Stone Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Stone Flooring Market Intelligence
Project finance for large-scale quarry rehabilitation and asset-light leasing models for fabrication equipment is rewriting capital requirements for mid-tier stone processors. Cosentino Group leverages vertical integration from quarry to slab to maintain margin control across premium surfaces. Levantina Group anchors its position through captive Spanish and Brazilian quarry assets that sustain volume consistency. Mohawk Industries competes via broad distribution reach and brand portfolio density in North American retail channels.
Stone flooring comprises dimension stone slabs or tiles cut from quarried rock—primarily marble, granite, slate, and limestone—typically finished to specified thicknesses between 10 mm and 30 mm and installed with thin-set adhesive or mortar bed systems for structural permanence in high-traffic environments. Marble holds established share in luxury residential and hospitality settings where aesthetic distinction commands premium positioning, while granite dominates commercial kitchens and institutional lobbies demanding abrasion resistance. The floating and pre-attached installation segments are gaining specification share as modular construction methods reduce on-site skilled labor requirements.
EPA quarry dust standards and OSHA silica exposure limits shape extraction and fabrication workplace practices in the United States, while the EU Green Deal's carbon border adjustments and CE marking requirements for construction products pressure importers to document lifecycle emissions. India's BIS certification for dimension stone quality and the Rajasthan State Pollution Control Board's mining consent conditions govern domestic supply reliability. Stakeholders must monitor regulatory divergence between embodied carbon accounting methodologies as compliance costs fragment competitive positioning across export markets.
Market Dynamics
The EU Green Deal's embodied carbon disclosure mandates are compressing margins for exporters while concentrating procurement power among vertically integrated quarry-to-slab operators with verified lifecycle data.
Growth Catalysts
- UAE Luxury Hospitality:Dubai and Riyadh hotel developments specify premium marble and travertine for lobbies and guest suites, pulling volume from Rajasthan quarries through dedicated project contracts.
- REACH Compliance Premium:European importers now pay documented premiums for CE-marked stone with verified extraction emissions, rewarding processors who invested in quarry-to-project traceability systems early.
- Thin-Set Adhesive Advances:Modified polymer thin-sets rated for heavy-traffic commercial installation are displacing traditional mortar beds, reducing skilled labor hours and accelerating project timelines.
Market Restraints
- Rajasthan Supply Concentration:Overreliance on the Makrana and Rajsamand quarry belts creates vulnerability to monsoon flooding and state mining consent delays that freeze export volumes for 60-90 day periods.
- Silica Exposure Compliance:OSHA's respirable crystalline silica permissible exposure limit of 50 micrograms per cubic meter forces US fabricators to invest in wet-cutting infrastructure or face operational shutdowns.
- Engineered Stone Substitution:Quartz composite surfaces priced 30-40% below equivalent granite are capturing mid-market residential specification previously held by natural stone tile.
Strategic Opportunities
- Carbon Border Adjustment Arbitrage:EU importers with documented low-carbon quarry operations can capture margin expansion as the CBAM phases in construction materials coverage through 2026.
- Modular Prefabrication:Factory-attached underlayment systems compatible with floating installation methods open specification in multi-family housing where traditional mortar beds face weight restrictions.
- Saudi Giga-Project Pipeline:NEOM and Red Sea Development Authority tenders specify natural stone for exterior cladding and interior flooring, creating dedicated offtake agreements for qualified suppliers.
Industry Challenges
- Master Craftsperson Scarcity:Wet-polishing and hand-finishing skills required for premium marble specification are disappearing as veteran Italian and Portuguese technicians retire without trained replacements.
- Multi-Jurisdiction Certification Lag:Simultaneous BIS, CE marking, and EPA compliance documentation extends product launch timelines by 8-14 months for new quarry sources.
- Legacy ERP Integration:Rajasthan-based processors struggle to connect quarry management systems with customer-facing traceability portals demanded by EU Green Deal procurement clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stone Flooring Market |
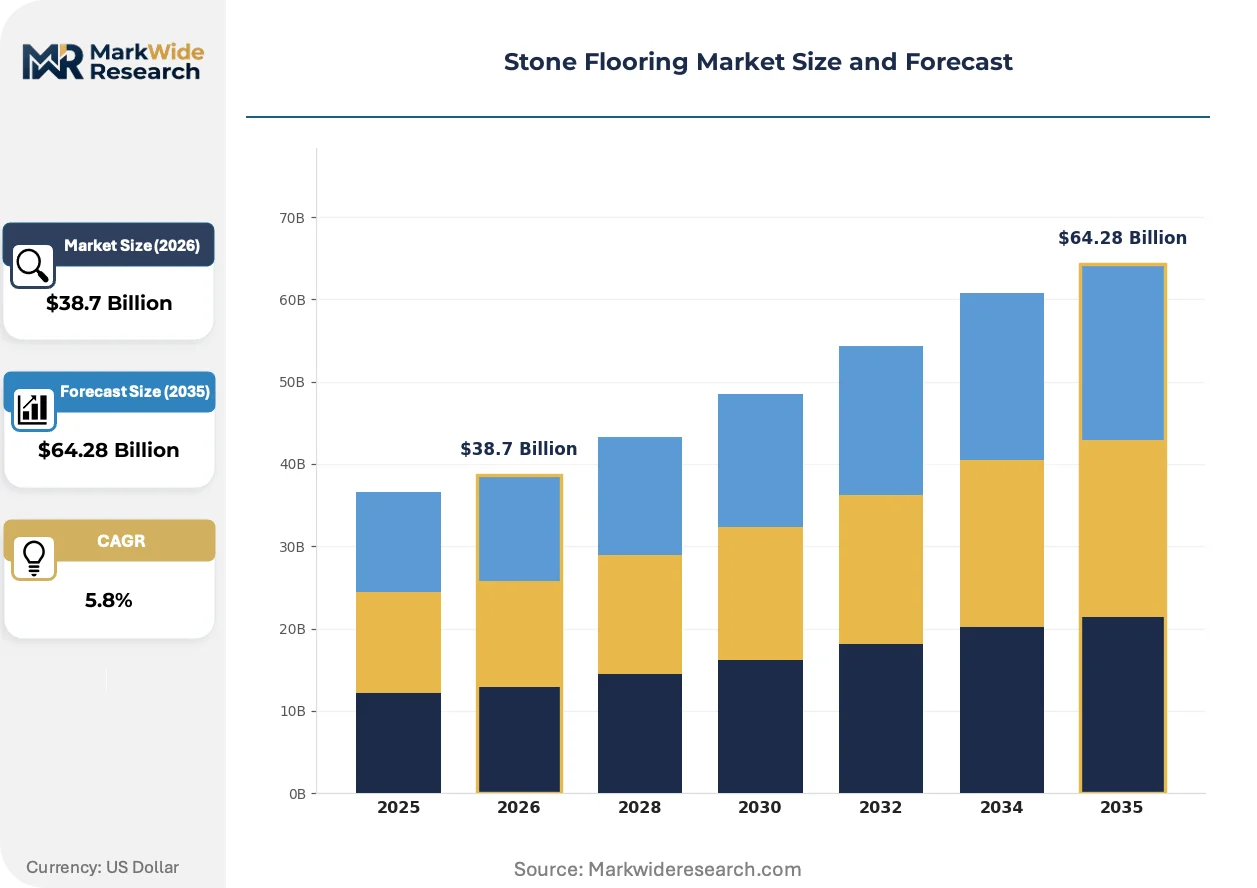
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marble, Granite, Slate, Limestone Application: Residential, Commercial, Institutional, Outdoor Installation Type: Thin-Set, Mortar Bed, Floating, Pre-Attached Finish Type: Polished, Honed, Tumbled, Textured |
| Companies Covered | Stone Source, Emser Tile, Mohawk Industries, Antolini Luigi & C. S.p.a., Cosentino Group, Shaw Industries, Levantina Group, Arizona Tile, Polycor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stone Flooring Market Strategic Shifts & Innovations
Digital traceability infrastructure and installation mechanization are restructuring competitive advantage away from raw material access toward data-verified supply chain control.
Waterjet cutting combined with CNC surface texturing is collapsing the cost differential between standard polished finishes and custom architectural surfaces. Boutique hospitality designers in Milan and Miami specify these machined textures for feature walls and flooring insets. The technology is collapsing the traditional premium commanded by hand-finished specialty surfaces, forcing artisan-dependent competitors into narrower ultra-luxury niches.
The EU Green Deal's Construction Products Regulation amendment mandates Environmental Product Declarations for all stone flooring placed on the European market. Fabricators must now document quarry extraction energy, water consumption, and waste generation through third-party verification. Indian exporters to Germany and the Netherlands are consolidating around large processors with in-house sustainability audit capabilities, marginalizing smaller traders.
Architects and developers now require blockchain-verified chain-of-custody documentation from quarry to installation site. Large commercial projects in London and Singapore specify this as a contract condition, displacing traditional paper-based certificates of origin. Procurement teams at international hotel chains are the most aggressive adopters, using verified provenance as a brand differentiation tool in sustainability marketing.
Stone Flooring Market Segmentation
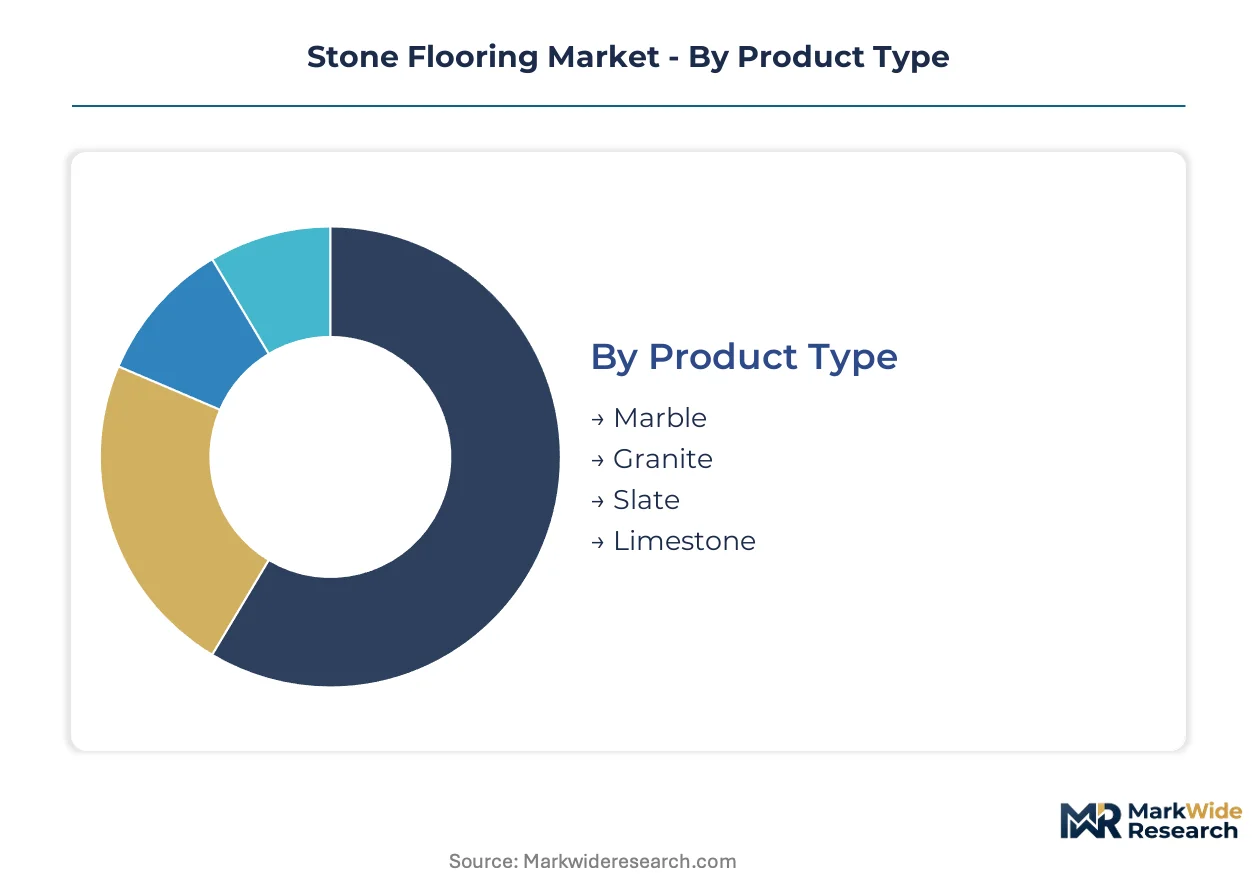
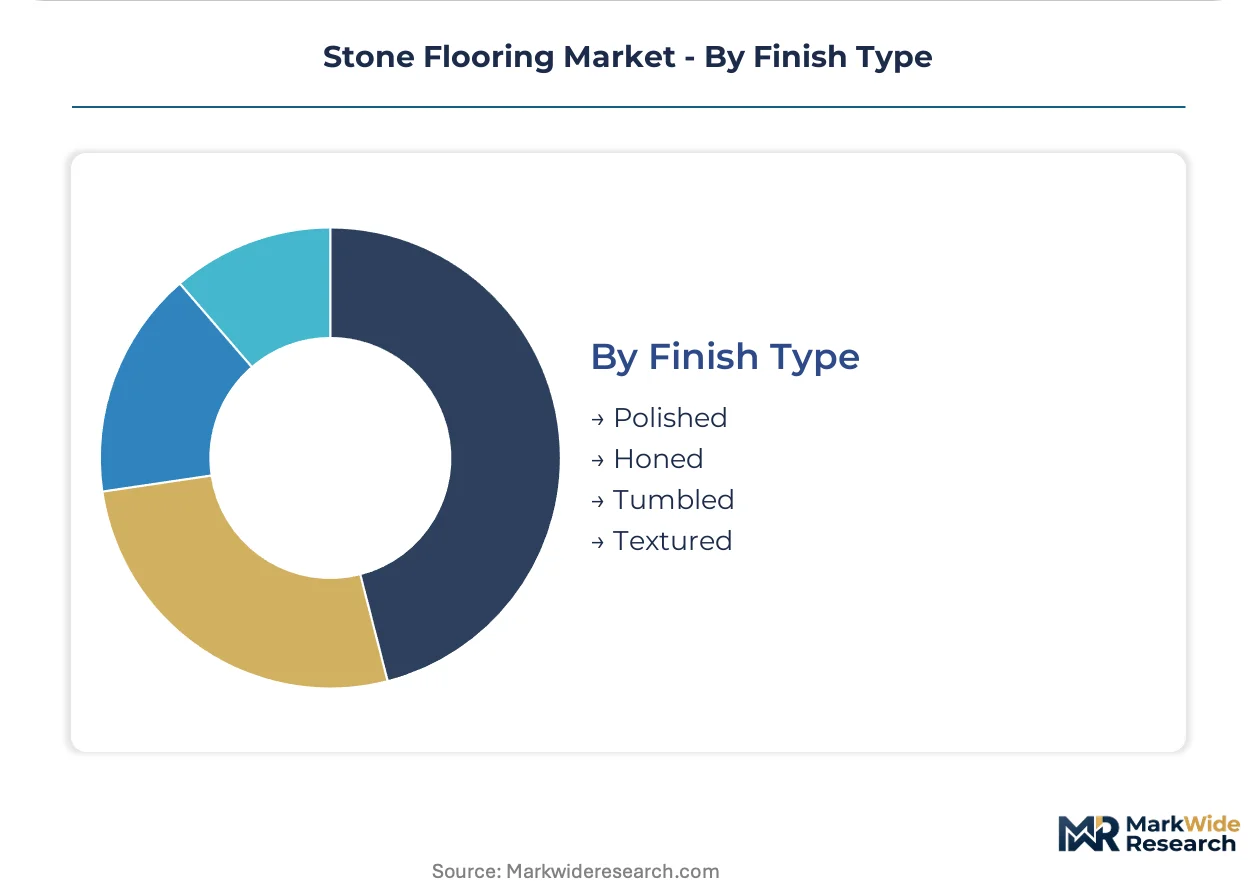
Stone flooring segmentation reveals how specification requirements diverge across project types and installation constraints. Product chemistry, surface finish, and mounting systems each create distinct procurement channels with incompatible supplier capabilities.
Product Type:
Material composition determines structural performance thresholds and aesthetic positioning across construction verticals.
- Marble:Metamorphic calcium carbonate stone with characteristic veining, specified in 10-20 mm thicknesses for interior applications. Luxury hospitality developments in Dubai and Riyadh specify Calacatta and Statuario varieties for lobby flooring, though porosity requires regular sealing maintenance.
- Granite:Igneous silicate mineral composite with Mohs hardness 6-7, enabling abrasion resistance in high-traffic commercial environments. Institutional lobbies and commercial kitchens across North American and Middle Eastern markets specify granite for durability under rolling loads and chemical exposure.
- Slate:Fine-grained metamorphic rock with natural cleavage planes enabling slip-resistant split finishes. Exterior paving and pool deck applications favor slate's low water absorption and thermal stability.
- Limestone:Sedimentary calcium carbonate with uniform texture suitable for large-format tiles. Historic restoration projects and traditional architectural styles specify limestone for color consistency with existing masonry.
Marble commands the established base. The steepest expansion runs through granite as commercial durability specifications tighten.
Application:
End-use environments impose divergent performance certifications and installation complexity tiers.
- Residential:Single-family and multi-family housing specifies stone for kitchens, bathrooms, and entryways, with floating installation methods gaining share in renovation projects where structural load limits prohibit mortar beds.
- Commercial:Retail, hospitality, and office developments require ADA-compliant slip resistance ratings and documented fire performance. REACH-compliant European importers now demand EPD-verified extraction emissions for hotel and retail fit-outs.
- Institutional:Government buildings, healthcare facilities, and educational institutions specify stone for durability under decades of continuous use. BIS certification and wet-slip testing dominate procurement criteria in Indian public sector tenders.
- Outdoor:Exterior paving, plaza decking, and landscape architecture requires freeze-thaw resistance and salt tolerance. Thermal expansion accommodation and drainage integration constrain installation system selection.
Commercial applications command the established base. The steepest expansion runs through residential as modular prefabrication reduces skilled labor barriers.
Installation Type:
Mounting methodology determines project timeline, structural loading, and skilled labor requirements.
- Thin-Set:Modified polymer adhesive systems enable direct bonding to concrete substrates, reducing installation height and curing time. Heavy-traffic commercial formulations now displace traditional mortar beds in airport and hospital specifications.
- Mortar Bed:Sand-cement screed systems provide structural permanence and substrate correction for natural stone's dimensional variation. Heritage restoration and premium residential projects retain mortar beds for acoustic isolation and crack suppression.
- Floating:Interlocking or click-lock systems with factory-attached underlayment enable rapid installation without adhesive curing. Multi-family housing developers specify floating stone-look luxury vinyl or engineered stone composites where weight restrictions prohibit traditional stone.
- Pre-Attached:Factory-bonded underlayment and membrane systems compatible with modular construction methods. Offsite fabrication clusters in Rajasthan and Spain are investing in pre-attached production lines for European and Middle Eastern project contracts.
Mortar bed installation commands the established base. The steepest expansion runs through thin-set as polymer adhesive performance advances.
Finish Type:
Surface processing determines light reflectance, slip resistance, and maintenance protocols.
- Polished:Mechanical grinding to 3000+ grit produces mirror reflectance, specified for luxury residential and hospitality interiors where visual impact dominates. Waterjet and CNC texturing technologies are compressing premiums previously commanded by hand-polished artisan finishes.
- Honed:Satin-smooth surface with subdued reflectance, balancing aesthetics with reduced visibility of scratches and etching. Commercial office and residential specifications favor honed finishes for lower maintenance requirements.
- Tumbled:Abrasive aging process producing rounded edges and antique appearance. Mediterranean and traditional architectural styles specify tumbled travertine and limestone for exterior paving and interior feature walls.
- Textured:CNC-machined or waterjet-cut surface patterns enabling custom architectural effects. Boutique hospitality designers in Milan and Miami specify machined textures for feature flooring insets, collapsing cost differentials against hand-finished specialty surfaces.
Polished finishes command the established base. The steepest expansion runs through textured surfaces as CNC machining capabilities proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium stone commands pricing premiums in Dubai and Riyadh that Rajasthan exporters cannot replicate in European markets facing carbon border adjustments. This asymmetry concentrates investment in traceability infrastructure for EU-bound supply chains while Gulf project finance absorbs volume from legacy quarries.
United States
Commercial hospitality and luxury residential construction in Miami, Los Angeles, and New York specify granite and marble for high-traffic lobbies and amenity spaces. OSHA's respirable crystalline silica standard at 50 micrograms per cubic meter forces fabricators toward wet-cutting infrastructure investments. Fabrication clusters in Georgia and Tennessee are expanding capacity to serve southeastern hotel development pipelines.
Germany
Hotel operators and retail developers in Berlin, Munich, and Hamburg now require Environmental Product Declarations for all stone flooring procurement. The EU Green Deal's Construction Products Regulation amendment mandates third-party verification of quarry extraction emissions. Importers in the Rhine-Ruhr industrial corridor are consolidating around large processors with in-house sustainability audit capabilities.
India
Rajasthan's Makrana and Rajsamand quarry belts supply Calacatta and Statuario marble for Middle Eastern luxury hospitality projects. BIS certification for dimension stone quality and Rajasthan State Pollution Control Board mining consent conditions govern domestic supply reliability. Fabrication clusters around Jaipur and Udaipur are investing in pre-attached underlayment production lines for modular construction exports.
United Arab Emirates
Dubai's hotel developments and Riyadh's giga-projects specify premium travertine and marble for lobbies, guest suites, and exterior cladding. MOHAP construction product safety standards and Dubai Municipality green building regulations shape procurement specifications. Dedicated project contracts from NEOM and Red Sea Development Authority tenders are pulling volume through direct offtake agreements with qualified Rajasthan suppliers.
Spain
Architectural restoration in Barcelona and Madrid sustains demand for traditional limestone and granite matching historic masonry. CE marking requirements and EU Green Deal carbon border adjustments pressure importers to document lifecycle emissions. Quarry-to-slab operators in Galicia and Extremadura leverage captive domestic assets to maintain volume consistency for European distribution.
Stone Flooring Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream where quarry access and fabrication scale determine margin capture. The vendor base organizes around three strategic archetypes: vertically integrated quarry-to-slab operators with captive mineral assets, brand-dense distributors controlling retail channel access, and regional fabricators serving project-specific specification. Consolidation pressure concentrates among mid-tier processors lacking traceability infrastructure for EU Green Deal compliance. Competitive moves center on backward integration into quarry assets and modular prefabrication capacity for floating installation systems.
Among vertically integrated specialists, Cosentino Group and Levantina Group exemplify the quarry-captive archetype with Spanish and Brazilian mineral assets sustaining volume consistency. Mohawk Industries occupies a position representing brand-dense distribution reach across North American retail channels. These three anchors illustrate how competitive advantage is concentrating around verified supply chain control rather than raw material access alone.
| Leading Market Players |
|---|
| Stone Source |
| Emser Tile |
| Mohawk Industries |
| Antolini Luigi & C. S.p.a. |
| Cosentino Group |
| Shaw Industries |
| Levantina Group |
| Arizona Tile |
| Polycor |
| Others |
Cost & Logistics Intelligence
Undercapacity in Rajasthan's wet-season fabrication clusters compresses export volumes and emboldens spot-price premiums for Gulf-bound Calacatta and Statuario marble. This utilization squeeze rewards processors with captive quarry assets and traceability infrastructure, while marginalizing traders dependent on spot-market slab procurement.
Pricing Analysis
Configured-to-order pricing for CNC-textured architectural surfaces commands spreads exceeding standard polished slabs by multiples reflecting labor displacement and design exclusivity. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with CE-marked EPD-verified stone capturing documented premiums from REACH-compliant European importers. Cost compression in mid-market granite tile intensifies as quartz composite surfaces priced below equivalent natural stone capture residential specification. Commercial hospitality developers in Dubai and Riyadh exhibit least price sensitivity, while North American multi-family housing developers face strict value-engineering thresholds.
Supply Chain Analysis
Export-control regimes limiting quarry-to-project transparency technology flows constrain Rajasthan-based processors seeking EU Green Deal compliance. Supply concentrates in India, Spain, and Brazil, with fabrication clusters drawing from captive limestone, granite, and marble deposits. Wet-cutting infrastructure, polymer-modified thin-set adhesives, and blockchain-verified chain-of-custody documentation constitute critical input dependencies. Single-source vulnerability concentrates in Makrana and Rajsamand quarry belts where monsoon flooding freezes export volumes. Distribution runs through vertically integrated quarry-to-slab operators and brand-dense retail channel networks across North American and European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stone flooring incumbents face sustained substitution pressure from engineered quartz surfaces capturing mid-market residential specification previously held by natural granite and marble tile.
For Market Incumbents: Pre-empt quartz composite encroachment by accelerating backward integration into captive Rajasthan quarry assets with verified EPD documentation for EU-bound supply chains. Invest in CNC texturing and waterjet cutting capabilities to collapse cost differentials against hand-finished artisan competitors. Channel control through direct offtake agreements with Saudi giga-project developers secures volume insulation from spot-market volatility. For New Entrants and Emerging Players: Build out modular prefabrication capacity for floating installation systems targeting North American multi-family housing weight-restricted renovation projects. White-space concentration sits in factory-attached underlayment production for European commercial developers facing skilled labor scarcity. Go-to-market execution should anchor in direct specification relationships with boutique hospitality designers in Milan and Miami seeking machined custom textures. For Investors and Strategic Acquirers: Long-term, this sits as a traceability-infrastructure consolidation play because EU Green Deal carbon border adjustments and blockchain-verified procurement clauses are marginalizing processors lacking in-house sustainability audit capabilities. Acquisition targets center on mid-tier Rajasthan fabricators with quarry management systems primed for ERP integration with customer-facing portals. Watch for inflection when BIS certification backlogs trigger consolidation among exporters unable to launch new quarry sources within standard product development timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Quarry Asset Acquisition | Captive mineral reserves in Rajasthan and Galicia secure volume consistency for EU and Gulf project contracts. |
| EPD Certification Investment | Third-party verified extraction emissions documentation unlocks REACH-compliant European hospitality procurement channels. |
| Modular Prefabrication Scale-Up | Factory-attached underlayment production lines penetrate multi-family housing weight-restricted specification segments. |
| Digital Traceability Infrastructure | Blockchain-verified chain-of-custody portals satisfy London and Singapore commercial project contract conditions. |
| CNC Texturing Capability Expansion | Waterjet and CNC machining collapses cost premiums against hand-finished artisan competitors in boutique hospitality. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with quarry operators, fabrication plant managers, European procurement officers at hotel chains, and Dubai-based project developers; and secondary validation through customs trade records, BIS certification databases, EU Construction Products Regulation amendments, and SEC filings from publicly traded flooring distributors. Bottom-up triangulation across quarry output estimates, slab processing volumes, and end-use project pipelines was cross-checked against top-down market sizing derived from construction spend allocation and material substitution elasticities.
Forecast inputs considered product type segmentation across marble, granite, slate, and limestone; installation methodology evolution from mortar bed toward thin-set and floating systems; surface finish technology displacement of hand-polishing by CNC machining; and regional regulatory divergence between EU carbon border adjustments and Gulf project finance absorption capacity. CAGRs were derived from elasticity modeling across construction verticals and material substitution dynamics. Quarry rehabilitation investment cycles and skilled craftsperson retirement demographics provided industry-specific forecast anchors throughout the projection horizon.
Stress conditions across monsoon disruption severity, silica compliance enforcement intensity, and engineered quartz price erosion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pace and Saudi giga-project tender schedules. Material shifts in REACH compliance cost pass-through structures or OSHA enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
Global Flooring Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Floor Covering Market