
 North America Vinyl Flooring Market | 2026-2036
North America Vinyl Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vinyl Flooring Market Intelligence
Aftermarket service revenue from commercial floor maintenance and replacement cycles is fragmenting across independent contractors and manufacturer-certified installer networks. Mohawk Industries leverages captive distribution to sustain margin capture in the luxury vinyl tile segment. Shaw Industries Group Inc. anchors its position through backward integration into PVC resin sourcing and extrusion capacity. Mannington Mills Inc. differentiates via Made-in-USA positioning and rapid domestic fulfillment.
North America vinyl flooring comprises synthetic polymer floor coverings manufactured from polyvinyl chloride resins combined with plasticizers, stabilizers, and print layers, typically produced through calendering or extrusion processes to achieve wear layers between 6 mil and 20 mil thickness. Luxury vinyl tile and vinyl plank categories command the dominant share of value pools as rigid-core constructions displace traditional sheet vinyl in residential and light commercial applications. Click lock installation systems are capturing share from glue-down methods in the residential end user segment due to reduced labor cost and faster project completion.
The EPA enforces formaldehyde emission standards under TSCA Title VI that directly constrain adhesive and core layer formulations used in domestic manufacturing. California Air Resources Board regulations extend beyond federal baselines, creating a bifurcated compliance landscape that elevates costs for products sold into the state. OSHA workplace exposure limits during installation affect contractor preferences toward low-VOC adhesive systems and floating floor methods. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and federal infrastructure spending allocation patterns that reshape commercial construction pipelines.
Market Dynamics
Waterproof rigid-core vinyl plank technology is compressing installation timelines and redirecting specification decisions across multi-family housing developments in the United States and Canada.
Growth Catalysts
- California Title 24 building energy standards:These regulations mandate thermal performance thresholds that favor insulated underlayment systems paired with rigid-core vinyl, expanding specification in new residential construction.
- Multi-family housing developers:Waterproof SPC and WPC constructions are capturing specification share in Texas, Florida, and Georgia apartment complexes due to moisture resistance and reduced maintenance liability.
- Click-lock installation systems:Floating floor methods are displacing glue-down approaches in residential renovation projects, cutting labor costs and shortening project completion windows.
Market Restraints
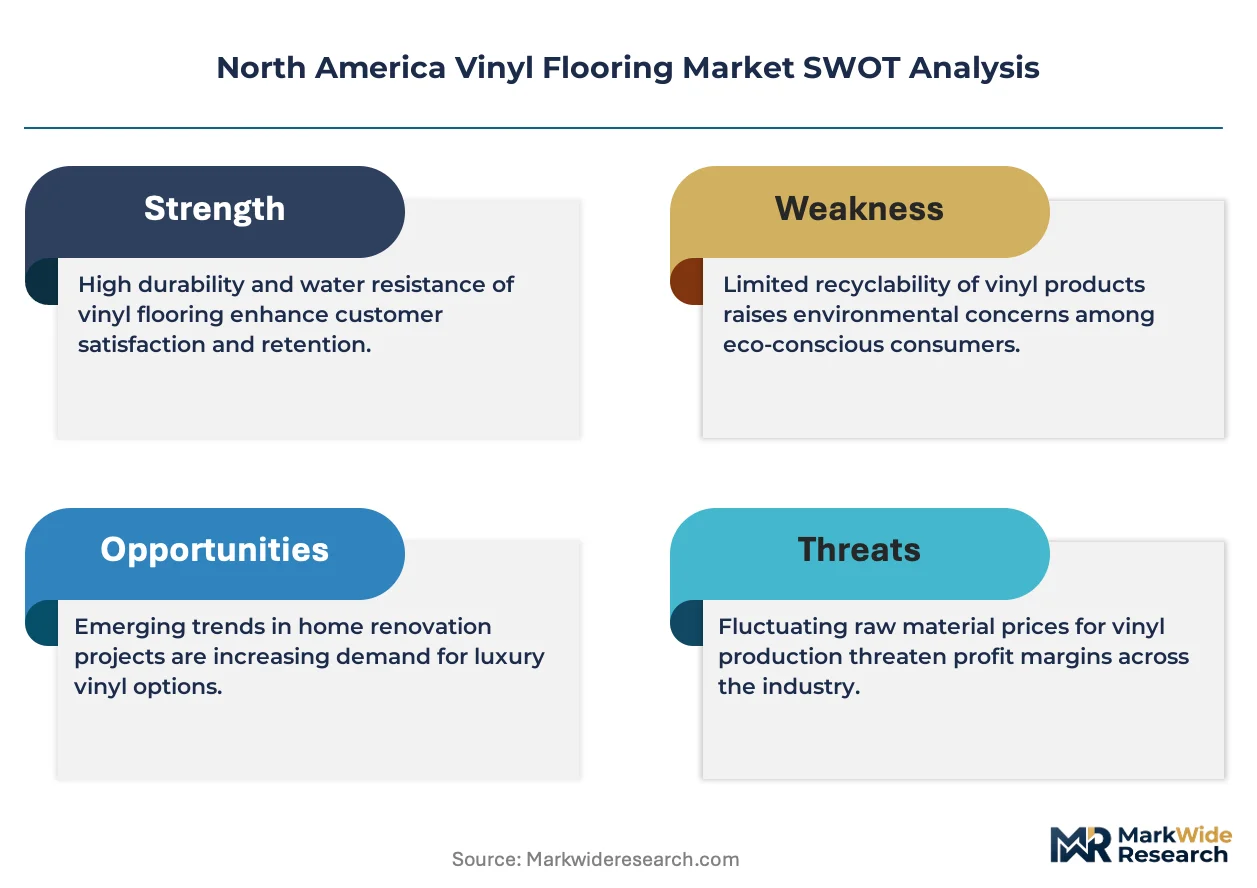
- PVC resin price volatility:Feedstock fluctuations in ethylene and chlorine markets compress margin predictability for domestic extrusion operations.
- EPA TSCA Title VI compliance costs:Formaldehyde emission testing and certification requirements elevate per-SKU regulatory burden for adhesive-dependent product lines.
- Laminate flooring substitution:Water-resistant laminate constructions at lower price points threaten vinyl plank penetration in entry-level residential segments.
Strategic Opportunities
- Canadian multi-family retrofit market:Aging rental stock in Toronto and Vancouver presents untapped volume for floating-floor LVT replacement cycles.
- Infrastructure spending allocation:Federal commercial construction pipelines in the United States are expanding specification opportunities for healthcare and education verticals.
- Low-VOC adhesive convergence:OSHA workplace exposure limits are accelerating contractor migration toward floating installations and certified low-emission systems.
Industry Challenges
- Installer certification gaps:Manufacturer-certified networks struggle to scale training capacity matching rigid-core product proliferation rates.
- State-level EPR framework fragmentation:Extended producer responsibility proposals in California and New York create divergent compliance roadmaps for national distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vinyl Flooring Market |
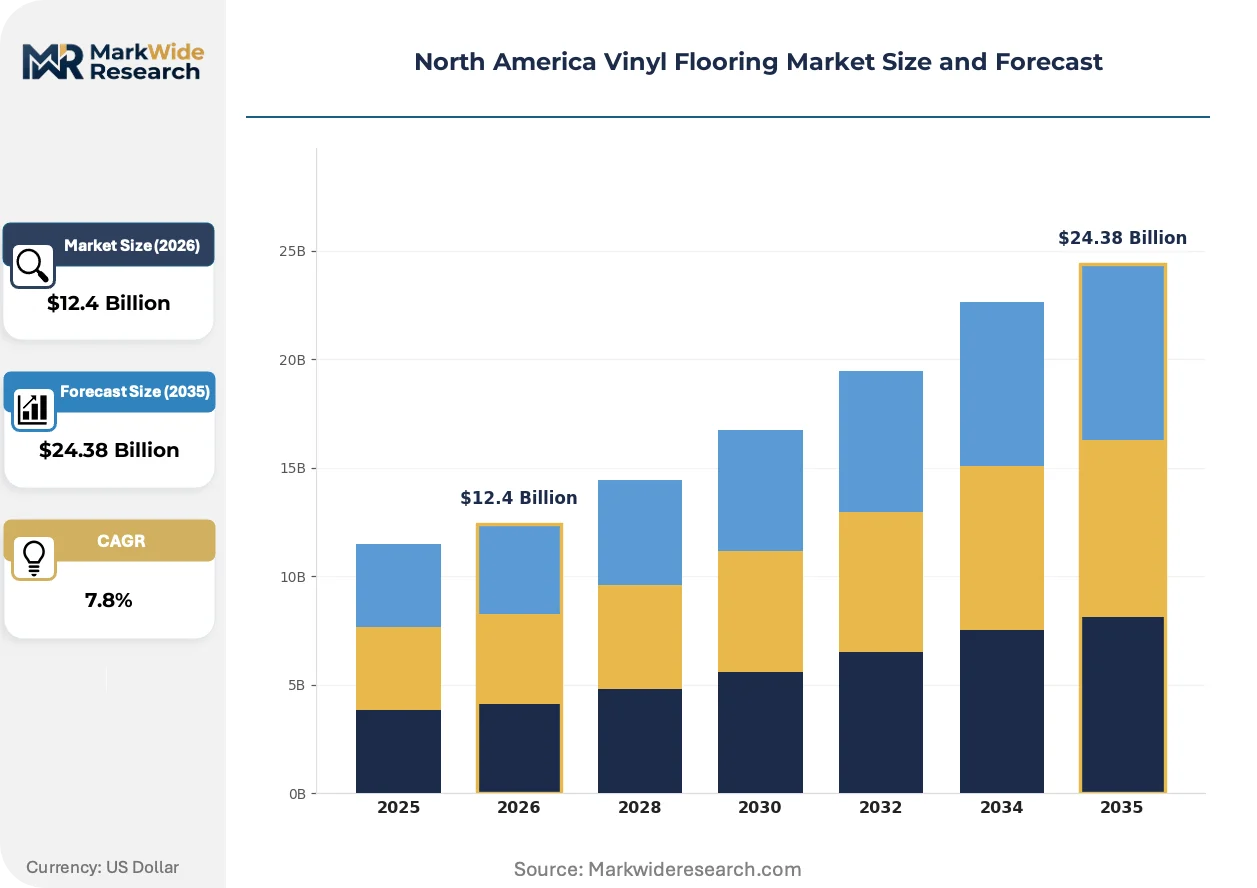
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $24.38 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tile, Vinyl Plank, Sheet Vinyl, Peel & Stick End User: Residential, Commercial, Industrial, Institutional Installation Type: Glue Down, Floating, Click Lock, Loose Lay Thickness: 3mm, 4mm, 5mm, 6mm |
| Companies Covered | Armstrong Flooring, LG Hausys, Mohawk Industries, Mannington Mills Inc., Gerflor, Shaw Industries Group Inc., Interface, American Biltrite, Tarkett, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vinyl Flooring Market Strategic Shifts & Innovations
Digital printing and rigid-core material science are compressing product development cycles and enabling mass-customization at price points previously reserved for commodity sheet goods.
Embossed-in-register surface technology is digitizing texture replication by synchronizing press plates with printed décor layers in real-time production lines. Residential buyers in the southeastern United States are specifying these products for whole-home installations at accelerating rates. The technology is digitizing how manufacturers manage SKU proliferation, compressing minimum order quantities and enabling regional pattern customization without retooling costs.
EPA enforcement of TSCA Title VI formaldehyde standards is tightening adhesive formulation constraints for domestic vinyl flooring manufacturers. Core layer suppliers must certify composite materials through third-party testing protocols, elevating documentation burdens. Products targeting California face additional Air Resources Board requirements, bifurcating compliance strategies between state-specific and national product lines.
Property management procurement teams are consolidating vendor relationships around full-service flooring packages spanning material, installation, and maintenance. Independent contractors are losing share to manufacturer-certified installer networks in the multi-family housing channel. This concentration is most visible in Texas and Florida, where institutional owners prioritize single-source accountability over lowest-bidder segmentation.
North America Vinyl Flooring Market Segmentation
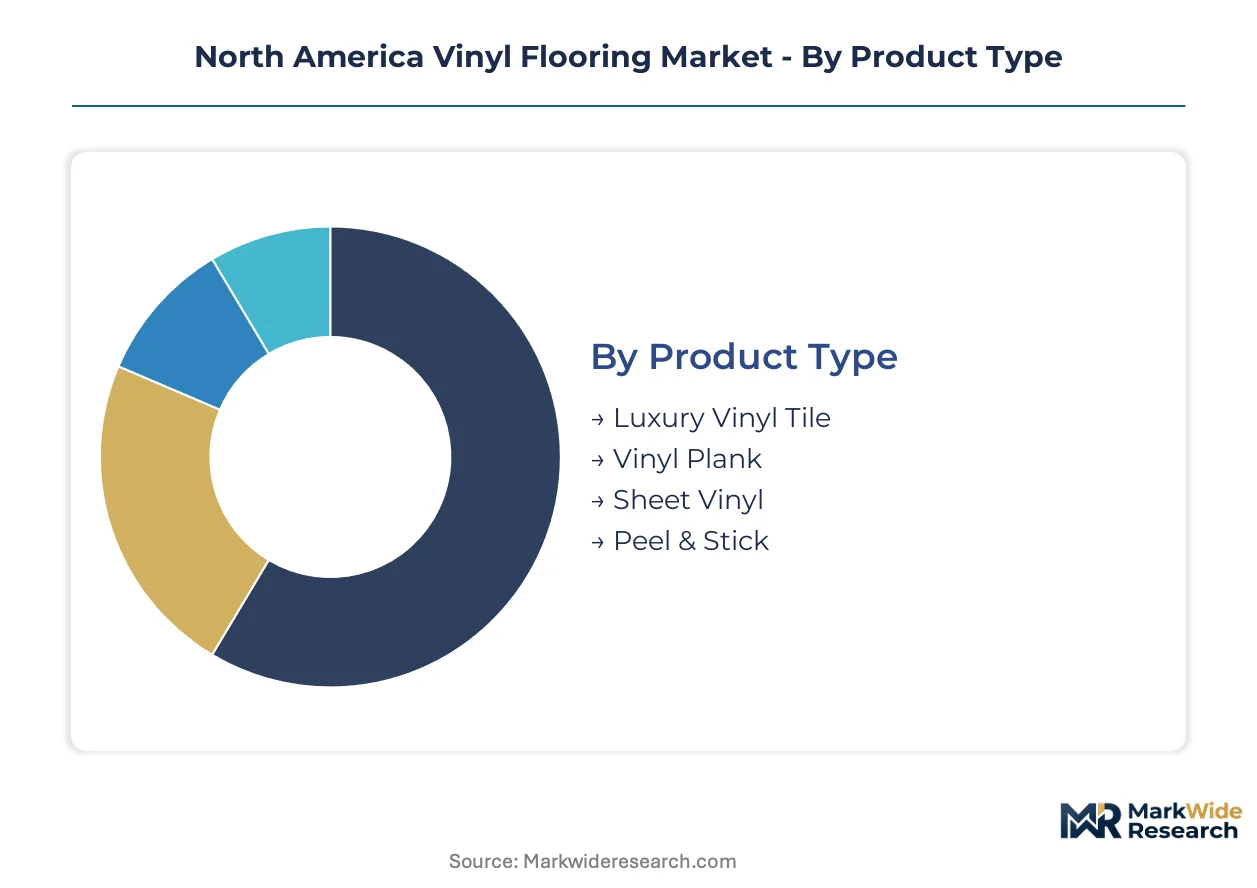
Product architecture and installation method choices in North American vinyl flooring reflect divergent cost structures, labor availability, and performance requirements across residential renovations and commercial new-builds. Specification patterns fragment sharply between floating-floor convenience in multi-family housing and glue-down permanence in healthcare and education verticals.
Product Type:
Residential and commercial buyers navigate a spectrum from premium rigid-core constructions to economy sheet goods based on durability requirements and total installed cost constraints.
- Luxury Vinyl Tile:Rigid-core LVT combines limestone-polymer composite or wood-plastic composite cores with high-definition printed décor layers and aluminum oxide wear layers. Texas and Florida multi-family developers specify these products for whole-unit installations where moisture resistance and rapid click-lock installation compress project timelines.
- Vinyl Plank:Extended plank formats replicate hardwood dimensions through extruded or calendered construction with embossed-in-register surface texturing. Georgia residential builders favor 7-inch and 9-inch widths for single-family spec homes where visual authenticity commands buyer premiums.
- Sheet Vinyl:Continuous roll goods manufactured through calendering processes achieve seamless moisture barriers for healthcare and institutional wet areas. California Title 24 compliance favors these products paired with insulated underlayment systems.
- Peel & Stick:Self-adhesive backing eliminates specialized installation equipment for DIY renovation segments. Entry-level residential applications in southeastern states absorb volume where labor cost sensitivity peaks.
The dominant share belongs to Luxury Vinyl Tile, while Vinyl Plank is closing the gap fastest.
End User:
Customer archetypes separate by project scale, maintenance liability tolerance, and specification authority concentration.
- Residential:Single-family owners and multi-family property managers drive specification toward waterproof rigid-core products with 20-year residential warranties. Click-lock floating systems dominate renovation activity where subfloor preparation costs deter glue-down methods.
- Commercial:Retail, hospitality, and office tenants prioritize 28 mil+ wear layers and rapid replacement cycles for high-traffic zones. Property management procurement teams in Texas and Florida consolidate vendor relationships around full-service flooring packages.
- Industrial:Manufacturing and warehousing facilities demand chemical-resistant surfaces with static-control properties. Epoxy-modified vinyl compositions address these requirements where OSHA workplace exposure limits influence material selection.
- Institutional:Healthcare and education verticals specify slip-resistant surfaces with antimicrobial additives. Federal infrastructure spending pipelines expand specification opportunities for these segments.
Residential commands the volume base, yet Commercial is expanding most quickly as property management procurement consolidates.
Installation Type:
Labor cost structures and subfloor condition variability dictate method selection across project types.
- Glue Down:Full-spread adhesive application achieves permanent bond for commercial high-traffic zones and rolling load requirements. EPA TSCA Title VI formaldehyde emission standards constrain adhesive formulation options and elevate compliance documentation burdens.
- Floating:Interlocking perimeter systems accommodate subfloor irregularity without adhesive or mechanical fastening. Multi-family housing developers in Georgia specify these methods to minimize maintenance liability and accelerate unit turnover.
- Click Lock:Precision-milled joint systems enable tool-free assembly with vertical and horizontal locking mechanisms. Residential renovation contractors prefer these systems for same-day project completion.
- Loose Lay:Friction-fit and perimeter-weighted systems eliminate adhesive entirely for temporary or rapid-replacement applications. Commercial tenants with short lease terms favor this flexibility.
Floating installations hold the largest share, though Click Lock is gaining share fastest among residential renovation specialists.
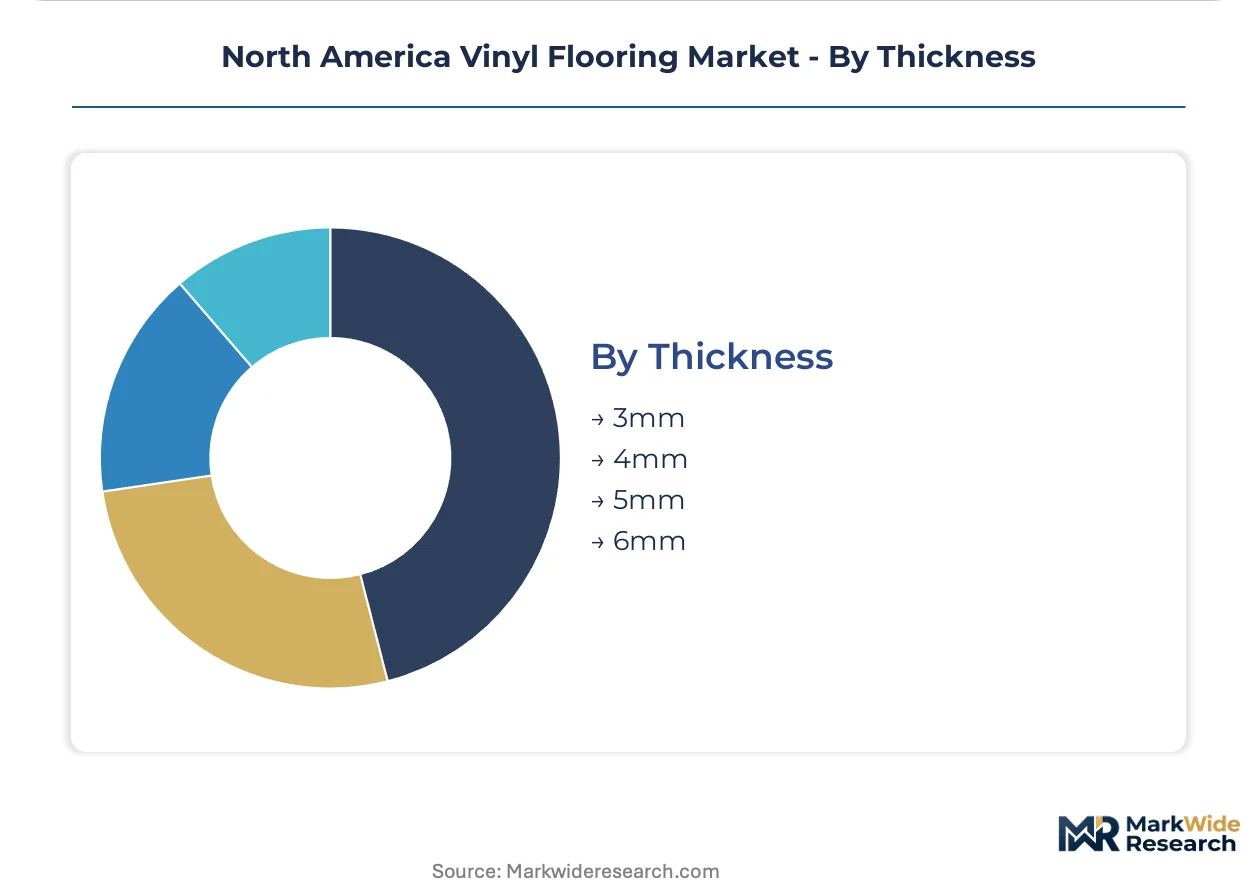
Thickness:
Core dimension correlates directly with impact resistance, acoustic performance, and subfloor tolerance specifications.
- 3mm:Thin-profile products target budget residential renovations with well-prepared subfloors. Peel-and-stick and loose-lay methods accommodate these specifications.
- 4mm:Mid-range rigid-core constructions balance material cost with sufficient dimensional stability for residential floating installations. California Title 24 thermal performance thresholds favor these products paired with insulated underlayment.
- 5mm:Enhanced core thickness accommodates moderate subfloor irregularity without additional preparation. Multi-family housing developers specify these dimensions for cost-optimized durability.
- 6mm:Maximum core dimension delivers acoustic dampening and impact resistance for commercial and institutional applications. Healthcare and education verticals prioritize these specifications for occupant comfort and long service life.
The 4mm specification dominates residential volume, while 5mm is climbing the fastest as multi-family developers optimize cost-durability tradeoffs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the southeastern United States demonstrate the highest price elasticity, squeezing margins on entry-grade rigid-core products, while Canadian institutional purchasers absorb premium specifications with minimal volume sensitivity. This demand-elasticity contrast shapes regional production allocation and distribution network density across North America.
United States
Multi-family housing developers in Texas, Florida, and Georgia drive specification of waterproof SPC and WPC constructions for apartment complexes. EPA TSCA Title VI formaldehyde emission standards constrain adhesive formulation options for domestic manufacturers. Dallas-Fort Worth and Atlanta metropolitan clusters concentrate distribution hubs serving the fastest-growing residential construction sub-markets.
Canada
Aging rental stock in Toronto and Vancouver generates replacement demand for floating-floor LVT systems in multi-family retrofits. Health Canada and PMRA regulations govern chemical emissions and antimicrobial claims in flooring products. Montreal-area manufacturing facilities supply Quebec and Ontario markets with rapid domestic fulfillment capabilities.
Mexico
Industrial facility construction in Nuevo León and the Bajío Region absorbs chemical-resistant vinyl compositions for manufacturing and warehousing applications. Mexican federal environmental standards under SEMARNAT align with North American harmonized protocols for VOC emissions. Mexico City metropolitan procurement teams specify slip-resistant surfaces for healthcare and education verticals receiving federal infrastructure allocations.
North America Vinyl Flooring Market Key Industry Players
Vertically integrated conglomerates and specialized domestic fabricators split the market along capability and geographic coverage vectors. Three archetypes dominate: diversified flooring conglomerates with captive resin supply, mid-scale regional specialists emphasizing Made-in-USA positioning, and import-dependent distributors competing on price. Consolidation pressure intensifies through backward integration into PVC extrusion capacity and manufacturer-certified installer network expansion.
Among diversified flooring conglomerates, Mohawk Industries, Shaw Industries Group Inc., and Mannington Mills Inc. exemplify strategic archetypes differentiated by supply chain control and domestic fulfillment speed. Mohawk leverages captive distribution infrastructure to sustain margin capture in luxury vinyl tile segments. Shaw anchors market position through upstream control over PVC resin sourcing and extrusion operations. Mannington occupies a specialist position emphasizing rapid domestic fulfillment and Made-in-USA manufacturing credentials.
| Leading Market Players |
|---|
| Armstrong Flooring |
| LG Hausys |
| Mohawk Industries |
| Mannington Mills Inc. |
| Gerflor |
| Shaw Industries Group Inc. |
| Interface |
| American Biltrite |
| Tarkett |
| Others |
Cost & Logistics Intelligence
Dalton, Georgia and the surrounding carpet corridor concentrate North American vinyl flooring extrusion capacity, with resin compounding and wear-layer coating operations clustered within 150 miles of distribution hubs serving Texas and Florida. This geographic density grants incumbent manufacturers freight-cost advantages that compress delivered pricing for multi-family housing developers while elevating barriers for distant competitors.
Pricing Analysis
Aftermarket service revenue from commercial floor maintenance contracts and replacement cycle management drives lifetime value capture for manufacturer-certified installer networks. Three-tier pricing structure across premium, standard, and economy levels separates rigid-core LVT with 20-mil wear layers from entry-grade peel-and-stick products. Price differentiation rests on certification grade for EPA TSCA Title VI compliance and California Air Resources Board thresholds. Cost compression in the entry-grade tier is intensifying because laminate flooring substitutes at lower price points threaten vinyl plank penetration. Multi-family housing developers in the southeastern United States demonstrate the highest price sensitivity, while Canadian institutional purchasers absorb premium specifications with minimal volume elasticity.
Supply Chain Analysis
Contract manufacturing concentration among domestic extrusion specialists in Georgia, Texas, and South Carolina holds the majority of rigid-core SPC and WPC capacity. Geographic supply concentration centers on the United States for finished goods, with PVC resin feedstock drawing from domestic ethylene crackers and chlorine production along the Gulf Coast. Raw material dependencies rest on plasticizer stabilizers, aluminum oxide wear-layer additives, and limestone-polymer composite core materials. Single-source vulnerability in specialized embossing equipment for embossed-in-register surface technology presents structural risk. Distribution runs through manufacturer-direct channels to large multi-family developers and wholesale distribution to independent retailers serving residential renovation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rigid-core waterproof technology is compressing installation timelines and redirecting specification decisions, positioning the market for early-cycle expansion as multi-family housing developers accelerate adoption of floating-floor systems.
For Market Incumbents: Insulate margin position by deepening captive control over PVC resin sourcing and extrusion capacity in the southeastern United States. Accelerate manufacturer-certified installer network expansion to capture aftermarket service revenue from commercial replacement cycles. Water-resistant laminate substitutes at lower price points threaten entry-grade vinyl plank volume, making certification investment for EPA TSCA Title VI and California Air Resources Board compliance a critical lever for premium-tier defense. For New Entrants and Emerging Players: Canadian multi-family retrofit markets in Toronto and Vancouver represent the most penetrable entry point, with aging rental stock generating replacement demand for floating-floor LVT systems underserved by incumbent distribution density. Infrastructure spending pipelines for healthcare and education verticals present specification opportunities where federal allocation patterns favor rapid domestic fulfillment. A go-to-market angle anchored on low-VOC adhesive systems and OSHA-compliant floating installation methods addresses contractor migration trends. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated fabricators with backward integration into resin sourcing and rapid domestic fulfillment capabilities. Long-term viability across the five-to-ten-year window rests on scale advantages in embossing-in-register surface technology and SKU proliferation management. The acquisition target archetype combines regional manufacturing presence with certified installer network scale. The signal to watch is state-level extended producer responsibility framework adoption in California and New York, which would bifurcate compliance strategies and elevate consolidation pressure on national distribution strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin Sourcing | Captive supply of ethylene-based feedstock insulates margin from petrochemical volatility. |
| Manufacturer-Certified Installer Network Expansion | Aftermarket service revenue capture displaces independent contractors in multi-family channels. |
| Embossed-in-Register Production Line Investment | Real-time texture synchronization enables mass-customization without retooling cost penalties. |
| Low-VOC Adhesive System Certification | OSHA workplace exposure compliance accelerates contractor preference for certified installation methods. |
| Regional Distribution Hub Concentration | Dalton and Dallas-Fort Worth proximity compresses freight cost to Texas and Florida construction markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association publications, and customs data. Primary interviews engaged product managers at vinyl flooring manufacturers, procurement directors at multi-family housing developers, certified installation contractors, and distribution channel partners. Secondary validation drew from EPA TSCA Title VI certification databases, California Air Resources Board compliance listings, and SEC filings of publicly traded flooring conglomerates. Bottom-up volume estimates from product-type and installation-method segments were triangulated against top-down construction spending allocations.
Forecast inputs include residential renovation activity indices, multi-family housing permit data, and commercial construction pipeline tracking. Segmentation dimensions modeled span product architecture, installation method, core thickness, and end-user vertical across the projection horizon. CAGRs were derived from regression analysis of historical volume patterns against macroeconomic drivers. Industry-specific forecast inputs incorporate PVC resin price indices and evolving formaldehyde emission standard enforcement intensity.
Stress conditions across ethylene feedstock volatility, EPA enforcement intensity, and laminate substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory stability and construction spending continuity. Quarterly review of multi-family housing permit trends and state-level extended producer responsibility legislative movement is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market