
 Global Floor Covering Market | 2026-2036
Global Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Global Floor Covering Market Foresight
Healthcare facility refurbishment is expanding as a priority vertical, with hospitals and clinics specifying antimicrobial, slip-resistant surfaces for patient safety zones. Mohawk Industries anchors North American manufacturing scale across broadloom carpet and resilient tile categories. Tarkett SA differentiates through bio-based vinyl formulations and closed-loop recycling infrastructure in European operations. Interface leads modular carpet tile innovation with carbon-neutral product lines targeting corporate sustainability mandates.
Floor covering encompasses finished surface materials installed over structural subfloors to provide wear resistance, thermal insulation, acoustic dampening, and aesthetic finish in built environments; products range from 2 mm vinyl sheets to 19 mm engineered hardwood planks, with wear-layer thickness and density ratings determining commercial versus residential suitability. Laminate and vinyl product types capture volume leadership in mass residential markets due to cost efficiency and moisture tolerance, while hardwood commands premium positioning in renovation segments where natural material authenticity drives specification. Ceramic tiles dominate wet-area applications across hospitality and healthcare installations, with large-format porcelain gaining share for seamless aesthetic and reduced grout maintenance.
The EPA's VOC emissions standards for composite wood products and California's CDPH Section 01350 indoor air quality protocols constrain adhesive and substrate formulations in US-bound supply chains. REACH chemical restrictions and CE marking requirements under the EU Construction Products Regulation shape material composition decisions for European market access. Stakeholders must monitor evolving carbon border adjustment mechanisms and building-level embodied carbon accounting standards that will increasingly determine product competitiveness across specification channels.
Market Dynamics
Building-level embodied carbon accounting is compressing specification timelines and forcing material transparency across the entire floor covering value chain. Specifiers now demand Environmental Product Declarations before shortlisting suppliers, reshaping competitive access to commercial and institutional projects.
Growth Catalysts
- EU Green Deal renovation mandates:The EU Green Deal's building renovation targets are redirecting public and private procurement toward certified sustainable materials, expanding addressable market for low-carbon flooring systems in member states.
- Healthcare facility refurbishment:Hospitals and clinics are specifying antimicrobial, slip-resistant surfaces for patient safety zones, creating dedicated demand verticals with higher specification standards and margin structures.
- Urban housing stock modernization:China, India, and Brazil are concentrating demand as metropolitan real estate development accelerates and residential renovation activity expands across their major corridors.
Market Restraints
- Petrochemical input volatility:Vinyl and synthetic carpet production remains exposed to ethylene and propylene price swings, compressing margin predictability for manufacturers without backward integration into resin supply.
- REACH chemical restrictions:ECHA's evolving substance restrictions on phthalates and heavy metal stabilizers force continuous formulation reformulation, creating compliance lag for suppliers serving European markets.
- Technical performance ceiling in wet areas:Laminate and engineered wood products face inherent moisture tolerance limitations that ceramic tile and luxury vinyl tile exploit, constraining share expansion in hospitality and healthcare wet zones.
Strategic Opportunities
- Carbon border adjustment mechanisms:Emerging EU carbon border tariffs on imported building materials will advantage domestic and near-shore manufacturers with verified low-emission production processes.
- Closed-loop recycling infrastructure:European operations are pioneering take-back programs and chemical recycling for vinyl flooring, creating service-based revenue streams and regulatory preference in public tenders.
- Corporate sustainability mandates:Fortune 500 headquarters and tech campus projects are specifying carbon-neutral product lines, opening premium specification channels for manufacturers with verified lifecycle data.
Industry Challenges
- EPD certification timeline compression:Third-party verified Environmental Product Declarations require 6-12 month validation cycles that lag behind project bid deadlines, forcing speculative pre-certification investments.
- Installation skill fragmentation:Large-format porcelain and rigid core vinyl planks demand specialized substrate preparation and leveling competencies that contractor networks lack at scale, generating warranty disputes and callback costs.
- Legacy adhesive compatibility:New low-VOC substrate formulations face bonding failures with existing installation chemistries, requiring system-level testing that extends product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Floor Covering Market |
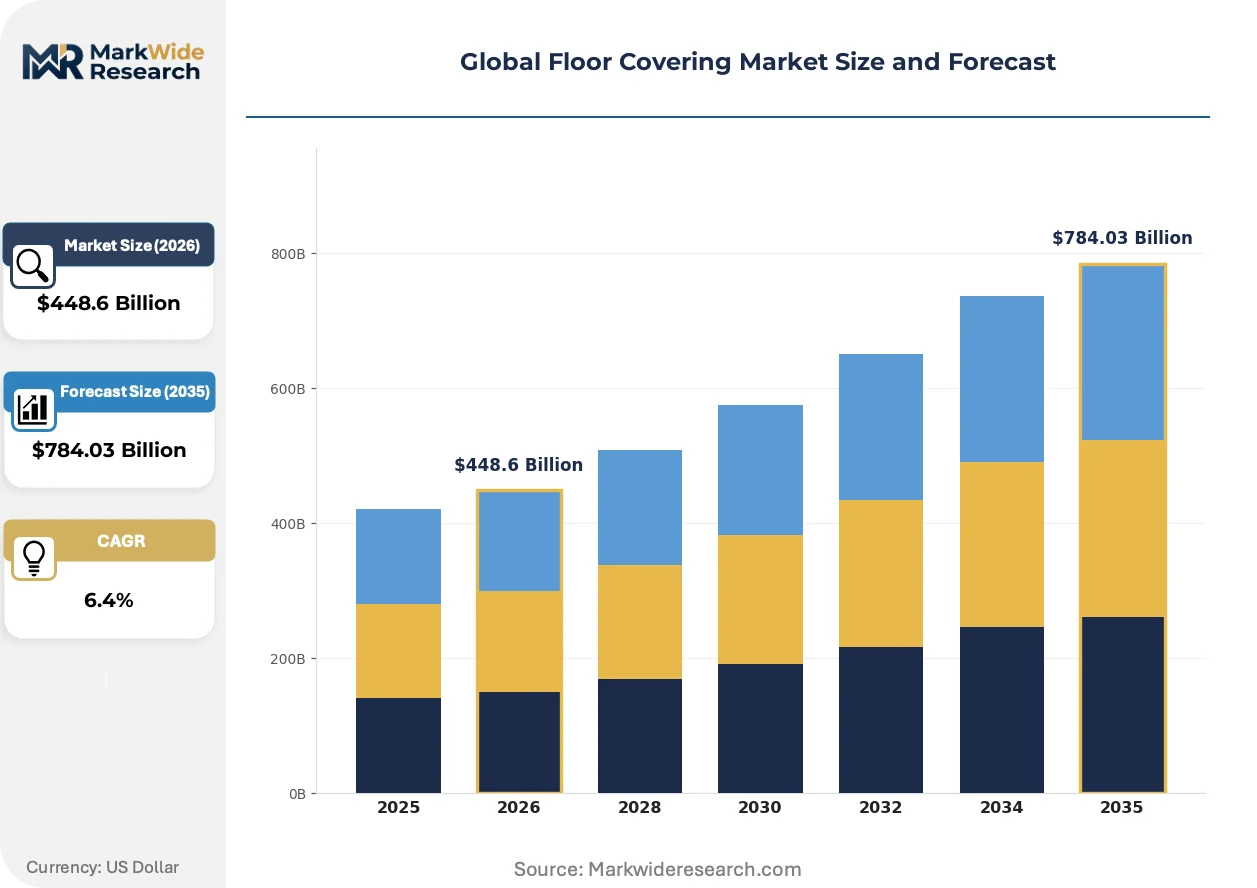
| Market Size in 2026 | $448.6 Billion |
| Market Size in 2035 | $784.03 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminate, Vinyl, Hardwood, Ceramic Tiles, Bamboo, Cork Installation Type: Glue Down, Click Lock, Floating, Nail Down, Peel & Stick Application: Commercial Spaces, Residential Units, Hospitality, Educational Institutions, Healthcare Facilities End User: Contractors, Interior Designers, Facility Managers, Property Developers, Retailers |
| Companies Covered | Interface, Mannington Mills, Mohawk Industries, Gerflor, Forbo Flooring Systems, Shaw Industries Group, Armstrong Flooring, Beaulieu International Group, Tarkett SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Floor Covering Market Shifts & Advancements
Digital specification tools and material science advances are collapsing the traditional divide between aesthetic preference and performance verification. Buyers now expect real-time carbon data and virtual sampling before physical procurement.
Digital printing technology is converging with high-definition surface embossing to replicate natural material grain structures on ceramic, vinyl, and laminate substrates. Hospitality designers and residential developers are adopting these products at accelerating rates to achieve authentic wood and stone aesthetics without natural material maintenance burdens. This convergence is compressing the premium positioning of solid hardwood and natural stone in renovation markets where performance durability outweighs material authenticity.
California's CDPH Section 01350 indoor air quality protocols are constraining adhesive and substrate formulations in US-bound supply chains. Manufacturers serving California projects must reformulate across entire product lines to meet VOC emissions standards, creating compliance bifurcation between California-compliant and standard product portfolios. Commercial office and healthcare segments in the state are driving fastest adoption of certified low-emission systems.
Building information modeling is reshaping how architects and contractors source floor covering materials, with specification decisions increasingly occurring within digital twin environments before physical sampling. Distributors and manufacturers are deploying virtual showrooms and augmented reality visualization tools that displace traditional branch-based selection processes. This behavioral shift is most visible in North American and Western European commercial projects where design-build delivery methods dominate procurement.
Global Floor Covering Market Segmentation
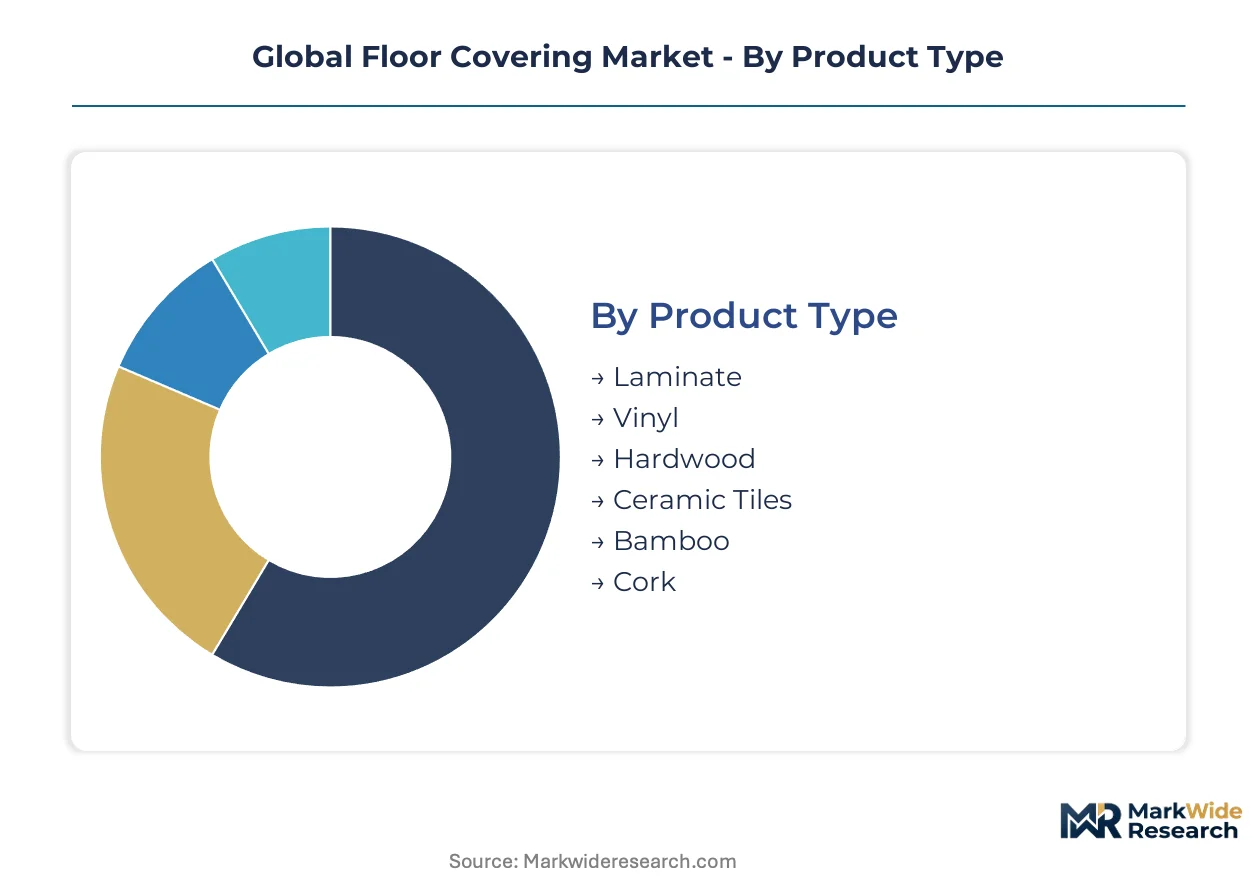
Floor covering procurement hinges on performance specifications that vary dramatically across installation environments and buyer types. Segmentation reveals how material selection criteria diverge between cost-driven residential renovation and compliance-heavy institutional specification. Understanding these fault lines enables targeted positioning across divergent margin structures and decision timelines.
Product Type:
Cost tier drives initial shortlisting, with wear-layer durability and moisture tolerance filtering final selection in commercial applications.
- Laminate:Multi-layer synthetic construction with high-density fiberboard core and photographic wear layer replicates wood aesthetics at reduced material cost. Residential renovation in Germany and France favors laminate for rental property refresh cycles where capital recovery timelines compress specification budgets.
- Vinyl:PVC-based resilient flooring spans sheet, tile, and luxury vinyl plank formats with superior moisture resistance and acoustic dampening. Healthcare facilities in the United States specify vinyl for patient safety zones requiring antimicrobial additives and slip-resistant embossing.
- Hardwood:Solid and engineered timber products command premium positioning through natural material authenticity and refinishing longevity.
- Ceramic Tiles:Fired clay and porcelain formats dominate wet-area applications with impervious surface characteristics and thermal mass benefits.
- Bamboo:Grass-based alternative to hardwood offers rapid renewability and comparable tensile strength for sustainability-focused specifications.
- Cork:Harvested bark material delivers natural acoustic insulation and thermal cushioning for specialized residential and commercial environments.
Vinyl leads on scale across mass residential and institutional channels; bamboo leads on momentum as EU Green Deal procurement expands bio-based material mandates.
Installation Type:
Application context dictates method selection, with substrate condition and project timeline compressing options in renovation versus new construction.
- Glue Down:Full-spread adhesive application creates permanent bond suited to heavy commercial traffic loads and rolling equipment. Healthcare and hospitality installations in Italy and Spain specify glue-down vinyl for dimensional stability under continuous cleaning protocols and point-load stress.
- Click Lock:Mechanical joining system enables floating installation without adhesives, accelerating project completion and reducing skilled labor dependency. Residential developers in China deploy click-lock laminate and rigid core vinyl across high-volume housing stock modernization projects.
- Floating:Interlocking plank or tile systems rest on underlayment without substrate attachment, accommodating subfloor irregularity.
- Nail Down:Traditional hardwood fastening method requires plywood or wood subfloor and specialized carpentry competency.
- Peel & Stick:Pressure-sensitive adhesive backing enables rapid deployment for temporary installations and budget-constrained refresh projects.
Click lock leads on scale through residential volume penetration; glue down leads on momentum as commercial specification tightens performance warranties.
Application:
Traffic intensity and regulatory exposure segment demand, with healthcare and hospitality commanding premium certification requirements.
- Commercial Spaces:Office, retail, and mixed-use environments specify for durability under variable foot traffic and furniture loading. Corporate headquarters in California and New York prioritize low-VOC systems meeting CDPH Section 01350 protocols for indoor air quality compliance.
- Residential Units:Single-family and multifamily housing drives volume through renovation cycles and new construction completions.
- Hospitality:Hotels and restaurants balance aesthetic differentiation with stain resistance and acoustic performance for guest experience.
- Educational Institutions:Schools and universities specify for safety, maintainability, and budget predictability across extended facility lifecycles.
- Healthcare Facilities:Hospitals and clinics demand antimicrobial surfaces, slip resistance, and seamless hygiene maintenance.
Residential units lead on scale through housing stock turnover; healthcare facilities lead on momentum as patient safety regulation tightens surface material standards.
End User:
Procurement authority and technical competency fragment the buyer landscape, with specification influence shifting across project phases.
- Contractors:Installation firms control material selection through trade relationships and warranty compatibility requirements. General contractors in Brazil and Mexico leverage volume purchasing agreements to steer project specifications toward stocked inventory and familiar installation systems.
- Interior Designers:Aesthetic and sustainability criteria drive designer influence in premium residential and hospitality segments.
- Facility Managers:Operational lifecycle cost analysis governs replacement and refurbishment decisions in institutional portfolios.
- Property Developers:Capital cost optimization and speed-to-market priorities shape material selection in speculative construction.
- Retailers:Consumer-facing distribution channels influence residential replacement demand through merchandising and financing programs.
Contractors lead on scale through installation-driven specification capture; facility managers lead on momentum as lifecycle cost analytics penetrate institutional procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as manufacturers relocate capacity to jurisdictions with lower carbon compliance costs. The EU carbon border adjustment mechanism will accelerate this migration by penalizing high-emission imports from non-EU sources.
United States
Healthcare facility refurbishment and corporate headquarters construction drive specification demand for low-VOC systems. EPA emissions standards and California CDPH Section 01350 protocols constrain adhesive formulations in supply chains. Dallas-Fort Worth and Atlanta metropolitan corridors concentrate distribution infrastructure for mass residential vinyl and laminate products.
Germany
EU Green Deal renovation mandates redirect public procurement toward certified sustainable materials. REACH chemical restrictions on phthalates force continuous formulation reformulation across product lines. The Rhine-Ruhr industrial cluster anchors European manufacturing scale for resilient flooring and broadloom carpet categories.
China
Urban housing stock modernization and commercial real estate development concentrate demand in major metropolitan corridors. The country's national building materials regulator enforces GB standards for indoor air quality and product safety. Shanghai and Shenzhen manufacturing zones supply global export markets with cost-optimized laminate and vinyl production.
India
Residential renovation activity expands as homeowners prioritize durable, low-maintenance surfaces in tier-1 and tier-2 cities. BIS certification requirements shape quality standards for domestic market access. The Mumbai-Pune and Delhi-NCR corridors concentrate real estate development and associated floor covering procurement.
Brazil
Metropolitan housing modernization and hospitality sector investment create demand for moisture-tolerant ceramic and vinyl systems. ANVISA regulations govern antimicrobial surface claims in healthcare applications. São Paulo state anchors South American manufacturing and distribution infrastructure for resilient flooring categories.
Global Floor Covering Market Competitive Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from core categories into adjacent surface materials. The vendor base organizes around three structural tiers: integrated multinationals with resin-to-retail control, regional specialists with formulation expertise, and private-label fabricators serving price-sensitive channels. Two competitive vectors define current positioning: M&A activity consolidating distribution networks, and capacity expansion into low-carbon production platforms.
Within the integrated multinational tier, Mohawk Industries, Tarkett SA, and Interface exemplify divergent strategic archetypes. Mohawk Industries represents North American manufacturing scale across broadloom carpet and resilient tile categories. Tarkett SA anchors European operations with bio-based vinyl formulations and closed-loop recycling infrastructure. Interface occupies a position in modular carpet tile innovation with carbon-neutral product lines targeting corporate sustainability mandates.
| Leading Market Players |
|---|
| Interface |
| Mannington Mills |
| Mohawk Industries |
| Gerflor |
| Forbo Flooring Systems |
| Shaw Industries Group |
| Armstrong Flooring |
| Beaulieu International Group |
| Tarkett SA |
| Others |
Supply & Pricing Matrix
EU Green Deal renovation mandates gate qualified supply and premium-tier pricing access by requiring Environmental Product Declarations and verified low-carbon production processes for public procurement eligibility. Manufacturers without certified lifecycle data face exclusion from institutional specification channels where margin structures compress toward commodity levels.
Pricing Analysis
Distributor margin layers separate project-based contract pricing from retail markups in residential channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and wear-layer durability specifications. Cost compression in mass-market vinyl runs through ethylene price volatility and Asian import competition. Facility managers in institutional portfolios exhibit lowest price sensitivity due to lifecycle cost analytics, while residential renovators in tier-2 cities drive volume through promotional financing.
Supply Chain Analysis
Workforce availability constraints in Shanghai and Shenzhen manufacturing zones limit capacity expansion for laminate and vinyl exports. Production concentrates in China, Germany, and the United States, with raw material dependencies on PVC resin, titanium dioxide pigments, and limestone filler. Single-source vulnerability in phthalate-free plasticizer formulations creates compliance lag for European market access. Distribution runs through specialized flooring distributors and big-box retail networks with regional stocking requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in carbon-neutral product lines where corporate sustainability mandates justify premium positioning above commodity flooring tiers.
For Market Incumbents: Hedge against REACH chemical restriction acceleration by accelerating bio-based formulation R&D and securing alternative plasticizer supply agreements. Backward integration into recycled content streams defends margin position against virgin resin price swings. Certification investment in EPD pre-validation compresses bid timelines for EU public tenders. For New Entrants and Emerging Players: Direct-to-contractor digital platforms bypass established distributor relationships in residential renovation segments. White-space targets include antimicrobial vinyl systems for outpatient clinic chains and rigid core products for multifamily housing developers in India and Brazil. Specification capture through virtual showroom deployment accelerates trial before physical sampling investment. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with formulation expertise but limited EPD certification infrastructure. Long-term viability hinges on carbon border adjustment mechanism preparedness across the projection horizon. Acquisition targets include European operations with closed-loop recycling infrastructure and verified low-emission production data. Watch for EU carbon border tariff implementation timing as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| EPD Pre-Certification Investment | Accelerates specification access for EU Green Deal public procurement mandates. |
| Bio-Based Formulation Transition | Reduces REACH compliance exposure while capturing premium sustainability positioning. |
| Closed-Loop Recycling Infrastructure | Creates service revenue streams and regulatory preference in European tenders. |
| Digital Specification Platform Launch | Displaces traditional branch-based selection in North American commercial projects. |
| Regional Manufacturing Footprint Expansion | Mitigates carbon border tariff exposure through near-shore production qualification. |
Research Methodology
Multiple input streams — primary interviews with flooring procurement managers, distributor operations heads, and facility management directors; secondary validation through customs trade data, EPA emissions filings, and EU Construction Products Regulation databases; plus industry association production statistics — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification decision criteria across healthcare, hospitality, and corporate office verticals. Secondary sources included REACH substance restriction updates, CDPH Section 01350 protocol documentation, and national building materials regulator filings in China and India.
Historical volume trajectories were cross-referenced against panel input from manufacturing executives and commercial contractors to anchor growth assumptions across the analysis window. Segmentation modeling incorporated product type, installation method, application environment, and end-user procurement authority dimensions. CAGRs were derived from fitted trend analysis adjusted for regulatory intervention timing and housing stock turnover cycles. Forecast inputs included urbanization rates in target metropolitan corridors and embodied carbon accounting standard adoption curves.
The model assumes a particular technology adoption path; alternative pathways for digital specification tools and chemical recycling scale-up would alter the outlook. Forecasts reflect assumptions regarding EU carbon border mechanism implementation scope and California indoor air quality protocol expansion to additional states. Material deviation in these regulatory triggers or petrochemical input cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Fiberglass Flooring Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
Hard Surface Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
United States Floor Covering Market