
 Europe Carpet and Rugs Market | 2026-2036
Europe Carpet and Rugs Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Carpet and Rugs Market Foresight
A capital-intensity divergence between integrated fiber producers and asset-light importers is unwinding competitive stability across the European floor covering trade. Mohawk Industries leverages its captive nylon extrusion capacity to anchor margin control across tufted broadloom lines. Fletco Carpets competes through regional weaving clusters in Denmark, while Balta Group dominates Belgian distribution networks into French retail channels.
Carpets and rugs comprise textile floor coverings manufactured through tufting, weaving, knotting, or felting processes, with pile weights typically ranging from 16 to 48 ounces per square yard depending on end-use durability requirements. Tufted constructions sustain volume leadership across European residential replacement cycles due to mechanized production speed, while woven Axminster and Wilton formats retain premium positioning in London hospitality refurbishment. Wool material grades command specification loyalty among heritage commercial interiors, though recycled PET polyester is displacing virgin polymer in Nordic public sector tenders.
The EU Green Deal's product environmental footprint rules, REACH chemical restrictions, and France's AGEC anti-waste law collectively reshape material compliance costs and design-for-recycling obligations across the value chain. ECHA's evolving restrictions on per- and polyfluoroalkyl substances threaten stain-resistant treatment formulations, forcing reformulation investments ahead of enforcement windows. Stakeholders must monitor secondary raw material certification pipelines and polymer traceability systems to preserve specification access across institutional procurement frameworks.
Market Dynamics
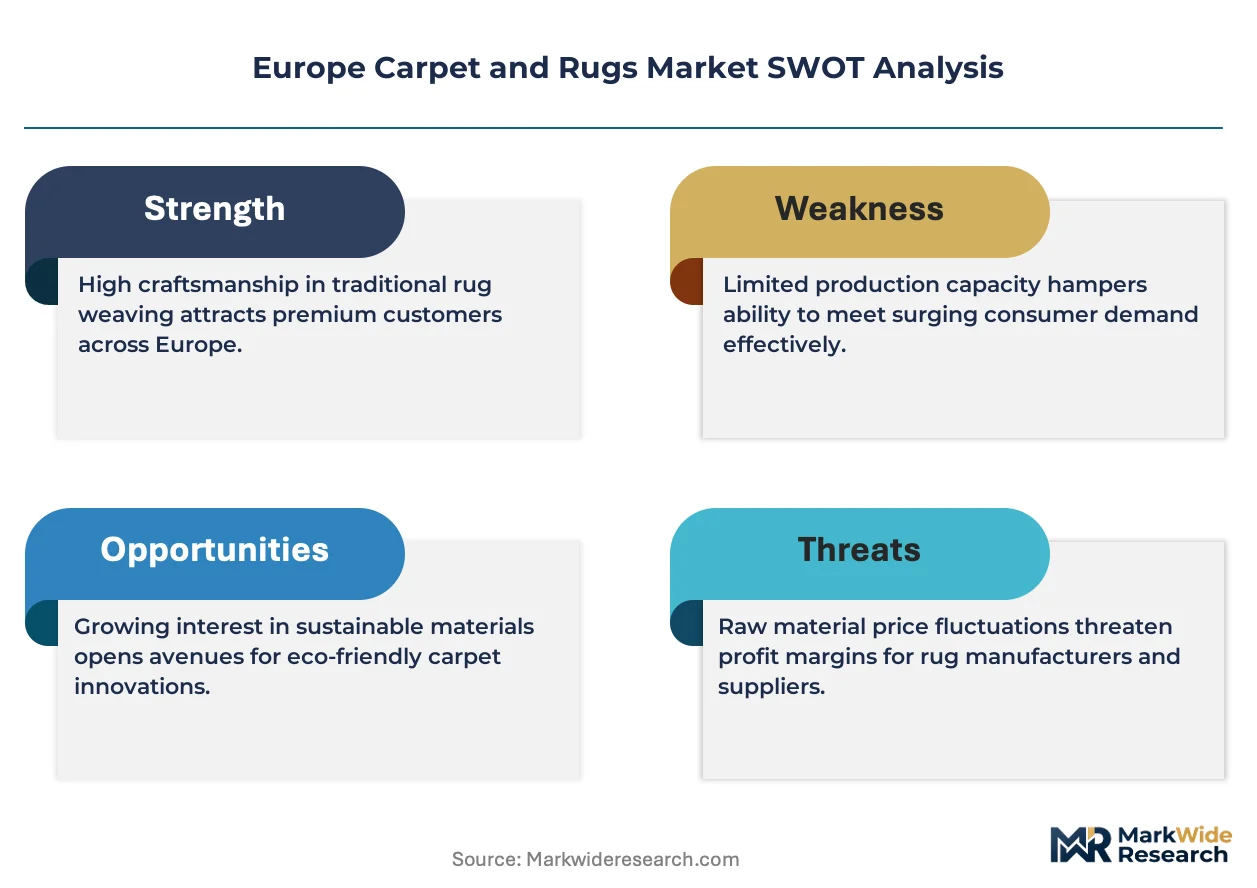
The EU Green Deal's material traceability mandates are forcing a wholesale reconfiguration of European carpet supply chains toward certified wool and recycled nylon sourcing. Procurement officers now face binding verification requirements that favor integrated fiber producers over asset-light importers.
Growth Catalysts
- Hospitality refurbishment cycles:German and French hotel renovation timelines are compressing specification windows for premium tufted broadloom and woven Axminster formats.
- REACH chemical restrictions:ECHA's evolving per- and polyfluoroalkyl substance limitations are accelerating reformulation investments in stain-resistant treatments ahead of enforcement.
- Nordic public sector tenders:Danish and Swedish institutional buyers are mandating recycled PET polyester content in commercial flooring contracts.
Market Restraints
- Raw material cost volatility:Wool fiber prices fluctuate with Australian and New Zealand clip volumes, squeezing margin predictability for premium woven lines.
- Belgian distribution concentration:A narrow corridor of Flemish logistics hubs controls last-mile access into French retail channels, creating bottleneck risk.
- Technical substitution ceiling:Recycled nylon 6,6 cannot yet match virgin polymer tenacity for high-traffic aviation and rail applications.
Strategic Opportunities
- Eastern European contract penetration:Polish and Romanian office development corridors remain underpenetrated by Western European specification brands.
- France's AGEC anti-waste law:Extended producer responsibility mandates are creating first-mover advantage for closed-loop recycling infrastructure investments.
- Digital sampling convergence:Virtual reality visualization tools combined with automated dye-matching systems are compressing specification-to-order timelines for Milan design studios.
Industry Challenges
- Polymer traceability skill gaps:Supply chain auditors lack standardized certification protocols for verifying recycled content claims across multi-tier nylon supply networks.
- Capex intensity for extrusion capacity:Captive nylon polymerization requires eight-figure investments that exclude mid-scale weavers from margin-protected specification tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Carpet and Rugs Market |
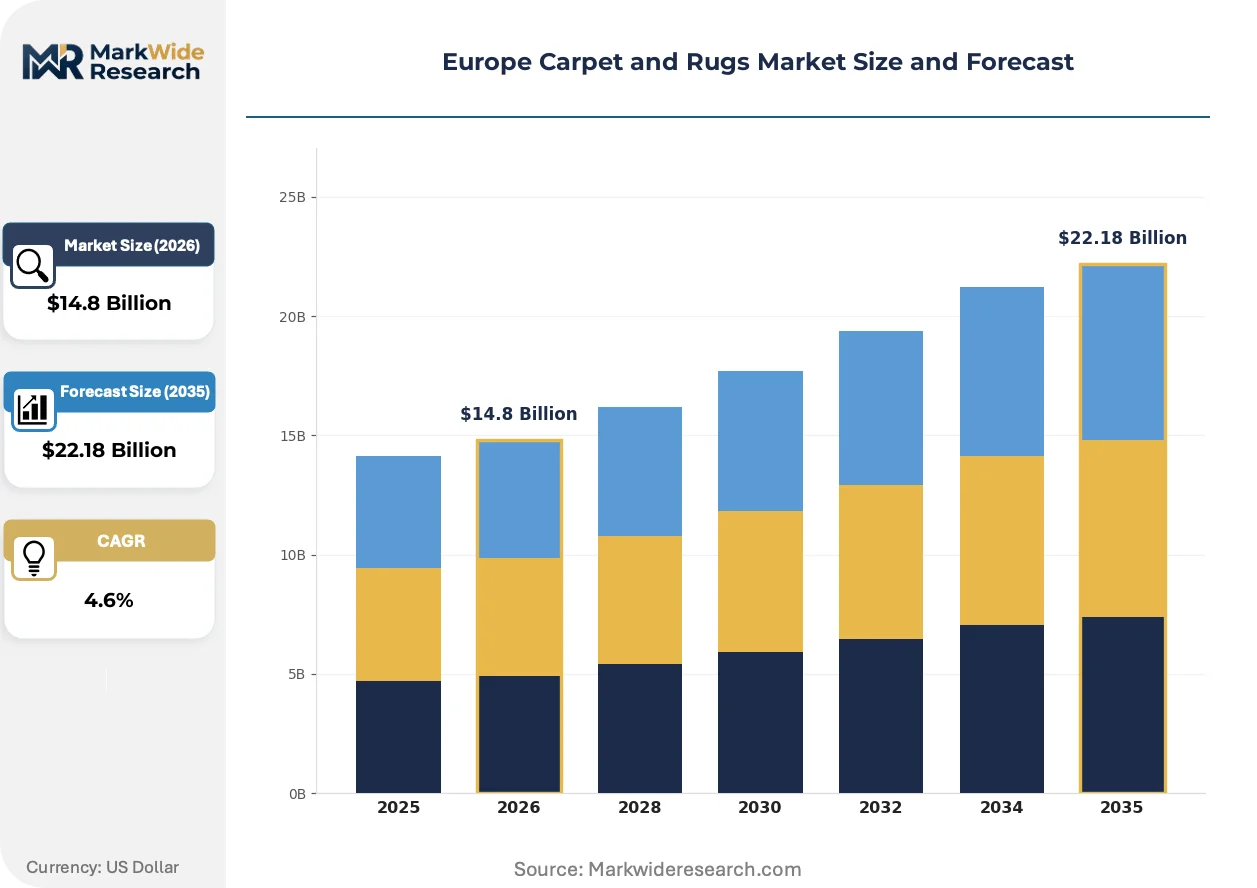
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tufted, Woven, Knotted, Flokati Material: Wool, Nylon, Polyester, Jute End User: Residential, Commercial, Hospitality, Automotive Feature: Eco-Friendly, Stain-Resistant, Customizable, Luxury |
| Companies Covered | Mohawk Industries, Fletco Carpets, Balta Group, Condor Carpets, Beaulieu International Group, Desso, Ulster Carpet Mills, Brintons Carpets, Tarkett, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Carpet and Rugs Market Shifts & Advancements
Active noise-reduction carpet backings and bio-based adhesive systems are displacing conventional petroleum-derived construction layers across European commercial specifications. These material shifts coincide with compressed project timelines that reward rapid-sample-turnaround capabilities.
Solution-dyed nylon fiber technology is miniaturizing color-batch minimums from thousands of pounds to hundreds, enabling hospitality designers to specify custom palettes without inventory risk. London and Milan boutique hotel projects are adopting this capability at accelerating rates. The technology is compressing the traditional specification hierarchy that reserved custom color access to high-volume Axminster orders.
ECHA's proposed restrictions on per- and polyfluoroalkyl substances in stain-resistant treatments are forcing reformulation investments across the value chain. German chemical suppliers are accelerating fluorine-free alternatives ahead of anticipated enforcement windows. Hospitality and healthcare segments in France and the UK are pre-emptively shifting procurement toward compliant treatments to avoid future specification lockout.
Institutional buyers are consolidating flooring contracts under single-source framework agreements that bundle installation, maintenance, and end-of-life retrieval. French hospital networks and Swedish municipal housing authorities are pioneering this model. The shift compresses supplier margins while locking in volume commitments that favor integrated manufacturers with captive recycling infrastructure.
Europe Carpet and Rugs Market Segmentation
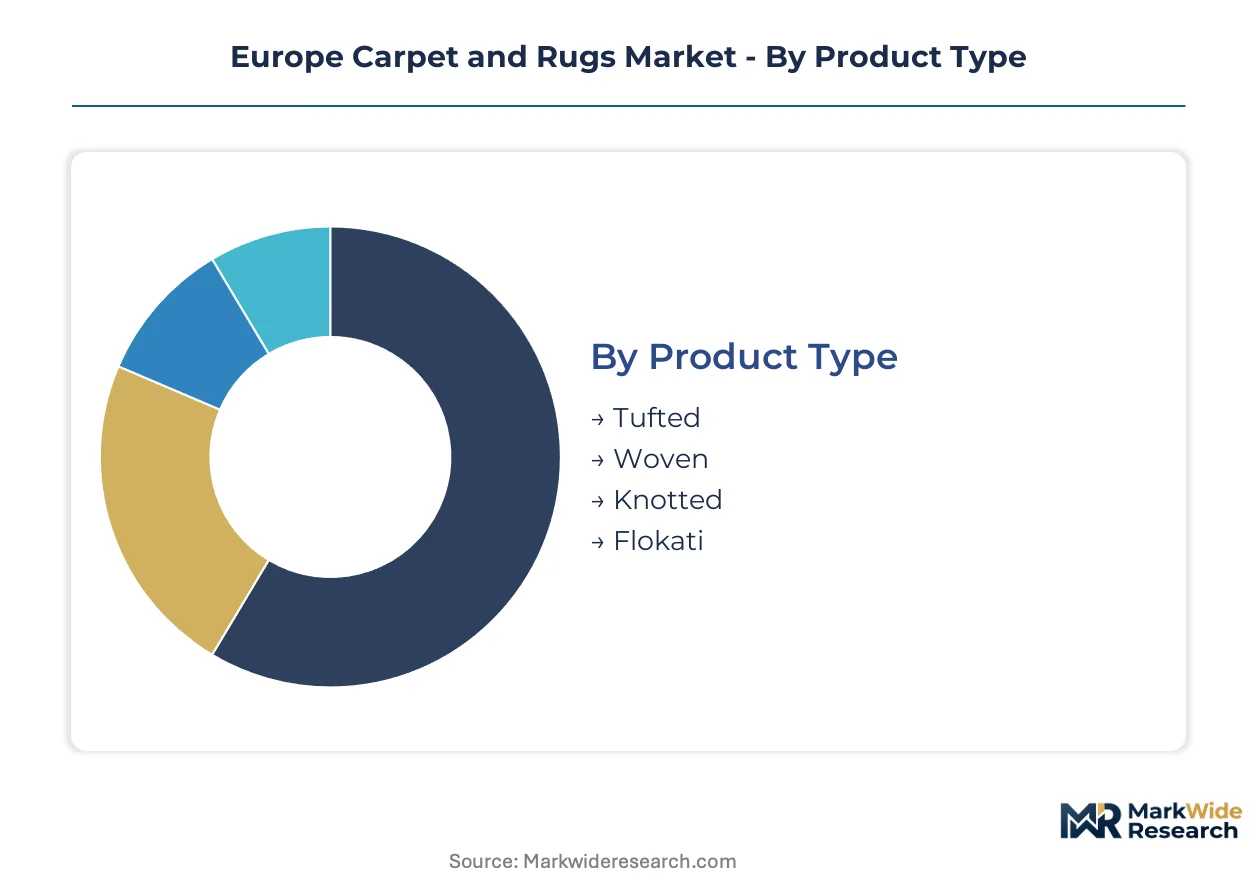
European carpet procurement increasingly segments around compliance architecture rather than traditional performance metrics alone. Specification officers now filter options through REACH chemical restrictions, EU Green Deal traceability mandates, and France's AGEC anti-waste law obligations before considering aesthetic or durability characteristics.
Product Type:
Margin pools concentrate in mechanized production formats where speed-to-dye-lot and minimum-order compression protect pricing power against low-cost import competition.
- Tufted:Mechanized needle-punch construction dominates residential replacement cycles across Germany and France, with pile weights ranging from 24 to 40 ounces per square yard for commercial durability. German hospitality refurbishment timelines are compressing specification windows for premium broadloom formats with rapid-sample-turnaround requirements.
- Woven:Axminster and Wilton constructions retain specification loyalty in London heritage hospitality interiors where pattern complexity and wool content command premium positioning. REACH chemical restrictions on stain-resistant treatments are forcing reformulation investments that favor integrated weavers with captive chemical partnerships.
- Knotted:Hand-tied pile construction serves niche luxury residential segments in Milan and Paris design districts where artisan provenance justifies extended lead times.
- Flokati:Long-pile shag constructions from Greek regional traditions occupy specialty import channels into Nordic residential markets.
The dominant share belongs to Tufted, while Woven is closing the gap fastest through hospitality specification upgrades.
Material:
Supply chain configuration determines access to institutional procurement frameworks more than intrinsic fiber performance.
- Wool:Natural fiber grades from Australian and New Zealand clip volumes command heritage commercial specifications in London and Paris, though price volatility squeezes margin predictability for premium woven lines. EU Green Deal material traceability mandates favor certified wool with verified farm-to-fiber documentation.
- Nylon:Solution-dyed polymer dominates high-traffic aviation and rail applications where tenacity requirements exceed recycled alternatives. ECHA's evolving per- and polyfluoroalkyl substance restrictions are accelerating fluorine-free stain-resistant treatment reformulations ahead of enforcement windows.
- Polyester:Recycled PET fiber displaces virgin polymer in Danish and Swedish public sector tenders with mandatory recycled content thresholds.
- Jute:Natural backing and face fiber serves eco-positioned residential segments in German and Benelux markets with bio-based adhesive compatibility requirements.
Wool retains the margin premium, though Nylon commands the largest volume position across contract flooring corridors.
End User:
Procurement consolidation under single-source framework agreements is compressing supplier margins while locking in volume commitments.
- Residential:Replacement-driven demand concentrates in Western European urban corridors around Milan and London design hubs, with digital sampling tools compressing specification-to-order timelines.
- Commercial:Polish and Romanian office development corridors remain underpenetrated by Western European specification brands with established recycling infrastructure.
- Hospitality:German and French hotel renovation cycles are accelerating specification upgrades for premium tufted broadloom and woven Axminster formats with active noise-reduction backings.
- Automotive:Molded carpet applications face technical substitution ceilings where recycled nylon 6,6 cannot yet match virgin polymer tenacity for high-traffic specifications.
Commercial holds the broadest installed base, while Hospitality is expanding most quickly through compressed refurbishment timelines.
Feature:
Regulatory compliance is becoming the primary feature differentiator ahead of traditional performance attributes.
- Eco-Friendly:Certified recycled content and bio-based adhesive systems displace petroleum-derived construction layers across French hospital networks and Swedish municipal housing authority tenders.
- Stain-Resistant:Fluorine-free treatment formulations are gaining mandatory adoption in France and UK healthcare segments to pre-empt ECHA enforcement lockout.
- Customizable:Solution-dyed nylon technology miniaturizes color-batch minimums from thousands of pounds to hundreds, enabling boutique hotel projects in London and Milan to specify custom palettes without inventory risk.
- Luxury:Heritage wool grades and hand-knotted provenance serve ultra-premium residential segments in Paris and Milan where specification loyalty resists polymer substitution.
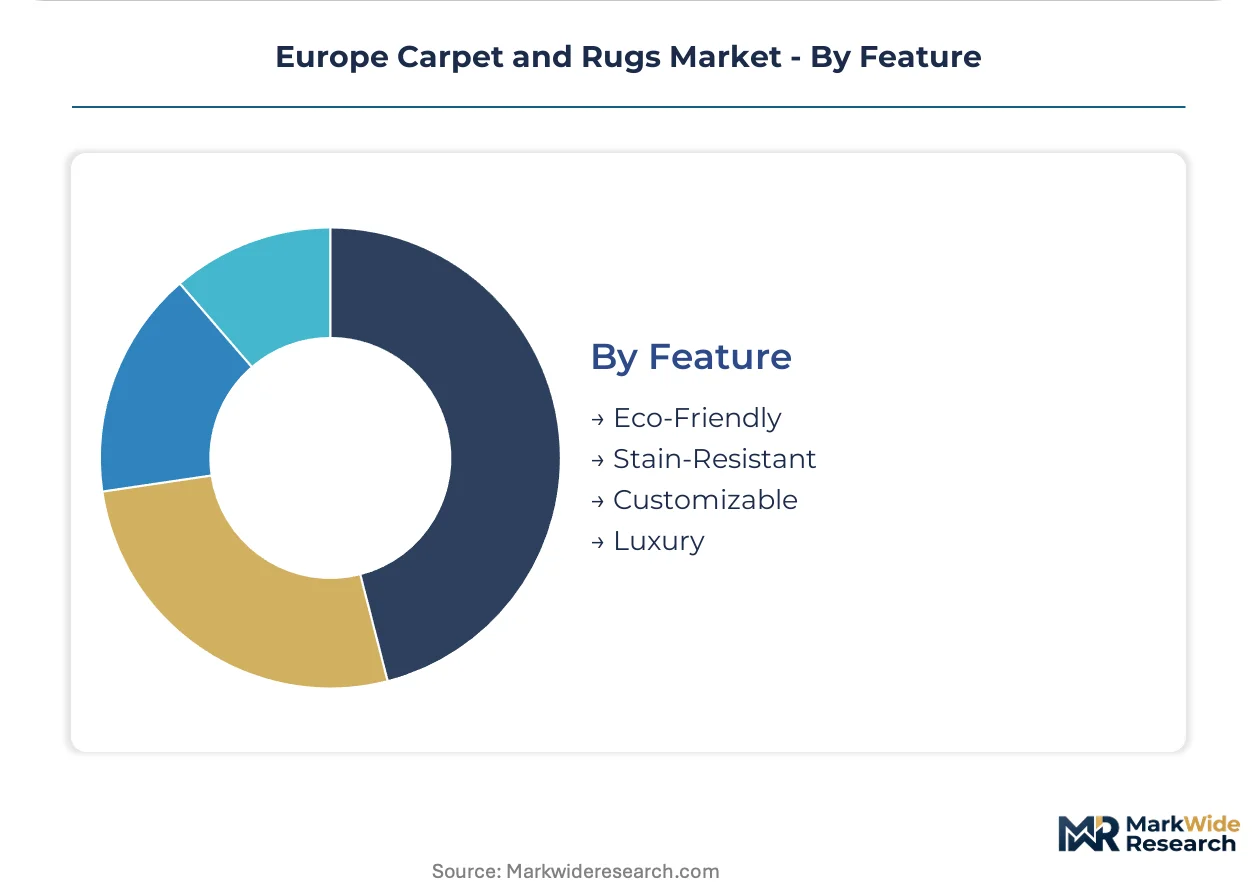
Eco-Friendly specifications are climbing the fastest through institutional procurement mandates, while Luxury maintains the highest margin per square meter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and French hospitality corridors while Italian and Spanish markets absorb margin compression from import competition. This asymmetry reflects divergent specification standards and enforcement stringency across EU member states.
Germany
Hotel refurbishment cycles in Berlin and Munich are compressing lead times for premium tufted broadloom with active noise-reduction backings. REACH chemical restrictions on per- and polyfluoroalkyl substances are accelerating fluorine-free stain-resistant treatment adoption ahead of ECHA enforcement windows. The Rhine-Ruhr industrial corridor hosts integrated fiber producers with captive nylon extrusion capacity serving aviation and rail specifications.
France
AGEC anti-waste law mandates are redirecting hospital network procurement toward closed-loop recycling infrastructure with extended producer responsibility obligations. Paris hospitality design studios are adopting solution-dyed nylon technology for boutique hotel custom palettes with compressed color-batch minimums. The Île-de-France region concentrates specification influence for heritage commercial interiors where wool grades command loyalty.
United Kingdom
London hospitality refurbishment sustains demand for woven Axminster and Wilton constructions in heritage interiors where pattern complexity justifies premium positioning. ECHA-aligned regulatory pressure is pre-emptively shifting healthcare segment procurement toward compliant stain-resistant treatments. The Midlands manufacturing cluster retains weaving capacity for high-traffic contract specifications with established chemical partnerships.
Italy
Milan design hubs are driving digital sampling convergence with virtual reality visualization tools compressing specification-to-order timelines for residential replacement cycles. EU Green Deal material traceability mandates favor certified wool with verified farm-to-fiber documentation for luxury segments. Northern Italian textile districts maintain artisan hand-knotted production for ultra-premium residential channels.
Belgium
Flemish logistics hubs control last-mile distribution access into French retail channels, creating bottleneck risk for asset-light importers without integrated networks. REACH compliance costs are filtering specification access toward integrated producers with captive chemical reformulation capabilities. The Ghent-Antwerp corridor concentrates Belgian distribution networks serving Benelux and northern French contract flooring markets.
Europe Carpet and Rugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European carpet trade. Integrated fiber producers with captive nylon extrusion capacity anchor margin control in high-traffic commercial specifications, while regional weaving clusters compete on rapid-sample-turnaround capabilities for hospitality refurbishment cycles. Three archetypes dominate: integrated polymer producers with backward control over raw material supply, regional specialists leveraging proximity to design hubs, and asset-light importers dependent on third-party certification pipelines. Competitive moves concentrate on strategic partnerships for closed-loop recycling infrastructure and geographic expansion into underpenetrated Eastern European office development corridors.
Among integrated manufacturers with captive fiber production, Mohawk Industries exemplifies the polymer-control archetype, while Fletco Carpets represents regional weaving specialists leveraging Danish production proximity to Nordic public sector tender requirements. Balta Group occupies a position within the distribution-integrated tier, anchoring Belgian logistics access into French retail channels. These three players illustrate the structural divergence between margin-protected specification tiers and volume-competing import channels reshaping competitive stability across the European floor covering trade.
| Leading Market Players |
|---|
| Mohawk Industries |
| Fletco Carpets |
| Balta Group |
| Condor Carpets |
| Beaulieu International Group |
| Desso |
| Ulster Carpet Mills |
| Brintons Carpets |
| Tarkett |
| Others |
Supply & Pricing Matrix
Recycled PET polyester displacement of virgin polymer in Nordic public sector tenders simultaneously redraws raw material sourcing maps toward Danish chemical reclamation clusters and compresses margin premiums for conventional nylon extrusion tiers. Procurement officers now weight verified circular content above legacy performance metrics, redirecting specification economics toward integrated recyclers with captive feedstock pipelines.
Pricing Analysis
The customization-premium spread between solution-dyed nylon color-batch minimums and standard tufted broadloom inventories captures the widest price differential in European contract flooring. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with EU Green Deal traceability documentation commanding measurable uplifts. Cost compression in economy tufted lines is intensifying because Turkish import volumes are absorbing mid-scale weaver market share. Hospitality specification buyers demonstrate lowest price sensitivity, while residential replacement segments in Benelux markets resist premium positioning.
Supply Chain Analysis
Belgium and the Netherlands anchor European carpet distribution through Flemish logistics corridors controlling last-mile access into French retail channels. Raw material flows draw from Australian wool clip volumes, Saudi petrochemical feedstocks for nylon polymerization, and Greek cotton-jute blending operations for natural backing layers. Single-source vulnerability concentrates in the Rhine-Ruhr nylon extrusion cluster, where captive polymerization capacity rests on eight-figure capital commitments excluding mid-tier competitors. Distribution runs through specification houses in Milan and London design hubs that bundle installation and maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymer traceability auditing capabilities have become the scarcest operational asset across European carpet supply chains, with standardized certification protocols for multi-tier nylon networks remaining underdeveloped. This competency gap separates integrated producers with in-house verification systems from asset-light importers facing procurement exclusion.
For Market Incumbents: Fortify specification access through captive recycling infrastructure investments aligned with France's AGEC extended producer responsibility mandates. Backward integration into solution-dyed nylon extrusion protects margin control against Turkish volume competition. ECHA's evolving per- and polyfluoroalkyl substance restrictions threaten stain-resistant treatment formulations, demanding accelerated fluorine-free reformulation partnerships with German chemical suppliers. For New Entrants and Emerging Players: EU Green Deal material traceability certification fast-tracks market entry into Danish and Swedish public sector tenders with mandatory recycled content thresholds. Polish and Romanian office development corridors remain the most penetrable geography for specification brands with established circular infrastructure. Digital sampling convergence with virtual reality visualization tools offers a differentiated go-to-market angle for Milan design studio relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional weaving specialists in Denmark and the United Kingdom lacking captive fiber production. Long-term viability over the coming decade hinges on closed-loop recycling infrastructure ownership rather than brand equity alone. Watch for ECHA enforcement windows on fluorinated treatments as an inflection indicator accelerating consolidation toward compliant integrated manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nylon Extrusion | Captive polymerization secures margin control against Turkish import pricing pressure. |
| Closed-Loop Recycling Infrastructure Buildout | AGEC compliance creates first-mover advantage in French hospital network procurement. |
| Fluorine-Free Treatment Reformulation | ECHA-aligned chemical partnerships preempt specification lockout in UK healthcare segments. |
| Digital Sampling Platform Deployment | Virtual reality tools compress specification-to-order timelines for Milan hospitality projects. |
| Eastern European Distribution Expansion | Polish office corridors offer volume growth outside saturated Western European channels. |
Research Methodology
Desk research of customs trade databases, REACH regulatory filings, and EU Green Deal implementation guidelines preceded structured interviews with procurement officers at French hospital networks, specification directors at Milan design studios, and technical directors at Belgian distribution hubs. Primary fieldwork with Nordic municipal housing authority tender managers and German hospitality refurbishment contractors was cross-validated against secondary sources including ECHA substance restriction timelines and AGEC compliance documentation. Bottom-up volume modeling triangulated against top-down macroeconomic indicators across the analysis window.
Variance decomposition across product type, material grade, end-use segment, and geographic regulatory cluster shaped the analytical framework. Modeled dimensions included tufted versus woven construction formats, certified wool versus recycled nylon versus virgin polymer material tiers, and hospitality versus commercial versus residential end-use applications. CAGRs were derived through regression analysis of historical specification volumes against projected refurbishment cycle compression. Industry-specific inputs incorporated ECHA enforcement probability weightings and AGEC extended producer responsibility implementation pacing.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal material traceability mandate enforcement and stable Australian wool clip volumes; material deviation would warrant model refresh. Forecasts reflect base-case regulatory implementation without anticipating accelerated ECHA restrictions or delayed AGEC compliance deadlines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
China Floor Covering Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Germany Resilient Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
Germany Flooring Market
Flooring, Carpets, and Rugs
India Non-Resilient Floor Covering Market