
 Terrazzo Flooring Market | 2026-2036
Terrazzo Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Terrazzo Flooring Market Intelligence
LEED v4.1 and WELL Building Standard certifications are redrawing competitive access in commercial flooring specification. TERRAZZCO leverages captive epoxy resin blending to control material consistency across large-format installations. Concord Terrazzo Company anchors its position through artisan-driven restoration services for historic buildings. Diespeker & Co. specializes in bespoke metal divider strip configurations that differentiate premium residential commissions.
Terrazzo flooring comprises a composite surface of marble, quartz, granite, glass, or other aggregates bound in cementitious or resinous matrices, typically installed at thicknesses ranging from one-half to three inches over concrete substrates. Epoxy-based systems dominate new commercial construction due to thinner profiles and faster cure cycles, while cementitious formulations retain share in heritage restoration where breathability matters. The commercial application segment leads absolute volume, though institutional projects—particularly K-12 and university buildings—represent the fastest-growing specification channel as public procurement tightens lifecycle cost criteria. Polished finish types command premium positioning in corporate and hospitality settings, whereas honed surfaces gain traction in healthcare environments where slip resistance protocols override gloss requirements.
The U.S. Green Building Council's LEED framework and California's Department of Public Health CDPH Standard Method v1.2 govern volatile organic compound thresholds and material ingredient disclosure for interior flooring systems. The EPA's Renovation, Repair, and Painting Rule and OSHA silica exposure limits shape jobsite preparation protocols and wet-grinding equipment mandates during installation. Stakeholders must monitor evolving state-level embodied carbon legislation and extended producer responsibility proposals that could restructure aggregate sourcing and end-of-life recovery obligations for resin-bound flooring systems.
Market Dynamics
Thin-set epoxy terrazzo systems are compressing installation timelines from weeks to days, reconfiguring contractor capacity planning and project bidding structures across commercial construction corridors.
Growth Catalysts
- LEED v4.1 Material Disclosure:Certification mandates for volatile organic compound thresholds and ingredient transparency are pulling specification toward epoxy systems with documented supply chain provenance.
- Sun Belt Metropolitan Construction:Phoenix, Austin, and Miami development corridors are concentrating healthcare and airport capital expenditure, driving large-format terrazzo volume.
- WELL Building Standard Adoption:Indoor air quality protocols are filtering flooring selection toward low-emitting resin-bound systems in corporate headquarters and hospitality.
Market Restraints
- Silica Exposure Compliance:OSHA silica limits mandate wet-grinding equipment and respiratory protection, elevating jobsite preparation costs and contractor qualification barriers.
- Cementitious System Decline:Breathable heritage formulations face technical displacement where faster cure cycles and thinner profiles dominate new construction specification.
- Skilled Artisan Scarcity:Terrazzo installation requires specialized grinding and polishing expertise, constraining crew scaling in high-volume metropolitan markets.
Strategic Opportunities
- Extended Producer Responsibility Proposals:California and New York legislative drafts on end-of-life recovery obligations could reward domestic aggregate recyclers with preferred supplier status.
- Healthcare Slip-Resistance Protocols:Honed finish specifications in hospital and clinic environments open premium positioning for textured surface engineering.
- K-12 Lifecycle Cost Procurement:Public school districts are tightening total cost of ownership criteria, favoring terrazzo's durability against vinyl and carpet alternatives.
Industry Challenges
- Embodied Carbon Measurement:State-level legislation in Washington and Colorado requires supply chain emissions disclosure, complicating aggregate sourcing from distant quarries.
- Epoxy Resin Price Volatility:Petrochemical input fluctuations compress margin predictability for contractors bidding fixed-price commercial installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Terrazzo Flooring Market |
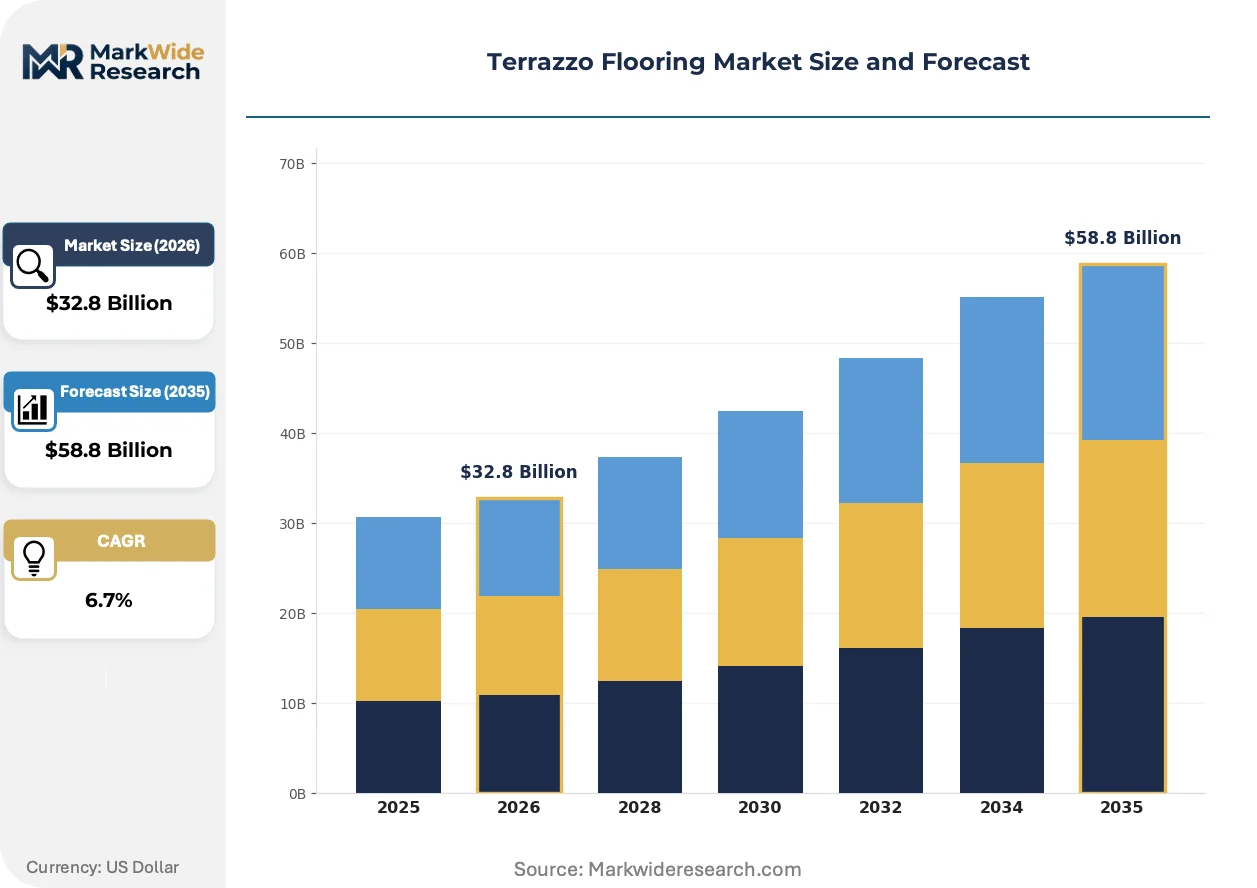
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $58.8 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: White Cement, Epoxy, Polyacrylate, Terrazzo Tiles Application: Commercial, Residential, Institutional, Industrial Finish Type: Polished, Honed, Matte, Textured Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Terrazzo & Marble Supply Companies, TERRAZZCO, Concord Terrazzo Company, Daltile, Kingspan Group, 4m Group, Diespeker & Co., AGGLOTECH, RBC Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Terrazzo Flooring Market Strategic Shifts & Innovations
Material science advances and certification protocol tightening are bifurcating the terrazzo market between specification-grade epoxy systems and artisan cementitious restoration, with distinct capability requirements emerging for each track.
Recycled glass and post-consumer porcelain aggregates are fragmenting traditional marble-dominated specification. Airport terminal designers in Denver and Atlanta are specifying these materials at expanding scale. The shift is compressing demand for virgin quarried stone while elevating suppliers with captive recycling infrastructure.
California's Department of Public Health CDPH Standard Method v1.2 is hardening volatile organic compound thresholds for interior flooring. Manufacturers must now submit full material ingredient documentation to qualify for state-funded institutional projects. Healthcare and education procurement offices are filtering bids against this standard, disqualifying systems with incomplete disclosure.
Facility managers are consolidating flooring maintenance under multi-year service contracts rather than capital replacement cycles. Corporate campus and university buyers are bundling installation with scheduled restoration and re-polishing. This pattern concentrates most visibly in Texas and Florida, where rapid building stock expansion strains in-house maintenance capacity.
Terrazzo Flooring Market Segmentation
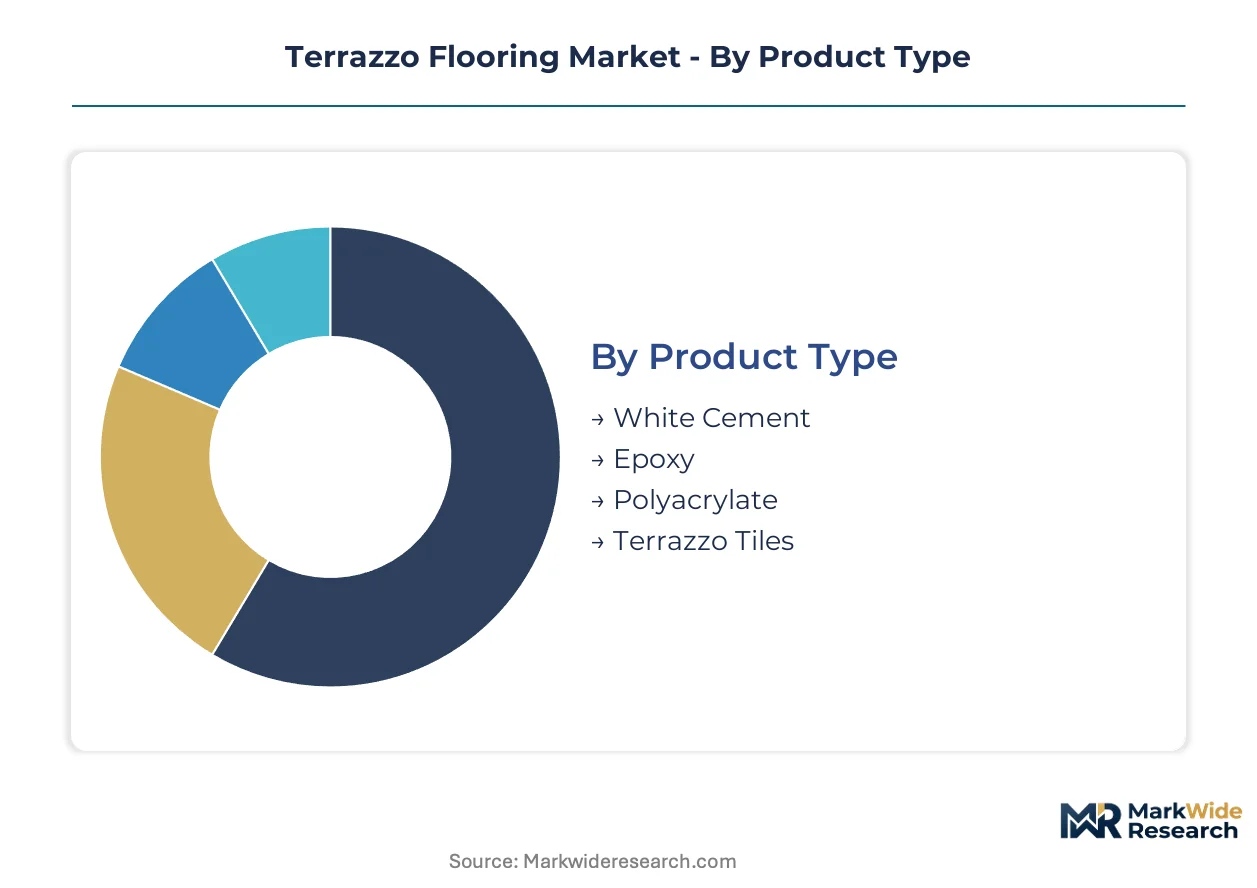
Terrazzo flooring specification channels bifurcate between large-format commercial projects procured through direct manufacturer relationships and smaller residential or renovation work flowing through distributor networks. Understanding these channel dynamics reveals where margin compression concentrates and where technical support requirements escalate.
Product Type:
Epoxy systems flow predominantly through direct sales channels serving commercial contractors, while cementitious and tile formats distribute more heavily through retail and distributor networks serving renovation markets.
- Epoxy:Thin-set resin matrices cure rapidly and install at reduced thickness, making them the default for airport terminals and healthcare campuses where downtime minimization drives procurement. Demand concentrates in Sun Belt metropolitan corridors where new construction volume is heaviest.
- White Cement:Traditional Portland-based binders carry higher embodied carbon profiles but remain specified for heritage restoration where substrate breathability prevents moisture damage. Specification persists in historic district renovations across the northeastern United States.
- Polyacrylate:Modified acrylic binders offer intermediate cure speeds and improved UV stability for exterior applications.
- Terrazzo Tiles:Pre-cast modular units enable faster installation in renovation contexts where wet-pour methods prove impractical.
Epoxy dominates installed base. Polyacrylate is where expansion concentrates for exterior and specialty applications.
Application:
Cost tier stratification separates high-value institutional projects with lifecycle cost mandates from price-sensitive residential renovations where material substitution pressure is acute.
- Commercial:Corporate headquarters, hospitality, and retail environments specify large-format seamless installations where design flexibility and durability justify premium positioning. LEED v4.1 and WELL Building Standard compliance filter specification toward documented low-emitting systems.
- Institutional:K-12 schools and university buildings represent the steepest expansion trajectory as public procurement tightens total cost of ownership criteria against vinyl and carpet alternatives. State education departments in Texas and Florida are driving volume.
- Residential:Custom homes and luxury multi-family specify artisan-driven cementitious work or bespoke epoxy designs.
- Industrial:Manufacturing and warehouse facilities prioritize chemical resistance and load-bearing capacity over aesthetic refinement.
Commercial anchors revenue concentration. Institutional procurement is climbing the fastest.
Finish Type:
Customer type differentiation separates corporate and hospitality buyers seeking polished gloss surfaces from healthcare facility managers prioritizing slip-resistance protocols.
- Polished:High-gloss surfaces achieved through progressive diamond grinding command premium positioning in corporate lobbies and hospitality settings where visual impact drives specification.
- Honed:Satin-finish surfaces with enhanced slip resistance gain specification in hospital corridors and clinic environments where OSHA safety protocols override aesthetic preferences.
- Matte:Low-shear finishes suit residential and boutique commercial contexts.
- Textured:Aggregate-exposed surfaces provide maximum traction for wet environments.
Polished finishes dominate premium specification. Honed surfaces are gaining share fastest in healthcare-driven markets.
Distribution Channel:
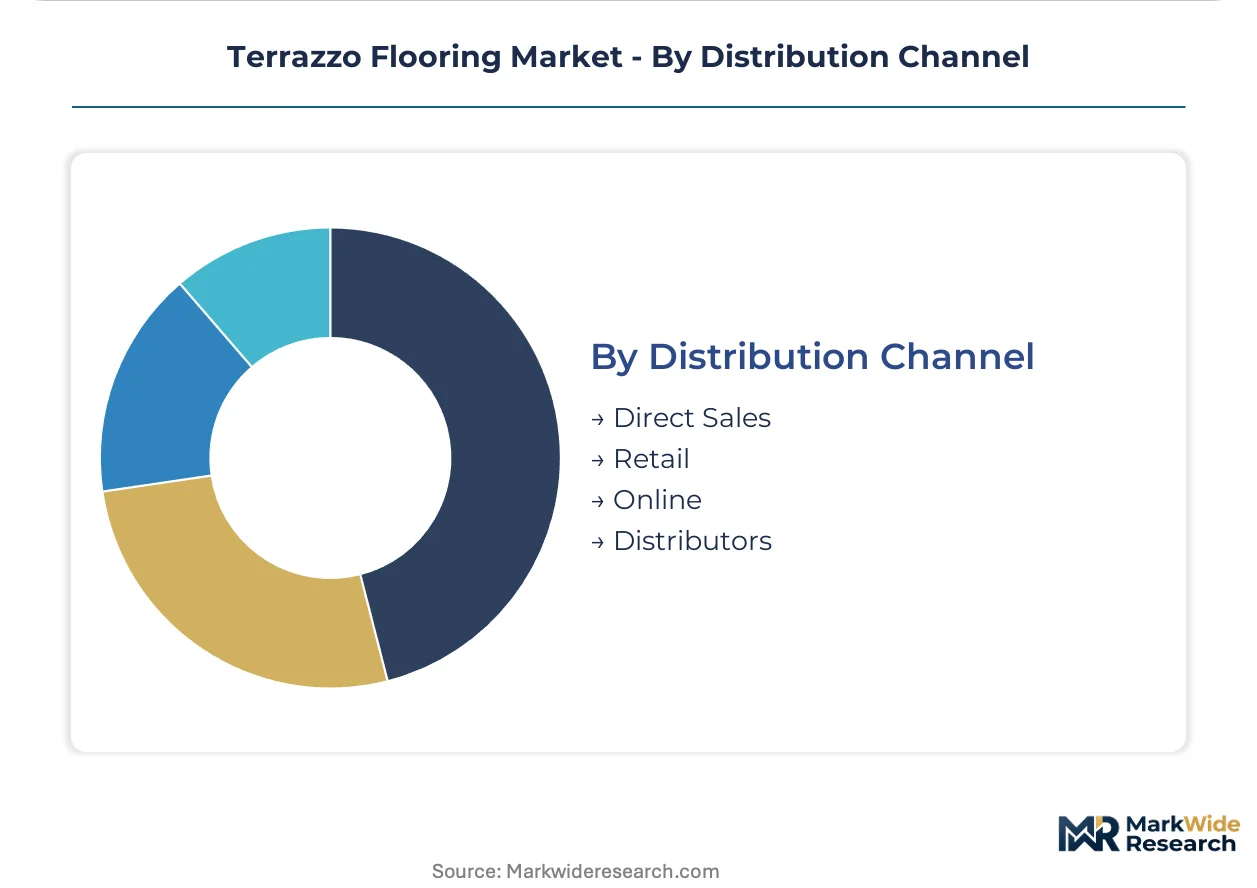
Volume concentration in large-format commercial work tilts procurement toward direct manufacturer engagement, while fragmented residential demand sustains distributor and retail intermediation.
- Direct Sales:Manufacturer-to-contractor relationships dominate airport, healthcare, and corporate campus projects where technical consultation, custom color matching, and installation supervision are bundled into procurement.
- Distributors:Regional flooring supply houses aggregate demand from mid-sized commercial contractors and institutional maintenance departments, particularly in Texas and Florida where building stock expansion strains direct sales capacity.
- Retail:Showroom-based specification serves residential renovation and small commercial projects.
- Online:Digital channels facilitate sample procurement and preliminary specification for remote or preliminary project phases.
Direct sales capture the largest project value. Distributor relationships are expanding fastest as metropolitan construction volume outpaces manufacturer direct capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare and airport procurement offices concentrate specification authority in Sun Belt metropolitan corridors, while institutional buyers in the Northeast and Midwest filter bids through legacy building stock constraints. This buyer-archetype distribution shapes where epoxy thin-set systems displace cementitious alternatives.
United States
Phoenix, Austin, and Miami development corridors drive large-format terrazzo volume through healthcare campus and airport terminal capital expenditure. OSHA silica exposure limits mandate wet-grinding equipment and respiratory protection, elevating contractor qualification barriers. Texas and Florida public school districts are tightening total cost of ownership criteria, favoring terrazzo durability against vinyl alternatives.
Germany
Heritage restoration projects in Berlin and Munich sustain specification for breathable cementitious formulations where substrate moisture management prevents structural damage. REACH regulations govern volatile organic compound thresholds and material ingredient disclosure for interior flooring systems. The Bavarian construction cluster concentrates artisan-driven restoration capacity for historic building stock.
China
Airport terminal expansions in Beijing and Shanghai specify large-format epoxy systems where rapid cure cycles minimize operational downtime. GB standards and MIIT guidelines shape material performance requirements for commercial interior finishes. The Yangtze River Delta manufacturing base supplies resin matrices and recycled glass aggregates for domestic installation.
United Arab Emirates
Hospitality and corporate headquarters development in Dubai and Abu Dhabi drives premium polished finish specification for visual impact in lobby and atrium spaces. MOHAP indoor air quality protocols filter flooring selection toward low-emitting resin-bound systems. The Dubai construction corridor concentrates direct manufacturer-to-contractor procurement relationships for large-format seamless installations.
India
Institutional building stock expansion in Maharashtra and Karnataka generates demand for durable flooring in educational and healthcare facilities. BIS material standards and state-level public works procurement guidelines shape specification criteria for government-funded projects. The Mumbai-Pune industrial corridor concentrates distributor networks serving mid-sized commercial contractors.
Terrazzo Flooring Market Key Industry Players
Player mix skews toward regional specialists with captive resin blending or artisan restoration capabilities rather than diversified building materials conglomerates. Market structure remains fragmented across geographically concentrated installation crews and manufacturer-direct sales organizations. Two strategic archetypes dominate: epoxy system suppliers controlling material consistency through in-house resin production, and heritage restoration specialists leveraging artisan grinding expertise. Competitive moves concentrate on capacity expansion in Sun Belt metropolitan markets and strategic partnerships with airport and healthcare procurement offices.
Among North American epoxy system suppliers, TERRAZZCO and Concord Terrazzo Company exemplify divergent positioning strategies. TERRAZZCO occupies a position within the captive manufacturing archetype through controlled resin blending operations. Concord Terrazzo Company anchors the heritage restoration tier, representing artisan-driven service capabilities for historic building stock. Diespeker & Co. sits within the European specialist segment, reflecting bespoke metal divider strip engineering for premium residential commissions.
| Leading Market Players |
|---|
| Terrazzo & Marble Supply Companies |
| TERRAZZCO |
| Concord Terrazzo Company |
| Daltile |
| Kingspan Group |
| 4m Group |
| Diespeker & Co. |
| AGGLOTECH |
| RBC Industries |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between epoxy resin suppliers and large-format terrazzo contractors lock in supply access and price visibility across Sun Belt metropolitan construction corridors. These structures insulate procurement offices from petrochemical input volatility while cementing manufacturer-direct relationships.
Pricing Analysis
Cost-plus contracts with petrochemical indexation dominate epoxy terrazzo procurement, tying installed pricing to resin feedstock benchmarks. Three-tier pricing structure across premium LEED-certified systems, standard commercial grades, and economy cementitious alternatives separates specification tiers. Cost compression in standard epoxy grades is intensifying because of resin price volatility and contractor margin pressure. K-12 institutional buyers exhibit highest price sensitivity, while corporate headquarters procurement demonstrates lowest sensitivity due to lifecycle cost mandates.
Supply Chain Analysis
Strait of Malacca transit underwrites silica sand and marble aggregate flows from Southeast Asian quarries to U.S. manufacturing facilities. Epoxy resin production concentrates in Texas and Louisiana petrochemical corridors, while recycled glass aggregate processing localizes in Ohio and Pennsylvania. Supply chain risk centers on single-source vulnerability for specialized grinding equipment from German manufacturers. Distribution runs through direct manufacturer-to-contractor channels for large-format projects, with regional distributors serving mid-tier commercial renovation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The terrazzo flooring market functions as a defensive-moat industry where artisan grinding expertise and captive resin blending create switching costs that protect incumbent positions.
For Market Incumbents: Consolidate installation crew capacity in Phoenix, Austin, and Miami corridors where healthcare and airport capital expenditure concentrates. Acquire distressed cementitious restoration specialists in northeastern historic districts to preempt specialty competitor emergence. Deepen backward integration into recycled glass aggregate processing to offset virgin quarry exposure under Washington and Colorado embodied carbon legislation. For New Entrants and Emerging Players: Multi-year maintenance service bundling represents an under-served layer where facility managers lack in-house restoration capacity. Target Texas and Florida public school districts with honed-finish terrazzo alternatives to vinyl flooring, leveraging lifecycle cost procurement criteria. Pursue distributor partnerships rather than direct sales to avoid incumbent manufacturer-contractor relationship barriers. For Investors and Strategic Acquirers: Capital is best deployed toward captive resin blending specialists with Sun Belt installation capacity. The five-to-ten year viability window favors asset-light service models over capital-intensive manufacturing given embodied carbon regulatory uncertainty. Monitor California extended producer responsibility legislative drafts as the inflection signal for aggregate recycler valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | New grinding and polishing crews in Miami and Austin address healthcare campus backlog. |
| Backward Integration | In-house epoxy resin blending insulates TERRAZZCO from petrochemical price volatility. |
| Long-term Supply Agreement | Airport procurement offices lock in thin-set system pricing across multi-terminal programs. |
| Joint Venture | Recycled glass processors partner with terrazzo manufacturers to secure LEED v4.1 compliance. |
| Geographic Expansion | Heritage restoration specialists extend from Boston to Philadelphia historic districts. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with terrazzo installation contractors, resin formulation chemists, airport procurement officers, and healthcare facility managers; and secondary validation against U.S. Green Building Council certification databases, OSHA silica compliance records, state education department procurement filings, and petrochemical trade flow data. Bottom-up project pipeline aggregation and top-down construction spending allocation were triangulated.
Across the analysis window, the forecasting framework modeled volume and value through product type, application segment, finish specification, and distribution channel dimensions. CAGRs were derived from trend extrapolation of installed square footage against construction put-in-place indices. Industry-specific inputs included LEED certification penetration rates and public school district lifecycle cost procurement adoption curves.
Underlying assumptions cover sustained healthcare and airport capital expenditure in Sun Belt corridors, with deviation risk concentrated in state-level embodied carbon legislation and epoxy resin feedstock price volatility. Practitioners should keep alternative scenarios live as extended producer responsibility regulatory frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Taiwan Floor Covering Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
United Kingdom Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Resilient Flooring Market