
 Germany Flooring Market | 2026-2036
Germany Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Flooring Market Insights
Commercial property investors and healthcare facility operators is bifurcating demand away from traditional residential renovators who once dominated volume. Tarkett SA leverages its ReStart take-back program to anchor circularity credentials across German hospital and airport projects. Mohawk Industries competes through vertical integration into laminate substrate production, controlling resin supply chains that buffer volatile European petrochemical pricing. Forbo Flooring GmbH differentiates via linoleum manufacturing at its Assendelft-adjacent facility, sustaining natural composition advantages as chemical disclosure rules tighten.
Germany flooring encompasses surface coverings installed to provide structural support, thermal insulation, acoustic dampening, and aesthetic finish across built environments, with products typically classified by wear-layer thickness, slip-resistance rating, and volatile organic compound emission level under ISO 16000 standards. Laminate surfaces lead volume through cost efficiency in residential retrofit, while vinyl plank gains fastest specification growth in commercial settings requiring moisture resistance and rapid installation. Hardwood occupies premium margin pools among heritage building renovations and luxury residential developments where dimensional stability and refinishing longevity justify higher material and labor investment.
The KBA building code, EU Green Deal construction product requirements, and REACH chemical restrictions collectively shape material eligibility, with phthalate bans and formaldehyde thresholds eliminating certain vinyl and composite imports from German distribution channels. ECHA substance evaluation processes are forcing reformulation timelines that favor domestic and near-European manufacturers with in-house toxicology and compliance teams. Stakeholders must monitor how the EU AI Act's emerging building energy performance verification tools will automate specification decisions and potentially disintermediate traditional architect-specifier relationships.
Market Dynamics
The EU Green Deal's embodied carbon requirements are redirecting procurement toward certified bio-based and recycled-content flooring systems, compressing specification timelines for domestic manufacturers while eliminating certain import channels.
Growth Catalysts
- Healthcare Estate Modernization:Hospital renovation programs across Bavaria and North Rhine-Westphalia are accelerating specification of low-emission resilient surfaces for clinical hygiene environments.
- KBA Building Code Stringency:Updated technical standards for fire resistance and slip safety are forcing replacement cycles in commercial and public infrastructure applications.
- Logistics Cluster Expansion:Automotive manufacturing and warehouse distribution hubs are driving large-format installation demand for durable industrial-grade surfacing.
Market Restraints
- Petrochemical Input Volatility:Resin and plasticizer feedstock costs fluctuate with European refinery capacity constraints, compressing margin predictability for vinyl and composite producers.
- REACH Compliance Friction:ECHA substance evaluation processes for phthalate alternatives and formaldehyde thresholds extend reformulation timelines by 18-24 months.
- Heritage Substrate Limitation:Historic building renovation projects face technical constraints from dimensional instability in traditional hardwood over underfloor heating systems.
Strategic Opportunities
- Take-Back Program Infrastructure:Circular economy mandates under EU Green Deal construction product rules create first-mover advantage for closed-loop material recovery systems.
- AI-Enabled Specification Tools:The EU AI Act's emerging building energy performance verification automation will reshape architect-specifier relationships toward algorithm-driven product selection.
- Airport Terminal Expansion:Frankfurt and Munich aviation infrastructure projects represent concentrated demand for rapid-install, high-wear commercial surfacing with acoustic dampening properties.
Industry Challenges
- Toxicology Expertise Scarcity:REACH substance dossier preparation and SVHC notification procedures require specialized compliance personnel that mid-tier manufacturers struggle to recruit.
- Certification Timeline Compression:ISO 16000 VOC emission testing and CE marking documentation must accelerate to match compressed construction procurement schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Flooring Market |
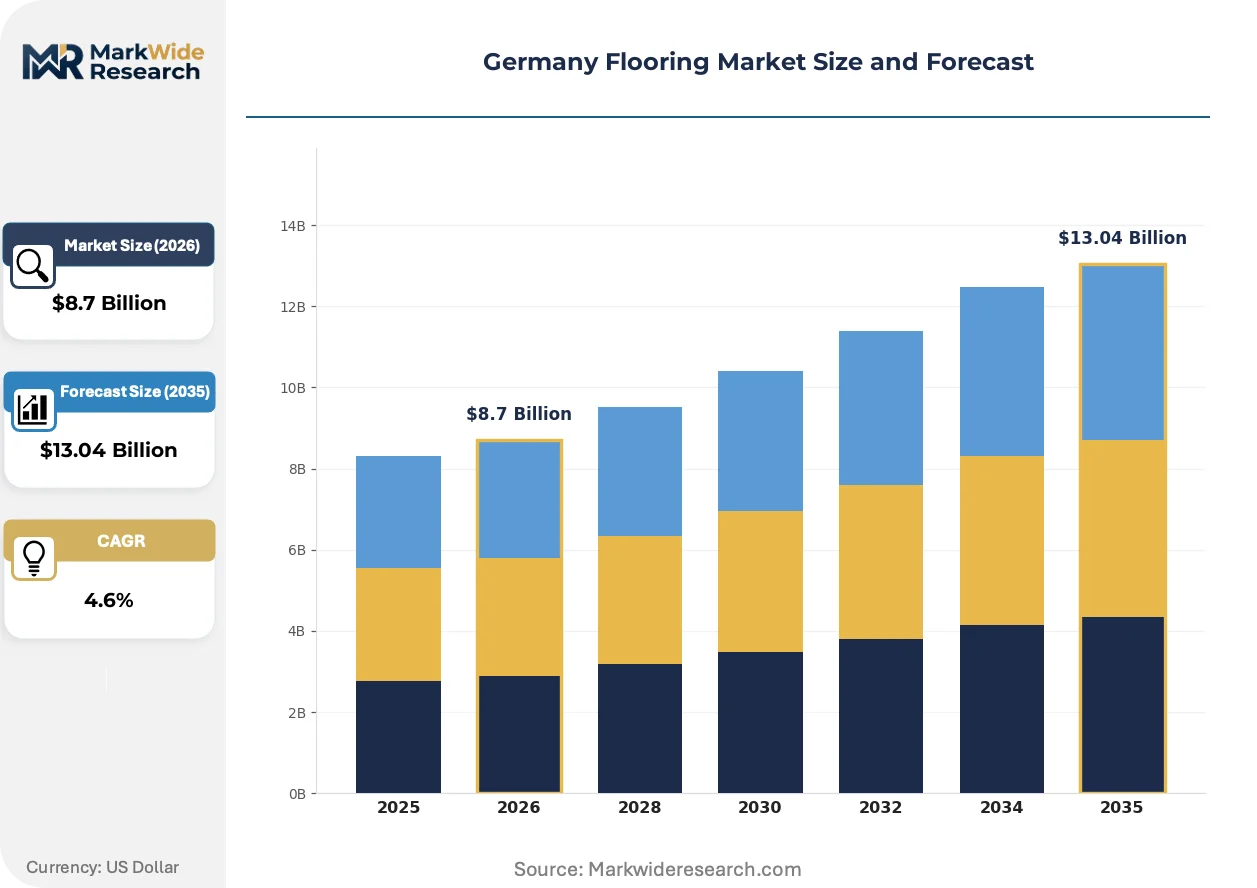
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardwood, Laminate, Vinyl, Carpet Installation Method: Glue Down, Nail Down, Floating, Loose Lay End User: Residential, Commercial, Industrial, Public Sector Distribution Channel: Online Retail, Specialty Stores, Wholesale, Direct Sales |
| Companies Covered | Mohawk Industries, Tarkett SA, Forbo Flooring GmbH, Milliken Flooring, Nora Systems GmbH, Gerflor, Shaw Industries Group, Kronospan Holdings Ltd, Swiss Krono Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Flooring Market Trends and Innovations
Material science advances and automated specification tools are restructuring competitive advantage around circularity credentials and rapid-deployment capabilities rather than traditional distribution relationships.
Digital printing technology applied to luxury vinyl plank surfaces is bifurcating aesthetic performance from material cost, enabling healthcare facility operators and airport developers to specify high-fidelity wood and stone visual replication at resilient flooring price points. Commercial renovators are adopting these surfaces fastest where moisture resistance and rapid installation compress project timelines. This technology is bifurcating the mid-market segment between premium aesthetic specification and economy functional deployment.
REACH chemical restrictions and the EU Green Deal's construction product requirements are eliminating certain vinyl and composite imports from German distribution channels, favoring domestic and near-European manufacturers with in-house toxicology teams. ECHA substance evaluation processes for phthalate bans are forcing reformulation investments that smaller import-dependent distributors cannot absorb. Laminate and linoleum categories are capturing displaced specification volume as chemical disclosure rules tighten.
Facility managers and commercial property investors are consolidating specification authority away from traditional architect-specifier relationships, centralizing procurement decisions around lifecycle cost and embodied carbon metrics. Engineering consultants and sustainability officers are displacing design-focused intermediaries in hospital and logistics project workflows. This concentration is most visible in North Rhine-Westphalia's automotive manufacturing estate renovations where corporate ESG mandates override individual project aesthetic preferences.
Germany Flooring Market Segmentation
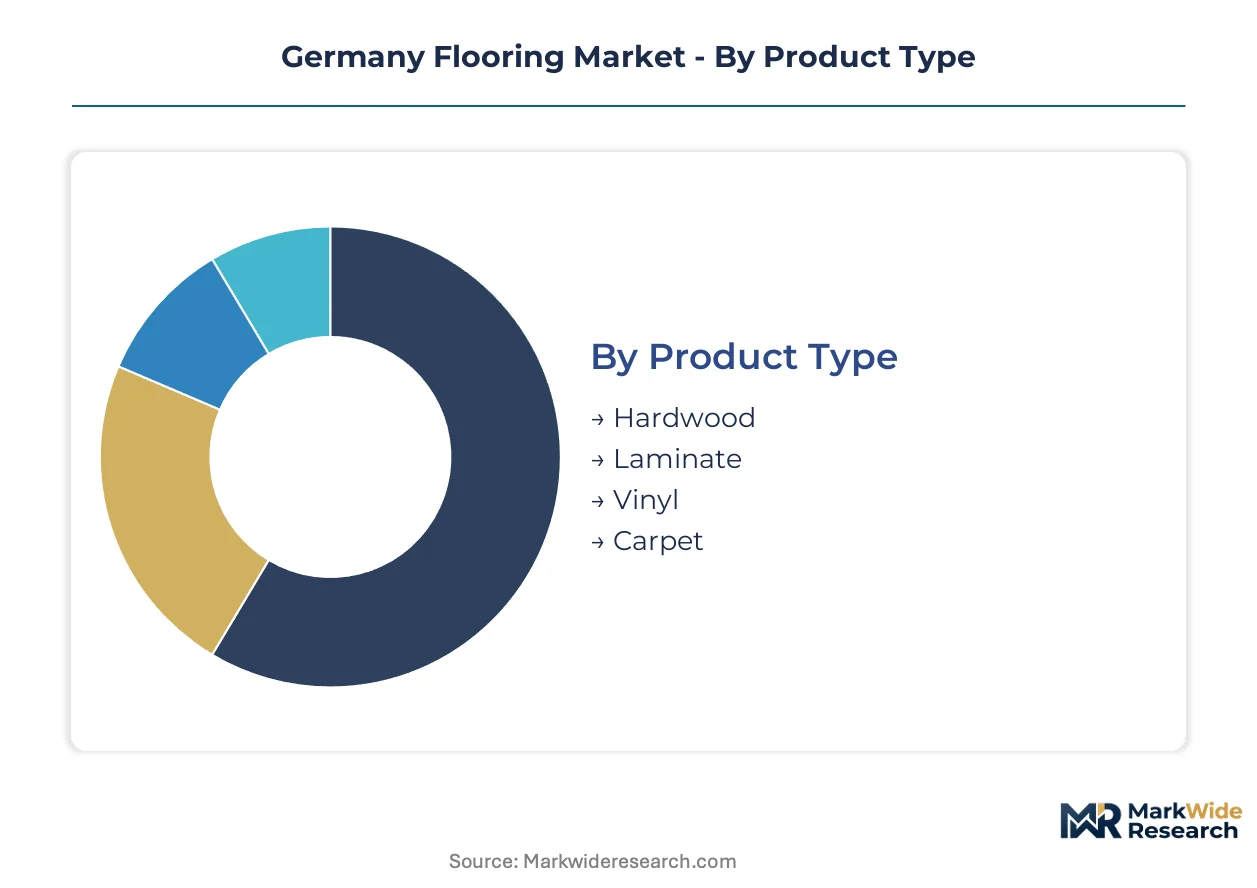
German flooring procurement patterns diverge sharply across product categories and installation contexts. Specification authority concentrates differently in healthcare renovation versus residential retrofit, reshaping how manufacturers align their distribution and certification investments.
Product Type:
Substitution pressure from low-emission alternatives is fragmenting traditional category boundaries as REACH compliance costs reshape competitive economics.
- Laminate:High-density fiberboard core with melamine wear layer delivers cost efficiency in residential retrofit across Bavaria and North Rhine-Westphalia. Multi-family housing developers specify this category fastest where budget constraints override premium aesthetic requirements.
- Vinyl:Resilient surfaces with fiberglass reinforcement and polyurethane coating capture specification growth in clinical hygiene environments. Hospital renovation programs in Munich and Frankfurt accelerate demand for moisture-resistant, rapid-install systems with ISO 16000 emission certification.
- Hardwood:Solid and engineered planks with aluminum oxide finishes dominate heritage building renovations where dimensional stability and refinishing longevity justify premium investment.
- Carpet:Broadloom and tile formats with solution-dyed fibers retain specification in acoustic-sensitive airport terminals and office environments.
Laminate retains volume leadership; vinyl holds the steepest expansion curve.
Installation Method:
Cost tier differentiation separates premium specification from economy deployment based on labor intensity and substrate preparation requirements.
- Floating:Click-lock plank systems install over existing substrates without adhesive, compressing project timelines in logistics hub renovations. Warehouse operators across North Rhine-Westphalia specify this method for rapid operational restart.
- Glue Down:Full-spread adhesive application delivers dimensional stability in high-traffic commercial settings. Healthcare facility operators in Bavaria prioritize this method for clinical environments requiring seam integrity and moisture protection.
- Nail Down:Traditional fastening for solid hardwood over wood subfloors dominates heritage residential renovations with underfloor heating compatibility constraints.
- Loose Lay:Friction-fit systems with fiberglass backing enable rapid deployment and future removal for temporary commercial installations.
Floating installation commands the widest application range; glue down captures premium commercial specification.
End User:
Customer type determines whether procurement prioritizes lifecycle cost metrics or upfront capital expenditure constraints.
- Commercial:Property investors and facility managers centralize specification authority around embodied carbon and total cost of ownership. Office and retail estate renovations across Frankfurt and Munich drive demand for certified bio-based systems.
- Residential:Individual renovators and multi-family developers balance aesthetic preference with KBA building code compliance for fire resistance and slip safety.
- Public Sector:Municipal procurement frameworks for schools and administrative buildings prioritize REACH-compliant materials with documented recycled content.
- Industrial:Automotive manufacturing and distribution hubs require industrial-grade surfacing with chemical resistance and load-bearing capacity.
Commercial end users concentrate specification authority fastest; residential retains volume scale.
Distribution Channel:
Supply concentration favors channels with in-house toxicology expertise and accelerated CE marking documentation capabilities.
- Specialty Stores:Regional flooring retailers with technical consultation services dominate residential renovation projects requiring substrate assessment and installation coordination.
- Wholesale:Distributors serving contractor networks capture commercial project volume through volume pricing and just-in-time delivery to construction sites.
- Direct Sales:Manufacturer-direct relationships with hospital operators and airport authorities bypass traditional intermediaries for large-format specification.
- Online Retail:E-commerce platforms with sample fulfillment and digital visualization tools gain share in residential replacement purchases.
Specialty stores retain residential channel leadership; direct sales expands most quickly in commercial infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German flooring supply chains concentrate in southwestern and western industrial corridors where resin compounding, fiberboard milling, and linoleum manufacturing clusters have developed over decades. Bavaria and North Rhine-Westphalia together absorb the dominant share of commercial specification volume.
Bavaria
Hospital renovation programs and automotive manufacturing estates drive specification of low-emission resilient surfaces across Munich and Nuremberg metropolitan zones. The KBA building code enforces strict fire resistance and slip safety standards that accelerate replacement cycles in clinical and industrial environments. Munich's airport terminal expansion projects concentrate demand for rapid-install commercial surfacing with acoustic dampening properties.
North Rhine-Westphalia
Logistics hub operators and warehouse developers specify large-format floating installations for rapid operational restart across the Rhine-Ruhr industrial belt. REACH compliance requirements for phthalate alternatives filter procurement toward domestic manufacturers with in-house toxicology capabilities. Düsseldorf and Cologne commercial property investors centralize specification authority around embodied carbon metrics and total cost of ownership calculations.
Baden-Württemberg
Heritage building renovations in Stuttgart and Heidelberg sustain premium demand for engineered hardwood with aluminum oxide finishes and dimensional stability. The EU Green Deal's construction product requirements redirect public sector procurement toward certified bio-based systems in municipal school and administrative projects. Karlsruhe's research institutions anchor testing and certification infrastructure for ISO 16000 VOC emission protocols.
Lower Saxony
Automotive supplier parks and distribution centers around Wolfsburg and Hanover generate industrial-grade surfacing demand with chemical resistance and load-bearing specifications. ECHA substance evaluation timelines for formaldehyde thresholds extend reformulation investments that favor established domestic compounders. The region's port logistics infrastructure facilitates resin and plasticizer feedstock distribution to vinyl manufacturing facilities.
Hesse
Frankfurt's financial services sector and expanding airport aviation infrastructure create concentrated demand for high-wear commercial carpet tile and luxury vinyl plank specification. Corporate ESG mandates from headquarters-based property investors override individual project aesthetic preferences in favor of lifecycle cost optimization. The region's central location supports just-in-time distribution coordination to construction sites across southern and western Germany.
Germany Flooring Market Competitive Landscape
Concentration sits with diversified surface covering conglomerates and specialized resilient flooring manufacturers that have invested in circular economy infrastructure and REACH compliance capabilities. The vendor base separates into three strategic tiers: integrated multinationals controlling substrate supply chains, regional specialists with toxicology expertise, and import-dependent distributors facing regulatory displacement. Dominant competitive moves include portfolio diversification into bio-based material categories and capacity expansion for closed-loop material recovery systems.
Within the integrated multinational tier, Mohawk Industries and Tarkett SA exemplify divergent strategic positioning. Mohawk represents backward integration into laminate substrate production with captive resin supply chains. Tarkett anchors circular economy credentials through take-back program infrastructure serving hospital and airport specification channels. Forbo Flooring GmbH occupies a distinct position among natural composition specialists with linoleum manufacturing capabilities that align with tightening chemical disclosure rules.
| Leading Market Players |
|---|
| Mohawk Industries |
| Tarkett SA |
| Forbo Flooring GmbH |
| Milliken Flooring |
| Nora Systems GmbH |
| Gerflor |
| Shaw Industries Group |
| Kronospan Holdings Ltd |
| Swiss Krono Group |
| Others |
Pricing and Supply Chain Analysis
ISO 16000 VOC emission certification gates both supply qualification and price differentiation simultaneously, compressing procurement timelines for certified domestic manufacturers while eliminating discount-positioned imports from specification channels. REACH substance dossier requirements add compliance cost layers that stratify pricing tiers between established compounders and import-dependent distributors.
Pricing Analysis
REACH chemical restrictions dictate the pricing tier structure across German flooring procurement, separating premium-certified bio-based systems from standard laminate and economy vinyl imports. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with hospital operators and airport developers least price-sensitive due to lifecycle cost mandates. Cost compression in economy vinyl tiers is intensifying because ECHA substance evaluation timelines extend reformulation investments. Residential renovators and multi-family housing developers exhibit highest price sensitivity, prioritizing KBA building code compliance over premium emission certification.
Supply Chain Analysis
Just-in-time inventory strategies dominate commercial project procurement, with logistics hub operators and warehouse developers prioritizing rapid operational restart over strategic stockpiling of resin and fiberboard substrates. Geographic supply concentration rests on Germany, Belgium, and the Netherlands for linoleum and laminate core production, while vinyl compounding draws from German and Polish petrochemical corridors. Raw material dependencies center on melamine resins, high-density fiberboard, and phthalate-alternative plasticizers. Single-source vulnerability in European refinery capacity creates feedstock disruption risk. Distribution runs through wholesale contractor networks and manufacturer-direct hospital and airport channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent flooring manufacturers face substitution defense against low-emission linoleum and bio-based alternatives displacing traditional vinyl specification as REACH compliance costs reshape competitive economics.
For Market Incumbents: Consolidate toxicology expertise and certification infrastructure to defend specification share against REACH-compliant natural composition substitutes. Deepen backward integration into resin compounding to buffer petrochemical input volatility and protect margin structures in vinyl categories. Prioritize take-back program infrastructure investment to anchor circular economy credentials in hospital and airport procurement channels. For New Entrants and Emerging Players: Rapid-install floating systems for logistics hub renovations represent a service-layer gap where incumbents under-serve warehouse operators demanding compressed project timelines. Target North Rhine-Westphalia's automotive manufacturing estate renovations with direct sales relationships bypassing traditional architect-specifier intermediaries. Pursue ISO 16000 certification acceleration as primary go-to-market credential against import-dependent distributors facing ECHA substance evaluation delays. For Investors and Strategic Acquirers: EU Green Deal construction product requirements reshape the acquisition landscape toward manufacturers with closed-loop material recovery infrastructure and in-house compliance teams. Long-term viability favors domestic compounders with toxicology capabilities and bio-based portfolio diversification over import-reliant distribution assets. Watch ECHA substance evaluation timelines for phthalate alternatives as the signal indicating regulatory acceleration or delay that would revise competitive positioning assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Take-Back Program Infrastructure | Tarkett's ReStart program anchors circularity credentials in German hospital and airport specification channels. |
| Backward Integration into Resin Production | Mohawk's captive supply chains buffer European petrochemical pricing volatility for laminate substrate manufacturing. |
| Bio-Based Material Portfolio Expansion | Forbo's linoleum manufacturing at Assendelft-adjacent facility aligns with tightening REACH chemical disclosure rules. |
| Direct Sales Channel Development | Manufacturer-direct relationships with Munich airport authorities bypass traditional intermediaries for large-format commercial projects. |
| ISO 16000 Certification Acceleration | Rapid VOC emission testing documentation matches compressed procurement schedules in Bavaria healthcare renovation programs. |
Research Methodology
A spread of perspectives from flooring procurement managers, hospital facility directors, logistics hub operators, and architect-specifiers converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from KBA building code documentation, ECHA substance evaluation records, EU Green Deal construction product requirements, and German customs trade data. Bottom-up installation volume estimates triangulated against top-down construction expenditure flows.
Segmentation dimensions modeled include product type, installation method, end user category, and distribution channel across the projection horizon. CAGRs were derived from trend extrapolation of specification authority shifts and embodied carbon procurement mandates. Industry-specific forecast inputs incorporated REACH reformulation timeline assumptions and healthcare estate modernization program pipelines.
Forecasts assume regulatory continuity in REACH, KBA building code, and EU Green Deal regimes; material policy shifts would require re-modeling. Specific risks include ECHA substance evaluation acceleration, petrochemical feedstock disruption, and AI-enabled specification tool adoption altering architect-specifier relationships. Revision becomes warranted when REACH SVHC notification thresholds cross new substance categories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
US Resilient Flooring Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Wood and Laminate Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Global Vinyl Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Bamboo Flooring Market
Flooring, Carpets, and Rugs
Global Floor Covering Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market